
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Radiodermatitis Market Size 2023 | USD 471.68 Million |
| Radiodermatitis Market, CAGR | 4.05% |
| Radiodermatitis Market Size 2032 | USD 674.26 Million |
Market Overview
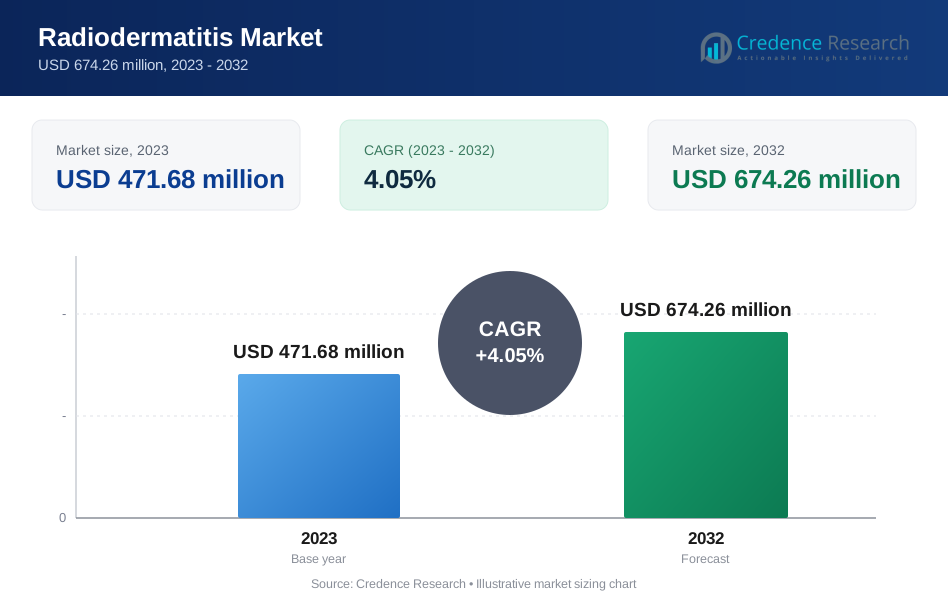
The Radiodermatitis Market is projected to grow from USD 471.68 million in 2023 to an estimated USD 674.26 million by 2032, registering a compound annual growth rate (CAGR) of 4.05% from 2024 to 2032. This growth underscores the increasing prevalence of radiodermatitis among cancer patients undergoing radiation therapy, driving demand for effective preventive and therapeutic solutions.
Market drivers include the growing number of patients undergoing radiation therapy, advancements in treatment modalities, and rising healthcare expenditure focused on patient safety and comfort. Innovative wound care products, such as hydrocolloid dressings, honey-based therapies, and steroid-based topical agents, are enhancing the efficacy of radiodermatitis management. The demand for effective treatments has led to notable research and development, encouraging market entrants and established players alike to prioritize this segment.
Geographically, North America dominates the Radiodermatitis market, driven by advanced healthcare infrastructure, higher radiation therapy prevalence, and robust reimbursement frameworks. Europe holds a significant share due to increasing cancer cases and supportive healthcare policies. The Asia-Pacific region is expected to experience the fastest growth owing to expanding healthcare access and rising cancer rates. Key players driving the market include Mölnlycke Health Care, Smith & Nephew plc, 3M Company, BMG Pharma S.p.A., and Stratpharma AG, whose ongoing innovations cater to evolving patient needs.
Market Drivers
Rising Prevalence of Cancer and Increasing Use of Radiation Therapy
The increasing incidence of cancer globally remains a significant driver for the radiodermatitis market. Cancer is among the leading causes of mortality worldwide, with millions of new cases diagnosed each year. Radiation therapy, often used as a primary or adjunct treatment, has proven effective for many cancers but frequently results in radiodermatitis as a side effect. According to the World Health Organization, roughly half of cancer patients undergo radiation therapy, with many experiencing skin reactions ranging from mild erythema to severe ulceration. This creates a sustained and growing need for effective radiodermatitis prevention and management solutions. Companies are investing heavily in research to develop new and improved products to address these skin reactions, including creams, gels, dressings, and systemic therapies designed to minimize or heal radiation-induced skin damage. For instance, in 2024, it is projected that over 2 million new cancer cases will be diagnosed in the United States alone, with 611,720 cancer-related deaths expected to occur, highlighting the growing need for effective treatments like radiation therapy, which often leads to radiodermatitis as a side effect.
Advancements in Radiodermatitis Treatment Modalities
Innovation and advancements in the treatment of radiodermatitis are key drivers for market growth. Traditional approaches to managing radiodermatitis often focused on basic wound care or pain relief, but new treatment modalities have shifted toward proactive prevention and healing solutions that improve patient outcomes. Advanced wound care products, such as hydrocolloid dressings, silicone-based dressings, and honey-based therapies, are gaining traction for their effectiveness in reducing symptoms and promoting rapid healing. Furthermore, steroidal and non-steroidal topical agents, growth factor-based therapies, and specialized emollients are being increasingly adopted. The expansion of product portfolios tailored to different stages and severities of radiodermatitis has enhanced patient adherence and efficacy, making the market more diverse and comprehensive. This push towards innovation is supported by partnerships, collaborations, and increased funding for research, enabling continuous progress in treatment offerings.
Growing Awareness and Emphasis on Patient Quality of Life
Patient quality of life is a growing area of focus within the healthcare industry, and the need for better radiodermatitis care reflects this trend. As radiation therapy often causes physical discomfort, emotional stress, and social anxiety due to visible skin damage, healthcare providers are recognizing the importance of improving the patient experience. This awareness has driven healthcare systems and organizations to prioritize skin health management in cancer treatment protocols. Government initiatives, patient advocacy campaigns, and hospital protocols that emphasize comprehensive care, including managing radiodermatitis, have played a role in creating a supportive market environment. Increased awareness of radiodermatitis and a greater understanding of its impact on patients have driven higher demand for targeted therapies and motivated companies to introduce more effective and innovative solutions that improve comfort and adherence to radiation therapy schedules.
Expanding Healthcare Infrastructure and Increased Healthcare Expenditure
The expansion of healthcare infrastructure and rising healthcare expenditures globally are critical drivers for the radiodermatitis market. Emerging economies are experiencing rapid growth in healthcare spending, improving patient access to cancer care, including radiation therapy. As healthcare systems develop, more individuals receive accurate diagnoses and timely cancer treatments, leading to a higher demand for radiodermatitis management solutions. Increased funding for oncology and patient care, coupled with supportive government policies, has facilitated the widespread adoption of advanced treatment products and technologies in radiodermatitis care. Moreover, the growing integration of wound care management practices and specialized radiodermatitis solutions within hospitals, clinics, and cancer treatment centers has driven market penetration. Companies operating in this space are responding to these demands by expanding their global reach, investing in marketing and distribution channels, and tailoring solutions to local needs, further enhancing market accessibility and growth potential.
Market Trends
Increasing Use of Advanced Wound Care Products and Personalized Treatment Approaches
One of the most prominent trends in the radiodermatitis market is the growing adoption of advanced wound care products tailored specifically to treat and prevent radiation-induced skin damage. Traditional methods, such as basic emollients and over-the-counter creams, are being supplemented or replaced by more sophisticated solutions like hydrocolloid, hydrogel, and silicone-based dressings. These advanced dressings offer improved adherence, moisture balance, and faster healing, significantly reducing symptoms and improving patient comfort. Topical corticosteroids, non-steroidal anti-inflammatory agents, and growth factor-based treatments are being utilized to minimize inflammation, relieve discomfort, and promote skin repair. Moreover, personalized treatment regimens, driven by a deeper understanding of patient-specific factors such as cancer type, radiation dosage, and individual skin sensitivity, are becoming increasingly prevalent. This trend is further supported by digital tools and healthcare software platforms, enabling clinicians to tailor care more precisely and effectively. For instance, in a study involving 30 cancer patients (20 with breast cancer and 10 with head-and-neck cancer), the use of CSMed® wound dressing significantly delayed the onset of radiation dermatitis by over a week and reduced the severity of symptoms, as evidenced by lower Radiation Therapy Oncology Group (RTOG) scores between weeks 3 and 7 of treatment compared to untreated areas.
Focus on Preventive Care and Integration into Radiation Therapy Protocols
Another significant trend shaping the radiodermatitis market is the growing emphasis on preventive care and its integration into broader radiation therapy protocols. Traditionally, radiodermatitis treatment has focused on post-onset management, addressing symptoms after they appear. However, the current trend is shifting toward prevention, with proactive measures and early interventions gaining traction. Healthcare providers and oncology centers are incorporating skin care regimens, barrier creams, and anti-inflammatory treatments into radiation therapy protocols from the outset. By prioritizing prevention, these measures aim to reduce the severity of radiodermatitis and ensure uninterrupted and more effective radiation therapy schedules. This preventive approach aligns with the overarching focus on improving patient outcomes, minimizing treatment disruptions, and reducing overall healthcare costs associated with radiodermatitis complications. This trend has encouraged pharmaceutical companies, healthcare providers, and regulatory bodies to collaborate and promote awareness of best practices for radiodermatitis prevention and management.
Market Restraints and Challenges
Limited Awareness and Inconsistent Treatment Protocols
A key restraint for the radiodermatitis market is the limited awareness among patients and healthcare providers about the comprehensive management of radiodermatitis. Despite the significant impact of radiodermatitis on patients' quality of life and the continuity of cancer treatment, many healthcare facilities do not have standardized protocols in place to prevent or manage this condition. Variability in treatment approaches often results in suboptimal care, with some patients receiving only basic palliative support instead of evidence-based, proactive management options. Inadequate training and limited access to specialized products further exacerbate this challenge, particularly in regions with constrained healthcare resources. As a result, the effectiveness and adoption of radiodermatitis therapies remain inconsistent across different markets, limiting the overall growth and penetration of available solutions.
High Cost of Advanced Treatment Solutions
The high cost of advanced radiodermatitis management products poses a considerable challenge to market growth, particularly in low- and middle-income countries. While innovative therapies such as hydrocolloid dressings, growth factor treatments, and specialized creams offer superior care, they are often priced at a premium, making them less accessible to patients without adequate insurance coverage or financial resources. This cost barrier can lead patients and healthcare providers to rely on more affordable but less effective treatment options. Additionally, reimbursement issues for radiodermatitis-specific products and therapies can further limit their usage, particularly in markets with restrictive healthcare budgets or complex insurance processes. Consequently, high costs and limited reimbursement coverage hinder broader market adoption, restricting patient access to state-of-the-art care and limiting the overall impact of advanced solutions in addressing radiodermatitis.
Market Segmentation Analysis
By Product
Hydrogel and hydrocolloid dressings are widely utilized for creating a moist wound environment that accelerates healing and reduces radiodermatitis-related discomfort, with increasing use in clinical settings due to their effectiveness in managing skin reactions. No-sting barrier films are gaining popularity as protective solutions that shield sensitive skin from radiation-induced irritation, particularly benefiting patients with compromised skin integrity. Silver leaf dressings offer antimicrobial properties that prevent infection and promote wound healing, making them particularly valuable for severe cases. Silicone-coated dressings provide gentle adhesion, minimizing skin trauma during removal and offering pain relief and skin protection. Corticosteroids effectively reduce inflammation and swelling in moderate to severe cases, alleviating irritation and discomfort. Hydrophilic creams and emollients are favored for their moisturizing capabilities, soothing and protecting dry, damaged skin during therapy, forming a vital part of routine care. Additionally, other supportive products, including topical analgesics and innovative therapies, contribute to managing and preventing radiodermatitis symptoms comprehensively.
By Route of Administration
The route of administration in the radiodermatitis market is primarily dominated by topical treatments due to their direct application on affected areas, offering targeted relief and faster healing. Most products, such as creams, gels, and dressings, are formulated for topical use, ensuring effective localized management of symptoms. In contrast, oral treatments are less commonly used but play a role in specific cases where symptoms or inflammation cannot be adequately managed through topical applications alone.
Segments
Based on Product
- Hydrogel & Hydrocolloid Dressings
- No-Sting Barrier Films
- Silver Leaf Dressings
- Silicone-Coated Dressings
- Corticosteroids and Hydrophilic Creams
- Others
Based on Route of Administration
- Topical
- Oral
Based on Distribution Channel
- Hospitals
- Cancer Specialist Clinics
- Research Institutes
- Others
Based on Region
- North America
- Europe
- Asia-Pacific
- Rest of the World
Regional Analysis
North America (40%)
North America holds the largest share in the radiodermatitis market, driven by advanced healthcare infrastructure, a high prevalence of cancer, and well-established healthcare reimbursement policies. The region's commitment to cancer treatment research and development further supports the demand for radiodermatitis management products. The United States, in particular, has a significant market share due to the availability of innovative therapies, widespread awareness among healthcare professionals, and strong patient support systems. Canada also contributes to the market through effective healthcare programs, increasing cancer prevalence, and initiatives focused on improving patient outcomes in radiotherapy. The presence of major market players and high investments in clinical trials further bolster the region’s dominance.
Europe (30%)
Europe ranks as the second-largest market for radiodermatitis treatment products. This region benefits from a high prevalence of cancer, increased adoption of radiation therapy, and strong government support for healthcare innovations. Countries such as Germany, the UK, and France lead in terms of market penetration, with robust healthcare systems that prioritize cancer care. Europe’s emphasis on patient safety and quality care during cancer treatment drives the demand for advanced radiodermatitis management products, including topical agents and specialized dressings. Ongoing research collaborations between industry players, healthcare providers, and academic institutions further enhance market development, creating opportunities for new product launches and innovation.
Key players
- 3M
- Mölnlycke Health Care AB
- KCI Licensing Inc.
- Smith & Nephew
- Helsinn Healthcare SA
- Stratpharma AG
- Helsinn Healthcare SA
Competitive Analysis
The radiodermatitis market is highly competitive, with key players striving to enhance their market presence through innovation, strategic partnerships, and expanding their product portfolios. Companies such as 3M and Mölnlycke Health Care AB leverage their broad wound care expertise and extensive product offerings to maintain a strong market position. KCI Licensing Inc., Smith & Nephew, and Stratpharma AG emphasize R&D investments to develop advanced and effective solutions, while Helsinn Healthcare SA focuses on targeted therapies and patient-centric strategies. Competition is driven by the increasing demand for effective radiodermatitis management solutions, pushing market leaders to continuously improve their products. Price competitiveness, technological innovation, and regulatory compliance are critical factors shaping the competitive landscape, compelling companies to differentiate themselves and meet evolving patient and healthcare provider needs.
Recent Developments
- In **April 2024**, Mölnlycke Health Care signed an agreement to acquire P.G.F. Industry Solutions GmbH, a manufacturer of Granudacyn, a range of solutions for wound cleansing and moisturizing. This acquisition is aimed at consolidating Mölnlycke's position as a global leader in wound care.
- In **January 2024**, Smith & Nephew launched a new silicone-based foam dressing designed to manage exudate and protect fragile skin, which can be particularly beneficial for patients undergoing radiation therapy and experiencing radiodermatitis.
- In **March 2023**, Helsinn Healthcare SA expanded its oncology supportive care portfolio by launching a new topical gel specifically formulated to alleviate the symptoms of radiodermatitis in cancer patients undergoing radiation therapy.
- In **June 2023**, Stratpharma AG introduced an advanced silicone-based dressing designed to reduce the severity of radiation-induced skin reactions, providing enhanced protection and promoting faster healing for radiodermatitis patients.
Market Concentration and Characteristics
The radiodermatitis market exhibits a moderately concentrated structure characterized by the presence of a mix of well-established players and emerging companies focused on developing innovative treatment solutions. Key players dominate the market through extensive product portfolios, encompassing advanced dressings, topical agents, and systemic therapies designed to manage and prevent radiation-induced skin reactions. Market concentration is driven by continuous research and development efforts, collaborations with healthcare providers, and increasing investment in patient-centric solutions. Companies compete based on efficacy, safety, and the ability to cater to diverse patient needs. The market's characteristics include a strong emphasis on evidence-based, patient-friendly products, adherence to regulatory standards, and growth opportunities spurred by rising cancer prevalence and increased use of radiation therapy globally.
Report Coverage
The research report offers an in-depth analysis based on Product, Route of Administration, Distribution Channel and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The focus on early intervention and preventive care protocols for managing radiodermatitis will continue to grow, enhancing patient outcomes and reducing treatment interruptions.
- The development of novel topical agents, such as bioengineered creams and hydrophilic formulations, will drive market expansion by providing more effective and targeted therapies.
- Advancements in wound care dressings, including hydrogel and silicone-based solutions, are expected to deliver superior protection and faster healing, boosting market demand.
- As cancer incidence rates increase globally, the demand for effective radiodermatitis management solutions will rise, creating sustained growth opportunities for market participants.
- Emerging economies with expanding healthcare infrastructure and rising healthcare spending will contribute to increased access to radiodermatitis treatment options.
- Patient comfort, quality of life, and adherence to cancer treatment protocols will be emphasized, encouraging innovation and comprehensive care approaches.
- Key players are likely to engage in partnerships and collaborations to accelerate product development, expand geographical reach, and enhance market penetration.
- Faster regulatory approvals and favorable policies for new radiodermatitis therapies will encourage market entry and the introduction of innovative products.
- Patient advocacy groups and healthcare organizations will continue raising awareness about radiodermatitis, improving diagnosis, treatment rates, and driving market growth.
- The use of telemedicine, mobile apps, and wearable devices to monitor and manage radiodermatitis symptoms remotely will revolutionize patient care and treatment adherence.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Prevalence of Cancer and Radiation Therapy
The increasing global incidence of cancer and the widespread use of radiation therapy as a primary or adjunct treatment are leading to a higher number of patients experiencing radiodermatitis, thereby driving demand for effective management solutions.
Advancements in Radiodermatitis Treatment Modalities
Innovations such as hydrocolloid dressings, silicone-based products, and honey-based therapies are improving patient outcomes and expanding the range of available treatment options, encouraging both adoption and market growth.
Growing Awareness and Emphasis on Patient Quality of Life
Healthcare providers and organizations are prioritizing comprehensive skin care management in cancer protocols, recognizing the impact of radiodermatitis on patient comfort and treatment adherence, which is increasing demand for targeted therapies.
Expanding Healthcare Infrastructure and Expenditure
Emerging economies are investing in healthcare infrastructure and oncology services, improving access to radiation therapy and associated supportive care, which is boosting the uptake of radiodermatitis management products.
Integration of Preventive Care into Radiation Therapy Protocols
There is a growing trend toward incorporating preventive measures and early intervention for radiodermatitis within standard radiation therapy protocols, reducing severity and ensuring uninterrupted cancer treatment, thus fueling market expansion.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the market size of the Radiodermatitis market in 2023 and 2032, and what is its projected CAGR?
What factors are driving the growth of the Radiodermatitis market?
Which region currently dominates the Radiodermatitis market?
What are some key products used for managing radiodermatitis?
Who are some of the key players in the Radiodermatitis market?
Why is the Asia-Pacific region expected to experience fast growth in the Radiodermatitis market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Product
- 1.2.1 Hydrogel & Hydrocolloid Dressings
- 1.2.2 No-Sting Barrier Films
- 1.2.3 Silver Leaf Dressings
- 1.2.4 Silicone-Coated Dressings
- 1.2.5 Corticosteroids and Hydrophilic Creams
- 1.2.6 Others
- 1.3 By Route of Administration
- 1.3.1 Topical
- 1.3.2 Oral
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2023: USD 471.68 million → 2032: USD 674.26 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2023
- 2.6.2 Forecast Period: 2023-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2023
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Radiodermatitis Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Radiodermatitis Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2023-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2023-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Radiodermatitis Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2023-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Radiodermatitis Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Radiodermatitis Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Radiodermatitis Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Radiodermatitis Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Radiodermatitis Market Outlook, 2023-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2023: USD 471.68 million → 2032: USD 674.26 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2023
- 11.2 Market Forecast, 2023-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Radiodermatitis Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2023
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Product - Market Size and Forecast, 2023-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2023-2032
- 12.3.4 Volume Forecast, 2023-2032
- 12.3.5 Base-Year Market Share, 2023
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Hydrogel & Hydrocolloid Dressings
- 12.3.7.2 No-Sting Barrier Films
- 12.3.7.3 Silver Leaf Dressings
- 12.3.7.4 Silicone-Coated Dressings
- 12.3.7.5 Corticosteroids and Hydrophilic Creams
- 12.3.7.6 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Route of Administration - Market Size and Forecast, 2023-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2023-2032
- 12.4.4 Volume Forecast, 2023-2032
- 12.4.5 Base-Year Market Share, 2023
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Topical
- 12.4.7.2 Oral
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global Radiodermatitis Geographic Market Outlook, 2023-2032
- 13.1 Regional Market Size and Share, 2023
- 13.2 Regional Market Forecast, 2023-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Radiodermatitis Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2023-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Radiodermatitis Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2023
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2023-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 3M
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Mölnlycke Health Care AB
- 17.4 Smith & Nephew
- 17.5 Stratpharma AG
- 17.6 KCI Licensing Inc.
- 17.7 Helsinn Healthcare SA
- 17.8 BMG Pharma S.p.A.
- 17.9 ConvaTec Group PLC
- 17.10 Coloplast
- 17.11 Medline Industries
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

