
Market Overview:
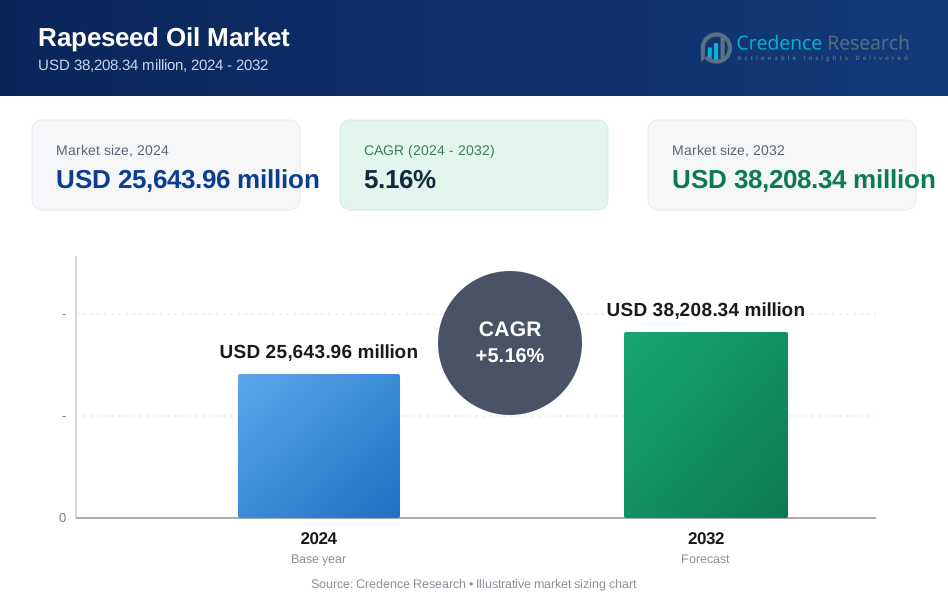
The Rapeseed Oil Market size was valued at USD 21,400.00 million in 2018 to USD 25,643.96 million in 2024 and is anticipated to reach USD 38,208.34 million by 2032, at a CAGR of 5.16% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Rapeseed Oil Market Size 2024 | USD 25,643.96 million |
| Rapeseed Oil Market, CAGR | 5.16% |
| Rapeseed Oil Market Size 2032 | USD 38,208.34 million |
Growth in the Rapeseed Oil Market is primarily driven by increasing health awareness and the growing preference for low-saturated-fat edible oils. Its rich omega-3 fatty acid composition supports cardiovascular health, encouraging adoption in both retail and food service sectors. Rising biodiesel production and government renewable energy mandates also contribute significantly. Expanding food processing industries, coupled with advancements in oil refining technologies, further strengthen market expansion and product diversification.
Europe remains the leading region in the Rapeseed Oil Market, supported by strong production and biodiesel demand, particularly in Germany, France, and the UK. Asia Pacific is an emerging region with growing consumption in China and India, driven by dietary changes and industrial expansion. North America shows moderate growth, supported by health-conscious consumers and biodiesel policies. Latin America, the Middle East, and Africa are developing markets, where improving supply chains and awareness of healthy oils foster future demand.

Market Insights:
- The Rapeseed Oil Market was valued at USD 21,400.00 million in 2018, reached USD 25,643.96 million in 2024, and is projected to hit USD 38,208.34 million by 2032, expanding at a CAGR of 5.16%.
- Europe leads with a 31.3% share, supported by strong biodiesel production, efficient refining infrastructure, and widespread use of sustainable oils.
- Asia Pacific follows with a 28.8% share, driven by China and India’s expanding food processing sectors and growing demand for healthy cooking oils.
- North America holds a 20.4% share, propelled by health-conscious consumers and steady biodiesel consumption, while Asia Pacific remains the fastest-growing region with rising urbanization and renewable energy initiatives.
- Processed rapeseed oil accounts for roughly 65% of total market revenue due to its industrial and culinary applications, whereas virgin oil contributes the remaining 35%, supported by growing interest in premium and cold-pressed varieties.
Market Drivers
Rising Health Awareness and Preference for Low-Fat Edible Oils
The Rapeseed Oil Market experiences strong growth due to increasing health awareness among consumers. People are adopting low-fat diets to manage cholesterol and heart health. Rapeseed oil’s rich omega-3 and omega-6 content strengthens its appeal as a healthy edible oil. It contains one of the lowest saturated fat levels among cooking oils, enhancing demand in both households and food service sectors. Consumers view it as a balanced and natural alternative to other vegetable oils. Growing obesity rates encourage healthy substitutes in cooking. Governments and health agencies promote rapeseed oil consumption for cardiovascular benefits. These factors continue to strengthen global adoption and consumption patterns.
Growing Demand from Biodiesel and Renewable Energy Sectors
The Rapeseed Oil Market benefits from rapid expansion in biodiesel applications driven by energy transition policies. Governments encourage biofuel production to reduce dependence on fossil fuels. Rapeseed oil serves as an efficient feedstock for biodiesel due to its favorable chemical properties. It improves engine performance and lowers emissions. Renewable energy programs in Europe, Canada, and Asia support its industrial demand. Global oilseed processing companies invest in refining facilities to meet sustainability goals. Energy diversification trends push industries to seek plant-based oil alternatives. It remains a crucial link between agriculture and clean energy development.
- For instance, in Germany, the Association of the German Biofuels Industry (VDB) reported that in 2024, biodiesel production reached 3.6 million tonnes with rapeseed oil accounting for 53.1% of all feedstock (roughly 1.45 million tonnes processed into biodiesel).
Expanding Food Processing and Packaged Food Industry
The Rapeseed Oil Market gains traction from the growing packaged food and food processing industries. Processed food producers prefer rapeseed oil for its neutral flavor and light texture. Its oxidative stability makes it ideal for frying and baking. Food manufacturers use it for sauces, margarine, and dressings. Urbanization increases demand for ready-to-eat products containing healthy oils. Rising income levels in emerging markets improve consumer spending on nutritious products. Food service chains adopt rapeseed oil for large-scale cooking operations. It enhances the shelf life of packaged foods, creating steady demand from food processors.
Technological Improvements in Extraction and Refining Processes
The Rapeseed Oil Market benefits from continuous improvements in seed processing and oil extraction technologies. Advanced cold-pressing techniques preserve nutrients and flavor. Modern refining reduces impurities while retaining essential fatty acids. Automation enhances production efficiency and quality consistency. Companies invest in R&D to increase yield from seeds and minimize wastage. Sustainable processing lowers the carbon footprint of oil production. Enhanced logistics networks ensure faster delivery to industrial and retail users. It creates cost efficiency and supports manufacturers in scaling production for global markets.
- For instance, Iberol Sociedade Ibérica de Biocombustíveis e Oleaginosas, S.A. implemented the second phase of its Screw Presses Project at its Iberian facility, increasing rapeseed oil yield by 0.73% and scaling overall process capacity by 25%.
Market Trends
Shift Toward Sustainable and Organic Rapeseed Cultivation Practices
The Rapeseed Oil Market witnesses a shift toward sustainable and organic farming methods. Farmers adopt eco-friendly cultivation techniques to reduce pesticide residues and soil degradation. Organic rapeseed oil appeals to environmentally conscious consumers. Retailers promote certified organic variants in premium segments. Sustainable sourcing initiatives by major producers strengthen brand image and supply reliability. Governments support organic farming through subsidies and certification programs. It enhances traceability in supply chains, improving transparency. The trend reflects rising alignment between health-conscious consumers and green agriculture.
Increased Usage of Rapeseed Oil in Cosmetic and Pharmaceutical Applications
The Rapeseed Oil Market expands its reach into non-food sectors, including cosmetics and pharmaceuticals. Manufacturers use it in skin care and hair formulations for its emollient properties. Its high vitamin E content supports natural anti-aging and moisturizing benefits. Pharmaceutical companies utilize it in soft gels and topical preparations. Demand grows for plant-based ingredients in personal care products. Brands market rapeseed-derived oils as clean-label ingredients. It aligns with consumer preference for sustainable, chemical-free formulations. This trend diversifies market applications beyond edible oil consumption.
- For instance, Beiersdorf launched the NIVEA Cellular Epigenetics Rejuvenating Serum, featuring EPICELLINE®, a patented ingredient powered by epigenetic science. The product was rolled out in Europe in August 2025 and is scheduled to be available in 30 countries by the end of 2025. This launch is documented in Beiersdorf’s newsroom and industry news, where the company provides scientific evidence of skin age reversal demonstrated by efficacy for visible results in as little as two weeks.
Rising Consumption of Cold-Pressed and Unrefined Oils
The Rapeseed Oil Market experiences strong demand for cold-pressed and unrefined products. Consumers associate these oils with superior nutrition and minimal processing. Cold-pressed variants retain natural antioxidants and omega fatty acids. Boutique brands emphasize purity and freshness through small-batch production. Online retail and specialty stores boost accessibility of premium-quality oils. Rising disposable incomes encourage purchases of healthier alternatives. It reflects a broader trend toward transparency and quality in edible oil products. This trend strengthens consumer trust and brand loyalty.
- For instance, Clearspring's Organic Rapeseed Oil is produced from 100% European, cold-pressed, unrefined rapeseeds and is certified organic and kosher as evidenced by current product pages. Analytical tests published for Clearspring indicate vitamin E concentration at 34mg/100ml and omega-3 alpha-linolenic acid content of 6.6g/100ml, supporting claims of high natural antioxidant and omega fatty acid retention that consumers seek in cold-pressed oils.
Integration of Advanced Supply Chain and Packaging Technologies
The Rapeseed Oil Market integrates smart logistics and innovative packaging systems. Manufacturers deploy traceability tools to monitor quality and reduce losses. Flexible packaging formats improve product preservation and reduce waste. Automation in bottling lines enhances hygiene and productivity. Digital platforms enable real-time tracking of shipments and stock levels. Sustainable packaging using biodegradable materials gains popularity. Producers emphasize tamper-evident and recyclable bottles to appeal to eco-conscious consumers. It enhances efficiency and brand credibility in global trade.

Market Challenges Analysis
Volatile Price Fluctuations and Dependence on Crop Yields
The Rapeseed Oil Market faces major challenges from fluctuating seed prices and variable crop yields. Climate changes affect rapeseed cultivation cycles, influencing production costs. Droughts or excess rainfall impact seed quality and yield output. Price volatility in global oilseed markets creates uncertainty for processors and traders. Competition from palm and soybean oil affects pricing dynamics. Farmers encounter high input costs due to fertilizer and energy inflation. Market participants must manage risks through forward contracts and inventory controls. It increases the need for diversified sourcing strategies to maintain stability.
Trade Barriers, Policy Uncertainty, and Supply Chain Constraints
The Rapeseed Oil Market encounters challenges from trade restrictions and regulatory shifts. Tariffs and export bans disrupt global oil movement. Changes in biodiesel mandates influence demand forecasts. Regional supply chain disruptions lead to raw material shortages. Limited infrastructure in emerging markets slows production expansion. Environmental regulations tighten compliance standards for refining operations. These factors restrict international competitiveness for smaller producers. It requires adaptive logistics and strategic alliances to maintain consistent supply flow.
Market Opportunities
Rising Adoption of Bio-Based Industrial Oils and Lubricants
The Rapeseed Oil Market presents new opportunities in bio-based industrial products. Manufacturers use rapeseed oil as a base for biodegradable lubricants, hydraulic fluids, and greases. Growing industrial focus on eco-friendly materials strengthens demand. Regulatory pressure on petrochemical lubricants encourages transition to plant-based alternatives. Collaboration between energy and chemical sectors fosters product innovation. It supports sustainability goals while reducing environmental impact. The opportunity extends to agriculture, construction, and marine applications.
Expanding Penetration in Emerging Economies and Niche Segments
The Rapeseed Oil Market gains growth potential in emerging economies with rising middle-class populations. Consumers in Asia-Pacific, Latin America, and Africa shift toward healthier edible oils. Local refining and distribution networks expand accessibility in urban areas. Niche product launches like flavored or fortified oils attract younger buyers. Investments in retail packaging and e-commerce channels boost reach. It enables producers to capture demand in both household and industrial markets.
Market Segmentation Analysis:
By Product Type
The Rapeseed Oil Market is segmented into processed and virgin oil types. Processed rapeseed oil dominates due to its wide use in cooking, food manufacturing, and biodiesel production. It offers stability, a neutral taste, and longer shelf life, which attract large-scale food processors. Virgin oil, extracted through cold pressing, gains traction among health-conscious consumers. Its minimal processing helps retain natural nutrients and aroma. It finds demand in premium retail and cosmetic segments. The segment’s growth reflects rising consumer focus on healthy and sustainable products.
- For instance, Germany’s cold-pressed edible rapeseed oil segment now features over 140 decentralized oil mills nationwide, with consumer demand attributed to the retained aroma and characteristic taste-a trend confirmed by peer-reviewed research and market monitoring as of May 2025.
By End User
The Rapeseed Oil Market serves food service, food processor, and retail sectors. Food processors lead the market due to consistent demand from packaged food and snack industries. The oil’s stability and cost-effectiveness make it a preferred ingredient for frying and baking. The food service sector grows with expanding restaurant and catering businesses. Retail consumers increasingly buy smaller packs driven by home cooking trends. It strengthens brand diversification across consumer and industrial segments, ensuring continuous market growth.
- For instance, Nestlé, Unilever, and General Mills consistently use refined rapeseed oil in products ranging from margarine to ready-to-eat meals, supported by documented ingredient lists and sustainability disclosures.
By Distribution Channel
The Rapeseed Oil Market utilizes modern trade, franchise outlets, specialty stores, and online channels. Modern trade holds the largest share due to its strong network and product visibility. Franchise outlets expand brand access in urban centers. Specialty stores target premium and health-focused buyers with organic and cold-pressed variants. Online channels show the fastest growth, supported by digital marketing and easy delivery. It enhances convenience and accessibility, widening consumer reach across developed and emerging markets.

Segmentation:
By Product Type
- Processed
- Virgin
By End User
- Food Service
- Food Processor
- Retail
By Distribution Channel
- Modern Trade
- Franchise Outlets
- Specialty Stores
- Online
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
The North America Rapeseed Oil Market size was valued at USD 5,007.60 million in 2018 to USD 5,887.70 million in 2024 and is anticipated to reach USD 8,753.60 million by 2032, at a CAGR of 5.2% during the forecast period. North America holds a 20.4% market share. The region shows steady demand driven by growing health awareness and preference for low-saturated-fat oils. The U.S. dominates due to high consumption in packaged food and biodiesel applications. Canada contributes through large-scale rapeseed (canola) production and export activities. It benefits from government support for renewable fuel blending. Food manufacturers adopt rapeseed oil for its neutral flavor and cooking versatility. The expanding vegan and plant-based product segments further stimulate growth. Advanced refining technology strengthens product consistency and export competitiveness.
Europe
The Europe Rapeseed Oil Market size was valued at USD 7,875.20 million in 2018 to USD 9,174.71 million in 2024 and is anticipated to reach USD 13,134.22 million by 2032, at a CAGR of 4.6% during the forecast period. Europe accounts for a 31.3% share of the global market. The region is a mature and dominant producer led by Germany, France, and the U.K. The European Union’s renewable energy targets and biodiesel mandates create high demand. Food industries prefer rapeseed oil for its light texture and nutritional benefits. Sustainable farming and traceable supply chains align with consumer priorities. It benefits from government incentives promoting low-emission fuel sources. Local processors focus on organic and cold-pressed variants to cater to premium consumers. Innovation in crop genetics and refining enhances yield efficiency.
Asia Pacific
The Asia Pacific Rapeseed Oil Market size was valued at USD 5,970.60 million in 2018 to USD 7,432.79 million in 2024 and is anticipated to reach USD 12,085.33 million by 2032, at a CAGR of 6.3% during the forecast period. Asia Pacific holds a 28.8% market share, showing the fastest growth globally. China remains the leading consumer and importer due to strong food processing and retail sectors. India’s edible oil deficit drives rapeseed oil imports and production expansion. Japan and South Korea adopt it in premium packaged and health-oriented products. Growing population and urbanization increase cooking oil demand. The rise in quick-service restaurants supports bulk sales. It gains traction in biodiesel blending projects across emerging economies. Investment in refining infrastructure enhances market penetration and price competitiveness.
Latin America
The Latin America Rapeseed Oil Market size was valued at USD 1,519.40 million in 2018 to USD 1,805.08 million in 2024 and is anticipated to reach USD 2,516.78 million by 2032, at a CAGR of 4.3% during the forecast period. Latin America represents a 6% share of the global market. Brazil and Argentina lead regional production, leveraging favorable climates for oilseed cultivation. Growing interest in biodiesel supports demand for rapeseed oil. The food processing sector adopts it for bakery and snack products due to cost efficiency. Retail expansion in urban centers increases household consumption. It benefits from trade agreements facilitating oil exports to North America and Europe. Economic recovery and rising middle-class income strengthen edible oil purchases. Sustainability certification initiatives enhance the region’s global competitiveness.
Middle East
The Middle East Rapeseed Oil Market size was valued at USD 500.76 million in 2018 to USD 538.36 million in 2024 and is anticipated to reach USD 668.86 million by 2032, at a CAGR of 2.8% during the forecast period. The region accounts for a 1.6% market share. Limited domestic production makes the market import-dependent. The United Arab Emirates and Saudi Arabia dominate consumption through food service and catering sectors. Demand rises from health-conscious expatriate populations and hospitality growth. Retail brands promote fortified and premium oil variants to attract urban consumers. It benefits from increasing western dietary influences. Government trade diversification policies support food import channels. Expanding cold-chain logistics improves product availability and storage stability.
Africa
The Africa Rapeseed Oil Market size was valued at USD 526.44 million in 2018 to USD 805.32 million in 2024 and is anticipated to reach USD 1,049.55 million by 2032, at a CAGR of 3.0% during the forecast period. Africa holds a 1.9% share of the global market. Demand increases with population growth and changing dietary habits. South Africa remains the largest consumer due to urbanization and industrial food use. Egypt’s retail and food service sectors expand the import base. It relies heavily on European and Asian imports to meet consumption needs. Government initiatives encourage local oilseed processing to reduce dependency. Rising awareness of healthy fats stimulates gradual adoption in urban markets. Distribution improvements and affordability drive steady growth across key African economies.
Key Player Analysis:
- Archer Daniels Midland (ADM)
- Bunge Limited
- Cargill Inc.
- Adani Wilmar Ltd.
- Associated British Foods (ACH)
- Ruchi Soya Industries Ltd
- Beidahuang Group
- Borges Mediterranean Group
- Fuji Vegetable Oil, Inc.
- Marico Limited
Competitive Analysis:
The Rapeseed Oil Market features intense competition among global and regional producers focused on product quality, pricing, and distribution efficiency. Leading players such as Archer Daniels Midland, Bunge Limited, Cargill Inc., Adani Wilmar, and Associated British Foods dominate through integrated supply chains and large refining capacities. It benefits from advanced logistics, vertical integration, and sustainable sourcing initiatives. Emerging companies like Beidahuang Group, Borges Mediterranean Group, and Marico Limited strengthen regional presence with localized production and brand positioning. Innovation in cold-pressing, biofuel processing, and organic variants drives product differentiation. Strategic partnerships and acquisitions expand geographic coverage and processing scale. The market’s competitive landscape continues evolving with a strong emphasis on traceability, sustainability, and value-added product portfolios.
Recent Developments:
- In October 2025, PepsiCo and Soil Capital announced a new partnership focused on regenerative agriculture practices among rapeseed oil producers in Europe. This strategic initiative aims to benefit over 35,000 acres across the UK, France, and Belgium, empowering farmers in PepsiCo’s supply sheds with financial incentives and agronomic guidance tailored to regional challenges.
- In October 2025, the Australian Oilseeds company formed a joint venture to enter India's edible oil market. This move marks a significant partnership development and is expected to boost the supply of rapeseed oil and possibly other vegetable oils in the fast-growing Indian market, responding to rising demand for healthy edible oils among Indian consumers.
Report Coverage:
The research report offers an in-depth analysis based on Product Type, End User, Distribution Channel. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Demand for healthy edible oils will drive steady consumption growth across food processing and retail sectors.
- Expansion in biodiesel and bio-lubricant applications will strengthen industrial demand.
- Cold-pressed and organic variants will gain traction due to rising consumer preference for natural products.
- Technological upgrades in refining and extraction will enhance yield efficiency and reduce environmental impact.
- E-commerce and direct-to-consumer platforms will expand accessibility in both developed and emerging regions.
- Sustainability certifications will become essential for global trade compliance and brand differentiation.
- Crop innovation programs will focus on improving rapeseed varieties with higher oil content and resistance to climate change.
- Strategic alliances between food and energy industries will boost diversification of rapeseed oil applications.
- Government renewable fuel mandates will sustain long-term industrial use and capacity expansion.
- Regional producers will invest in local refining to improve self-sufficiency and export competitiveness.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Health Awareness and Preference for Low-Fat Edible Oils
Consumers are increasingly seeking healthier cooking oils with low saturated fat and high omega-3 content, positioning rapeseed oil as a preferred choice for both households and food service sectors. This trend is reinforced by government and health agency recommendations for cardiovascular health.
Growing Demand from Biodiesel and Renewable Energy Sectors
Government mandates and energy transition policies are driving the use of rapeseed oil as a key feedstock for biodiesel, especially in Europe and North America. Its favorable chemical properties and sustainability profile make it essential for renewable fuel production, boosting industrial demand.
Expanding Food Processing and Packaged Food Industry
The growth of the packaged food and food processing industries increases the use of rapeseed oil due to its neutral flavor, oxidative stability, and suitability for frying and baking. Urbanization and rising incomes in emerging markets further drive demand from food manufacturers and service chains.
Technological Improvements in Extraction and Refining Processes
Advancements in cold-pressing, refining, and automation have improved oil yield, quality, and cost efficiency. These innovations support the production of both mass-market and premium rapeseed oil products, enabling manufacturers to meet diverse consumer and industrial needs.
Shift Toward Sustainable and Organic Rapeseed Cultivation
Sustainable and organic farming practices are gaining traction, appealing to environmentally conscious consumers and supporting premium product segments. Certification programs and traceable supply chains enhance brand value and market access, especially in developed regions.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Rapeseed Oil Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Rapeseed Oil Market projected to grow between 2024 and 2032?
Which Rapeseed Oil held the largest share in 2024?
What are the key drivers for the growth of the rapeseed oil market
What are the primary factors fueling the growth of the Rapeseed Oil Market?
Who are the leading companies in the Rapeseed Oil Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End User
- 1.2.1 Food Service
- 1.2.2 Food Processor
- 1.2.3 Retail
- 1.3 By Product Type
- 1.3.1 Processed
- 1.3.2 Virgin
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 25,643.96 million → 2032: USD 38,208.34 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Rapeseed Oil Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Rapeseed Oil Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Rapeseed Oil Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Rapeseed Oil Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Rapeseed Oil Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Rapeseed Oil Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Rapeseed Oil Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Rapeseed Oil Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 25,643.96 million → 2032: USD 38,208.34 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Rapeseed Oil Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End User - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Food Service
- 12.3.7.2 Food Processor
- 12.3.7.3 Retail
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Product Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Processed
- 12.4.7.2 Virgin
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global Rapeseed Oil End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Rapeseed Oil Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Rapeseed Oil Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Rapeseed Oil Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Archer Daniels Midland (ADM)
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Bunge Limited
- 18.4 Cargill Inc.
- 18.5 Adani Wilmar Ltd.
- 18.6 Associated British Foods (ACH)
- 18.7 Ruchi Soya Industries Ltd
- 18.8 Beidahuang Group
- 18.9 Borges Mediterranean Group
- 18.10 Fuji Vegetable Oil, Inc.
- 18.11 Marico Limited
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

