
Market Overview:
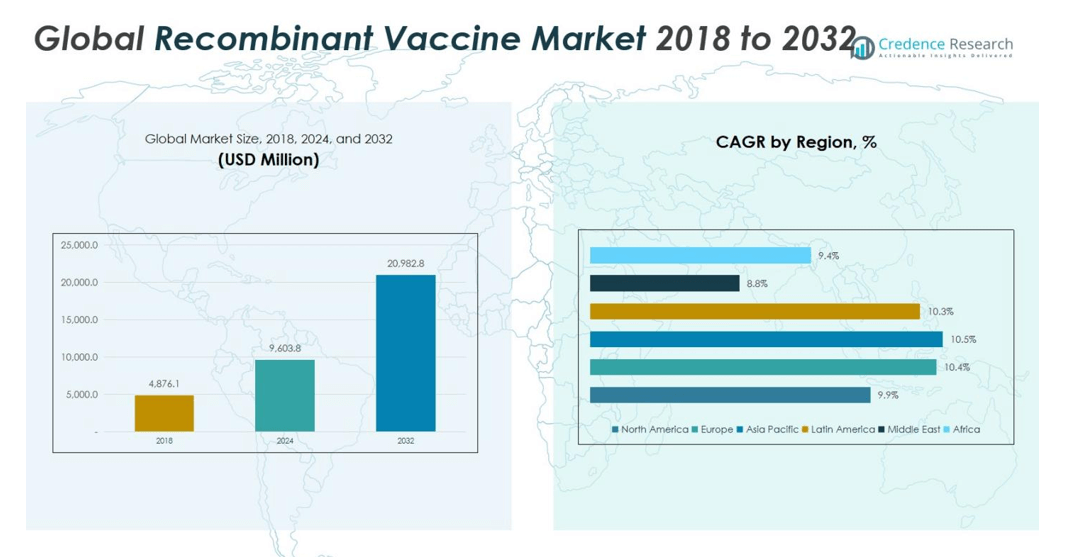
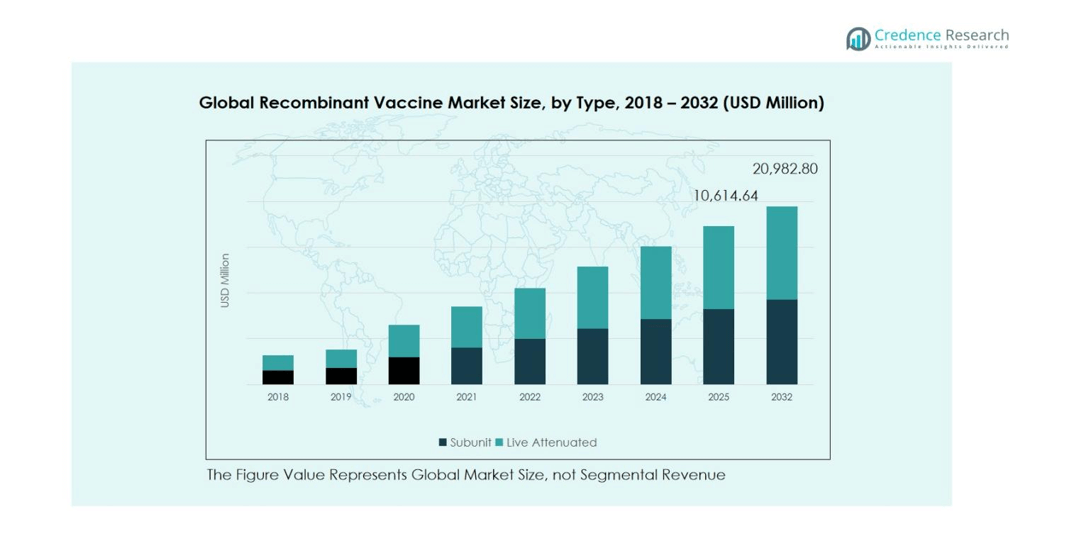
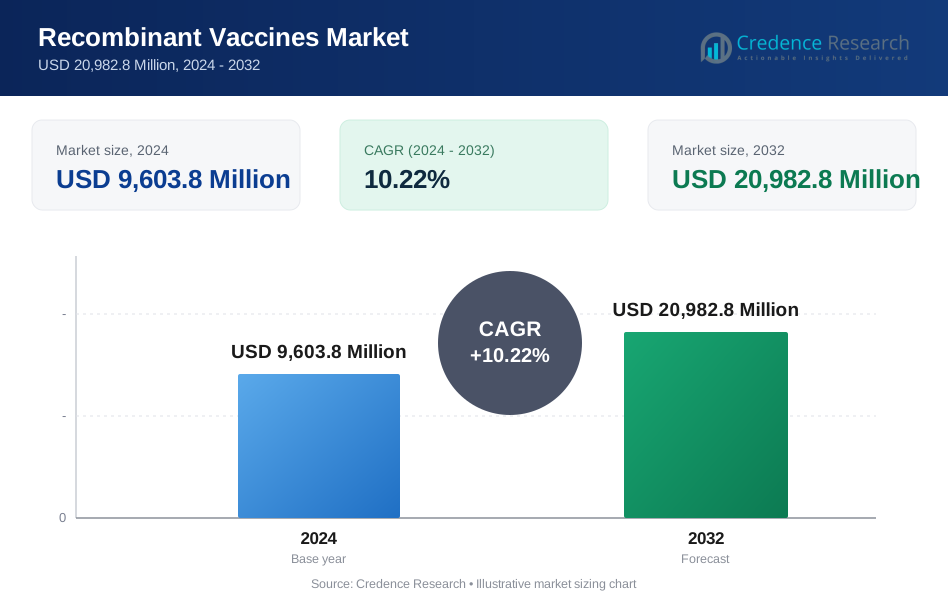
Recombinant Vaccine Market size was valued at USD 4,876.1 Million in 2018, rising to USD 9,603.8 Million in 2024, and is anticipated to reach USD 20,982.8 Million by 2032, at a CAGR of 10.22% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Recombinant Vaccine Market Size 2024 | USD 9,603.8 Million |
| Recombinant Vaccine Market, CAGR | 10.22% |
| Recombinant Vaccine Market Size 2032 | USD 20,982.8 Million |
The Recombinant Vaccine Market is dominated by key players such as GSK plc, Serum Institute of India, Novartis AG, Merck & Co., Inc., Pfizer, Inc., Cipla Inc., Sanofi, Bharat Biotech, CanSino Biologics, and AstraZeneca. These companies are driving market growth through strategic collaborations, research and development, and geographic expansion, focusing on innovative vaccine technologies and combination formulations. Asia Pacific leads the global market with a 26% share in 2024, driven by rising population, government immunization programs, and expanding healthcare infrastructure. Europe follows closely, holding 25% of the market, supported by preventive healthcare initiatives and strong regulatory frameworks. North America, with 23% market share, benefits from advanced R&D, high adoption rates, and extensive vaccination campaigns. Collectively, these regions account for the majority of global market revenue, while emerging markets in Latin America, the Middle East, and Africa offer significant growth opportunities for the leading players to expand their portfolios and reach underserved populations.
Market Insights
- The Recombinant Vaccine Market was valued at USD 9,603.8 Million in 2024 and is projected to reach USD 20,982.8 Million by 2032, growing at a CAGR of 10.22%. Subunit vaccines hold 62% of the market share in 2024, and parenteral administration dominates with 78% share, while Hepatitis B vaccines lead disease indications with 28% share.
- Rising prevalence of infectious diseases, increasing government immunization programs, and growing awareness about vaccine-preventable illnesses are driving the market globally.
- Market trends include the growing adoption of combination and multivalent vaccines, technological advancements in recombinant DNA vaccines, and expansion into emerging regions such as Asia Pacific and Latin America.
- The market is competitive, with key players including GSK plc, Serum Institute of India, Novartis AG, Merck & Co., Pfizer, Sanofi, Bharat Biotech, CanSino Biologics, and AstraZeneca, focusing on R&D, strategic collaborations, and geographic expansion to strengthen their position.
- High manufacturing costs, complex production processes, and stringent regulatory requirements act as restraints, while North America, Europe, and Asia Pacific together account for the majority of market revenue.
Market Segmentation Analysis:
By Type:
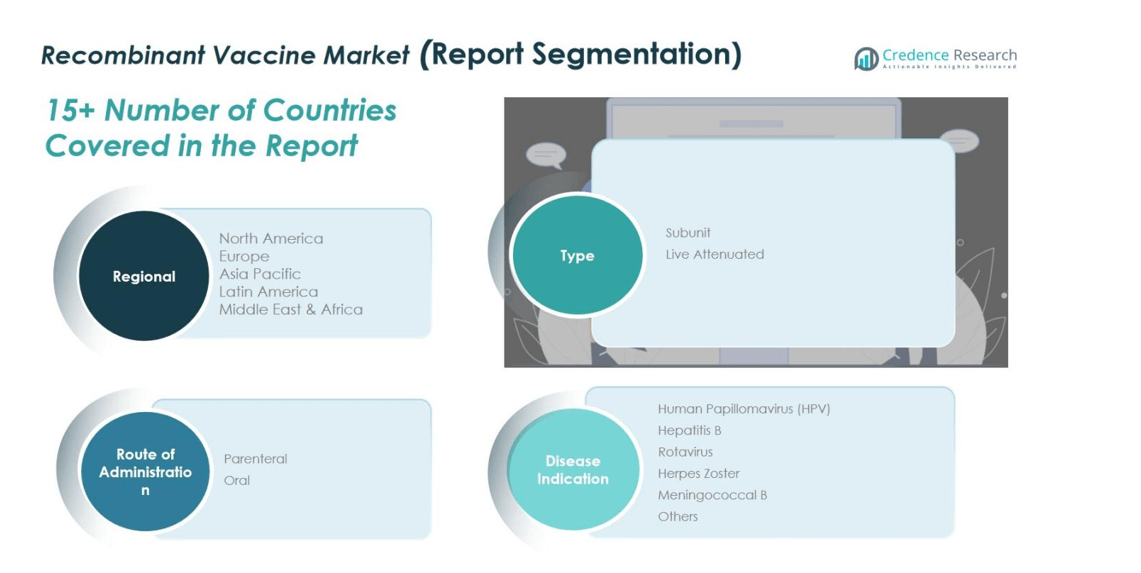
The recombinant vaccine market by type is primarily segmented into subunit and live attenuated vaccines. Subunit vaccines dominate the market, holding 62% of the share in 2024, driven by their safety profile, ability to target specific antigens, and lower risk of adverse reactions compared to live attenuated vaccines. The rising prevalence of chronic infectious diseases and growing adoption in pediatric and adult immunization programs further support their growth. Live attenuated vaccines, while effective, face limited uptake due to cold chain requirements and potential safety concerns in immunocompromised populations.
- For instance, the Baiya SARS-CoV-2 Vax 1 subunit vaccine demonstrated strong neutralizing antibody responses in preclinical trials using low antigen doses, highlighting the efficiency and adaptability of subunit vaccine formulations.
By Route of Administration:
Recombinant vaccines are administered via parenteral and oral routes, with parenteral vaccines capturing 78% of the market share in 2024. Their dominance is fueled by higher efficacy, broader clinical acceptance, and established injection-based immunization programs across hospitals and clinics globally. Oral vaccines, although convenient and needle-free, account for a smaller share due to stability issues and limited indications. Increasing government immunization initiatives and growing awareness about vaccine-preventable diseases are driving the overall market, reinforcing the preference for parenteral administration in routine and mass vaccination campaigns.
- For instance, the COVID-19 vaccine Convidecia Air®, an inhaled recombinant vaccine developed by CanSinoBIO, exemplifies the growth in nasal delivery methods, leveraging inhalation to stimulate mucosal immunity effectively.
By Disease Indication:
Within disease indications, the market is led by Hepatitis B vaccines, holding 28% of the market share in 2024, driven by mandatory immunization programs and rising prevalence of Hepatitis B globally. Human Papillomavirus (HPV) vaccines follow closely, supported by cervical cancer prevention initiatives. Rotavirus, herpes zoster, and meningococcal B vaccines contribute smaller shares but are witnessing growth due to increasing pediatric vaccination programs and awareness of adult immunization. The market growth is propelled by government-led vaccination campaigns, expanding healthcare infrastructure, and rising focus on disease prevention and immunization coverage worldwide.
Key Growth Drivers
Rapid Rise in Infectious Diseases
The increasing prevalence of infectious diseases worldwide acts as a key growth driver for the recombinant vaccine market. Governments and healthcare organizations are intensifying vaccination programs to control diseases such as Hepatitis B, HPV, and Rotavirus. Rising awareness about disease prevention, coupled with growing public health initiatives, is boosting vaccine adoption. Additionally, urbanization, global travel, and changing lifestyle patterns contribute to higher exposure to pathogens, increasing the demand for safe and effective recombinant vaccines across all age groups, thereby driving market expansion.
- For instance, the quadrivalent HPV vaccine showed 100% efficacy against four HPV subtypes (6/11/16/18) three years post-vaccination, significantly reducing the incidence of cervical lesions in young women.
Technological Advancements in Vaccine Development
Continuous innovation in recombinant DNA technology and vaccine formulations is propelling market growth. Advanced techniques allow the development of subunit and multivalent vaccines that are highly specific, safer, and effective against complex infectious agents. Improvements in adjuvants, delivery systems, and stability of vaccines enhance immunogenicity and shelf life. These technological developments not only increase the acceptance of recombinant vaccines among healthcare providers and patients but also expand applications across new disease indications, strengthening overall market adoption and facilitating faster response to emerging infectious diseases.
- For instance, advanced adjuvants like AS37, a synthetic TLR7a agonist adjuvant combined with alum, have shown potent immunogenicity and acceptable safety profiles in Phase I clinical trials for meningococcal and hepatitis B vaccines.
Government Initiatives and Immunization Programs
Supportive government policies and large-scale immunization programs worldwide are significantly driving the recombinant vaccine market. Initiatives by agencies such as WHO, CDC, and national healthcare authorities promote vaccination awareness and accessibility, particularly in developing regions. Subsidized vaccine programs, mandatory immunization schedules, and public-private collaborations encourage higher uptake. Funding for research and development, coupled with policies ensuring affordability and distribution, reinforces vaccine penetration, enabling wider population coverage. Such government-led efforts create a favorable regulatory environment, boosting both market growth and public trust in recombinant vaccines.
Key Trends and Opportunities
Rising Adoption of Combination and Multivalent Vaccines
A prominent trend in the recombinant vaccine market is the growing preference for combination and multivalent vaccines, which protect against multiple pathogens in a single dose. This approach reduces the number of injections required, improves patient compliance, and streamlines immunization schedules. Pediatric and adult immunization programs increasingly favor these vaccines to enhance coverage and efficiency. Manufacturers are investing in developing innovative formulations that combine antigens without compromising safety or efficacy, creating significant market opportunities in regions with high vaccination demand and limited healthcare resources.
- For instance, Sanofi Pasteur developed Hexyon, a fully-liquid hexavalent combination vaccine protecting against diphtheria, tetanus, pertussis, poliovirus, Hib, and hepatitis B, streamlining vaccination schedules.
Expansion into Emerging Markets
Emerging markets in Asia Pacific, Latin America, and Africa present substantial growth opportunities for recombinant vaccines due to rising healthcare awareness, expanding vaccination infrastructure, and increasing disposable incomes. Governments in these regions are prioritizing immunization programs to combat infectious diseases, creating demand for reliable vaccine solutions. Local manufacturing, strategic partnerships, and technology transfers further facilitate market penetration. This expansion allows global players to tap into underserved populations while addressing regional healthcare challenges, driving revenue growth and fostering long-term sustainability in the recombinant vaccine sector.
- For instance, Sinergium Biotech in Argentina and BioManguinhos in Brazil are actively participating in mRNA vaccine technology transfer programs, supporting local development to reduce import dependency and improve timely vaccine access.
Key Challenges
High Manufacturing Costs and Complex Production
Recombinant vaccines involve intricate production processes, including advanced cell culture systems and stringent quality control, leading to high manufacturing costs. These factors limit affordability and accessibility, particularly in low-income regions. Production complexity also increases dependency on specialized facilities and skilled personnel, constraining rapid scale-up during outbreaks. Companies must invest heavily in R&D and infrastructure to maintain consistent supply and regulatory compliance. These challenges can impact market growth by restricting adoption rates, particularly where cost-sensitive healthcare systems struggle to implement large-scale vaccination programs.
Regulatory and Safety Concerns
Strict regulatory frameworks and stringent approval processes pose a significant challenge for recombinant vaccines. Regulatory agencies require extensive clinical trials to validate safety and efficacy, which can delay product launches and increase development costs. Additionally, public concerns about adverse effects and vaccine hesitancy can affect market acceptance. Compliance with international standards and post-marketing surveillance further complicates commercialization. These regulatory and safety hurdles necessitate continuous investment in quality assurance and monitoring, slowing market expansion despite growing global demand for recombinant vaccines.
Regional Analysis
North America
North America’s recombinant vaccine market was valued at USD 1,154.18 million in 2018, increasing to USD 2,232.07 million in 2024, and is projected to reach USD 4,756.80 million by 2032, at a CAGR of 9.9%. The region holds 23% of the global market share in 2024, driven by strong healthcare infrastructure, government immunization programs, and high awareness of vaccine-preventable diseases. The U.S. dominates the market through advanced R&D, innovative vaccines, and strategic collaborations, ensuring consistent adoption and growth.
Europe
Europe was valued at USD 1,289.74 million in 2018, is expected to reach USD 2,571.09 million in 2024, and is projected at USD 5,707.32 million by 2032, growing at a CAGR of 10.4%. With a 25% market share in 2024, strong healthcare infrastructure, preventive vaccination programs, and strict regulatory frameworks drive growth. Key countries such as the UK, Germany, and France lead adoption through government campaigns and investments in vaccine technology, particularly for HPV, Hepatitis B, and Rotavirus.
Asia Pacific
Asia Pacific’s market was valued at USD 1,566.22 million in 2018, projected to reach USD 3,131.68 million in 2024, and estimated at USD 6,978.88 million by 2032, registering a CAGR of 10.5%. Accounting for 26% of the global market share in 2024, the region benefits from rising population, improving healthcare infrastructure, and government vaccination initiatives. China, India, and Japan drive growth through local production, affordability programs, and expanding pediatric and adult immunization programs.
Latin America
Latin America’s recombinant vaccine market was USD 525.65 million in 2018, expected to grow to USD 1,039.82 million in 2024, and projected at USD 2,285.03 million by 2032, at a CAGR of 10.3%. Holding around 11% of the global market share in 2024, Brazil and Argentina lead adoption through government vaccination programs, local manufacturing, and partnerships with global vaccine makers. Rising healthcare access and awareness campaigns are boosting market growth across the region.
Middle East
The Middle East market was valued at USD 233.08 million in 2018, rising to USD 426.96 million in 2024, and expected to reach USD 839.31 million by 2032, growing at a CAGR of 8.8%. With around 4% of the global market share in 2024, growth is driven by government vaccination programs, expanding healthcare infrastructure, and partnerships with global manufacturers. GCC countries, Israel, and Turkey dominate the market, supported by increasing awareness of infectious disease prevention.
Africa
Africa’s recombinant vaccine market stood at USD 107.28 million in 2018, projected to reach USD 202.23 million in 2024, and expected to grow to USD 415.46 million by 2032, with a CAGR of 9.4%. Representing 2% of the global market share in 2024, growth is supported by immunization programs, international funding, and healthcare partnerships. South Africa and Egypt are key contributors, focusing on HPV, Hepatitis B, and Rotavirus vaccines to expand access and improve vaccination coverage.
Market Segmentations:
By Type
- Subunit
- Live Attenuated
By Route of Administration
- Parenteral
- Oral
By Disease Indication
- Human Papillomavirus (HPV)
- Hepatitis B
- Rotavirus
- Herpes Zoster
- Meningococcal B
- Others
By Region:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the recombinant vaccine market is dominated by key players such as GSK plc, Serum Institute of India, Novartis AG, Merck & Co., Inc., Pfizer, Inc., Cipla Inc., Sanofi, Bharat Biotech, CanSino Biologics, and AstraZeneca. These companies are actively focusing on research and development, strategic collaborations, and product innovation to strengthen their market position. The market is characterized by high entry barriers due to complex regulatory approvals and advanced manufacturing requirements, giving established players a competitive advantage. Companies are expanding their portfolios through acquisitions, partnerships, and geographic expansion to capture emerging markets, particularly in Asia Pacific and Latin America. Continuous investment in novel vaccine technologies, combination and multivalent vaccines, and improvements in delivery systems further enhance competitiveness. Additionally, strong government collaborations and large-scale immunization programs support market penetration and long-term growth, making strategic innovation and distribution efficiency critical success factors.
Key Player Analysis
- GSK plc
- Serum Institute of India
- Novartis AG
- Merck & Co., Inc.
- Pfizer, Inc.
- Cipla Inc.
- Sanofi
- Bharat Biotech
- CanSino Biologics
- AstraZeneca
- Other Key Players
Recent Developments
- In May 2024, Novavax, Inc. entered into a co-exclusive licensing agreement with Sanofi S.A. to co-commercialize its adjuvanted COVID-19 recombinant protein vaccine globally, excluding certain Asia-Pacific markets.
- In April 2025, GC Biopharma gained approval from South Korea’s Ministry of Food and Drug Safety (MFDS) for BARYTHRAX, recognized as the world’s first recombinant anthrax vaccine.
- In March 2025, ImmunityBio, Inc. began the first dosing of its recombinant BCG vaccine (rBCG) under the Expanded Access Program (EAP) in the United States to help address BCG shortages used in bladder cancer treatment.
- In July 2025, Vaxart, Inc. announced that its stock began trading on OTCQX and highlighted the continued development of its oral recombinant pill-based vaccines targeting coronavirus, norovirus, and influenza, using its proprietary vaccine platform.
Report Coverage
The research report offers an in-depth analysis based on Type, Route of Administration, Disease Indication and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market is expected to grow steadily due to increasing prevalence of infectious diseases worldwide.
- Rising government immunization programs will continue to boost vaccine adoption across regions.
- Technological advancements in recombinant DNA and vaccine formulations will drive innovation and effectiveness.
- Growing preference for combination and multivalent vaccines will enhance patient compliance and coverage.
- Expansion into emerging markets in Asia Pacific, Latin America, and Africa will provide significant growth opportunities.
- Pediatric and adult immunization programs will further strengthen demand for recombinant vaccines.
- Strategic partnerships and collaborations among key players will accelerate product development and market reach.
- Increasing awareness and focus on disease prevention will support market growth.
- Regulatory support and streamlined approval processes will facilitate faster market entry of novel vaccines.
- Investments in manufacturing infrastructure and distribution channels will improve accessibility and scalability globally.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rapid Rise in Infectious Diseases
The increasing prevalence of infectious diseases such as Hepatitis B, HPV, and Rotavirus is prompting governments and healthcare organizations to intensify vaccination programs, directly boosting demand for recombinant vaccines.
Technological Advancements in Vaccine Development
Continuous innovation in recombinant DNA technology and vaccine formulations enables the creation of safer, more effective, and multivalent vaccines, expanding the range of preventable diseases and accelerating market adoption.
Government Initiatives and Immunization Programs
Supportive government policies, large-scale immunization campaigns, and public-private collaborations are increasing vaccine accessibility and coverage, particularly in developing regions, thereby driving market growth.
Rising Adoption of Combination and Multivalent Vaccines
The preference for vaccines that protect against multiple pathogens in a single dose is improving patient compliance and streamlining immunization schedules, leading to higher uptake in both pediatric and adult populations.
Expansion into Emerging Markets
Growing healthcare awareness, improving infrastructure, and increasing disposable incomes in Asia Pacific, Latin America, and Africa are creating substantial opportunities for market expansion and penetration among underserved populations.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Recombinant Vaccine Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Recombinant Vaccine Market projected to grow between 2025 and 2032?
Which Recombinant Vaccine Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Recombinant Vaccine Market?
Who are the major players in this Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Subunit
- 1.2.2 Live Attenuated
- 1.3 By Disease Indication
- 1.3.1 Hepatitis B
- 1.3.2 Human Papillomavirus (HPV)
- 1.3.3 Rotavirus
- 1.3.4 Herpes Zoster
- 1.3.5 Meningococcal B
- 1.3.6 Others
- 1.4 By Route of Administration
- 1.4.1 Parenteral
- 1.4.2 Oral
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 9,603.8 Million → 2032: USD 20,982.8 Million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Recombinant Vaccines Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Recombinant Vaccines Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Recombinant Vaccines Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Recombinant Vaccines Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Recombinant Vaccines Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Recombinant Vaccines Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Recombinant Vaccines Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Recombinant Vaccines Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 9,603.8 Million → 2032: USD 20,982.8 Million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Recombinant Vaccines Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Subunit
- 12.3.7.2 Live Attenuated
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Disease Indication - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Hepatitis B
- 12.4.7.2 Human Papillomavirus (HPV)
- 12.4.7.3 Rotavirus
- 12.4.7.4 Herpes Zoster
- 12.4.7.5 Meningococcal B
- 12.4.7.6 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Route of Administration - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Parenteral
- 12.5.7.2 Oral
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Recombinant Vaccines Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Recombinant Vaccines Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Recombinant Vaccines Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 GSK plc
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Serum Institute of India
- 17.4 Novartis AG
- 17.5 Merck & Co., Inc.
- 17.6 Pfizer, Inc.
- 17.7 Sanofi
- 17.8 Bharat Biotech
- 17.9 CanSino Biologics
- 17.10 AstraZeneca
- 17.11 Cipla Inc.
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

