
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Remote Breathalysers Market Size 2024 | USD 735 Million |
| Remote Breathalysers Market, CAGR | 4.6% |
| Remote Breathalysers Market Size 2032 | USD 1053.27 Million |
Market Overview:
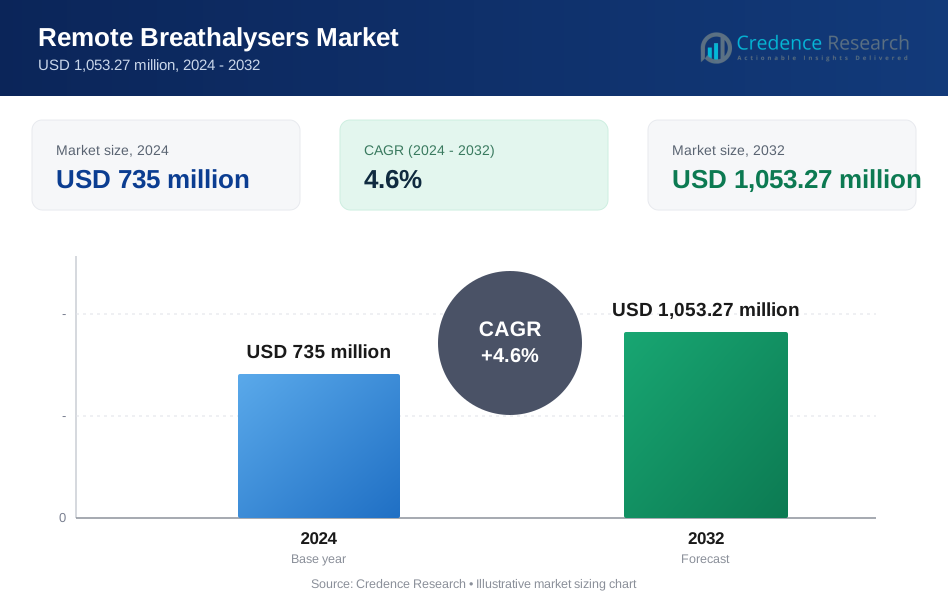
The Remote Breathalysers Market is projected to grow from USD 735 million in 2024 to an estimated USD 1053.27 million by 2032, with a compound annual growth rate (CAGR) of 4.6% from 2024 to 2032.
The Remote Breathalysers Market’s Key drivers include the growing adoption of remote alcohol monitoring technologies by law enforcement agencies and employers concerned with occupational safety. The need to ensure road safety and reduce accidents due to drunk driving has led to an increased focus on advanced breathalyser technologies. Additionally, advancements in Internet of Things (IoT) technology have made it easier to integrate remote breathalysers with mobile applications and cloud-based platforms, allowing for real-time monitoring and reporting. Rising concerns over alcohol-related incidents in public transportation and industries handling heavy machinery have also contributed to market growth, as organizations seek solutions to improve employee safety and compliance with local laws and regulations.
Regionally, North America dominates the remote breathalysers market, driven by stringent government regulations and high awareness about the dangers of alcohol consumption while driving or at the workplace. The United States, in particular, is a key market due to the strong enforcement of DUI laws and the widespread adoption of remote alcohol monitoring in probation and parole systems. Europe follows closely, with countries like the UK, Germany, and France enforcing strict road safety regulations. Meanwhile, the Asia-Pacific region is expected to witness the highest growth during the forecast period, owing to increasing urbanization, rising disposable incomes, and growing awareness of road safety. Key emerging markets in the region include China, India, and Japan, where governments are implementing stricter regulations to combat drunk driving.
Market Drivers:
Increasing Demand for Alcohol Monitoring in Law Enforcement:
One of the primary drivers of the remote breathalysers market is the increasing need for alcohol monitoring in law enforcement. Governments and authorities worldwide are implementing stricter laws to curb alcohol-related offenses, particularly driving under the influence (DUI). For instance, in 2022, 13,524 people died in alcohol-related crashes in the United States, with one person dying every 39 minutes in drunk-driving crashes. These laws often mandate the use of breathalysers to monitor and control alcohol consumption, especially among drivers and individuals under probation. Remote breathalysers provide real-time monitoring solutions, allowing law enforcement agencies to monitor offenders from a distance, ensuring compliance without the need for frequent in-person checks.
Growing Adoption in Workplace Safety Programs:
The rising focus on occupational health and safety, particularly in industries such as transportation, construction, and manufacturing, has further driven the adoption of remote breathalysers. Companies operating in high-risk sectors are increasingly incorporating alcohol testing as part of their workplace safety protocols to reduce the risk of accidents caused by impaired employees. Remote breathalysers offer employers a cost-effective and efficient method of monitoring employees’ alcohol levels without disrupting operations. The ability to conduct regular and random checks through mobile and cloud-based systems has also enhanced employer compliance with workplace safety regulations. This growing trend is particularly strong in regions where regulatory frameworks mandate alcohol testing for specific industries, further boosting market demand.
Advancements in IoT and Connected Devices:
Technological advancements, particularly in Internet of Things (IoT) technology, have significantly influenced the growth of the remote breathalysers market. Modern breathalysers now come equipped with IoT capabilities, allowing them to be integrated with smartphones and cloud-based platforms. These devices enable real-time data collection, storage, and analysis, providing instant feedback to both users and monitoring authorities. The convenience of remote monitoring, coupled with the ability to track alcohol consumption over time, has led to increased adoption of these devices across various sectors. IoT-enabled breathalysers have also found use in rehabilitation programs, where continuous monitoring is essential for tracking patient progress. As IoT technology continues to evolve, the remote breathalysers market is expected to benefit from further enhancements in connectivity and data management.
Rising Awareness of Road and Public Safety:
Public awareness of the dangers of alcohol consumption, particularly in relation to road safety, has been a significant driver for the remote breathalysers market. Drunk driving is a leading cause of traffic accidents globally, prompting governments, non-governmental organizations, and public safety advocates to push for stricter regulations and more comprehensive monitoring solutions. For instance, remote breathalysers offer a proactive approach to preventing alcohol-related accidents by allowing individuals to monitor their alcohol levels before operating a vehicle. Public safety campaigns, combined with the enforcement of stricter DUI regulations, have created a favorable environment for the adoption of remote breathalysers. As awareness continues to grow, both consumers and authorities are likely to increase their reliance on these devices, further driving market expansion.
Market Trends:
Integration of AI and Data Analytics:
One of the prominent trends shaping the remote breathalysers market is the integration of artificial intelligence (AI) and data analytics. AI is increasingly being used to enhance the functionality of breathalysers, enabling devices to analyze patterns of alcohol consumption and predict future behavior. Advanced AI algorithms can assess real-time data to provide insights into the user's alcohol levels over time, allowing for more effective monitoring and intervention. These systems are especially valuable in healthcare and law enforcement, where continuous tracking and predictive capabilities can help authorities or healthcare professionals manage individuals with alcohol dependency. As AI technology evolves, the ability to offer personalized recommendations and early warnings through remote breathalysers is becoming a key market differentiator.
Growing Use in Remote Health Monitoring:
Remote breathalysers are becoming a crucial component of remote health monitoring, particularly for patients recovering from alcohol-related disorders. The global rise in telehealth services, accelerated by the COVID-19 pandemic, has led to increased adoption of remote monitoring devices, including breathalysers. For instance, The Soberlink system, operational since 2011, has successfully monitored more than 55,000 individuals, with participants typically completing 2-4 breath tests per day within two-hour windows of agreed-upon times. These devices allow healthcare providers to track patients' alcohol consumption remotely, reducing the need for in-person visits while maintaining effective oversight. The data collected can be shared with healthcare professionals in real-time, enabling timely intervention if a patient’s alcohol levels exceed safe thresholds. This trend is expected to grow as the healthcare industry continues to expand its focus on remote care and chronic condition management, creating new opportunities for the breathalysers market.
Miniaturization and Portability:
The miniaturization of breathalyser devices and the growing demand for portable, easy-to-use products are key trends driving the market. Modern remote breathalysers are becoming more compact and lightweight, making them convenient for personal use in various situations. These smaller devices are designed to be highly accurate, user-friendly, and easily integrated with smartphones or wearable devices. For instance, The HOUND CANNABIS BREATHALYZER represents advancement in portable testing, providing results within minutes of on-site testing. Quest Diagnostics' laboratory in Lenexa, KS, has developed specialized mass spectrometry techniques to match these portable devices' sensitivity levels. Portability is particularly important for consumers who require constant monitoring, such as individuals in recovery programs or those subject to law enforcement mandates. As consumers prioritize convenience, manufacturers are focusing on developing devices that balance portability with high-performance standards, further fueling market demand.
Increasing Adoption in Corporate Wellness Programs:
The rise of corporate wellness programs aimed at promoting employee health and safety is another trend influencing the remote breathalysers market. Companies, especially those in high-risk industries such as transportation and construction, are incorporating regular alcohol testing into their wellness initiatives. This proactive approach to ensuring a safe work environment is not only reducing workplace accidents but also improving productivity and morale. Remote breathalysers offer companies a seamless way to monitor employees' alcohol consumption without intruding on their privacy, as the data can be collected and reported remotely. As corporate wellness programs continue to expand, particularly in regions with strict workplace safety regulations, the demand for remote breathalysers is expected to grow significantly.
Market Restraints and Challenges:
High Cost of Advanced Remote Breathalysers:
One of the key restraints in the remote breathalysers market is the high cost associated with advanced devices. While the integration of cutting-edge technologies such as IoT, AI, and data analytics has enhanced the functionality of breathalysers, it has also driven up the cost of these devices. For many consumers and organizations, particularly in developing regions, the price of advanced remote breathalysers can be prohibitive, limiting their adoption. Smaller businesses or budget-conscious institutions may opt for less expensive, manual alternatives that do not offer remote monitoring capabilities, thus restraining market growth. As a result, manufacturers face the challenge of balancing technological sophistication with affordability to reach a broader customer base.
Privacy Concerns and Data Security Issues:
The increasing use of connected breathalysers that transmit data in real-time has raised concerns over privacy and data security. Remote breathalysers often collect sensitive information about an individual's alcohol consumption, which can be misused if not adequately protected. Data breaches or unauthorized access to this information can lead to legal and reputational challenges for both manufacturers and users. These privacy concerns are particularly relevant in workplace or legal settings, where individuals may be reluctant to use such devices due to fears of surveillance or data misuse. Ensuring robust data protection and addressing these privacy issues are critical challenges that manufacturers must overcome to build trust and encourage broader adoption.
Lack of Standardization in Regulations:
Another significant challenge facing the remote breathalysers market is the lack of standardized regulations across different regions. While some countries have stringent laws mandating alcohol monitoring, others have inconsistent or less comprehensive regulations, leading to uneven adoption. This lack of uniformity creates market fragmentation, making it difficult for manufacturers to establish a consistent global presence. Companies operating in multiple regions must navigate varying regulatory environments, which can be costly and complex. Developing industry standards and harmonized regulations would help streamline the market and foster growth across geographies.
Market Segmentation Analysis:
By Product Type, the market is categorized into Clinical Laboratory Analyzers, Point-of-Care, and Testing Analyzers. Point-of-Care devices are gaining popularity due to their portability, ease of use, and ability to provide real-time results. Clinical Laboratory Analyzers, while more complex, are primarily used in hospital settings for precise and comprehensive alcohol and substance abuse testing.
By Application, the market is divided into Drug Abuse Detection, Alcohol Detection, and Others. Alcohol detection is the largest segment, driven by the increasing need for monitoring and preventing alcohol-related incidents, particularly in law enforcement and workplace safety programs. Drug abuse detection is also growing, supported by rising concerns over substance abuse and its impact on public and workplace safety.
By Technology, the market is segmented into Fuel Cell Technology, Semiconductor Oxide Sensor Technology, Infrared Spectroscopy, and Others. Fuel cell technology dominates due to its high accuracy and reliability in alcohol detection. Semiconductor oxide sensors are more cost-effective, making them attractive for personal and smaller-scale applications, while infrared spectroscopy is mainly used in advanced clinical and laboratory settings.
By End Users, the market includes Hospitals and Health Centers, Government and Private Workplaces, and Others. Government and workplace settings lead this segment due to regulatory requirements for monitoring employee and public safety. Hospitals and health centers also utilize these devices for medical testing and monitoring purposes.
Segmentation:
By Product Type-
- Clinical Laboratory Analyzers
- Point-Of-Care
- and Testing Analyzers.
By Application-
- Drug Abuse Detection
- Alcohol Detection
- and Others.
By Technology-
- Fuel Cell Technology
- Semiconductor Oxide Sensor Technology
- Infrared Spectroscopy
- Others
By End Users-
- Hospitals and Health Centers
- Government and Private Workplaces
- Others
Based on Region
- North America
- US
- Canada
- Mexico
- Europe
- Germany
- France
- UK
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
Regional Analysis:
North America
North America holds the largest share of the remote breathalysers market, accounting for approximately 40% of the global market. The United States dominates this region, driven by stringent DUI (driving under the influence) laws and an emphasis on public and workplace safety. High adoption rates in law enforcement, parole systems, and corporate safety programs have contributed significantly to market growth. In addition, the integration of advanced technologies such as IoT and AI in breathalysers, alongside government funding for road safety programs, has further propelled demand. Canada also plays a key role in market growth due to its strict alcohol consumption regulations and rising use of breathalysers in healthcare and workplace safety.
Europe
Europe is the second-largest region, holding about 30% of the global market share. Countries such as the UK, Germany, and France are leading contributors, largely due to stringent road safety regulations and growing workplace safety initiatives. The European Union’s strict regulations regarding alcohol consumption and driving, combined with rising public awareness campaigns, have fueled the adoption of remote breathalysers. The presence of well-established healthcare infrastructure in many European countries also supports the integration of remote breathalysers in clinical settings for alcohol and substance abuse monitoring.
Asia-Pacific
The Asia-Pacific region is expected to witness the highest growth rate, with a market share of around 20%. Rapid urbanization, increasing disposable income, and growing concerns over road safety have driven the demand for remote breathalysers in this region. Governments in countries like China, India, and Japan are implementing stricter laws to curb alcohol-related road accidents, creating a favorable environment for market growth. The rise in industrial safety standards, especially in sectors like manufacturing and transportation, has also contributed to the increasing adoption of remote breathalysers in the workplace. Furthermore, advancements in mobile technology and the growing use of connected devices are expected to boost market growth in this region.
Latin America and Middle East & Africa
Latin America and the Middle East & Africa account for a smaller share of the market, collectively representing about 10% of the global market. In Latin America, Brazil and Mexico are leading countries in the adoption of remote breathalysers, primarily due to rising concerns over traffic safety and increasing regulatory pressure to prevent alcohol-related accidents. In the Middle East & Africa, market growth is driven by rising investments in healthcare infrastructure and growing government initiatives to improve public safety. However, economic challenges and less stringent regulatory environments in some parts of these regions may limit market expansion.
Key Player Analysis:
- Abbott Laboratories
- Alcohol Monitoring Systems, Inc.
- Alere, Inc.
- Andatech Private Limited
- BACtrack
- Dragerwerk AG
- Intoximeters, Inc.
- Lifeloc Technologies
- Lion Laboratories Limited
- Quest Diagnostics
Competitive Analysis:
The remote breathalysers market is highly competitive, with several key players dominating through technological innovation, product diversification, and strategic partnerships. Leading companies such as Drägerwerk AG, Lifeloc Technologies, and BACtrack focus on integrating advanced technologies like IoT and AI to enhance the accuracy and connectivity of their devices. These firms also invest heavily in research and development to stay ahead of emerging competitors. Smaller companies and new entrants are increasingly focusing on affordability and ease of use to capture market share, particularly in developing regions. Additionally, strategic partnerships between manufacturers and law enforcement agencies, healthcare providers, and corporate safety programs further intensify competition. The competitive landscape is shaped by continuous product innovation, regulatory compliance, and expansion into new markets, with companies seeking to differentiate themselves through enhanced product features, customer support, and global reach. This environment is likely to spur further advancements and consolidation in the market.
Recent Developments:
- In September 2022 Hound Labs formed a strategic alliance with Quest Diagnostics to establish Quest as the exclusive provider of laboratory services for confirmatory testing using the HOUND CANNABIS BREATHALYZER.
- In February 2022 Cannabix Technologies Inc. launched its version 4.0 THC Breath Analyzer (THCBA) prototype and portable system for field use.
Market Concentration & Characteristics:
The remote breathalysers market is moderately concentrated, with a few leading players, such as Drägerwerk AG, BACtrack, and Lifeloc Technologies, holding significant market shares. These companies dominate the market through extensive product portfolios, advanced technology integration, and strong distribution networks. However, the market also features a growing number of smaller firms and startups that focus on innovation, particularly in affordability, portability, and user-friendly designs. The market is characterized by rapid technological advancements, particularly in IoT-enabled breathalysers and data analytics capabilities, which enhance real-time monitoring and reporting. Stringent regulatory requirements, especially in developed regions like North America and Europe, further shape the market, driving demand for high-accuracy devices. Additionally, the market is becoming increasingly competitive due to the expansion into emerging regions, where rising awareness of alcohol-related safety issues and growing regulatory frameworks are fostering new growth opportunities.
Report Coverage:
The research report offers an in-depth analysis based on By Product Type, By Application, By Technology and By End Users. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Increased integration of AI and IoT will enhance real-time data analysis and remote monitoring capabilities.
- Rising global awareness of road safety will drive demand for remote breathalysers, especially in developing regions.
- Adoption of fuel cell technology will continue to dominate due to its accuracy and reliability in alcohol detection.
- Growth in telemedicine and remote health monitoring will expand the use of breathalysers in healthcare settings.
- Regulatory advancements and stricter DUI laws globally will fuel market growth, particularly in North America and Europe.
- Emerging markets in Asia-Pacific will witness the fastest growth, driven by urbanization and regulatory initiatives.
- Demand for portable and user-friendly devices will increase, catering to both personal and workplace safety needs.
- Increasing corporate wellness programs focusing on alcohol testing will provide new opportunities in the corporate sector.
- Technological innovations, including miniaturization and cloud integration, will create competitive advantages.
- Data privacy and security concerns will remain critical challenges that manufacturers must address to ensure user trust.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Increasing Demand for Alcohol Monitoring in Law Enforcement
Stricter DUI laws and the need for real-time monitoring of offenders have led law enforcement agencies to adopt remote breathalysers, enabling compliance checks without frequent in-person visits and supporting public safety initiatives.
Growing Adoption in Workplace Safety Programs
Industries with high safety risks, such as transportation and construction, are integrating remote breathalysers into their safety protocols to reduce accidents caused by impaired employees and to comply with regulatory requirements.
Advancements in IoT and Connected Devices
The integration of IoT technology allows remote breathalysers to connect with mobile apps and cloud platforms, enabling real-time data collection, monitoring, and reporting, which enhances usability and expands applications in healthcare and law enforcement.
Rising Awareness of Road and Public Safety
Public campaigns and stricter regulations targeting drunk driving have increased the adoption of remote breathalysers, as both individuals and authorities seek proactive solutions to prevent alcohol-related accidents.
Integration of AI and Data Analytics
The use of AI and data analytics in remote breathalysers enables advanced pattern recognition, predictive monitoring, and personalized feedback, making these devices more effective for continuous monitoring in healthcare and legal settings.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth of the Remote Breathalysers Market?
What are the key drivers of the market’s growth?
Which region leads the Remote Breathalysers Market?
What are the major challenges in the market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End Users
- 1.2.1 Hospitals and Health Centers
- 1.2.2 Government and Private Workplaces
- 1.2.3 Others
- 1.3 By Technology
- 1.3.1 Fuel Cell Technology
- 1.3.2 Semiconductor Oxide Sensor Technology
- 1.3.3 Infrared Spectroscopy
- 1.3.4 Others
- 1.4 By Application
- 1.4.1 Drug Abuse Detection
- 1.4.2 Alcohol Detection
- 1.4.3 Others
- 1.5 By Product Type
- 1.5.1 Clinical Laboratory Analyzers
- 1.5.2 Point-Of-Care
- 1.5.3 Testing Analyzers
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 735 million → 2032: USD 1,053.27 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Remote Breathalysers Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Remote Breathalysers Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Remote Breathalysers Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Remote Breathalysers Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Remote Breathalysers Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Remote Breathalysers Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Remote Breathalysers Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Remote Breathalysers Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 735 million → 2032: USD 1,053.27 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Remote Breathalysers Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End Users - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Hospitals and Health Centers
- 12.3.7.2 Government and Private Workplaces
- 12.3.7.3 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Technology - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Fuel Cell Technology
- 12.4.7.2 Semiconductor Oxide Sensor Technology
- 12.4.7.3 Infrared Spectroscopy
- 12.4.7.4 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Drug Abuse Detection
- 12.5.7.2 Alcohol Detection
- 12.5.7.3 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Product Type - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Clinical Laboratory Analyzers
- 12.6.7.2 Point-Of-Care
- 12.6.7.3 Testing Analyzers
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Remote Breathalysers End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Remote Breathalysers Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Remote Breathalysers Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Remote Breathalysers Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Abbott Laboratories
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Alcohol Monitoring Systems, Inc.
- 18.4 Alere, Inc.
- 18.5 Andatech Private Limited
- 18.6 BACtrack
- 18.7 Dragerwerk AG
- 18.8 Intoximeters, Inc.
- 18.9 Lifeloc Technologies
- 18.10 Lion Laboratories Limited
- 18.11 Quest Diagnostics
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

