
Market Overview
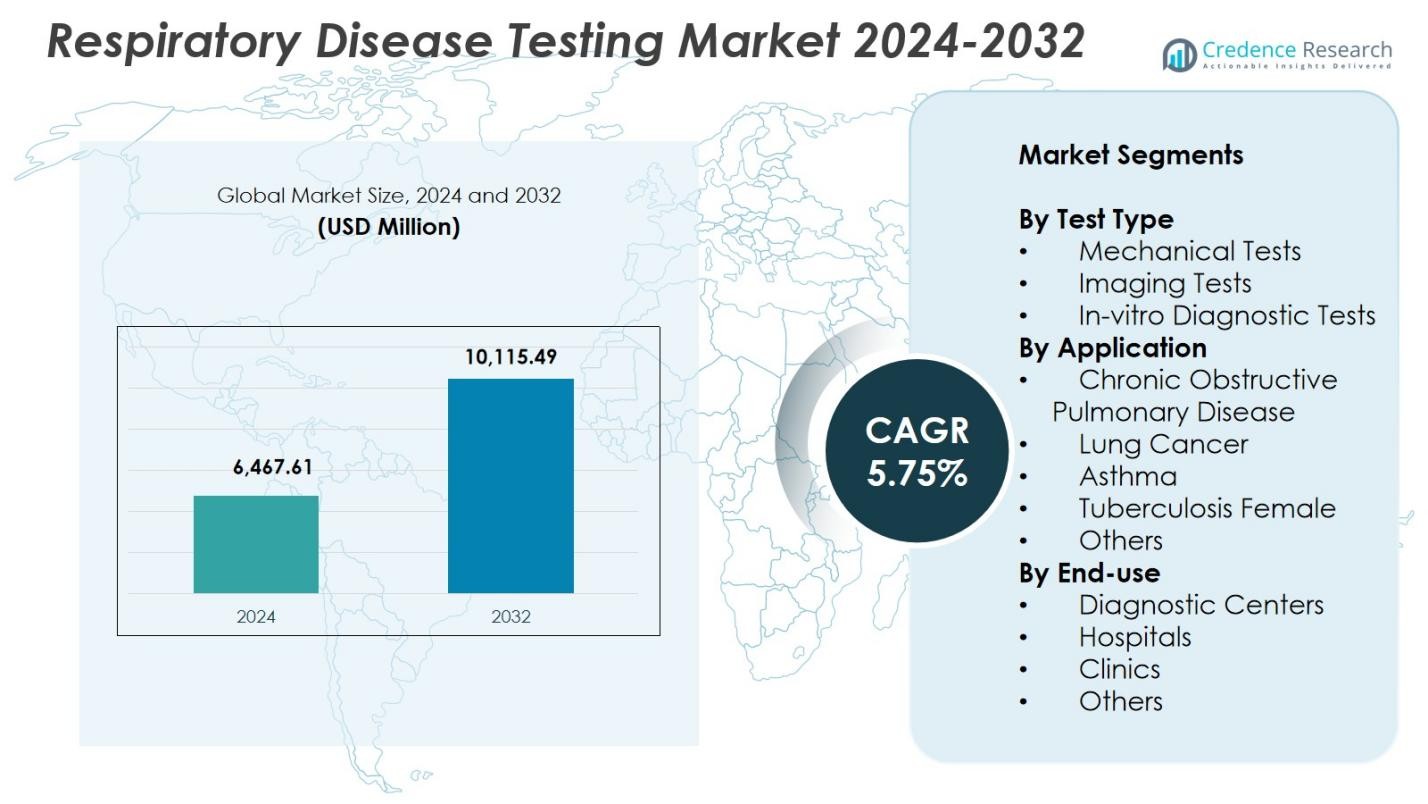
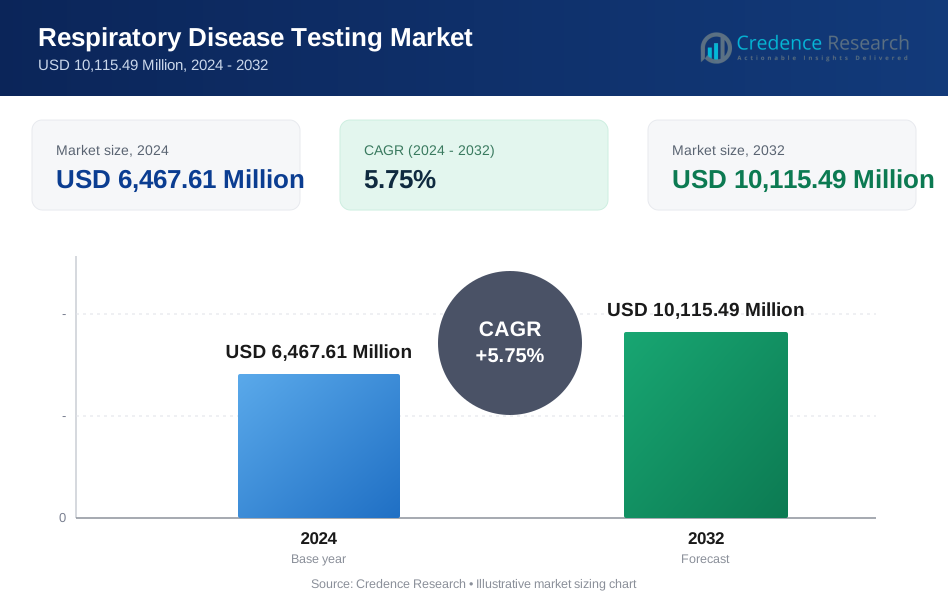
Respiratory Disease Testing Market size was valued at USD 6,467.61 Million in 2024 and is anticipated to reach USD 10,115.49 Million by 2032, at a CAGR of 5.75% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Respiratory Disease Testing Market Size 2024 | USD 6,467.61 Million |
| Respiratory Disease Testing Market, CAGR | 5.75% |
| Respiratory Disease Testing Market Size 2032 | USD 10,115.49 Million |
The Respiratory Disease Testing Market is shaped by the strong presence of leading players such as Medtronic, CAREstream Medical Ltd, VYAIRE MEDICAL INC, ResMed, Thermo Fischer Scientific, Fischer & Paykel, BioMerieux SA, Becton, Dickinson and Company, Abbott, and Koninklijke Philips N.V, who drive advancements in molecular diagnostics, imaging systems, spirometry devices, and point-of-care solutions. These companies focus on enhancing diagnostic accuracy, speed, and accessibility through continuous innovation and technology integration. North America led the market with 41.3% share in 2024, supported by robust healthcare infrastructure, high disease prevalence, and strong adoption of advanced respiratory diagnostic tools.
Market Insights
- The Respiratory Disease Testing Market reached USD 6,467.61 Million in 2024 and is projected to reach USD 10,115.49 Million by 2032, growing at a CAGR of 5.75%.
- Rising prevalence of COPD, asthma, lung cancer, and tuberculosis continues to drive strong demand for advanced diagnostics, including molecular assays, imaging systems, and spirometry tools.
- Key trends include rapid adoption of AI-powered imaging, digital spirometry, point-of-care PCR platforms, and home-based respiratory monitoring solutions that support early detection and remote care.
- Major players such as Medtronic, ResMed, Abbott, BioMerieux SA, Thermo Fischer Scientific, and VYAIRE MEDICAL INC expand product capabilities through innovation and healthcare partnerships.
- North America led with 41.3% share, Europe followed with 29.6%, and the In-vitro Diagnostic Tests segment dominated with 46.8% share, while high diagnostic equipment costs and workforce shortages remain notable restraints.
 Market Segmentation Analysis:
By Test Type:
The Respiratory Disease Testing Market is dominated by In-vitro Diagnostic (IVD) Tests, which accounted for 46.8% share in 2024, driven by their widespread use for early detection of respiratory infections, high accuracy, and ability to support molecular assays such as PCR and antigen testing. Increasing incidence of COPD, asthma, and infectious diseases accelerates the need for rapid and reliable diagnostic solutions. Mechanical tests and imaging tests continue to grow as complementary modalities, but the scalability, rapid turnaround time, and integration of automation in IVD platforms reinforce their leadership across global healthcare settings.
- For instance, bioMérieux's BIOFIRE Respiratory 2.1 (RP2.1) Panel serves as a frontline FDA-approved IVD test, identifying upper respiratory tract infections including COVID-19, influenza, and RSV in clinical settings.
By Application:
Chronic Obstructive Pulmonary Disease (COPD) led the Respiratory Disease Testing Market with 38.2% share in 2024, supported by rising global prevalence linked to smoking, pollution, and aging populations. The segment benefits from strong adoption of spirometry, biomarker-based testing, and imaging tools for disease monitoring and progression assessment. Advanced diagnostic systems offering early detection and personalized disease management accelerate growth. Asthma, lung cancer, tuberculosis, and other conditions continue to expand testing demand, but COPD remains the dominant application due to its chronic nature and the need for continuous diagnostic evaluation.
- For instance, ndd Medical Technologies offers the EasyOne Pro, a portable spirometer using TrueFlow ultrasound technology for accurate, calibration-free spirometry measurements in COPD patients.
By End-use:
The Hospitals segment dominated the Respiratory Disease Testing Market with 52.4% share in 2024, driven by their superior diagnostic infrastructure, availability of advanced imaging systems, and integration of molecular laboratories for high-volume testing. Hospitals serve as primary centers for managing acute and chronic respiratory conditions, enabling comprehensive evaluation through multidisciplinary care. Diagnostic centers and clinics continue to gain momentum with point-of-care testing and improved accessibility, yet hospitals remain the preferred end-use setting due to higher patient inflow, specialized respiratory units, and the ability to perform complex diagnostic procedures.
Key Growth Drivers
Rising Prevalence of Chronic and Infectious Respiratory Diseases
The increasing global burden of chronic and infectious respiratory conditions such as COPD, asthma, pneumonia, and tuberculosis continues to drive strong demand for advanced respiratory disease testing. Growing exposure to air pollution, tobacco consumption, occupational hazards, and lifestyle factors significantly elevates disease incidence across both developed and emerging regions. Healthcare providers are prioritizing early diagnosis to reduce complications, mortality rates, and overall treatment costs. As patient volumes rise, hospitals and diagnostic centers accelerate the adoption of modern testing modalities, including spirometry, biomarker assays, molecular diagnostics, and imaging technologies.
- For instance, Abbott's ID NOW platform delivers rapid molecular results in 13 minutes or less for respiratory pathogens including influenza A/B, RSV, and strep A from nasal swabs. This point-of-care system aids quick differentiation of viral infections to guide therapy in settings with high patient volumes.
Expansion of Molecular and Point-of-Care Testing Capabilities
Advancements in molecular diagnostics and point-of-care (POC) technologies are reshaping the Respiratory Disease Testing Market by enabling rapid, accurate, and decentralized testing. PCR platforms, multiplex assays, and portable analyzers offer improved sensitivity for detecting viral and bacterial respiratory pathogens. Their capability to deliver actionable results within minutes supports timely clinical decisions, particularly during outbreaks and emergency care scenarios. Increased investment in POC innovation and integration with digital reporting tools strengthens accessibility in remote regions. These developments support early intervention, reduce disease transmission, and boost market growth.
- For instance, bioMérieux's FilmArray system enables multiplex PCR detection of multiple respiratory viruses and bacteria simultaneously from a single sample, supporting comprehensive pathogen identification in minutes. Integration with automation enhances reliability for emergency care.
Increasing Healthcare Expenditure and Infrastructure Modernization
Rising healthcare spending, modernization of diagnostic infrastructure, and enhanced clinical capabilities in hospitals and diagnostic centers contribute significantly to market expansion. Governments and private healthcare investors are strengthening respiratory diagnostic capacities through new laboratory setups, improved imaging facilities, and adoption of automated testing systems. Emerging economies are prioritizing respiratory health due to rising pollution levels and growing patient loads, further accelerating investment. Enhanced reimbursement policies for respiratory testing and greater awareness of preventive healthcare also increase patient screening rates, reinforcing sustained market growth.
Key Trends & Opportunities
Integration of AI and Digital Technologies in Respiratory Diagnostics
Artificial intelligence, machine learning, and digital health tools are transforming respiratory disease diagnostics by improving accuracy, speed, and workflow efficiency. AI-powered imaging systems can detect early-stage abnormalities in lung scans, while algorithm-driven spirometry and predictive analytics enable better disease monitoring and risk assessment. Digital platforms also streamline data sharing between clinicians, supporting coordinated care. These innovations create opportunities for advanced diagnostic ecosystems that integrate automated interpretation, remote monitoring, and decision-support tools, addressing workforce shortages and enhancing diagnostic precision.
- For instance, Aidoc's AI algorithms analyze chest CT scans and achieve 93% sensitivity in detecting pulmonary embolisms, enabling rapid triage and notification to care teams for faster intervention.
Growing Adoption of Home-Based and Remote Respiratory Testing Solutions
The shift toward home-based diagnostics and telehealth-supported testing presents significant opportunities, particularly for chronic respiratory disease management. Portable spirometers, remote monitoring kits, and digital breath-analysis tools empower patients to track symptoms and lung function from home, reducing hospital visits and improving long-term disease control. Manufacturers are developing user-friendly devices integrated with mobile apps for real-time data transmission. This trend aligns with the rising preference for decentralized care, supporting early intervention and continuous disease surveillance while easing the burden on healthcare facilities.
- For instance, MIR's Smart One spirometer connects via Bluetooth to a dedicated smartphone app, enabling users to measure Peak Expiratory Flow (PEF) and Forced Expiratory Volume in 1 second (FEV1) in home settings for asthma or COPD monitoring.
Key Challenges
High Cost of Advanced Diagnostic Equipment and Testing Procedures
The elevated cost of respiratory imaging systems, molecular diagnostic platforms, and advanced analyzers remains a major challenge, particularly in low- and middle-income regions. High capital expenditure, recurring maintenance costs, and expensive consumables limit widespread adoption. Smaller clinics and diagnostic centers often struggle to justify investment, reducing access to advanced testing in underserved areas. Limited reimbursement coverage further exacerbates the issue, compelling patients to rely on basic diagnostics. This financial burden slows technology penetration and restricts equitable access to high-quality respiratory testing.
Shortage of Skilled Healthcare Professionals and Operational Barriers
The Respiratory Disease Testing Market faces persistent challenges due to limited availability of trained technicians, pulmonologists, and laboratory professionals capable of performing and interpreting advanced diagnostic tests. Inadequate training, high workload, and operational complexities in busy healthcare environments contribute to inefficient diagnostic workflows and delayed results. Additionally, stringent regulatory requirements and slow approval processes for innovative diagnostic technologies hinder timely market entry. These constraints affect testing accuracy, scalability, and service quality, ultimately limiting the market’s ability to meet growing diagnostic demands.
Regional Analysis
North America
North America dominated the Respiratory Disease Testing Market with 41.3% share in 2024, driven by advanced diagnostic infrastructure, high prevalence of COPD and asthma, and strong adoption of molecular and imaging-based testing. The region benefits from substantial healthcare spending, supportive reimbursement frameworks, and continuous technological innovation led by key manufacturers. Widespread integration of AI-enabled diagnostics, along with an extensive network of hospitals and specialized respiratory centers, enhances testing accuracy and accessibility. Growing awareness of early disease detection and an aging population further strengthen market growth across the United States and Canada.
Europe
Europe accounted for 29.6% share in 2024, supported by well-established healthcare systems, a rising burden of chronic respiratory diseases, and proactive public health initiatives promoting early screening. The region’s strong emphasis on preventive care and regulatory encouragement for advanced diagnostics foster steady adoption of molecular assays, spirometry, and imaging technologies. Countries such as Germany, the U.K., France, and Italy invest heavily in respiratory healthcare modernization. Increasing environmental pollution and occupational exposures further elevate testing demand. Ongoing collaborations between research institutes and diagnostic companies accelerate innovation and market expansion across the region.
Asia Pacific
Asia Pacific captured 21.8% share in 2024, propelled by rapid urbanization, high pollution levels, and increasing incidence of asthma, tuberculosis, and COPD. Expanding healthcare infrastructure in China, India, Japan, and Southeast Asia strengthens access to advanced diagnostic tools. Governments in the region are prioritizing early respiratory screening due to rising disease burdens and heightened public awareness. Growing investments in molecular diagnostics, imaging systems, and point-of-care devices drive significant market growth. The region’s large patient pool and improving affordability of diagnostic services position Asia Pacific as one of the fastest-growing markets through the forecast period.
Latin America
Latin America held 4.2% share in 2024, driven by increasing healthcare modernization, rising cases of chronic respiratory conditions, and improved access to diagnostic services in Brazil, Mexico, and Argentina. Public health initiatives targeting tuberculosis and smoking-related diseases support stronger adoption of diagnostic tests. Growth is further reinforced by expanding private healthcare facilities and gradual integration of molecular and imaging technologies. Despite economic constraints and uneven healthcare distribution, investments in urban medical centers and partnerships with global diagnostic companies help strengthen respiratory testing capabilities across major Latin American countries.
Middle East & Africa
The Middle East & Africa region accounted for 3.1% share in 2024, supported by growing healthcare investments, rising pollution-related respiratory conditions, and increased demand for early diagnostic screening. Gulf countries, including the UAE and Saudi Arabia, are expanding hospital infrastructure and adopting advanced molecular and imaging-based systems. In Africa, tuberculosis prevalence drives significant testing volume, though limited resources and workforce shortages constrain widespread adoption of high-end diagnostics. International health programs and technology partnerships continue to improve accessibility, supporting gradual market growth across the region.
Market Segmentations:
By Test Type
- Mechanical Tests
- Imaging Tests
- In-vitro Diagnostic Tests
By Application
- Chronic Obstructive Pulmonary Disease
- Lung Cancer
- Asthma
- Tuberculosis Female
- Others
By End-use
- Diagnostic Centers
- Hospitals
- Clinics
- Others
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the Respiratory Disease Testing Market features leading players such as Medtronic, CAREstream Medical Ltd, VYAIRE MEDICAL INC, ResMed, Thermo Fischer Scientific, Fischer & Paykel, BioMerieux SA, Becton, Dickinson and Company, Abbott, and Koninklijke Philips N.V. These companies strengthen the market through continuous innovation, portfolio expansion, and strategic collaborations. Major manufacturers focus on advancing molecular diagnostics, spirometry systems, imaging technologies, and point-of-care solutions to support rapid and accurate respiratory disease detection. Increasing investment in AI-enabled diagnostics, remote monitoring tools, and automated laboratory systems further enhances technological leadership. Companies also expand global reach through partnerships with hospitals, diagnostic centers, and research institutes, while targeting emerging markets with cost-effective solutions. Regulatory approvals, product launches, and acquisitions remain key strategies to enhance competitive positioning. Overall, the market is characterized by strong R&D pipelines, expanding digital integration, and rising emphasis on early diagnosis.
Key Player Analysis
- Abbott
- Becton
- Dickinson and Company
- Koninklijke Philips N.V
- ResMed
- VYAIRE MEDICAL INC
- Fischer & Paykel, Medtronic
- BioMerieux SA
- CAREstream Medical Ltd
- Thermo Fischer Scientific
Recent Developments
- In August 2025, Roche announced FDA 510(k) clearance for the cobas Respiratory 4-flex, its first respiratory test using TAGS technology for detecting SARS-CoV-2, influenza A, influenza B, and RSV in a single PCR assay.
- In October 2025, Thermo Fisher Scientific launched its new Molecular Microscope® Diagnostic System for Lung (MMDx® Lung), designed to improve detection of lung transplant rejection and injury.
- In September 2024, Vitalograph acquired Morgan Scientific, a US-based company specializing in software for pulmonary function testing systems like ComPAS2, to strengthen its respiratory diagnostics offerings.
Report Coverage
The research report offers an in-depth analysis based on Test Type, Application, End Use and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will expand steadily as early diagnosis becomes a priority across global healthcare systems.
- Adoption of AI-driven diagnostic platforms will improve accuracy and accelerate clinical decision-making.
- Molecular testing and rapid point-of-care devices will gain wider acceptance for respiratory disease screening.
- Remote and home-based testing solutions will grow as chronic disease management shifts toward decentralized care.
- Imaging advancements will enhance detection of early-stage lung disorders and support precision diagnosis.
- Integration of digital health tools will strengthen data connectivity, monitoring, and diagnostic automation.
- Emerging markets will experience faster adoption due to improving healthcare infrastructure and rising patient awareness.
- Product innovation will intensify as manufacturers develop portable, user-friendly, and high-sensitivity testing systems.
- Strategic collaborations between diagnostic companies and healthcare institutions will accelerate technology deployment.
- Increasing focus on preventive respiratory health will support regular screening programs and market expansion.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Respiratory Disease Testing Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Respiratory Disease Testing Market projected to grow between 2024 and 2032?
Which Respiratory Disease Testing Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Respiratory Disease Testing Market?
Who are the leading companies in the Respiratory Disease Testing Market?
Which region commanded the largest share of the Respiratory Disease Testing Market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Respiratory Disease Testing Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Respiratory Disease Testing Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 6,467.61 Million → 2032: USD 10,115.49 Million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Respiratory Disease Testing Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Respiratory Disease Testing Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Respiratory Disease Testing Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Respiratory Disease Testing Market Drivers
- 3.3 Respiratory Disease Testing Market Restraints & Challenges
- 3.4 Respiratory Disease Testing Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Respiratory Disease Testing Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Respiratory Disease Testing Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Respiratory Disease Testing category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Respiratory Disease Testing Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Respiratory Disease Testing Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Respiratory Disease Testing market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Respiratory Disease Testing Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Respiratory Disease Testing Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Respiratory Disease Testing Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Respiratory Disease Testing (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Respiratory Disease Testing Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Respiratory Disease Testing Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Respiratory Disease Testing Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Respiratory Disease Testing Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Respiratory Disease Testing Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Respiratory Disease Testing Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Respiratory Disease Testing Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Respiratory Disease Testing Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Respiratory Disease Testing Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
