
Russian pellets turn from Europe to Korea and local boilers
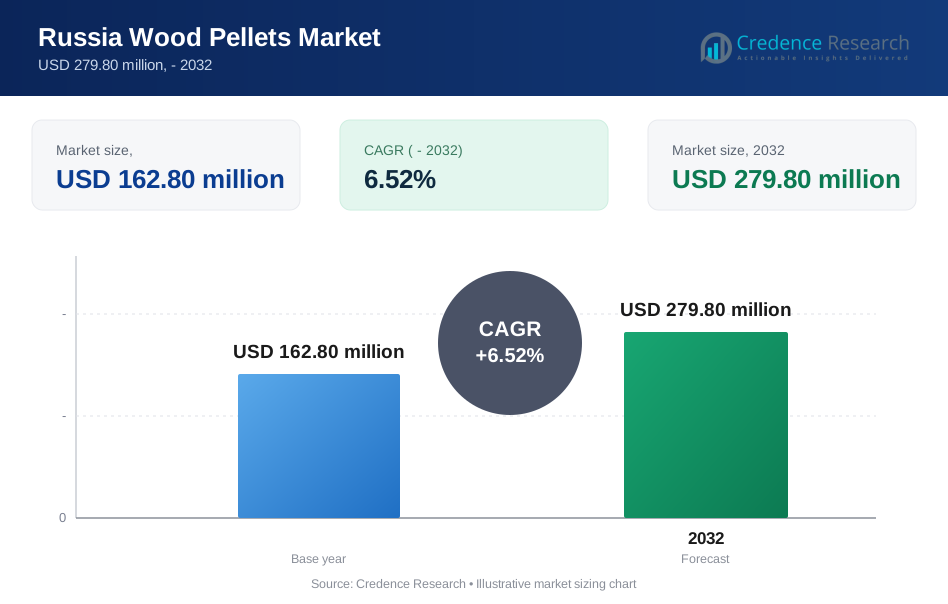
The Russia wood pellets market was valued at USD 171.6 million in 2025 and is projected to increase from USD 180.0 million in 2026 to USD 318.5 million by 2035, registering a CAGR of 6.38% during 2025–2035. Demand now rests on two outlets, as South Korean power plants co-fire industrial pellets with coal and Russian municipal boiler houses switch from coal and fuel oil to wood fuel. The Northwestern Federal District held the largest share, 38.0% in 2025, because its mills were built to ship to Europe through Baltic and White Sea ports. The defining commercial change is the European Union import ban on Russian wood products, applied to existing contracts from July 10, 2022, which pushed producers to Pacific routes and toward domestic heat. A possible opening of the Chinese market, where pellets are still classed as waste, is the largest swing factor.
Which Russian pellets and buyers fall inside the estimate?
The estimate counts wood pellets made in Russia from sawdust, shavings and other residues and sold either at home or abroad. It covers three grades, namely industrial pellets for power plants and large heat plants, premium residential pellets for household boilers and stoves, and standard and other pellets, including bark-rich and mixed-wood grades. Value is allocated to the federal district where the pellets are produced, so export plants count where they stand, not where buyers burn the fuel.
Fuel briquettes, wood chips, firewood and agricultural pellets made from straw, husks or peat are excluded, as are freight beyond the Russian port or border and pellet boilers themselves. About 2.46 million tons left Russia in 2021, the last full year before the ban, so the market starts from a much larger export base than it holds today.
Russia Wood Pellets Market Insights
- The Russia wood pellets market is projected to grow from USD 180.0 million in 2026 to USD 318.5 million by 2035, a 6.38% CAGR, as domestic heat replaces lost European demand.
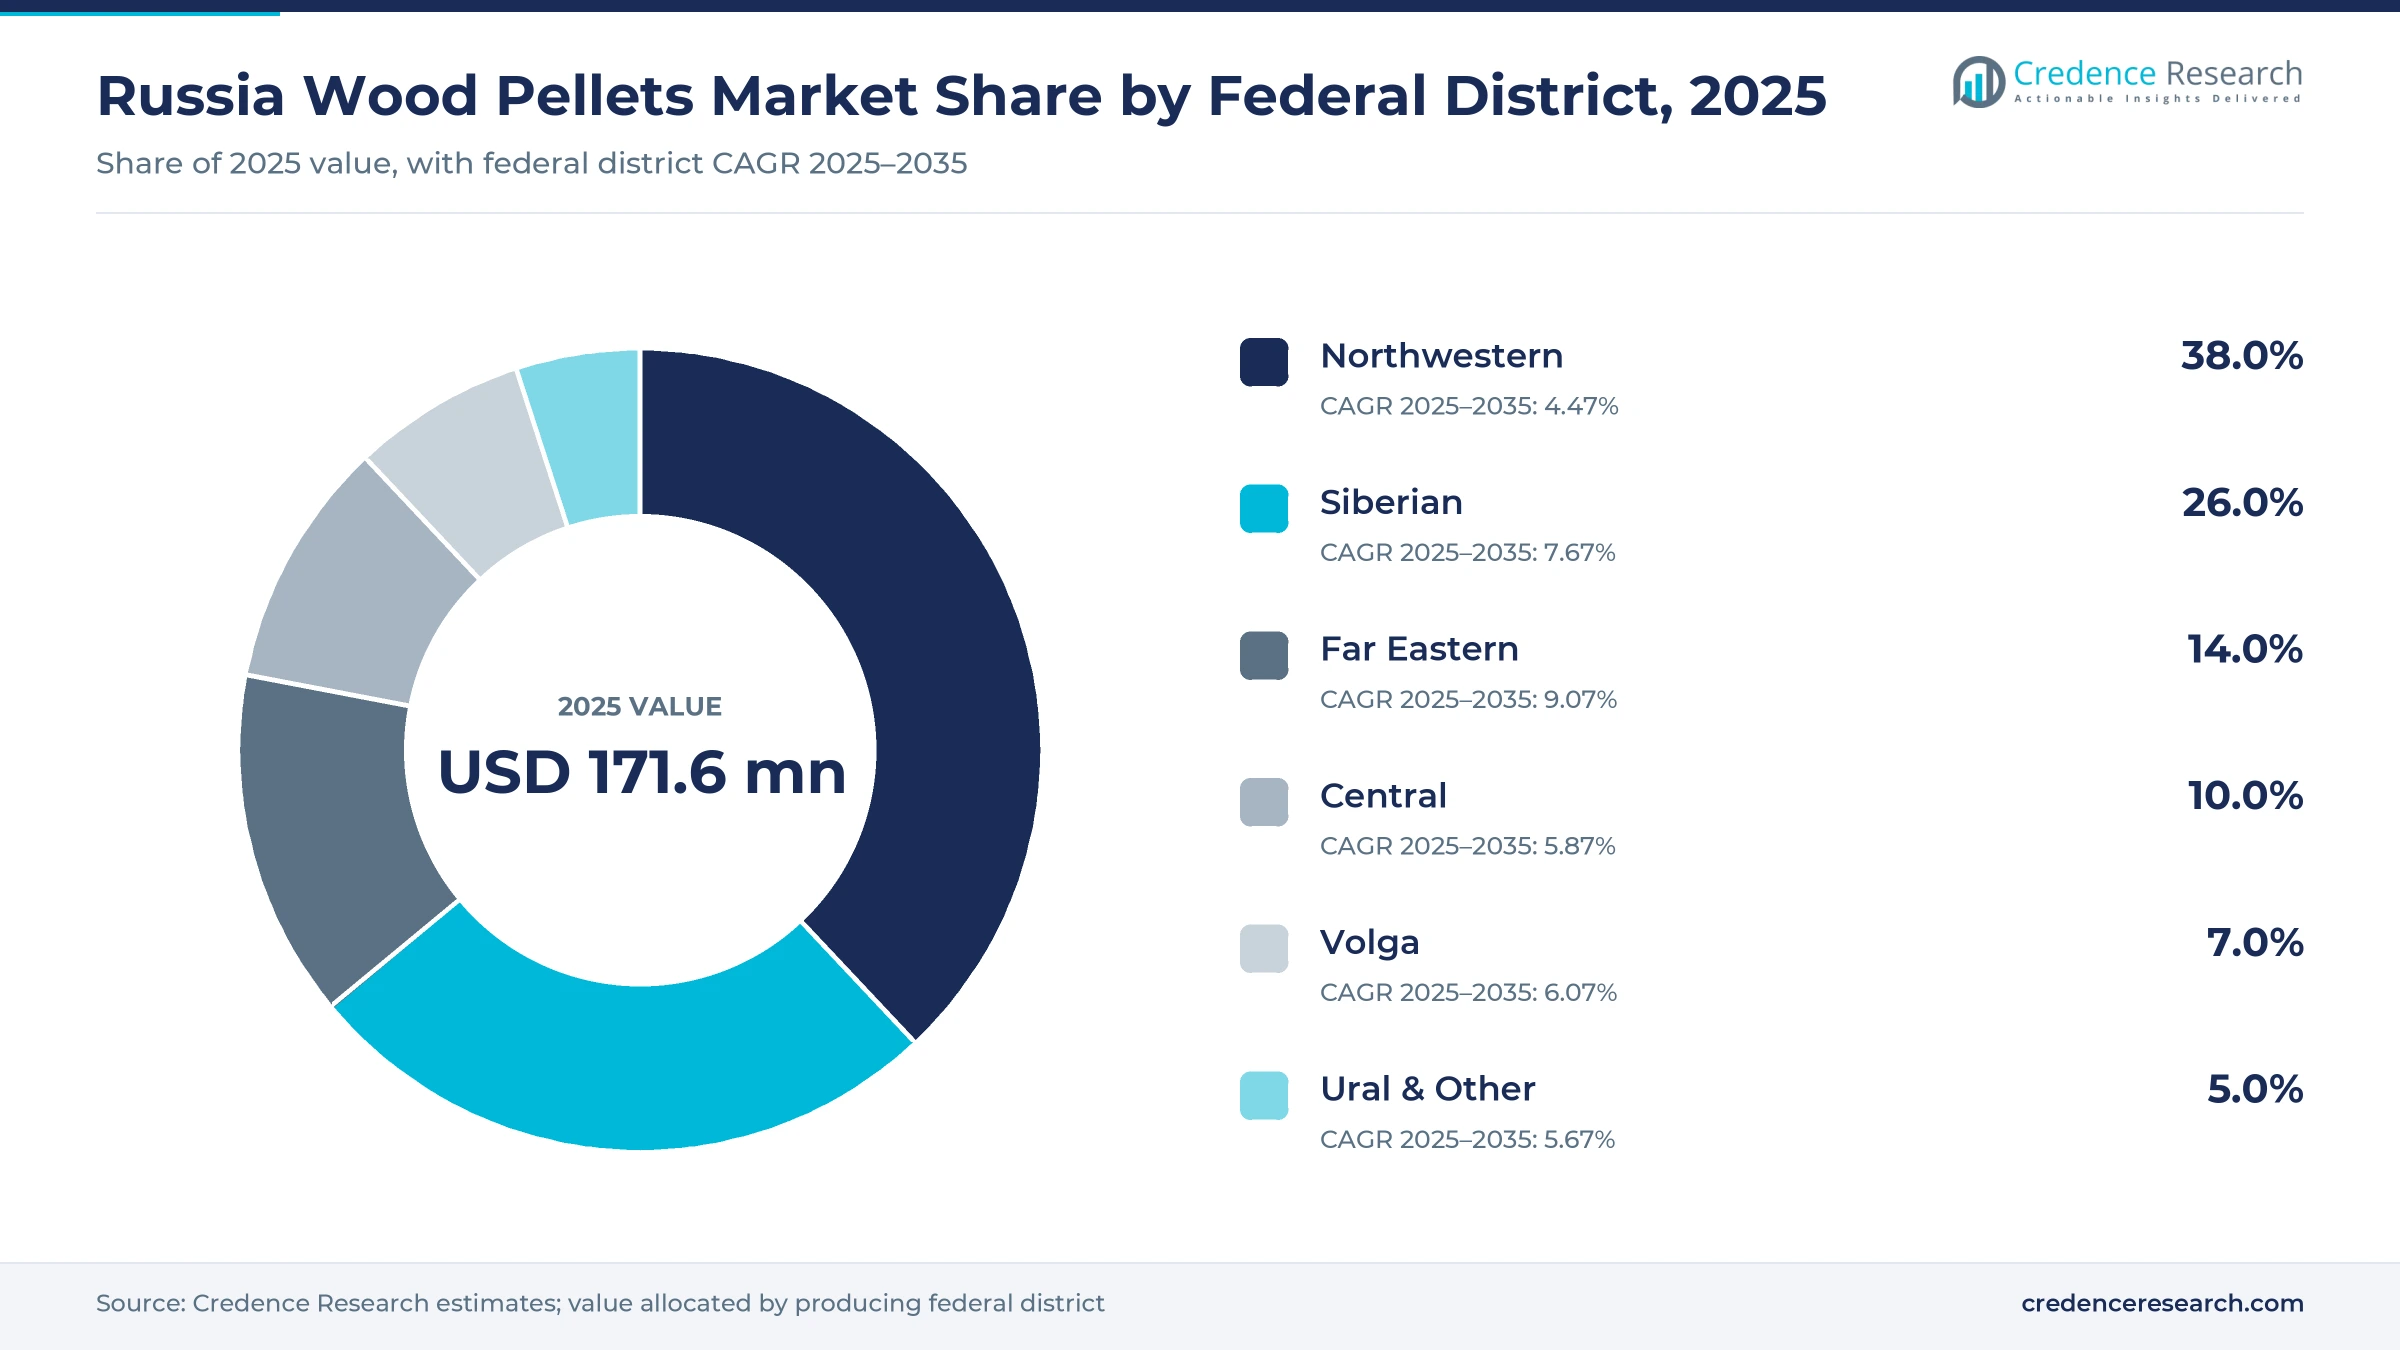
- The Northwestern Federal District held 38.0% of 2025 value, the largest share, because Arkhangelsk, Leningrad and Vologda mills were built for Baltic export.
- Industrial pellets accounted for 58.0% of 2025 value, the largest grade, because Korean power plants still buy bulk co-firing fuel from Russian export plants.
- In April 2025, the Industry and Trade Ministry proposed an RUB 80 billion program to convert coal and fuel oil boiler houses to pellets by about 2035.
- Segezha Group says it can make about 400,000 tons a year of pellets meeting Chinese standards, positioning sawmill groups for any Chinese market opening.
Industrial pellets lead while premium bags grow fastest
Bulk industrial pellets lead by grade while premium household bags grow fastest
Based on grade, the market is categorized into industrial pellets, premium residential pellets and standard and other pellets. Industrial pellets led with 58.0% of 2025 value, because most Russian capacity was built to supply European utilities and now ships the same bulk fuel to Korea. Premium residential pellets grow fastest at 7.81% a year, as low-ash bagged fuel for Russian and Central Asian households earns more per ton than export grades.
Co-firing plants lead end use while town boiler houses grow fastest
Based on end use, the market is categorized into power and CHP co-firing, municipal and district heating, residential heating and commercial and industrial heat. Power and CHP co-firing led with 46.0% of 2025 value, almost all of it shipped to South Korean plants. Municipal and district heating grows fastest at 10.95% a year, as forest regions convert coal and fuel oil boiler houses in remote towns, which favors producers located near those boilers.
| Segment Group | Leading Sub-segment | Share, 2025 | Fastest-growing Sub-segment | CAGR, 2025–2035 |
|---|---|---|---|---|
| By Grade | Industrial Pellets | 58.0% | Premium Residential Pellets | 7.81% |
| By End Use | Power & CHP Co-Firing | 46.0% | Municipal & District Heating | 10.95% |
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Korean co-firing and boiler plans drive pellet demand
The EU wood ban forced annual exports to find new buyers
Russia exported about 2.46 million tons of pellets in 2021, up 6.7%, mostly to European utilities. In April 2022, the EU adopted Council Regulation (EU) 2022/576, banning Russian wood products, with existing contracts allowed to run only until July 10, 2022. As a result, Northwestern producers lost their nearest, best-paying market overnight. The ban is the main reason the market is rebuilding from a lower base, and it pushes producers toward Asia and domestic boilers through the 2025–2035 forecast.
South Korean co-firing plants became the single large export outlet
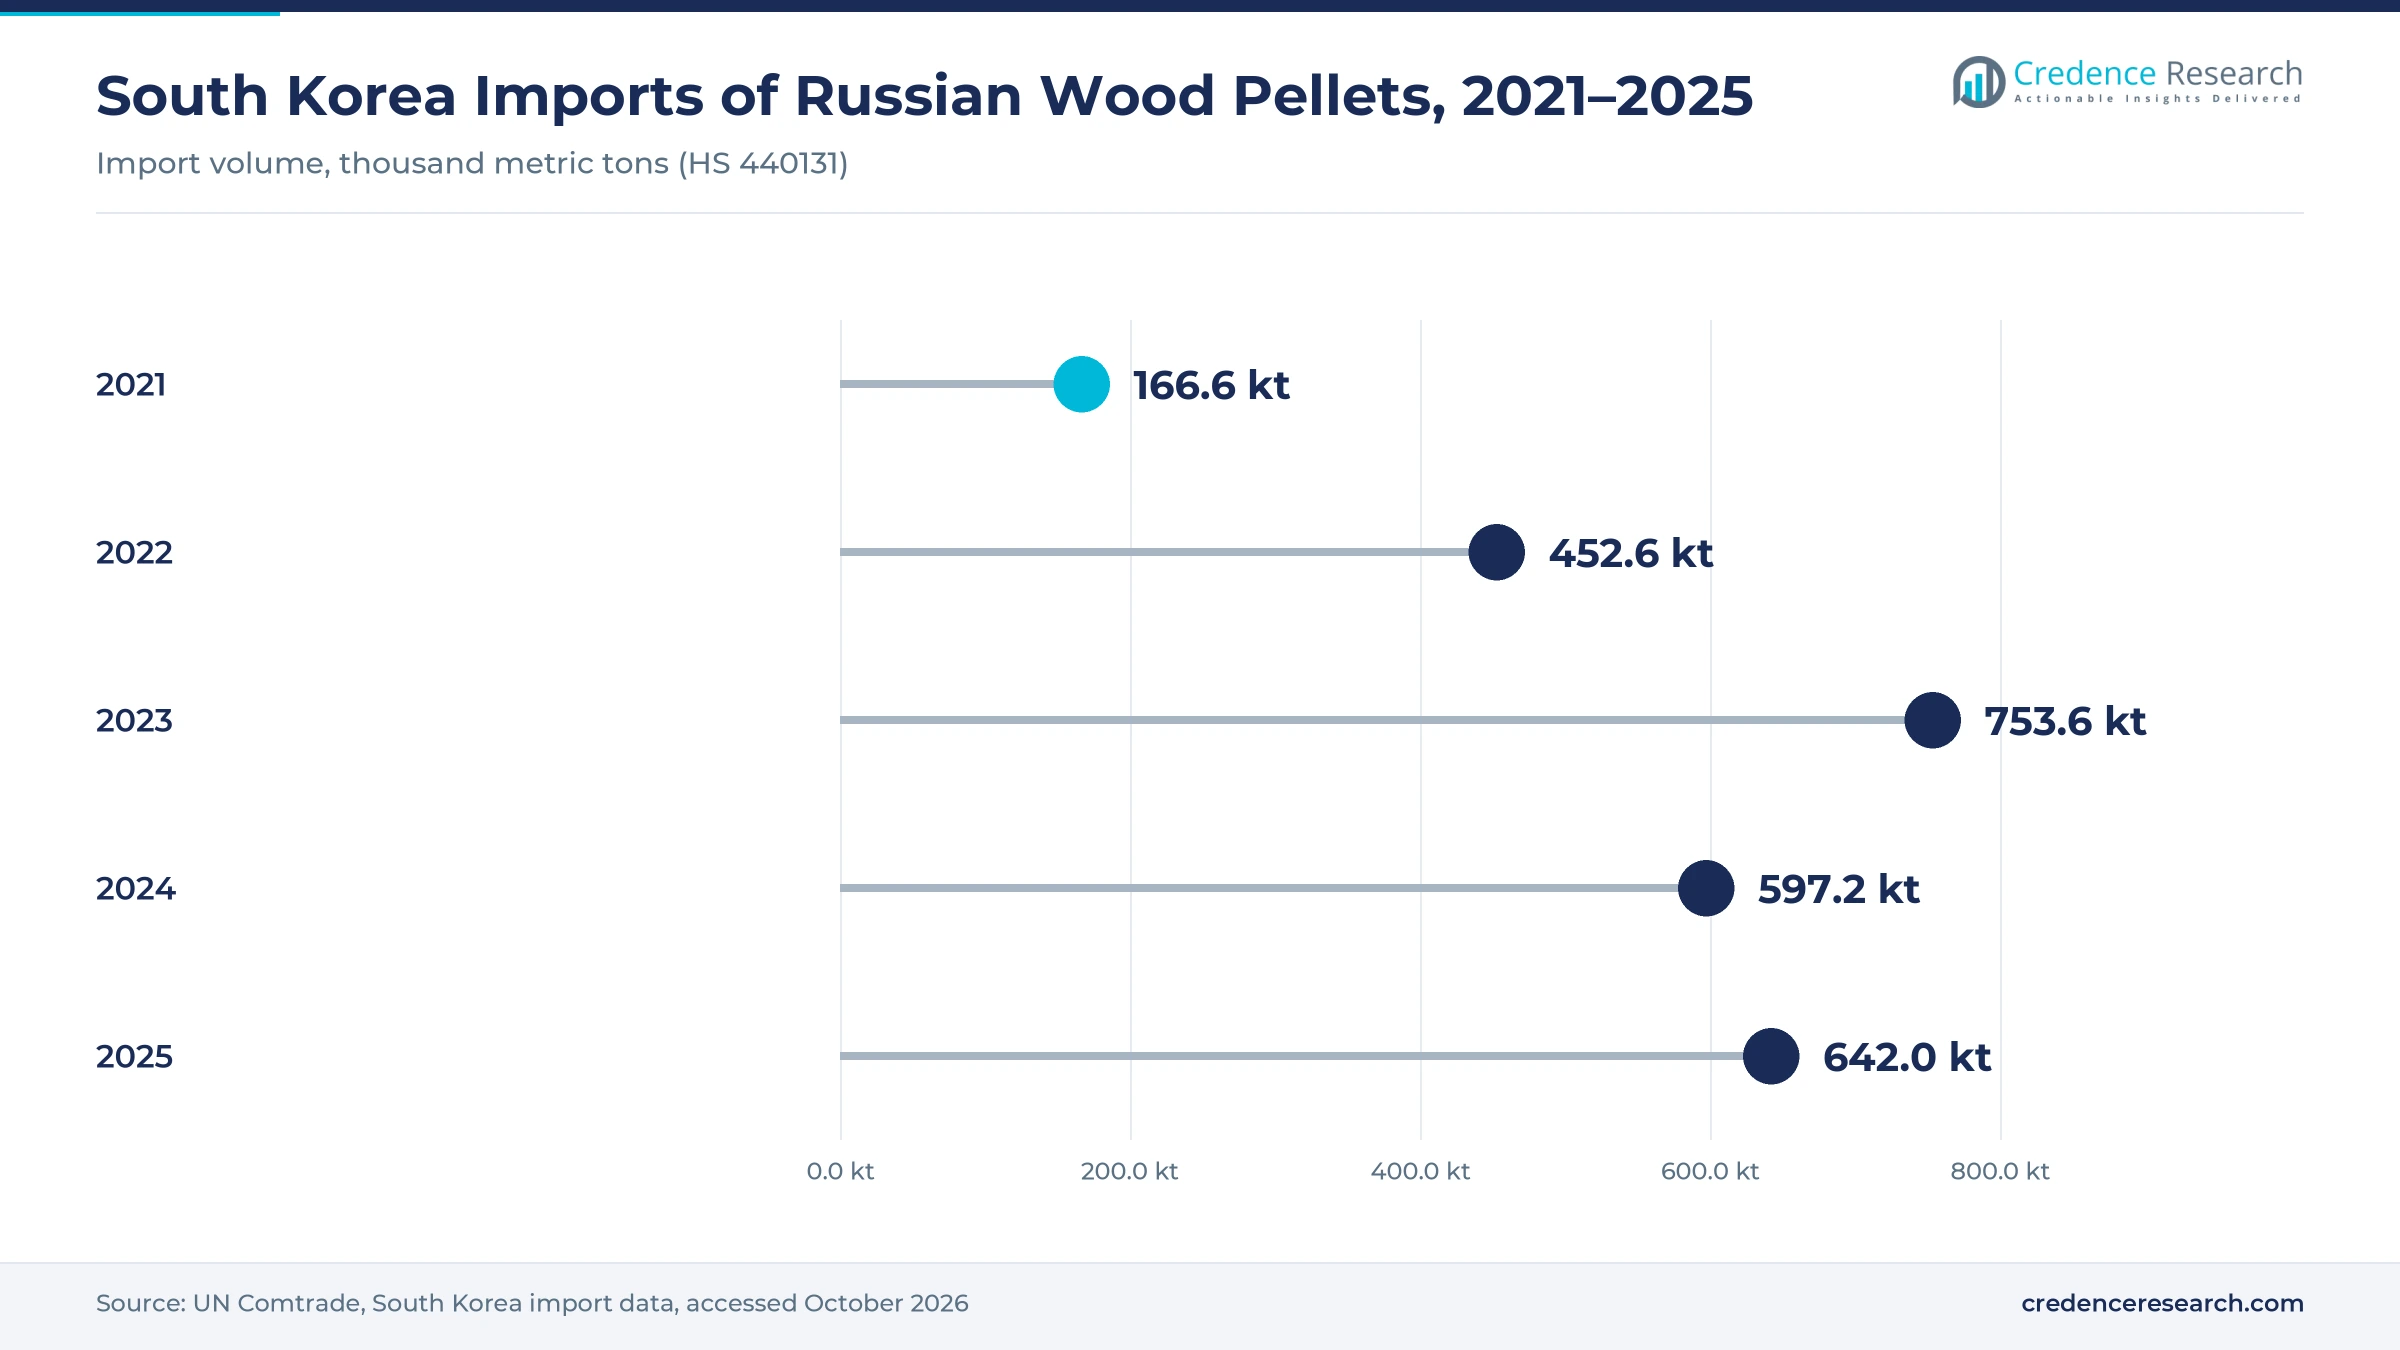
Before sanctions, Russia sold pellets to Europe, Japan and South Korea; it now exports essentially only to South Korea, according to the Industry and Trade Ministry. Korea-reported trade data on UN Comtrade show imports of Russian pellets rising from 166.6 thousand tons in 2021 to 753.6 thousand in 2023, then 642.0 thousand in 2025. That single outlet keeps industrial grades in demand in the short term, although Korean volumes have already slipped from their 2023 peak.
A boiler conversion proposal targets domestic heat
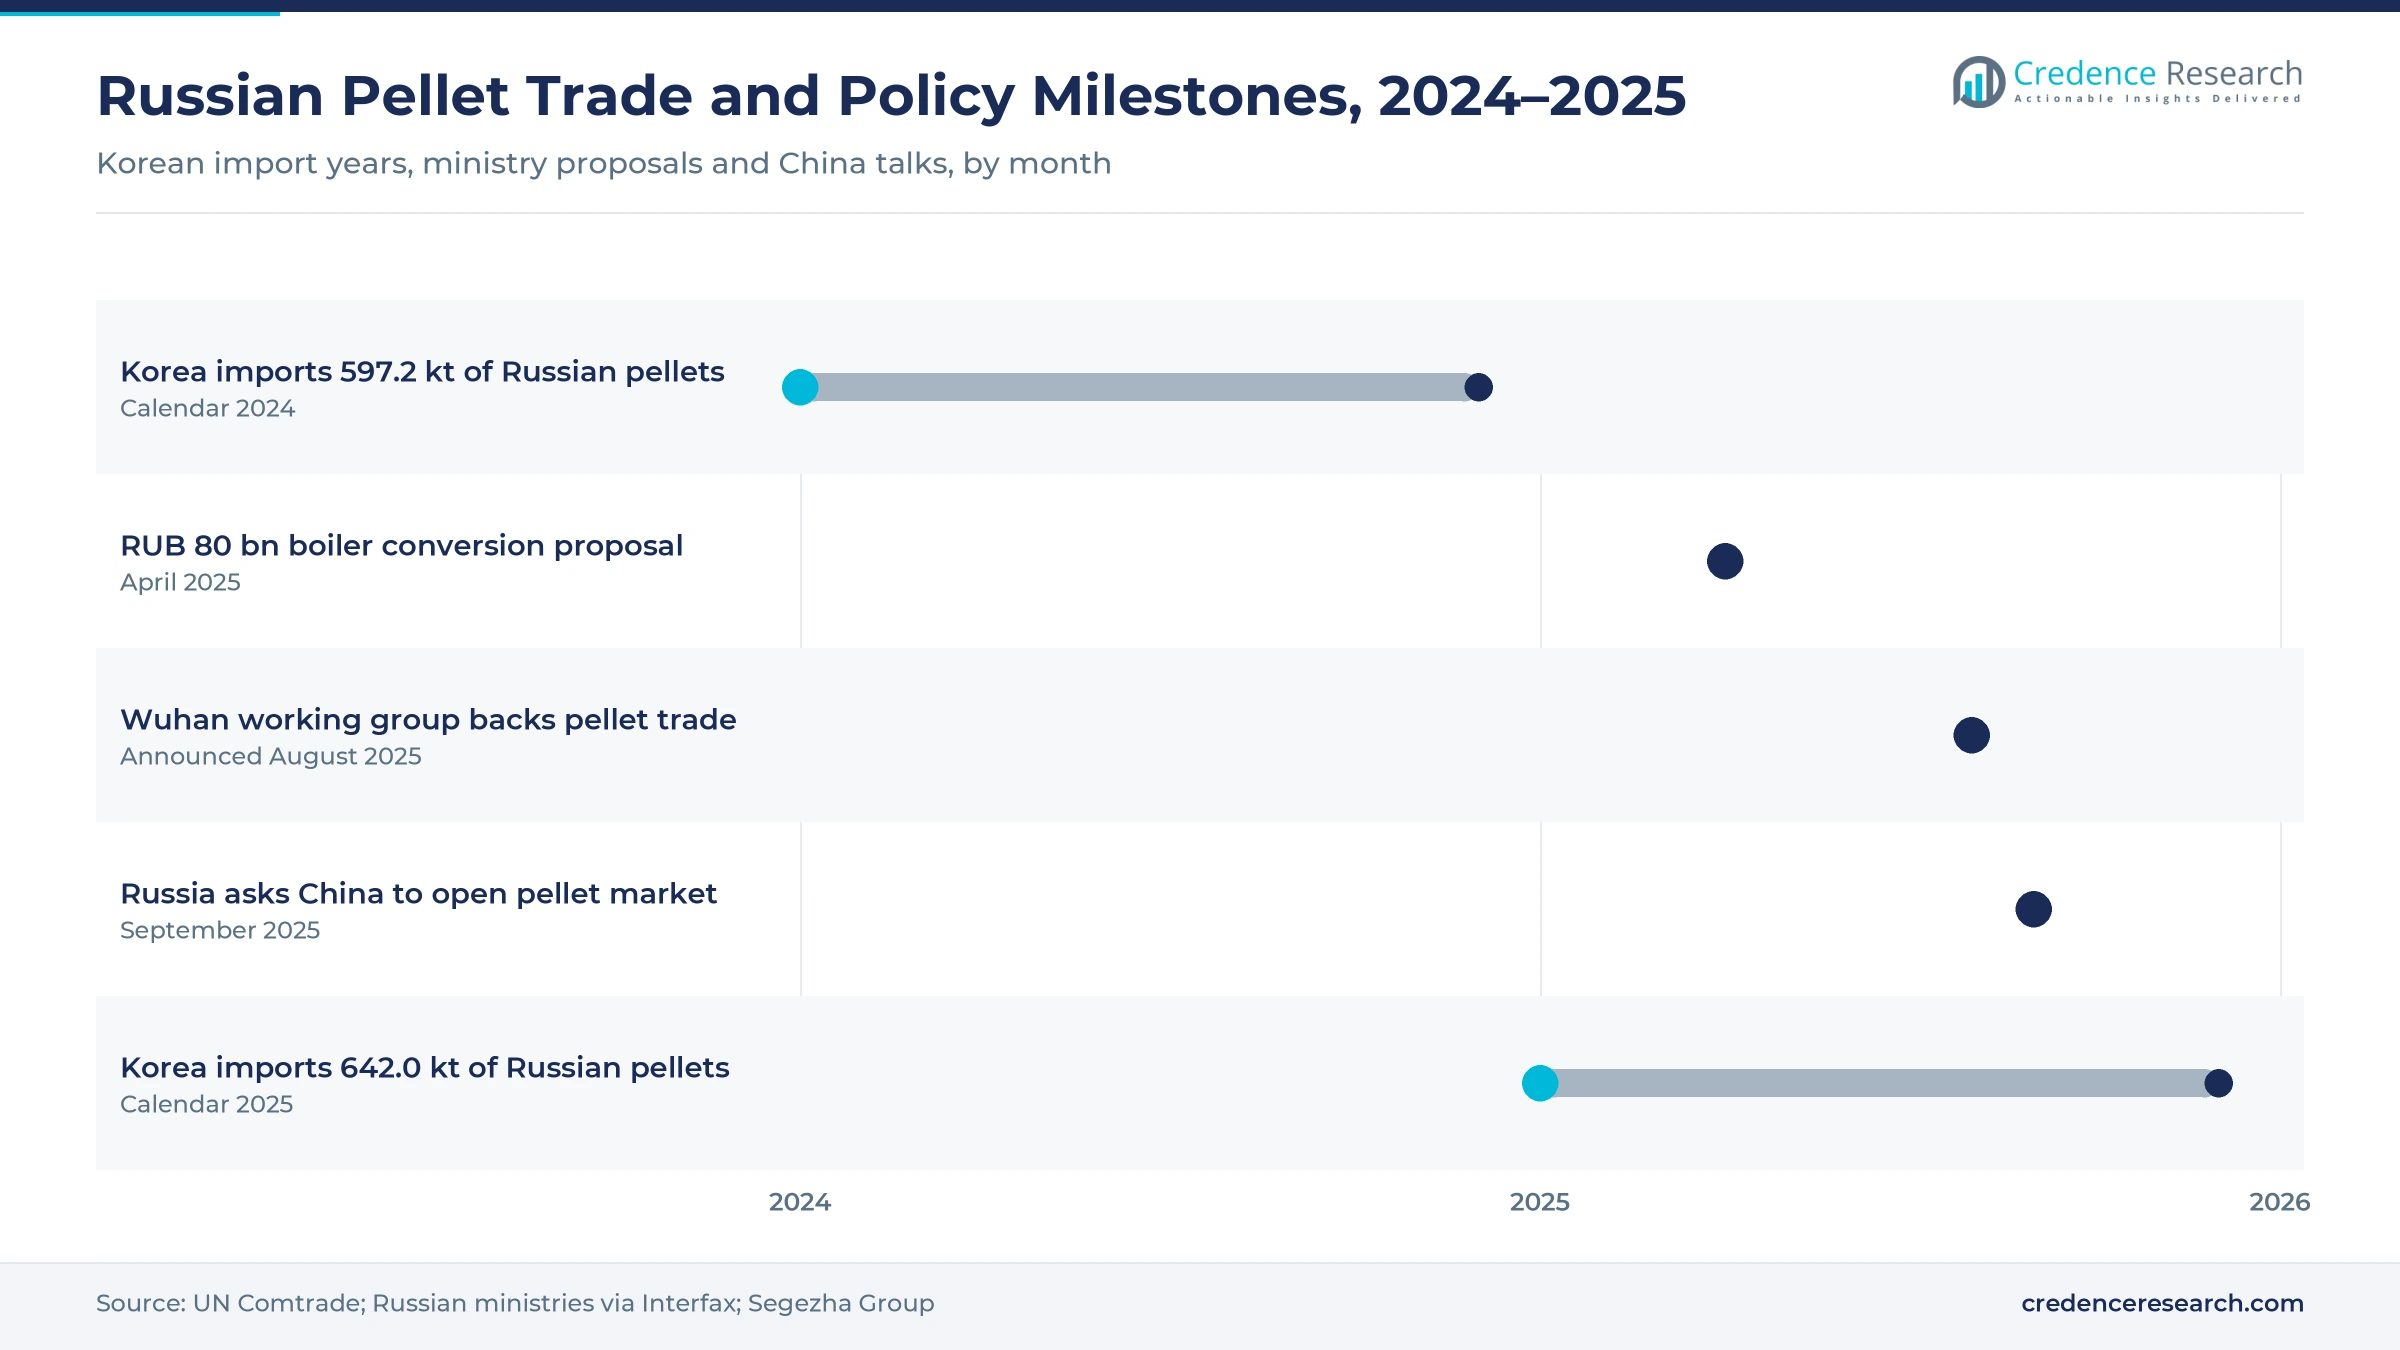
In April 2025, the Industry and Trade Ministry proposed converting fuel oil and coal boiler houses to pellets over about 10 years, at a cost of RUB 80 billion, to redirect the 1.5 million tons a year of lost exports, as reported by Interfax. The government had already allocated RUB 8 billion of treasury loans to 12 regions in 2023. Municipal and district heating is therefore the fastest-growing end use, a medium-term driver concentrated in the forest regions that host most mills.
Sawdust surpluses keep pellet feedstock cheap for sawmill groups
Russian sawmills produce large volumes of sawdust and shavings, and with fewer export outlets much of it piles up at mills. Output fell to about 1.9 million tons in 2023 from 2.6 million tons in 2022, according to WhatWood estimates, while roughly half of the 2023 output stayed in Russia. Cheap residues give sawmill groups a strong reason to keep pellet lines running at thin margins, which supports supply and domestic price competition through 2030.
Pacific routes, household grades and China redraw the map
Siberian and Far Eastern plants ship East by rail and Pacific ports
Producers in Siberia and the Far East now load pellets at Pacific ports for Korean buyers, while Baltic and White Sea plants built for Europe face long rail hauls. The Far Eastern Federal District is the fastest-growing producing district, because it sits closest to Korean, Japanese and potential Chinese demand. The trend shifts investment toward eastern mills and port terminals and away from the former Baltic export hubs.
Producers are moving toward premium bagged pellets for households
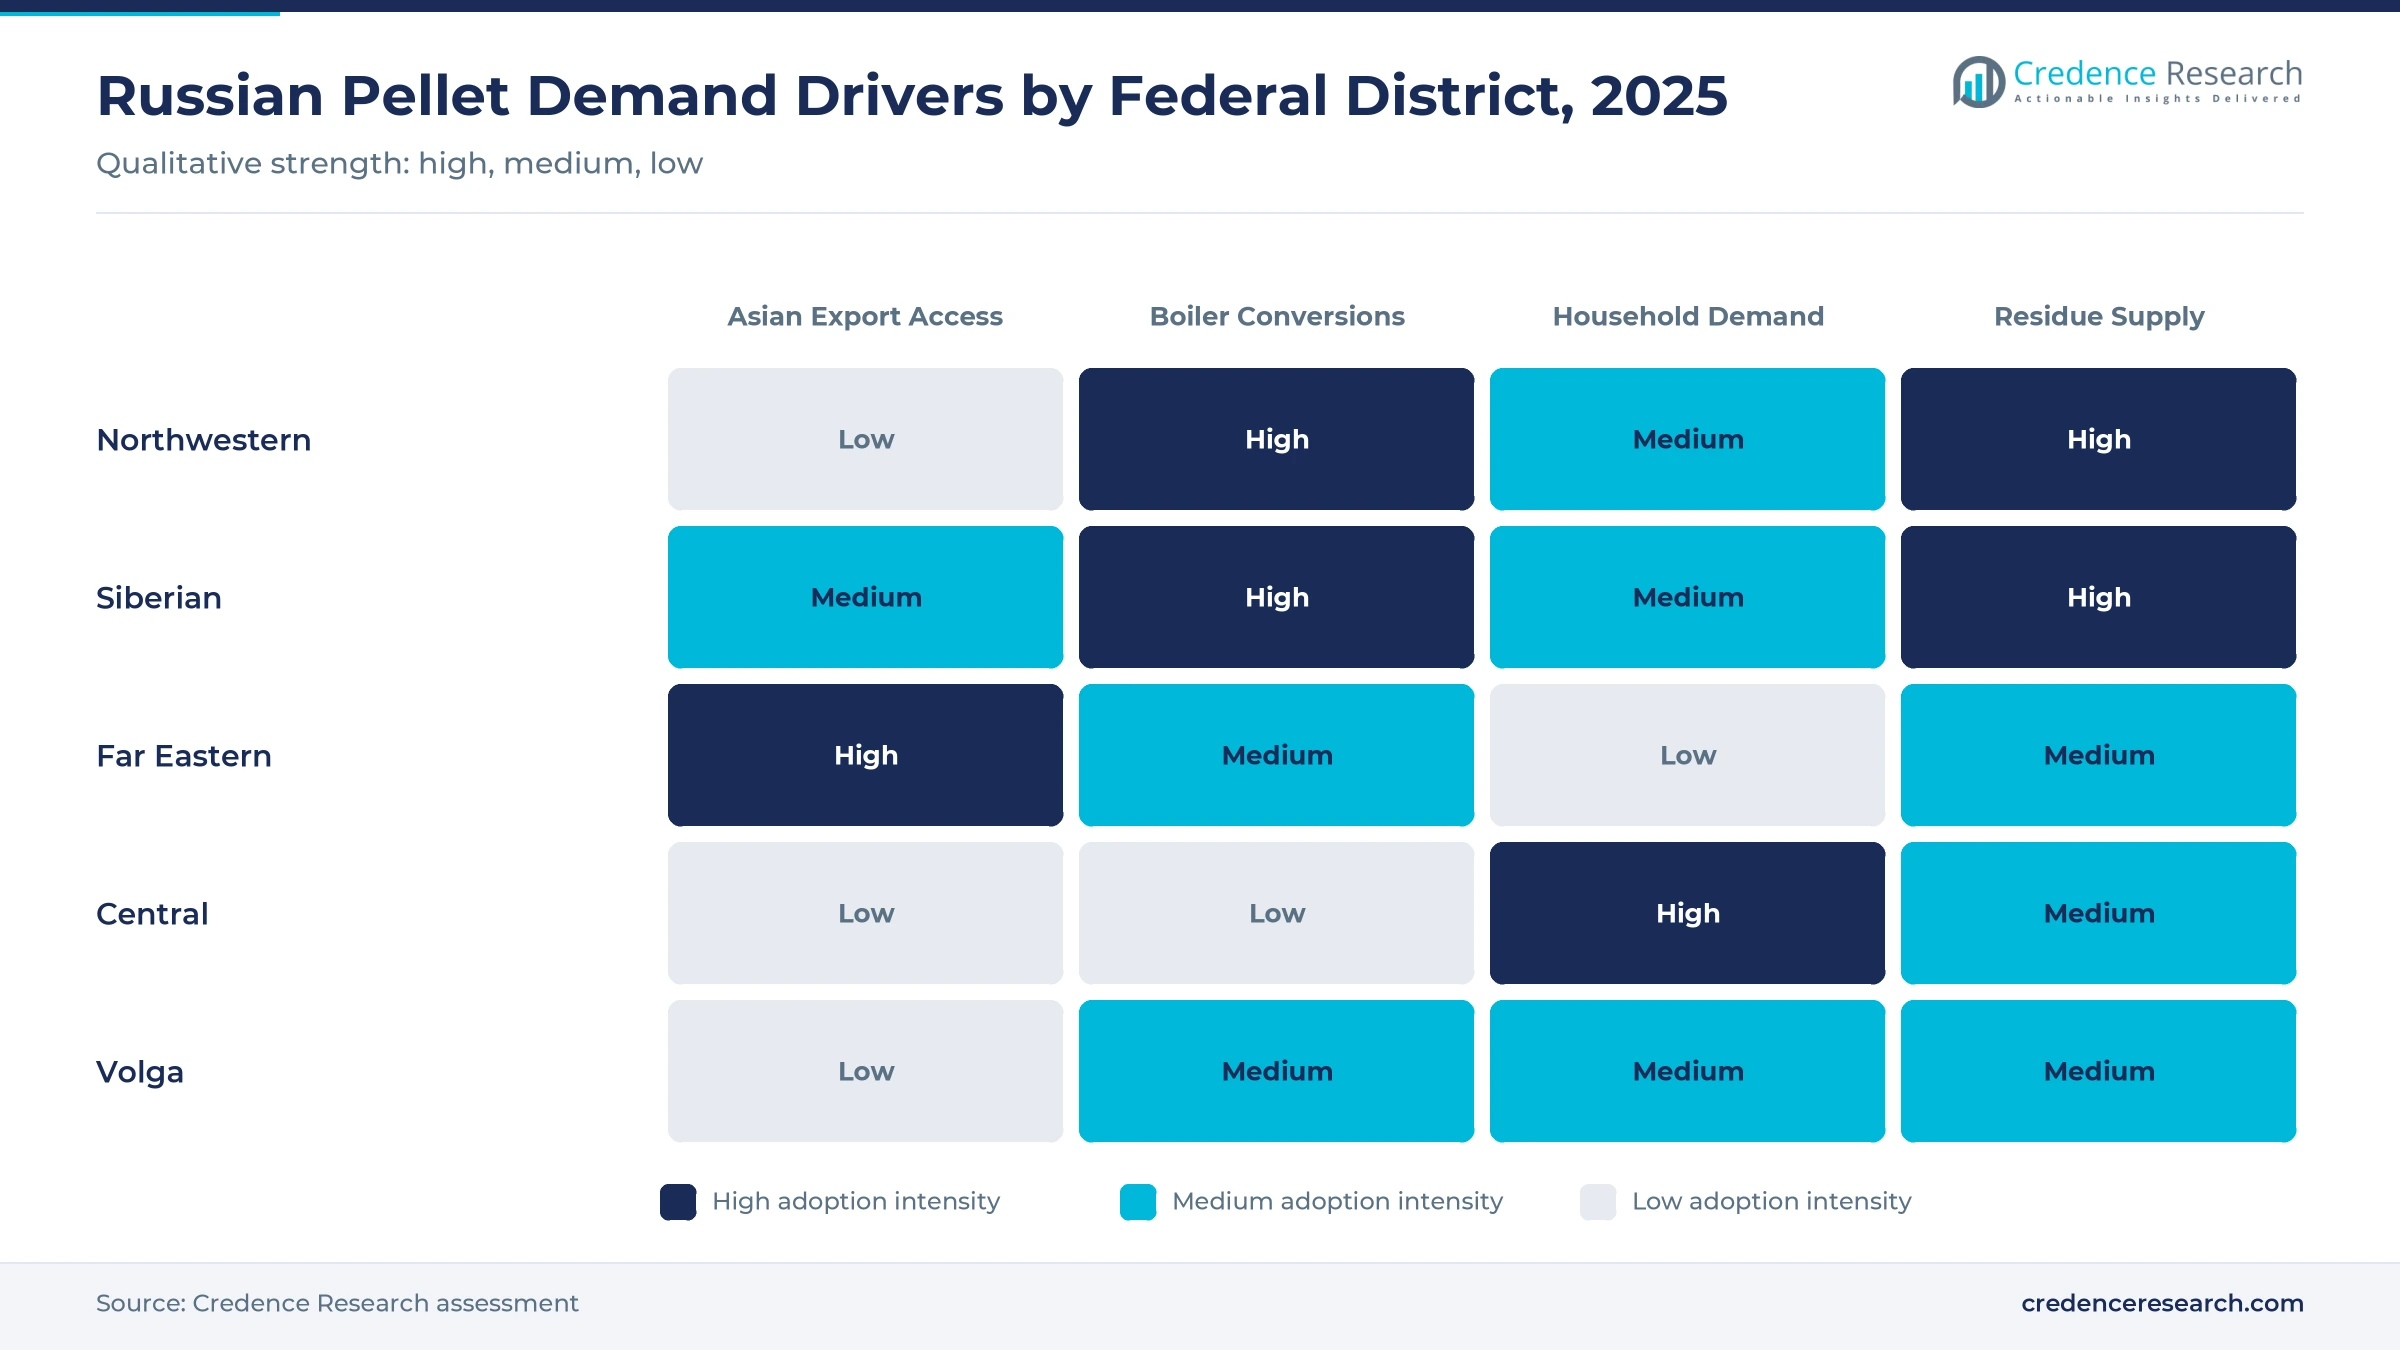
With industrial export prices under pressure, some producers now make premium low-ash pellets for Russian and Central Asian households that pay more per ton, which makes premium residential pellets the fastest-growing grade. The shift favors mills with drying, screening and bagging lines, and it lifts value faster than volume. The limit is cheap natural gas in much of European Russia, which caps household demand outside off-grid areas.
Municipal boiler conversions in remote forest towns open an opportunity
Boiler houses in Arkhangelsk Region, Komi and Krasnoyarsk Territory have already switched to biofuel, and the proposed conversion program would extend conversions through about 2035. Remote towns gain because pellets cost less to deliver than coal or fuel oil. Producers with nearby mills and boiler makers can win multi-year supply contracts, though the program still needs approval.
China could open an opportunity by reclassifying pellets as fuel
China still classifies wood pellets as waste, which blocks their import. In August 2025, Segezha Group announced that a Russian-Chinese working group meeting in Wuhan had agreed to facilitate pellet trade, and Segezha says it can produce about 400,000 tons a year meeting Chinese standards. Siberian producers would gain most from such an opening of the Chinese market. Far East Development Minister Alexey Chekunov has said Chinese buyers want pellets as a package with renewed roundwood exports.
Sanctions, rail hauls and cheap gas squeeze pellet margins
Sanctions on banks, insurers and shipping raise export costs
The EU ban removed the largest market, and sanctions on banks, insurers and shipping make the remaining exports slower and costlier to settle and insure. Exports in January to November 2023 reached about 848,000 tons, 50% below the same months of 2022. Large plants built for Europe run well below capacity, which raises unit costs. Producers can mitigate by using alternative payment routes and moving volume to domestic boiler contracts.
Long rail hauls eat into margins on a low-value bulk cargo
Pellets are a low-value bulk cargo, so rail from Siberia to Pacific ports and sea freight to Korea take a large share of the delivered price. Northwestern producers, the slowest-growing group, face the longest routes to Asian buyers. The consequence is thin margins and idle lines at western mills. Mitigation comes from long-term rail contracts, larger vessels and selling more volume to boiler houses within 1 or two regions of the mill.
Cheap natural gas limits household pellet demand
Natural gas is cheap across much of European Russia, so pellets compete mainly where gas pipelines do not reach. That keeps household demand small in the Central and Volga districts and slows the move to premium grades. Producers of bagged pellets are most affected, and they mitigate by targeting off-grid villages, dachas and Central Asian buyers, and by pairing pellet supply with boiler installation for small commercial users such as farms, schools and greenhouses.
Fading Korean co-firing support threatens industrial volume
South Korea is cutting support for co-firing biomass in coal plants, so Russian producers face a shrinking outlet for industrial pellets unless China opens. Korean imports of Russian pellets already fell from 753.6 thousand tons in 2023 to 597.2 thousand in 2024. The risk falls on export plants that sell 1 grade to 1 country. They mitigate by adding premium lines, chasing dedicated biomass power stations and preparing for Chinese certification.
Northwestern mills lose ground to plants near the Pacific
| Federal District | Share, 2025 | CAGR, 2025–2035 |
|---|---|---|
| Northwestern | 38.0% | 4.47% |
| Siberian | 26.0% | 7.67% |
| Far Eastern | 14.0% | 9.07% |
| Central | 10.0% | 5.87% |
| Volga | 7.0% | 6.07% |
| Ural & Other | 5.0% | 5.67% |
Northwestern Federal District is the former Baltic export base
The Northwestern Federal District held 38.0% of 2025 value and grows at 4.47% a year, the slowest of the six districts. Plants in Arkhangelsk, Leningrad, Vologda and Karelia were built to ship to Europe and now depend on long hauls to Asia and on domestic boilers. Arkhangelsk Region and Komi already run converted biofuel boiler houses, which gives local producers a home outlet. Vyborgskaya Cellulose, Ustyansky LPK and Lesozavod 25 sit in this district.
Siberian Federal District mills in Krasnoyarsk and Irkutsk turn East
The Siberian Federal District held 26.0% of 2025 value and grows at 7.67% a year. Krasnoyarsk and Irkutsk sawmill groups, including Novoyeniseysky LHK and Segezha's Lesosibirsk operations, ship industrial pellets by rail to Pacific ports for Korean utilities, and Krasnoyarsk Territory has also converted boiler houses to biofuel. A Chinese market opening would favor Siberian producers because they can reach northern China by rail without a sea leg, while rail capacity to the Pacific limits export growth today.
Far Eastern Federal District is the fastest-growing gateway to Asian buyers
The Far Eastern Federal District held 14.0% of 2025 value and is the fastest-growing district at 9.07% a year. Mills in Khabarovsk and Primorye sit closest to Korean, Japanese and potential Chinese buyers, which cuts freight costs on a low-value cargo. Growth comes from new export contracts and from boiler houses in remote settlements that rely on delivered coal and fuel oil. Limited local residue supply caps how fast capacity can expand.
Central, Volga and Ural districts supply household fuel near large cities
The Central Federal District held 10.0% of 2025 value and grows at 5.87% a year, serving households and small businesses near Moscow. The Volga Federal District held 7.0% and grows at 6.07% a year. The Ural and other districts held 5.0% and grow at 5.67% a year, and cheap gas limits demand in all three districts.
An EU ban, a boiler proposal and pellet talks with Beijing
| Development | Status and market relevance |
|---|---|
| In September 2025, Economic Development Minister Maxim Reshetnikov asked China to open its market to Russian fuel pellets, which China classifies as waste. | Requested. China is the largest potential new outlet. |
| In August 2025, Segezha Group announced that the Russian-Chinese forest working group had agreed in Wuhan to facilitate trade in wood pellets. | Agreed in principle. No regular shipments yet. |
| In April 2025, the Industry and Trade Ministry proposed an RUB 80 billion program to convert coal and fuel oil boiler houses to pellets by about 2035. | Proposed, not yet approved. Would make municipal heat the main domestic outlet. |
| In April 2022, the EU adopted Regulation (EU) 2022/576, banning Russian wood products, with existing contracts ending on July 10, 2022. | In force. Removed Europe, the main buyer of Russian pellets. |
Torrefaction, boiler automation and quality grading
- Torrefaction produces torrefied, or black, pellets that carry more energy per ton and resist water, cutting freight cost per unit of heat on long routes to Asian buyers.
- Boiler automation with automatic pellet boilers, feed screws and remote monitoring makes conversions practical for small towns that lack round-the-clock stokers.
- Quality grading into low-ash premium grades with consistent moisture control lets producers sell to households and meet stricter buyer specifications abroad.
- Residue logistics improve when drying and densifying sawdust at the mill gate turns a waste stream into a tradable fuel and lowers transport cost for remote producers.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Sawmill groups with free residues outlast export plants
Russian pellet supply splits into three groups, and integrated timber and paper groups, led by Segezha Group, turn their own sawdust into pellets and can run lines at thin margins because residues cost them little. Large export-focused plants, such as Vyborgskaya Cellulose in Leningrad Region, were built for European utilities and now carry the most idle capacity. Sawmill companies in Arkhangelsk Region and Krasnoyarsk Territory, including Ustyansky LPK, Lesozavod 25 and Novoyeniseysky LHK, sell to Korea and to local boilers, while many small regional producers sell bagged pellets to households. Export buyers want long-term supply, consistent quality and reliable shipping, so plants with port access win utility contracts, while domestic buyers want local supply and low prices. No producer publishes pellet sales on a comparable basis, so no share ranking is given.
Leading Russian pellet producers and their positions
| Company | Type | Role in the market |
|---|---|---|
| Segezha Group | Integrated timber group | Pellet lines at Northwestern and Siberian sawmills; says about 400,000 tons a year meet Chinese standards |
| Vyborgskaya Cellulose | Export pellet plant | Large Leningrad Region plant built for Europe; current output not confirmed |
| Ustyansky LPK | Sawmill group | Arkhangelsk Region pellets from sawmill residues; export volume not confirmed |
| Lesozavod 25 | Sawmill group | Arkhangelsk Region pellets from sawmill residues; export volume not confirmed |
| Novoyeniseysky LHK | Sawmill group | Krasnoyarsk Territory producer supplying Asian buyers; current volume not confirmed |
Pellets become a domestic heat fuel with an export option
Credence Research's view is that the Russian pellet business is turning from a European export trade into a domestic heat fuel with an Asian export option. Municipal boiler conversions offer the steadiest new demand, while China is the largest upside and the least certain. Sawmill groups with free residues, Pacific access and premium bagging lines are best placed. The main strategic risk is a double squeeze if Korean co-firing demand fades before China opens. Investors should watch approval and funding of the boiler conversion program and Chinese reclassification of pellets.
Plant capacity, trade data and boiler demand
The report uses 2025 as the base year and forecasts to 2035, with CAGR calculated over 2025–2035. Market values come from Credence Research's market model, built from pellet plant capacity and residue supply, export outlets, domestic boiler and household demand, and pellet prices by grade; grade, end-use and district splits are Credence Research estimates. Supporting evidence comes from government statements reported by news agencies, the EU regulation, UN Comtrade trade data and trade press production estimates. However, Russian official trade data are limited for the years after 2021.
Town boilers and Pacific exports decide the recovery
Through 2035, Russian pellet demand will tilt from a single Korean export outlet toward domestic municipal heat, household bags and, if it opens, China. Value will rise faster than volume as premium grades gain share. Siberian and Far Eastern producers will gain share from the Northwest because they sit closer to Asian buyers. Investment will flow to boiler conversions, bagging lines and eastern logistics. The pace depends on state funding for boilers, Korean biomass policy and whether Beijing reclassifies pellets as fuel.
Frequently Asked Questions
What was the size of the Russia wood pellets market in 2025?
What is the forecast value and CAGR of the Russia wood pellets market?
Why did Russian pellet exports fall?
Which federal district produces the most Russian wood pellets?
Which pellet grade leads the Russian market?
Who are the leading Russian wood pellet producers?
How could China change the Russia wood pellets market?
What role does domestic heating play in Russian pellet demand?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Grade
- 1.2.1 Industrial Pellets
- 1.2.2 Premium Residential Pellets
- 1.2.3 Standard & Other Pellets
- 1.3 By End Use
- 1.3.1 Power & CHP Co-Firing
- 1.3.2 Municipal & District Heating
- 1.3.3 Residential Heating
- 1.3.4 Commercial & Industrial Heat
- 1.4 By Federal District
- 1.4.1 Northwestern
- 1.4.2 Siberian
- 1.4.3 Far Eastern
- 1.4.4 Central
- 1.4.5 Volga
- 1.4.6 Ural & Other
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 171.6 million → 2035: USD 318.5 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Historical Period: 2018-2025
- 2.6.2 Base Year: 2025
- 2.6.3 Forecast Period: 2025-2035
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2035
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Russia Wood Pellets Market Trends and Developments
- 4.1 Historical Industry Development, 2018-2025
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Russia Wood Pellets Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis, 2018-2025
- 5.2 Demand Forecast, 2025-2035
- 5.3 Production and Output Trend, 2018-2025
- 5.4 Production and Output Forecast, 2025-2035
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Russia Wood Pellets Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends, 2018-2025
- 6.3 Pricing Outlook, 2025-2035
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Russia Wood Pellets Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Russia Wood Pellets Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Russia Wood Pellets Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Russia Wood Pellets Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Russia Wood Pellets Market Outlook, 2025-2035
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 171.6 million → 2035: USD 318.5 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size, 2018-2025
- 11.1.4 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2035
- 11.2.1 Revenue Forecast to 2035
- 11.2.2 Volume Forecast to 2035
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Russia Wood Pellets Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Grade - Market Size and Forecast, 2025-2035
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size, 2018-2025
- 12.3.3 Revenue Forecast, 2025-2035
- 12.3.4 Volume Forecast, 2025-2035
- 12.3.5 Base-Year Market Share, 2025
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Industrial Pellets
- 12.3.7.2 Premium Residential Pellets
- 12.3.7.3 Standard & Other Pellets
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By End Use - Market Size and Forecast, 2025-2035
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size, 2018-2025
- 12.4.3 Revenue Forecast, 2025-2035
- 12.4.4 Volume Forecast, 2025-2035
- 12.4.5 Base-Year Market Share, 2025
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Power & CHP Co-Firing
- 12.4.7.2 Municipal & District Heating
- 12.4.7.3 Residential Heating
- 12.4.7.4 Commercial & Industrial Heat
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Federal District - Market Size and Forecast, 2025-2035
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size, 2018-2025
- 12.5.3 Revenue Forecast, 2025-2035
- 12.5.4 Volume Forecast, 2025-2035
- 12.5.5 Base-Year Market Share, 2025
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Northwestern
- 12.5.7.2 Siberian
- 12.5.7.3 Far Eastern
- 12.5.7.4 Central
- 12.5.7.5 Volga
- 12.5.7.6 Ural & Other
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Russia Wood Pellets End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Russia Wood Pellets Geographic Market Outlook, 2025-2035
- 14.1 Domestic Market Distribution and Demand Clusters
- 14.2 State- or Province-Wise Market Size and Forecast, 2025-2035
- 14.3 City and Metropolitan Market Outlook
- 14.4 Industrial, Manufacturing and Commercial Clusters
- 14.5 Geographic Concentration of Key End Users
- 14.6 Local Pricing and Purchasing Differences
- 14.7 Domestic Production Facilities and Capacity Map
- 14.8 Local Infrastructure and Project Pipeline
- 14.9 State-Level Policy and Incentive Differences
- 14.10 Subnational Investment Hotspots and Opportunities
- 14.11 Distribution and Logistics Networks
- 14.12 Domestic Competitive Footprint
Chapter 15 Russia Wood Pellets Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2025-2035
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Russia Wood Pellets Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2025
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2025-2035
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Segezha Group
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Vyborgskaya Cellulose
- 18.4 Ustyansky LPK
- 18.5 Lesozavod 25
- 18.6 Novoyeniseysky LHK
- 18.7 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

