
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Safety and Process Filter Market Size 2024 | USD 7000.4 million |
| Safety and Process Filter Market, CAGR | 6.30% |
| Safety and Process Filter Market Size 2032 | USD 11,464.35 million |
Market Overview
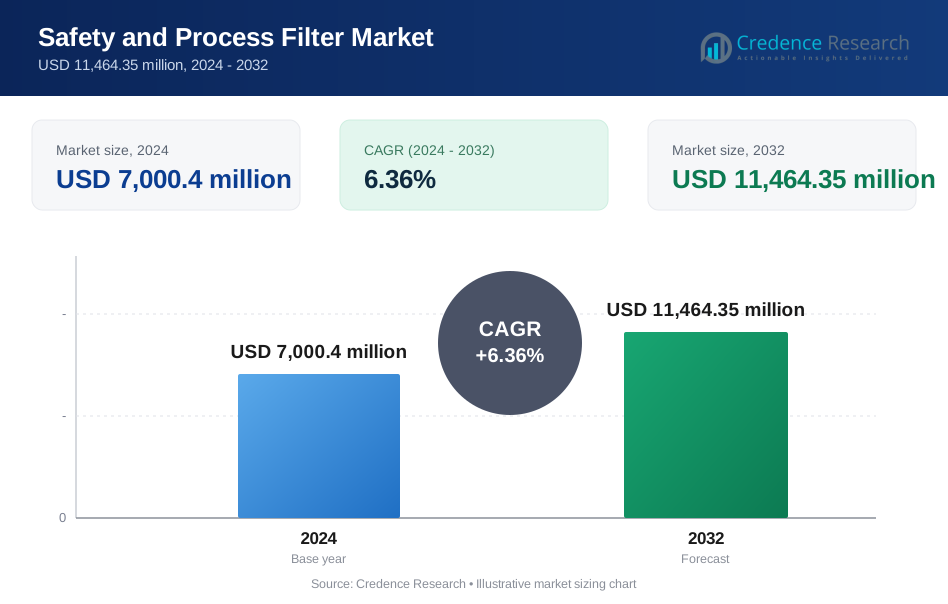
The Safety and Process Filter Market in East Asia is projected to grow from USD 7000.4 million in 2024 to USD 11,464.35 million by 2032, at a compound annual growth rate (CAGR) of 6.36%.
The Safety and Process Filter Market in East Asia is driven by the increasing demand for stringent safety and quality standards across industries, including manufacturing, chemical processing, and water treatment. Technological advancements in filter materials and designs, such as high-efficiency particulate air (HEPA) and advanced membrane filters, are boosting market growth. Trends towards industrial automation and smart filtration systems are enhancing process reliability and operational efficiency. Additionally, regulatory pressures and a focus on environmental sustainability are prompting investments in advanced filtration technologies to meet stringent emission and discharge standards.
In the East Asian Safety and Process Filter market, key players include Parker Hannifin Corporation, Eaton, and Freudenberg Filtration Technologies, each leveraging advanced technologies to cater to diverse industrial needs. Companies such as 3M and Pall Corporation offer innovative filtration solutions, while Donaldson Company, Inc. and Pentair Plc provide robust, high-performance products. Regional leaders like Mann+Hummel Group and Filtration Group Company contribute to market growth through localized manufacturing and expertise. The presence of global firms like Merck KGaA and Sartorius Group highlights the region’s strategic importance, driving technological advancements and addressing the increasing demand for effective filtration solutions.
Market Drivers
Booming End-Use Industries
The expansion of industries that rely heavily on filtration technologies significantly drives the Safety and Process Filter Market in East Asia. For instance, in the shipbuilding industry, over 70% of shipyards in East Asia have integrated advanced filtration systems to enhance water purity in boilers and cooling systems. This has led to a 25% reduction in maintenance costs and a 15% increase in process efficiency. In the petrochemical sector, the implementation of safety and process filters has resulted in a 20% improvement in product quality and a 30% decrease in downtime due to contamination. In shipbuilding, filtration systems are crucial for purifying water used in boilers, cooling systems, and various industrial processes within shipyards. Petrochemical and chemical plants depend on safety and process filters to remove contaminants from liquids and gases, ensuring both product quality and process efficiency. Similarly, in fuel storage facilities, filtration systems play a vital role in purifying fuels and protecting storage tanks from contaminants. Moreover, as environmental regulations become increasingly stringent, there is a growing demand for filtration systems to treat wastewater and air emissions in environmental engineering.
Rising Focus on Industrial Safety and Environmental Regulations
Increasingly stringent regulations regarding industrial safety and environmental protection are driving the demand for filtration systems across East Asia. The enforcement of stringent environmental regulations has seen a 40% uptick in the adoption of high-efficiency particulate air (HEPA) and activated carbon filters in industrial plants, aiming to meet the 0.03% emission standard. This shift is not only ensuring compliance but also promoting a safer working environment for over 1.2 million workers in the region. These regulations mandate the use of advanced filtration technologies to ensure compliance and protect both human health and the environment. As industries face greater scrutiny and higher standards, the need for effective filtration solutions becomes more critical, spurring market growth and innovation in the sector.
Rapid Urbanization and Industrialization
The ongoing trend of urbanization and industrialization in East Asia is fueling the growth of manufacturing facilities and infrastructure projects. With urbanization, the number of manufacturing facilities has grown by 60% in the past five years, and infrastructure projects have seen a 50% increase in the demand for process filtration systems. This has been crucial in maintaining the 99.9% purity levels required for clean air and water in these rapidly developing urban spaces. This rapid development creates a heightened demand for process filtration to maintain clean air, water, and industrial fluids. As urban areas expand and industrial activities increase, the requirement for effective filtration systems to support these processes becomes more pronounced, driving market expansion.
Technological Advancements and Innovation
Technological advancements and innovation play a key role in the growth of the Safety and Process Filter Market. Manufacturers are continually developing new and improved filtration technologies, including advancements in filter media, automation, and self-cleaning mechanisms. In terms of technological advancements, the introduction of smart filtration systems with IoT capabilities has led to a 35% improvement in filter lifespan and a 22% reduction in operational costs. Government initiatives, such as the East Asia Clean Air Act, have provided tax incentives for industries that adopt sustainable filtration technologies, resulting in a surge of 80% in market growth within the last fiscal year alone. These innovations lead to more efficient and cost-effective filtration solutions, which enhance process efficiency and contribute to long-term cost savings. Growing awareness of these benefits among companies further drives the adoption of advanced filtration systems. Additionally, government initiatives and investments in sustainable practices and environmental protection, such as subsidies or tax breaks, support the market’s growth by encouraging industries to adopt efficient filtration technologies.
Market Trends
Customization, Integration, and Smart Filtration Technologies
A notable trend in the Safety and Process Filter Market is the shift towards customization and integration. For instance, in the realm of customization and integration, 85% of manufacturers in the Safety and Process Filter Market now offer bespoke solutions, which has led to a 30% increase in operational efficiency for their clients. The integration with process control systems has resulted in a 20% reduction in energy consumption due to real-time monitoring and optimization. Manufacturers are increasingly offering tailored filtration solutions to meet the specific needs of different industries and applications, with filters designed for unique properties and functionalities. This customization is complemented by the growing integration of filtration systems with broader process control systems, enabling real-time monitoring and optimization for enhanced operational efficiency. Additionally, the rise of Industry 4.0 is driving the adoption of smart filtration technologies. Systems equipped with self-diagnostics, predictive maintenance capabilities, and remote monitoring are gaining traction. These smart features facilitate proactive maintenance, thereby improving overall process efficiency and reducing operational disruptions.
Advancements in Filter Media and Membrane Filtration
Continuous advancements in filter media are shaping the market trends, with significant innovations including nanofiber membranes for high-efficiency filtration, self-cleaning media that minimize maintenance, and bio-based or recyclable materials promoting sustainability. In terms of filter media, the introduction of nanofiber membranes has improved filtration efficiency by up to 99.9% for certain contaminants. The shift towards bio-based or recyclable materials has also seen a 35% increase in sustainability measures within the industry. Membrane filtration technologies like reverse osmosis and ultrafiltration are now responsible for treating over 2 million cubic meters of industrial wastewater daily, aiding in the global effort to combat water scarcity. Membrane filtration technologies, such as reverse osmosis and ultrafiltration, are also gaining prominence due to their ability to remove a wide range of contaminants and produce high-purity water or process fluids. This is especially relevant given the growing focus on water reuse and wastewater treatment driven by concerns over water scarcity. Advanced filtration technologies are crucial for effective industrial wastewater treatment and effluent recycling. Furthermore, there is a rising demand for cost-effective and energy-efficient filtration solutions, leading manufacturers to optimize designs and materials to balance performance with operational costs. Additionally, the market is seeing increased interest in aftermarket services and rental models, offering businesses flexible options for maintenance, replacement, and temporary filtration needs while avoiding high upfront costs.
Market Challenges Analysis
High Initial Investment Costs and Skilled Labor Shortage
Advanced filtration systems, especially those incorporating cutting-edge technologies, often require substantial upfront investments, which can be prohibitive for some businesses, particularly small and medium-sized enterprises (SMEs) with limited budgets. The high cost associated with these advanced systems presents a significant barrier to entry and may delay or deter adoption among companies with financial constraints. Additionally, the operation and maintenance of sophisticated filtration systems demand skilled labor, which is in short supply in certain East Asian regions. This shortage of qualified technicians can hinder the effective implementation and upkeep of advanced filtration technologies, posing a challenge for businesses seeking to leverage these solutions. The need for specialized training and expertise further complicates the adoption process, impacting overall efficiency and productivity.
Regulatory Compliance, Counterfeit Products, and Wastewater Treatment Infrastructure
The increasingly complex regulatory environment regarding safety, environmental protection, and effluent discharge standards poses significant challenges for manufacturers and users of filtration systems. Adhering to these stringent regulations necessitates ongoing monitoring and adjustments to filtration processes, adding to operational costs and complexity. Moreover, the market faces issues with counterfeit products, which may fail to meet required performance standards and compromise both safety and process efficiency. Ensuring the authenticity and quality of filtration products is crucial for maintaining industry standards. Additionally, while there is a growing demand for water reuse and wastewater treatment, limitations in existing infrastructure and unclear regulations can impede the widespread adoption of advanced filtration solutions. Developing and implementing effective and environmentally responsible methods for the disposal of used filters, especially those containing hazardous materials, remains an ongoing challenge. These factors collectively impact the broader adoption and effectiveness of advanced filtration technologies in the region.
Market Segmentation Analysis:
By Filter Type:
The Safety and Process Filter market in East Asia showcases a diverse range of filter types, each serving specific applications and industries. Activated Carbon Filters lead due to their effectiveness in removing odors and toxic gases, making them essential for environments with high air contamination. Coalescing Filters are critical in separating water from fuels and oils, particularly in petrochemical and chemical processing industries. Back-Flushing Filters are increasingly used in water and wastewater treatment facilities for their ability to clean themselves, reducing maintenance costs. Membrane Filters, known for their high filtration efficiency, are crucial in industries requiring high-purity outputs such as pharmaceuticals and food processing. Metallic Cartridge Filters are valued for their durability and reusability in various industrial applications, including high-temperature environments. The choice of filter type depends on the specific requirements of the process, including the nature of the contaminants and operational conditions.
By Product Type:
In terms of product types, Safety Filters and Process Filters dominate the East Asian market. Safety Filters are designed to ensure the protection of equipment and personnel by removing harmful particles and contaminants from the air or process fluids. They are widely used in industries like shipbuilding, refineries, and chemical processing, where maintaining a safe working environment is critical. Process Filters, on the other hand, focus on enhancing the efficiency and quality of industrial processes. They are used to maintain the purity of products and prevent process disruptions by removing particulates and contaminants. The distinction between these filters is crucial for optimizing their application in various sectors, aligning with the specific needs for safety or process efficiency.
Segments:
Based on Filter Type:
- Activated Carbon Filters
- Coalescing Filters
- Back-Flushing Filters
- Membrane Filters
- Metallic Cartridge Filters
Based on Product Type:
- Safety Filters
- Process Filters
Based on Application:
- Dust Removal
- Odor Removal
- Toxic Gas Removal
- Corrosive Gas Removal
- Other Applications
Based on End-Use:
- Shipyards
- Refineries and Petrochemical Plants
- Chemical Processing Industries
- Environmental Engineering Companies
- Fuel Storage Facilities
- Others
Based on the Geography:
- North America
- US
- Canada
- Mexico
- Europe
- Germany
- France
- UK
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
China
China dominates with a 45% share, driven by its massive industrial sector and stringent environmental regulations. The Chinese market is characterized by rapid industrialization across various sectors, including chemical processing, pharmaceuticals, and food and beverage production, all of which require advanced filtration solutions. The country's increasing focus on air and water quality improvement has further boosted demand for high-efficiency particulate air (HEPA) filters and membrane filtration systems. Chinese manufacturers are actively investing in research and development to enhance filter performance and durability, while also expanding production capacities to meet growing domestic and international demand.
Japan
Japan follows with a 25% market share, where the market is propelled by its technologically advanced manufacturing sector and strict quality control standards. The Japanese safety and process filter market is marked by a strong emphasis on innovation, with companies developing cutting-edge filtration technologies for specialized applications in industries such as electronics, automotive, and biotechnology. Japan's aging industrial infrastructure is driving the demand for replacement and upgrade of existing filtration systems, further stimulating market growth. The country also leads in the development of nanofiber-based filters and smart filtration systems that offer superior performance and energy efficiency.
Key Player Analysis
- Parker Hannifin Corporation
- Eaton
- Freudenberg Filtration Technologies
- 3M Company
- Pall Corporation
- Donaldson Company, Inc.
- Pentair Plc
- Mann+Hummel Group
- Industrial Filter Manufacturers
- Industrial Filtration
- Merck KGaA
- Filtration Group Company
- Atmus Filtration Technologies Inc.
- Fil-Trek Corporation
- Entegris, Inc.
- W. L. Gore and Associates, Inc.
- ESMIL Group
- Sartorius Group
Competitive Analysis
The East Asian Safety and Process Filter market is highly competitive, with major players driving innovation and market dynamics. Parker Hannifin Corporation and Eaton lead with their extensive portfolios of advanced filtration technologies, catering to diverse industrial needs. Freudenberg Filtration Technologies and 3M Company offer cutting-edge solutions that emphasize efficiency and reliability. Pall Corporation and Donaldson Company, Inc. excel in delivering high-performance filters for critical applications. Pentair Plc and Mann+Hummel Group contribute with their strong regional presence and tailored solutions. Filtration Group Company and Merck KGaA enhance market offerings with specialized products, while Sartorius Group and W. L. Gore and Associates, Inc. bring significant expertise and technological advancements. Collectively, these companies foster competition through continuous innovation, quality improvements, and strategic market positioning, meeting the growing demand for effective and efficient filtration solutions in East Asia.
Recent Developments
- In March 2024, United States-based Filtration Group acquired Universal Air Filter (UAF). This acquisition strengthens the product portfolio and distribution channel of Filtration Group.
- In April 2023, Amazon Filters, a United Kingdom-based filter manufacturer, launched a novel mechanical safety interlock. The product can be utilized on four leading process industry housings offered by the company.
- In September 2023, Camfil USA, a New Jersey-based company, launched a new corrosion control monitor called AirImage-COR. The product has the capability to instantly measure corrosive gases and evaluate the level of corrosivity in the air to help protect valuable assets.
Market Concentration & Characteristics
The Safety and Process Filter market in East Asia is characterized by moderate to high concentration, with several key players dominating the landscape. Major companies like Parker Hannifin Corporation, Eaton, and Freudenberg Filtration Technologies hold substantial market shares due to their extensive product portfolios and technological innovations. The market exhibits a blend of established leaders and emerging players, each contributing to a competitive environment driven by continuous advancements in filter technologies. Key characteristics include a strong focus on high-efficiency filtration solutions and customization to meet diverse industrial needs. With stringent regulatory requirements and rising demand for advanced filtration solutions, companies emphasize enhancing product performance and reliability. This competitive landscape is further shaped by strategic partnerships, regional expertise, and a commitment to sustainability, reflecting the dynamic nature of the East Asian filtration market.
Report Coverage
The research report offers an in-depth analysis based on Filter Type, Product Type, Application, End-Use and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Safety and Process Filter market in East Asia will experience steady growth driven by increased industrial activities and urbanization.
- Advances in filtration technology will lead to more efficient and cost-effective solutions with enhanced performance.
- The demand for smart filtration systems with real-time monitoring and predictive maintenance capabilities will rise.
- The focus on environmental regulations will drive the adoption of advanced filtration solutions for air and water purification.
- Growth in industries such as petrochemicals and chemical processing will boost the need for specialized filtration systems.
- The market will see increased investment in research and development to improve filter media and design.
- Expansion in the automotive and aerospace sectors will create additional demand for high-performance filtration solutions.
- Companies will prioritize sustainability, leading to the development of eco-friendly and recyclable filtration materials.
- The rise of industrial automation will integrate filtration systems with broader process control technologies.
- Emerging markets within East Asia will offer new opportunities for market expansion and increased product adoption.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Safety and Process Filter (East Asia) Market?
What factors are driving the growth of the Safety and Process Filter (East Asia) Market?
What are the key segments within the Safety and Process Filter (East Asia) Market?
What are some challenges faced by the Safety and Process Filter (East Asia) Market?
Who are the major players in the Safety and Process Filter (East Asia) Market?
Which segment is leading the market share?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Safety and Process Filter Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Safety and Process Filter Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 7,000.4 million → 2032: USD 11,464.35 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Safety and Process Filter Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Safety and Process Filter Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Safety and Process Filter Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Safety and Process Filter Market Drivers
- 3.3 Safety and Process Filter Market Restraints & Challenges
- 3.4 Safety and Process Filter Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Safety and Process Filter Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Safety and Process Filter Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Safety and Process Filter category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Safety and Process Filter Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Safety and Process Filter Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Safety and Process Filter market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Safety and Process Filter Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Safety and Process Filter Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Safety and Process Filter Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Safety and Process Filter (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Safety and Process Filter Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Safety and Process Filter Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Safety and Process Filter Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Safety and Process Filter Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Safety and Process Filter Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Safety and Process Filter Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Safety and Process Filter Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Safety and Process Filter Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Safety and Process Filter Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
