
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Safety Eyewear Market Size 2024 | USD 4,244.64 million |
| Safety Eyewear Market, CAGR | 6.08% |
| Safety Eyewear Market Size 2032 | USD 6,806.27 million |
Market Overview
The Global Safety Eyewear market size was valued at USD 4,244.64 million in 2024 and is anticipated to reach USD 6,806.27 million by 2032, at a CAGR of 6.08% during the forecast period (2024-2032).
The Global Safety Eyewear market is experiencing steady growth driven by increasing workplace safety regulations across industries such as construction, manufacturing, and healthcare. Rising awareness about eye protection, coupled with stricter enforcement of occupational safety standards, fuels demand for high-performance protective eyewear. The market also benefits from growing adoption in laboratories and cleanrooms, where contamination control is critical. Technological advancements, including anti-fog coatings, impact resistance, and lightweight materials, are enhancing user comfort and functionality, boosting product appeal. In addition, the rise of stylish and ergonomically designed safety eyewear is helping to overcome user resistance, especially in non-industrial settings. A growing preference for reusable and sustainable protective equipment is also shaping product innovation. The integration of smart features such as heads-up displays and augmented vision tools further reflects a trend toward multifunctionality in personal protective equipment, supporting the long-term expansion of the Safety Eyewear market globally.
The Global Safety Eyewear Market demonstrates strong geographical presence across North America, Europe, and Asia Pacific, with each region contributing significantly to overall growth. North America leads in adoption due to strict safety regulations and high awareness across industrial sectors. Europe follows closely, driven by advanced manufacturing, emphasis on sustainable practices, and growing use in healthcare and research facilities. Asia Pacific shows rapid expansion fueled by industrial growth, infrastructure development, and increasing workplace safety compliance. Key players shaping the market include Kimberly-Clark Corp., MCR Safety, Honeywell International, Inc., 3M, and Radians, Inc. These companies focus on product innovation, ergonomic design, and advanced lens technologies to meet evolving safety standards. They maintain a strong presence through diversified product portfolios, regional manufacturing facilities, and digital sales channels. Strategic partnerships, R&D investments, and expansion into emerging markets help them stay competitive in a market driven by functionality, comfort, and regulatory alignment.
Market Insights
- The Global Safety Eyewear Market was valued at USD 4,244.64 million in 2024 and is projected to reach USD 6,806.27 million by 2032, growing at a CAGR of 6.08% during the forecast period.
- Increasing workplace safety regulations across sectors such as construction, oil & gas, and manufacturing are driving the demand for certified protective eyewear.
- The market is witnessing a shift toward stylish, ergonomic designs and smart features like anti-fog lenses and heads-up displays to enhance comfort and user compliance.
- Key players including Kimberly-Clark Corp., Honeywell International, Inc., 3M, MCR Safety, and Radians, Inc. are focusing on product innovation and global expansion to stay competitive.
- Price sensitivity in emerging markets and the presence of low-cost, uncertified alternatives are restraining the widespread adoption of high-quality safety eyewear.
- North America leads in demand due to strong regulatory enforcement, while Asia Pacific shows the fastest growth driven by industrialization and infrastructure development.
- The market continues to benefit from the growing adoption of e-commerce platforms and direct-to-consumer models, expanding access across both industrial and personal safety segments.
Report Scope
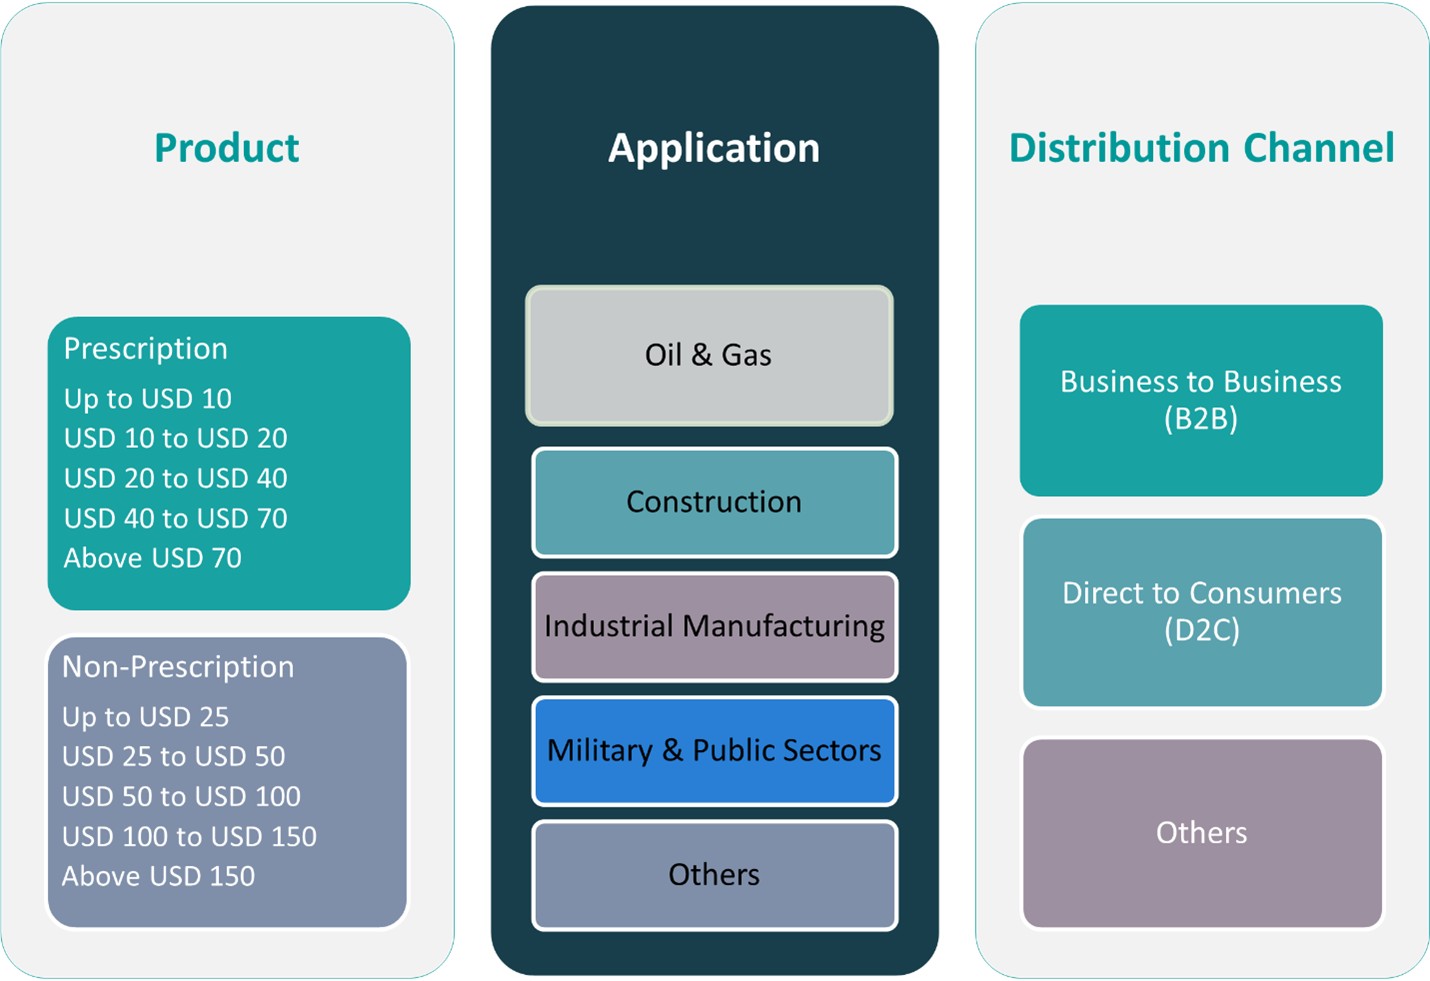
This report segments the Global Safety Eyewear Market as follows:
Market Drivers
Stringent Occupational Safety Regulations Accelerate Adoption
Government mandates and industry-specific regulations are major forces driving the Global Safety Eyewear Market. Regulatory bodies such as OSHA in the U.S. and EU-OSHA in Europe enforce strict compliance regarding employee safety, particularly in construction, manufacturing, and mining sectors. These industries present high risks of eye injuries, prompting companies to invest in certified protective eyewear. The growing emphasis on worker health and safety ensures sustained demand. Non-compliance often leads to penalties, encouraging consistent use of protective gear. The market benefits from rising institutional awareness of employee well-being.
- For instance, OSHA reports that eye injuries account for approximately 2,000 workplace incidents daily in the U.S., reinforcing the need for certified protective eyewear.
Increased Awareness of Eye Health Supports Market Expansion
Public and professional awareness around eye protection is increasing, influencing demand across multiple sectors. Campaigns promoting workplace safety and occupational health have led to a greater understanding of the risks associated with unprotected exposure. Industries such as healthcare and laboratory research now routinely use safety eyewear. The demand is also expanding into home and recreational activities like DIY tasks and sports. It allows manufacturers to target diverse customer bases beyond traditional industrial settings. The market stands to benefit from this widening application spectrum.
- For instance, workplace eye injuries decreased by 15.6% in 2020, yet over 18,510 cases still required at least one day away from work, highlighting the ongoing need for protective eyewear.
Rising Industrialization and Infrastructure Projects Create Demand
Rapid industrial growth across developing regions contributes significantly to the expansion of the Global Safety Eyewear Market. Emerging economies in Asia Pacific, Latin America, and the Middle East are seeing increased construction and infrastructure activities. These sectors require protective gear, including safety eyewear, for daily operations. Industrial automation and the growth of sectors like oil & gas and automotive further boost product consumption. Employers prioritize protective equipment to maintain productivity and reduce workplace incidents. This ongoing industrial expansion supports market growth in both established and emerging regions.
Technological Innovation Enhances Product Functionality
Innovations in lens materials, anti-fog coatings, and impact resistance are transforming the product landscape. Safety eyewear is no longer limited to bulky designs but now includes lightweight, comfortable, and visually appealing options. This evolution encourages broader adoption, especially in sectors where long hours of wear are required. Manufacturers integrate features like UV protection, scratch resistance, and interchangeable lenses to improve user experience. The Global Safety Eyewear Market benefits from such developments, which align with user preferences and industry requirements. These enhancements position protective eyewear as essential, not optional.
Market Trends
Integration of Smart Technologies Enhances Product Appeal
The incorporation of smart features into protective eyewear is reshaping user expectations and product design. Augmented reality displays, real-time data overlays, and connectivity to wearable systems are entering industrial settings. These innovations support worker training, improve task efficiency, and provide immediate hazard alerts. The Global Safety Eyewear Market benefits from this technological shift as industries seek multifunctional gear. It aligns with digital transformation strategies in manufacturing, energy, and defense sectors. Smart eyewear also supports remote collaboration in high-risk environments.
- For instance, manufacturers are integrating augmented reality (AR) displays and heads-up displays (HUDs) into safety eyewear to enhance worker efficiency and safety in industrial settings.
Emphasis on Style and Comfort Drives Broader Usage
Design evolution now plays a critical role in encouraging compliance across varied user groups. Employees prefer lightweight frames, ergonomic fits, and aesthetic appeal, particularly in environments requiring extended wear. Stylish protective eyewear is no longer confined to industrial applications but is being adopted in healthcare, research, and consumer markets. It helps eliminate resistance to usage by blending safety with visual appeal. The Global Safety Eyewear Market gains from manufacturers offering both protection and comfort. Enhanced user experience has become a competitive differentiator.
- For instance, Bollé Safety launched a new collection of safety goggles featuring wraparound designs for enhanced protection against dust, splashes, and impacts.
Sustainability Trends Influence Material Choices
Growing environmental consciousness is pushing manufacturers to develop eco-friendly products. Biodegradable frames, recyclable lenses, and sustainable packaging are emerging across product lines. It reflects broader ESG goals adopted by organizations worldwide. The demand for long-lasting and reusable eyewear also supports sustainable practices. The Global Safety Eyewear Market is adapting to these expectations by shifting toward circular material use. These practices help brands meet regulatory guidelines and appeal to environmentally aware buyers.
Online Retail and Direct-to-Consumer Channels Expand Reach
The shift toward e-commerce and direct sales models is increasing product accessibility across geographies. Online platforms allow buyers to compare features, certifications, and prices with ease. Brands leverage digital marketing to educate users about different product categories and their applications. It helps small and medium businesses access professional-grade safety equipment affordably. The Global Safety Eyewear Market benefits from this channel expansion by reaching niche segments and new markets. The trend supports both B2B and B2C growth strategies.
Market Challenges Analysis
High Price Sensitivity in Emerging Markets Restricts Growth
Cost remains a major barrier in expanding adoption across developing regions. Many small and medium-sized enterprises operate with limited safety budgets and prioritize essential protective equipment over premium eyewear. Low-cost imports and counterfeit products further complicate market penetration for established brands. The Global Safety Eyewear Market faces challenges in convincing buyers to shift from basic or unregulated products to certified, high-quality alternatives. It requires continuous education efforts and regulatory enforcement to change buyer behavior. Price-conscious markets often choose short-term savings over long-term safety investments.
- For instance, industrial automation and infrastructure expansion in Asia-Pacific have driven demand for safety eyewear, but price sensitivity remains a challenge for small and medium-sized enterprises.
Lack of Awareness and Compliance Limits Adoption
Despite regulations, many industries experience gaps in safety culture and enforcement. Workers may avoid wearing safety eyewear due to discomfort, lack of training, or underestimation of risks. Employers in certain sectors still overlook compliance due to operational pressures or limited inspection mechanisms. The Global Safety Eyewear Market struggles to achieve consistent usage across informal or unorganized sectors. It creates uneven demand patterns and affects standardization efforts. Stronger awareness programs and industry partnerships are essential to improve adoption rates and reduce workplace eye injuries.
Market Opportunities
Expansion into Non-Industrial Applications Unlocks New Demand
The growing awareness of personal safety outside industrial environments creates strong potential for category expansion. Sectors such as healthcare, education, sports, and household DIY activities now seek reliable eye protection solutions. Consumers increasingly purchase protective eyewear for personal use, broadening the target audience. The Global Safety Eyewear Market can leverage this trend by introducing products tailored for recreational and non-occupational use. It supports brand diversification and allows manufacturers to build direct-to-consumer relationships. Product innovations focused on comfort, style, and dual-purpose utility will help capture this emerging segment.
Adoption of Digital Platforms Supports Global Market Access
E-commerce growth offers strong distribution advantages for safety eyewear brands, especially in underpenetrated regions. Online platforms enable businesses to reach end users directly, educate them on certification standards, and offer customizable solutions. The Global Safety Eyewear Market benefits from digital tools that simplify product comparisons and enhance buyer decision-making. It reduces dependency on traditional supply chains and supports market entry with minimal physical infrastructure. Regional players can also scale by leveraging global marketplaces. Investments in digital marketing and customer engagement will accelerate visibility and sales across new demographics.
Market Segmentation Analysis:
By Product:
Within the product category, prescription safety eyewear holds a significant share due to its dual function of vision correction and eye protection. Price-based segments such as USD 20 to USD 40 and USD 40 to USD 70 are in demand for industrial and healthcare use. Non-prescription eyewear appeals to consumers seeking immediate protection, with strong uptake in the USD 25 to USD 50 and USD 50 to USD 100 ranges. It enables broader adoption across recreational, DIY, and workplace safety needs.
By Application:
By application, the construction and industrial manufacturing sectors dominate due to constant exposure to dust, debris, and hazardous materials. The oil & gas segment also demands high-grade protective eyewear, especially in offshore and chemical processing zones. Military and public sector use is growing steadily with adoption of advanced ballistic-rated eyewear.
By Distribution Channel:
The Global Safety Eyewear Market also segments by distribution channel into B2B, D2C, and others. B2B remains dominant due to institutional procurement and bulk purchasing by companies. Direct-to-consumer channels are gaining traction through online platforms offering customized and stylish safety eyewear for personal use.
Segments:
Based on Product:
- Prescription
- Up to USD 10
- USD 10 to USD 20
- USD 20 to USD 40
- USD 40 to USD 70
- Above USD 70
- Non-Prescription
- Up to USD 25
- USD 25 to USD 50
- USD 50 to USD 100
- USD 100 to USD 150
- Above USD 150
Based on Application:
- Oil & Gas
- Construction
- Industrial Manufacturing
- Military & Public Sectors
- Others
Based on Distribution Channel:
- Business to Business (B2B)
- Direct to Consumers (D2C)
- Others
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis
North America
North America holds a leading share in the Global Safety Eyewear Market, driven by strict workplace safety regulations and high awareness across industries. The U.S. accounts for the majority of the regional revenue due to strong adoption in construction, oil & gas, and industrial manufacturing sectors. Regulatory bodies like OSHA enforce compliance, ensuring consistent demand for certified protective eyewear. Major companies in the region invest in R&D to enhance product features such as anti-fog coating, UV protection, and comfort. E-commerce expansion further supports market penetration among individual consumers. North America accounted for over 32% of the global market share in 2024.
Europe
Europe ranks as the second-largest market with a strong presence in Germany, the U.K., and France. Stringent health and safety directives from the EU drive institutional adoption across manufacturing and public sector organizations. The region focuses on sustainable materials and ergonomic design, aligning with environmental and worker welfare goals. European companies are integrating recyclable components and smart features to address evolving needs. The Global Safety Eyewear Market in Europe benefits from steady industrial activity and growing demand in laboratories and healthcare environments. Europe held approximately 26% of the market share in 2024.
Asia Pacific
Asia Pacific is the fastest-growing region due to rapid industrialization, urban infrastructure projects, and rising worker safety awareness. Countries like China, India, and Japan are investing in manufacturing and construction, which increases the use of protective gear. Local governments are enforcing safety compliance more strictly, especially in hazardous environments. The Global Safety Eyewear Market in Asia Pacific sees rising demand for affordable, durable, and lightweight products. Domestic manufacturers are scaling up production and expanding distribution networks to meet local needs. Asia Pacific captured around 28% of the global market share in 2024.
Key Player Analysis
- Kimberly-Clark Corp.
- MCR Safety
- Honeywell International, Inc.
- 3M
- Radians, Inc.
Competitive Analysis
The competitive landscape of the Global Safety Eyewear Market is defined by the presence of several established players focused on innovation, product quality, and distribution strength. Key companies include Kimberly-Clark Corp., MCR Safety, Honeywell International, Inc., 3M, and Radians, Inc. These manufacturers compete by offering wide-ranging product portfolios that meet regulatory standards and cater to various industrial needs, from basic impact protection to specialized applications requiring anti-fog, anti-scratch, and UV-resistant coatings. Most of these companies maintain strong global supply chains and invest in regional manufacturing to optimize logistics and cost-efficiency. They also focus on R&D to introduce ergonomic and lightweight designs that enhance user comfort and encourage daily compliance. Digital transformation strategies, including direct-to-consumer sales and online customization options, further strengthen their market position. Strategic partnerships with distributors, safety training initiatives, and compliance-focused marketing help these players differentiate themselves in a competitive space that values both safety and user experience.
Recent Developments
- In April 2024, Popticals, a premium eyewear brand, launched the POPZULU Ops Edition, a line of ballistic glasses and safety eyewear. POPZULU is designed for tactical and industrial environments, offering full-scale defense with lenses engineered to shield and a frame that can collapse into a pocket-sized hard-shell case. The POPZULU sunglasses feature an innovative frame design and patented FL2 Micro-Rail System technology for collapsibility. They are crafted using high-quality materials like Hydrophobic Ri-Pel coating, Grilamid TR90 for lightweight and durability, and Impacto lenses from Carl Zeiss Vision that are 5X more resistant to hits and stresses than polycarbonate.
- In April 2024, Innovative Eyewear, Inc. announced filing two new U.S. patent applications related to its new Lucyd Armor smart safety glasses product, which is planned for introduction in mid-2024. The utility patent application covers the product's functional aspects, while the design patent application covers its ornamental design.
- In March 2024, Protective Industrial Products (PIP), a leader in personal protective equipment, acquired Scope Optics Pty Ltd., a safety eyewear company based in Australia. By incorporating Scope Optics' safety eyewear into its existing portfolio of eye protection brands, PIP is adding a wider selection of premium designs, advanced lens technologies, and exceptional value to serve its customers better. The acquisition of Scope Optics is another example of PIP's proven acquisition strategy to strengthen its portfolio of head-to-toe PPE solutions.
Market Concentration & Characteristics
The Global Safety Eyewear Market exhibits moderate to high market concentration, with a few major players dominating global sales through broad product portfolios and established distribution networks. It is characterized by steady demand from core sectors such as construction, oil & gas, manufacturing, and defense, where regulatory compliance ensures consistent product usage. The market favors companies that offer certified, comfortable, and technologically advanced eyewear, often tailored to meet specific occupational requirements. It also includes a mix of large multinationals and regional manufacturers, with competitive pricing playing a key role in emerging markets. Innovation in lens materials, frame design, and integration of smart features defines the evolving nature of the product landscape. The Global Safety Eyewear Market values functionality, durability, and user comfort, and its structure supports long-term contracts, institutional purchases, and rising consumer demand through online retail. Scalability and responsiveness to safety standards influence brand success and buyer loyalty.
Report Coverage
The research report offers an in-depth analysis based on Product, Application, Distribution Channel and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market is projected to grow steadily, driven by increasing awareness of workplace safety and stringent regulations across various industries.
- Technological advancements will lead to the development of smart safety eyewear with features like augmented reality displays and real-time hazard detection.
- There will be a growing demand for lightweight and comfortable eyewear, encouraging manufacturers to focus on ergonomic designs and advanced materials.
- The integration of sustainable materials in eyewear production will gain traction, aligning with global environmental concerns and consumer preferences.
- The Asia Pacific region is expected to witness significant growth due to rapid industrialization and increasing adoption of safety standards.
- Online retail channels will become more prominent, offering consumers easier access to a wide range of safety eyewear products.
- Customization options in safety eyewear will become more prevalent, catering to specific industry needs and individual preferences.
- Collaborations between safety eyewear manufacturers and technology firms will lead to innovative product offerings.
- The incorporation of anti-fog, anti-scratch, and UV protection features will become standard in safety eyewear products.
- Education and training programs emphasizing the importance of eye protection will support market growth by increasing product adoption rates.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Stringent Occupational Safety Regulations
Government mandates and industry-specific regulations, such as those enforced by OSHA and EU-OSHA, require the use of certified protective eyewear in high-risk sectors like construction, manufacturing, and mining. This regulatory pressure ensures consistent demand for safety eyewear as companies seek to avoid penalties and protect worker health.
Rising Awareness of Eye Health and Safety
Increased public and professional awareness about the risks of eye injuries has led to greater adoption of safety eyewear across industries and even in non-industrial settings such as healthcare, laboratories, and home DIY activities. Educational campaigns and workplace safety initiatives are expanding the market's reach.
Technological Advancements in Eyewear
Innovations such as anti-fog coatings, impact-resistant materials, lightweight frames, and smart features like heads-up displays are making safety eyewear more comfortable, functional, and appealing. These advancements drive higher compliance and open new application areas, supporting market growth.
Rapid Industrialization and Infrastructure Development
Emerging economies, particularly in Asia Pacific and Latin America, are experiencing significant growth in construction, manufacturing, and infrastructure projects. This expansion increases the need for protective equipment, including safety eyewear, to ensure worker safety and regulatory compliance.
Growth of E-commerce and Direct-to-Consumer Channels
The increasing adoption of online retail platforms and direct sales models is making safety eyewear more accessible to both industrial buyers and individual consumers. This trend is expanding market penetration, especially in under-served regions and among new customer segments.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Safety Eyewear Market?
What factors are driving the growth of the Safety Eyewear Market?
What are the key segments within the Safety Eyewear Market?
What are some challenges faced by the Safety Eyewear Market?
Who are the major players in the Safety Eyewear Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Product
- 1.2.1 Prescription (Up to USD 10, USD 10 to USD 20, USD 20 to USD 40, USD 40 to USD 70, Above USD 70)
- 1.2.2 Non-Prescription (Up to USD 25, USD 25 to USD 50, USD 50 to USD 100, USD 100 to USD 150, Above USD 150)
- 1.3 By Application
- 1.3.1 Oil & Gas
- 1.3.2 Construction
- 1.3.3 Industrial Manufacturing
- 1.3.4 Military & Public Sectors
- 1.3.5 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 4,244.64 million → 2032: USD 6,806.27 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Safety Eyewear Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Safety Eyewear Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Safety Eyewear Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Safety Eyewear Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Safety Eyewear Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Safety Eyewear Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Safety Eyewear Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Safety Eyewear Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 4,244.64 million → 2032: USD 6,806.27 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Safety Eyewear Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Product - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Prescription (Up to USD 10, USD 10 to USD 20, USD 20 to USD 40, USD 40 to USD 70, Above USD 70)
- 12.3.7.2 Non-Prescription (Up to USD 25, USD 25 to USD 50, USD 50 to USD 100, USD 100 to USD 150, Above USD 150)
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Oil & Gas
- 12.4.7.2 Construction
- 12.4.7.3 Industrial Manufacturing
- 12.4.7.4 Military & Public Sectors
- 12.4.7.5 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global Safety Eyewear End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Safety Eyewear Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Safety Eyewear Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Safety Eyewear Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Kimberly-Clark Corp.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 MCR Safety
- 18.4 Honeywell International, Inc.
- 18.5 3M
- 18.6 Radians, Inc.
- 18.7 Protective Industrial Products (PIP)
- 18.8 Bollé Safety
- 18.9 Uvex Safety Group
- 18.10 DuPont
- 18.11 Gateway Safety
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

