
Market Overview:
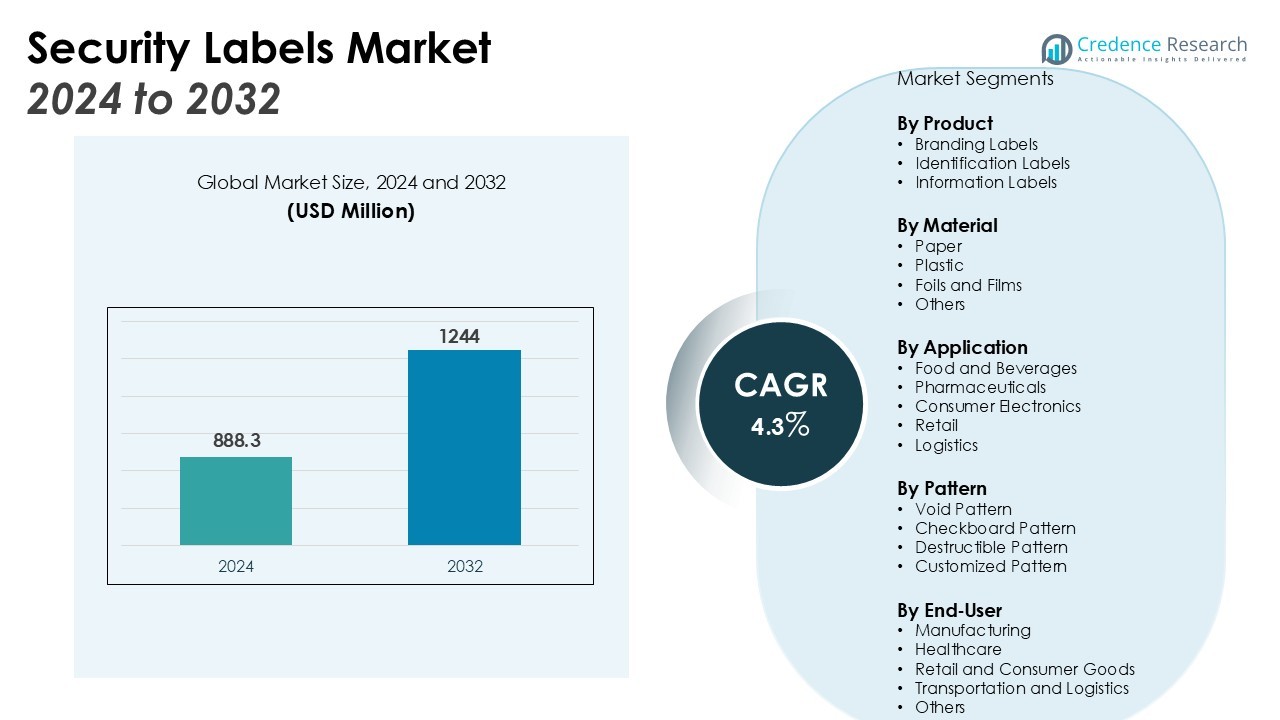
The Security Labels Market size was valued at USD 888.3 million in 2024 and is anticipated to reach USD 1244 million by 2032, at a CAGR of 4.3% during the forecast period (2024-2032).
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Security Labels Market Size 2024 | USD 888.3 Million |
| Security Labels Market, CAGR | 4.3% |
| Security Labels Market Size 2032 | USD 1244 Million |
The security labels market is experiencing steady expansion, supported by strong industry-wide adoption. Growth is driven by rising concerns over counterfeiting and theft, which encourage companies in pharmaceuticals, food and beverages, electronics, and luxury goods to use tamper-evident and authentication solutions. Regulatory frameworks, including serialization and traceability requirements, further strengthen demand. Continuous innovation in RFID, QR codes, holograms, and digital printing enhances label effectiveness, while the rapid rise of e-commerce fuels greater use of secure packaging across supply chains.
North America holds a dominant position due to strict regulatory standards, high consumer awareness, and widespread use of advanced labeling technologies. Asia-Pacific is emerging as the fastest-growing market, supported by rapid industrialization, expansion of e-commerce platforms, and growing compliance needs across exports. Europe continues to remain an important region, benefiting from established regulatory frameworks and demand for premium security packaging solutions. Latin America and the Middle East & Africa are also developing steadily, with growth underpinned by expanding retail networks, rising manufacturing activity, and increasing focus on brand protection.
Market Insights:
- The Security Labels Market reached USD 888.3 million in 2024 and is forecast to hit USD 1244 million by 2032, registering a CAGR of 4.3%.
- Rising counterfeiting and theft risks in pharmaceuticals, food and beverages, electronics, and luxury goods continue to drive adoption of tamper-evident and authentication labels.
- Government regulations mandating serialization, traceability, and compliance frameworks are reinforcing demand and creating strong entry barriers for non-compliant players.
- Technological advancements such as RFID, QR codes, holograms, and digital printing are enhancing label effectiveness, improving verification, and expanding supply chain transparency.
- The rapid growth of e-commerce and global trade is fueling demand for secure, tamper-evident packaging solutions that protect brand trust across distribution channels.
- North America accounted for 35% of market share, Asia-Pacific held 39%, and Europe represented 22%, reflecting a balanced but regionally diverse growth pattern.
- Despite high production costs and regulatory complexity, opportunities lie in sustainable materials, digital authentication, and expanding adoption across emerging economies.
Market Drivers:
Growing Threat of Counterfeiting and Product Theft
The Security Labels Market benefits from rising awareness of counterfeiting and theft across industries. Pharmaceuticals, food and beverages, electronics, and luxury goods face increasing risks, creating strong demand for tamper-evident and authentication labels. These solutions act as a first layer of protection for products during distribution and retail handling. Companies view them as essential tools for safeguarding brand reputation and consumer trust. Security labels now form a critical element of modern packaging strategies.
- For instance, Pfizer introduced RFID-embedded security labels on its Viagra packaging in 2006, enabling real-time authentication by supply chain partners, which improved counterfeit detection during distribution.
Regulatory Mandates and Compliance Requirements
Government regulations play a decisive role in shaping the Security Labels Market. Serialization laws, pharmaceutical traceability requirements, and compliance standards in various sectors require adoption of secure labeling practices. It ensures transparent product identification while reducing illegal trade activities. Businesses that fail to comply risk severe penalties and reputational damage. Regulatory enforcement continues to accelerate adoption across both developed and emerging markets.
- For instance, to meet global regulations like the U.S. Drug Supply Chain Security Act (DSCSA), Johnson & Johnson successfully implemented a serialization strategy for several thousand of its pharmaceutical products, ensuring full compliance and traceability.
Technological Advancements in Labeling Solutions
Innovation drives adoption in the Security Labels Market through the introduction of advanced features. RFID, QR codes, holograms, and digital printing are enhancing the scope and reliability of security labeling. These technologies improve product verification, support supply chain tracking, and strengthen authentication. It also provides manufacturers with flexible design options while reducing counterfeiting risks. Continuous investment in research is expanding the effectiveness and efficiency of security solutions.
Rising Impact of E-commerce and Global Supply Chains
The growth of e-commerce has created new demand patterns in the Security Labels Market. Online retail requires packaging that demonstrates integrity from dispatch to delivery. Secure and tamper-evident labels are increasingly viewed as vital for ensuring consumer confidence. It allows companies to protect shipments across complex supply networks where risks of diversion or tampering are high. The expansion of global trade further reinforces the need for reliable label-based protection.
Market Trends:
Adoption of Smart Labeling Technologies and Digital Integration
The Security Labels Market is witnessing strong adoption of smart technologies such as RFID, QR codes, and NFC-enabled solutions. These innovations allow real-time product authentication, improve traceability, and enhance supply chain transparency. It helps companies meet rising consumer expectations for secure, verified purchases across retail and online platforms. Integration of digital printing techniques also allows cost-effective customization, brand protection, and rapid scalability. Businesses are increasingly deploying labels with interactive features to engage customers and safeguard against counterfeiting. The shift toward digitally integrated security labeling reflects a broader industry trend toward combining protection with data-driven insights.
- For instance, Zebra Technologies projects that nearly six in 10 warehouse leaders plan to deploy RFID by 2028 to significantly enhance inventory visibility and reduce out-of-stock situations.
Sustainability Focus and Expansion Across Global Trade
Sustainability is shaping the Security Labels Market, with manufacturers emphasizing recyclable, biodegradable, and eco-friendly materials. It supports corporate commitments to reduce environmental impact while meeting regulatory pressures for sustainable packaging practices. Companies are focusing on lightweight label materials that lower costs without compromising durability or security. At the same time, growth in e-commerce and cross-border trade is expanding the demand for tamper-evident and authentication labels. International brands require solutions that ensure consistent product integrity across diverse regulatory environments. The combination of sustainable innovation and globalization is positioning security labels as essential components of modern packaging strategies.
- For instance, Cognosos launched the RT-270 finished vehicle logistics tag that integrates 900MHz wireless and Bluetooth Low Energy technology with an LED light, enabling real-time precise location tracking and operational efficiency improvements in automotive logistics.
Market Challenges Analysis:
High Production Costs and Complex Technology Integration
The Security Labels Market faces the challenge of balancing advanced technology with cost efficiency. Incorporating features such as RFID, holograms, and digital printing raises production expenses, which limits adoption among small and medium enterprises. It requires significant investment in specialized equipment and skilled labor to maintain quality standards. Companies often struggle to justify higher costs in price-sensitive markets, slowing overall penetration. Integration with existing supply chain systems also creates technical hurdles, demanding upgrades that not all businesses can afford. These barriers make scaling secure labeling solutions more complex across diverse industries.
Counterfeit Adaptation and Regulatory Variability
The Security Labels Market also contends with counterfeiters who quickly adapt to new technologies. It forces continuous innovation, which increases research and development costs for manufacturers. Inconsistent regulatory frameworks across countries add further complexity, creating compliance challenges for global brands. Companies must navigate differing requirements for serialization, traceability, and labeling formats, raising operational risks. The lack of standardization reduces efficiency and slows international adoption. These factors combine to create ongoing challenges that demand strategic investment and flexible solutions.
Market Opportunities:
Expansion Through Smart Packaging and Digital Authentication
The Security Labels Market holds strong opportunities through integration with smart packaging and digital authentication systems. Demand for interactive labels that link to mobile applications or online verification platforms is rising rapidly. It allows consumers to validate product authenticity and strengthens trust in global brands. Companies are leveraging QR codes, NFC, and RFID to combine brand engagement with protection. Growth of digital commerce is further fueling adoption, as online shoppers expect clear evidence of product safety. This convergence of technology and consumer trust positions secure labeling as a key enabler of modern retail strategies.
Sustainable Materials and Emerging Market Growth
The Security Labels Market is also well-positioned to benefit from the shift toward sustainable materials. Recyclable and biodegradable security labels align with corporate commitments to reduce environmental impact and meet regulatory targets. It opens new opportunities in regions where eco-friendly packaging adoption is accelerating. Expansion of retail and manufacturing in emerging economies further increases demand for tamper-evident and authentication solutions. Companies entering these markets can strengthen brand protection while complying with evolving regulatory standards. This combination of sustainability and geographic expansion creates long-term growth avenues for security label providers.
Market Segmentation Analysis:
By Product
The Security Labels Market is segmented by product into branding labels, identification labels, and information labels. Each type serves a distinct role in ensuring product safety and authenticity. Branding labels protect brand image by integrating logos and holograms, while identification labels focus on serialization and tracking. Information labels provide regulatory and handling details that support compliance and consumer safety. It reflects the wide adoption of labels as multi-functional security tools across industries.
- For instance, to enhance its brand protection offerings, All4Labels operates under the high-security certification ISO 14298, one of the key standards which ensures a secure manufacturing process for its advanced holographic labels.
By Material
Segmentation by material includes paper, plastic, and others such as foils and films. Paper labels dominate sectors requiring cost efficiency and flexibility, particularly in food and beverages. Plastic labels deliver durability, water resistance, and tamper protection, making them suitable for electronics and pharmaceuticals. Specialty foils and films offer advanced barriers and anti-counterfeit properties for high-value goods. It demonstrates how material choice is aligned with product type and regulatory requirements.
- For instance, Avery Dennison provides high-performance plastic solutions like its 2 Mil White PET label, a durable material engineered to withstand challenging conditions in specialized applications.
By Application
The Security Labels Market by application spans food and beverages, pharmaceuticals, consumer electronics, and retail. Food and beverages lead adoption due to strict safety regulations and brand protection needs. Pharmaceuticals rely on serialized and tamper-evident labels for compliance with traceability standards. Electronics and retail segments use secure labels to combat counterfeit products and safeguard customer trust. It highlights the essential role of security labels in protecting product integrity and meeting diverse industry demands.
Segmentations:
By Product
- Branding Labels
- Identification Labels
- Information Labels
By Material
- Paper
- Plastic
- Foils and Films
- Others
By Application
- Food and Beverages
- Pharmaceuticals
- Consumer Electronics
- Retail
- Logistics
By Pattern
- Void Pattern
- Checkboard Pattern
- Destructible Pattern
- Customized Pattern
By End-User
- Manufacturing
- Healthcare
- Retail and Consumer Goods
- Transportation and Logistics
- Others
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
Strong Presence in North America with Regulatory Support
North America accounted for 35% of the Security Labels Market in recent assessments. It is driven by strict compliance requirements and high consumer awareness. Companies across pharmaceuticals, food and beverage, and luxury goods sectors rely heavily on tamper-evident and authentication labels. It benefits from advanced printing technologies and established supply chain systems that ensure reliable deployment. Strong intellectual property laws and brand protection strategies further reinforce adoption. North America continues to act as a hub for innovation and early implementation of digital security features in packaging.
Rapid Expansion Across Asia-Pacific with Industrial Growth
Asia-Pacific captured 39% of the Security Labels Market in recent evaluations. It is supported by manufacturing expansion, urbanization, and the rise of e-commerce. Countries such as China, India, and Southeast Asian economies are investing in secure labeling to strengthen exports and protect brands in international trade. It benefits from growing retail demand and heightened awareness of counterfeit risks among consumers. The region is also witnessing increased adoption of smart packaging technologies integrated with QR codes and RFID. Rising government focus on regulatory compliance and product traceability further accelerates adoption.
Stable Growth in Europe with Emerging Opportunities in Other Regions
Europe represented 22% of the Security Labels Market in recent studies. It is supported by stringent regulatory frameworks and emphasis on premium product protection. Companies in the region are adopting sustainable and recyclable security labels to align with environmental policies. It reflects a strong balance between technological adoption and regulatory alignment. Emerging markets in Latin America and the Middle East & Africa are also displaying promising demand, driven by expanding retail networks and industrial sectors. These regions are increasingly turning to security labeling as a tool to combat counterfeiting and strengthen consumer trust.
Key Player Analysis:
- Zebra Technologies Corp.
- Brady Worldwide, Inc.
- 3M
- AVERY DENNISON CORPORATION.
- CCL Industries
- UPM-Kymmene Corporation
- MEGA FORTRIS GROUP
- Honeywell International, Inc.
- Invengo Information Technology Co., Ltd.
- tesa Tapes (India) Private Limited
Competitive Analysis:
The Security Labels Market is defined by strong competition among global and regional players focusing on innovation, compliance, and scalability. Leading companies invest heavily in research to enhance tamper-evident features, integrate RFID and QR technologies, and deliver cost-effective solutions that address rising counterfeiting threats. It benefits from continuous advancements in digital printing and sustainable materials that appeal to both regulatory bodies and environmentally conscious consumers. Market participants also compete through strategic mergers, acquisitions, and partnerships that expand their presence in emerging economies and strengthen product portfolios. Firms prioritize customization and supply chain integration to serve industries such as pharmaceuticals, food and beverages, electronics, and retail. The competitive landscape reflects a balance between established leaders with strong technological expertise and new entrants offering niche, eco-friendly solutions. This dynamic creates sustained pressure to innovate, improve operational efficiency, and meet evolving global standards in product authentication and brand protection.
Recent Developments:
- In March 2025, 3M formed a partnership with the European hydrogen innovation platform H2UB, contributing its expertise in materials science.
- In August 2025, Avery Dennison announced it signed a definitive agreement to acquire the U.S. flooring adhesives business of Meridian Adhesives Group for $390 million.
- In August 2024, CCL Industries announced record results for its second quarter, with a significant improvement in sales and net earnings for the six-month period ending June 30, 2024.
Report Coverage:
The research report offers an in-depth analysis based on Product, Material, Application, Pattern, End-User and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The Security Labels Market will witness steady expansion supported by demand for anti-counterfeit solutions.
- Pharmaceutical and healthcare sectors will continue to adopt serialization and traceability labels at scale.
- Food and beverage industries will drive strong usage of tamper-evident labels to ensure safety and regulatory compliance.
- It will see wider deployment of RFID, NFC, and QR-enabled labels that improve authentication and supply chain transparency.
- Sustainability will emerge as a key focus, with recyclable and biodegradable security labels gaining wider acceptance.
- E-commerce growth will increase demand for secure packaging that safeguards brand trust and consumer confidence.
- Regional growth in Asia-Pacific will strengthen further, supported by industrialization, exports, and e-commerce expansion.
- North America and Europe will maintain strong positions due to advanced regulations and established brand protection strategies.
- It will create opportunities for manufacturers investing in cost-efficient production and digital integration.
- Strategic collaborations, mergers, and investments in innovation will shape the competitive dynamics and accelerate adoption across industries.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Growing Threat of Counterfeiting and Product Theft
Increasing incidents of counterfeiting and theft in pharmaceuticals, food and beverages, electronics, and luxury goods are driving companies to adopt tamper-evident and authentication labels as essential tools for brand protection and consumer trust.
Regulatory Mandates and Compliance Requirements
Stringent government regulations around serialization, traceability, and compliance in sectors like pharmaceuticals and food are compelling businesses to implement secure labeling practices, creating strong demand and high entry barriers for non-compliant players.
Technological Advancements in Labeling Solutions
Continuous innovation in RFID, QR codes, holograms, and digital printing is enhancing the effectiveness of security labels, improving product verification, and expanding supply chain transparency, which encourages broader adoption across industries.
Rising Impact of E-commerce and Global Supply Chains
The rapid growth of e-commerce and global trade is fueling demand for secure, tamper-evident packaging solutions that protect brand trust and product integrity throughout complex distribution networks.
Sustainability Focus and Eco-friendly Materials
Increasing emphasis on recyclable, biodegradable, and eco-friendly security labels is aligning with corporate sustainability goals and regulatory pressures, opening new opportunities in regions where sustainable packaging adoption is accelerating.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Security Labels, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Security Labels Market projected to grow between 2024 and 2032?
Which Security Labels Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Security Labels Market?
Which region commanded the largest share of the Security Labels Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Pattern
- 1.2.1 Void Pattern
- 1.2.2 Checkboard Pattern
- 1.2.3 Destructible Pattern
- 1.2.4 Customized Pattern
- 1.3 By Product
- 1.3.1 Branding Labels
- 1.3.2 Identification Labels
- 1.3.3 Information Labels
- 1.4 By Material
- 1.4.1 Paper
- 1.4.2 Plastic
- 1.4.3 Foils and Films
- 1.4.4 Others
- 1.5 By Application
- 1.5.1 Food and Beverages
- 1.5.2 Pharmaceuticals
- 1.5.3 Consumer Electronics
- 1.5.4 Retail
- 1.5.5 Logistics
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 888.3 million → 2032: USD 1244 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Security Labels Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Security Labels Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Security Labels Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Security Labels Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Security Labels Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Security Labels Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Security Labels Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Security Labels Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 888.3 million → 2032: USD 1244 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Security Labels Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Pattern - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Void Pattern
- 12.3.7.2 Checkboard Pattern
- 12.3.7.3 Destructible Pattern
- 12.3.7.4 Customized Pattern
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Product - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Branding Labels
- 12.4.7.2 Identification Labels
- 12.4.7.3 Information Labels
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Material - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Paper
- 12.5.7.2 Plastic
- 12.5.7.3 Foils and Films
- 12.5.7.4 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Application - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Food and Beverages
- 12.6.7.2 Pharmaceuticals
- 12.6.7.3 Consumer Electronics
- 12.6.7.4 Retail
- 12.6.7.5 Logistics
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Security Labels End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Security Labels Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Security Labels Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Security Labels Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Zebra Technologies Corp.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Brady Worldwide, Inc.
- 18.4 3M
- 18.5 AVERY DENNISON CORPORATION
- 18.6 CCL Industries
- 18.7 UPM-Kymmene Corporation
- 18.8 MEGA FORTRIS GROUP
- 18.9 Honeywell International, Inc.
- 18.10 Invengo Information Technology Co., Ltd.
- 18.11 tesa Tapes (India) Private Limited
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

