
Market Overview
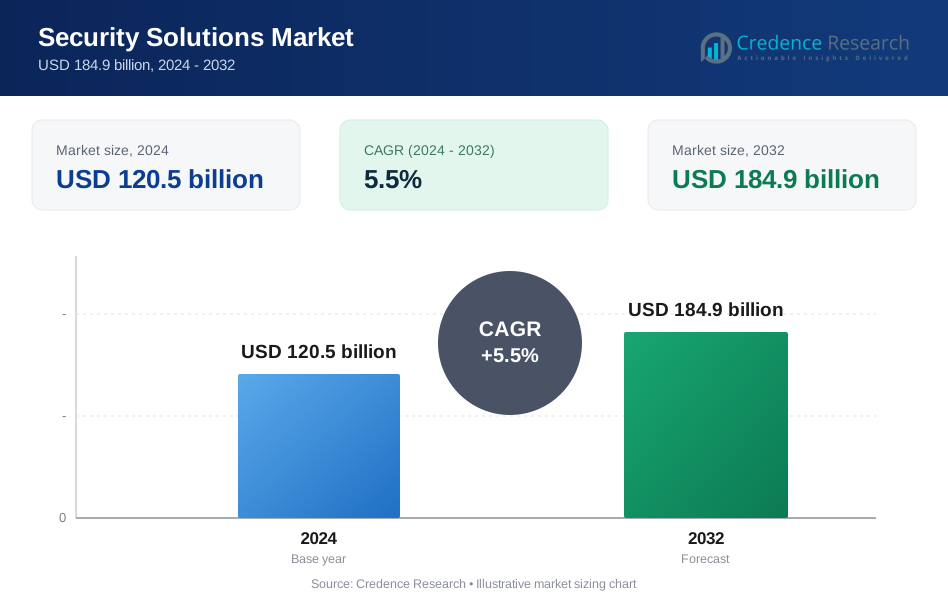
Security Solutions Market size was valued at USD 120.5 billion in 2024 and is anticipated to reach USD 184.9 billion by 2032, at a CAGR of 5.5% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Security Solutions Market Size 2024 | USD 120.5 billion |
| Security Solutions Market, CAGR | 5.5% |
| Security Solutions Market Size 2032 | USD 184.9 billion |
The Security Solutions Market grows through strong drivers such as rising demand for advanced surveillance, access control, and intrusion detection across commercial, industrial, and residential sectors. It gains momentum from smart city initiatives, regulatory compliance, and increasing focus on safeguarding digital-physical assets. Key trends include the integration of AI and predictive analytics for real-time monitoring, the rise of biometric and contactless authentication, and the shift toward cloud-based platforms that enable scalable remote management. The convergence of cybersecurity with physical systems further strengthens market adoption, while subscription-based and IoT-enabled solutions enhance accessibility and long-term growth potential.
The Security Solutions Market shows strong geographical presence with North America leading through advanced adoption, Europe focusing on regulatory-driven growth, and Asia-Pacific emerging as the fastest-growing region supported by smart city projects and industrial expansion. Latin America and the Middle East & Africa contribute steadily through infrastructure modernization and public safety initiatives. Key players such as Hikvision, Bosch Security Systems, ADT Corp., Axis Communications, Allegion, and Stanley Security Solutions drive competition through innovation, global reach, and diversified product portfolios.
[caption id="attachment_126783" align="alignnone" width="1136"] Security Solutions Market size[/caption]
Market Insights
- The Security Solutions Market was valued at USD 120.5 billion in 2024 and is projected to reach USD 184.9 billion by 2032, at a CAGR of 5.5%.
- Rising demand for advanced surveillance, access control, and intrusion detection drives adoption across commercial, residential, and industrial sectors.
- Integration of AI, predictive analytics, and biometric solutions defines key trends, along with cloud-based platforms for scalable remote management.
- Competitive landscape features global leaders focusing on innovation, diversified portfolios, and service-driven models to strengthen market reach.
- High implementation costs, regulatory complexities, and cybersecurity risks act as key restraints limiting adoption, especially for smaller enterprises.
- North America leads adoption, Europe grows through regulatory frameworks, and Asia-Pacific emerges as the fastest-growing region with strong smart city initiatives.
- Latin America and Middle East & Africa contribute steadily with infrastructure modernization, while key players shape growth through global expansion and advanced technologies.
Market Drivers
Growing Demand for Integrated Safety and Surveillance Systems
The Security Solutions Market expands with growing demand for integrated safety and surveillance systems that protect physical and digital assets. Organizations adopt advanced video surveillance, intrusion detection, and access control solutions to strengthen defense against rising security threats. It gains momentum from the integration of AI and machine learning that enables real-time monitoring and predictive analytics. Enterprises invest in intelligent cameras capable of analyzing up to 30 frames per second for enhanced accuracy in threat identification. Smart city projects and critical infrastructure modernization increase the need for centralized platforms that unify security operations. Continuous upgrades in surveillance networks create consistent adoption across industrial, commercial, and residential sectors.
- For instance, Bosch Security Systems outfitted Chiang Mai City in Thailand with over 400 security cameras, enhancing urban surveillance across key public areas to protect both residents and tourists under challenging environmental conditions.
Rising Importance of Cybersecurity Convergence with Physical Security
The Security Solutions Market benefits from the convergence of cybersecurity with physical security frameworks to address complex risks. Companies integrate biometric authentication, encrypted communication, and intrusion prevention tools into physical systems. It drives a holistic security environment where IoT-enabled devices connect with centralized command centers. Enterprises deploy multi-factor authentication, securing over 70% of enterprise access points across data-sensitive environments. Increased adoption of cloud-based surveillance platforms strengthens resilience against evolving cyber threats. Governments encourage standardized compliance frameworks that enforce digital-physical protection strategies across industries.
- For instance, a 2025 survey conducted by HID in the "State of Security and Identity" report-drawing from over 1,800 security professionals including installers, integrators, and OEMs-revealed that approximately 35 percent of respondents are currently using biometric technologies.
Expanding Role of Automation and Artificial Intelligence in Security Deployment
The Security Solutions Market advances through automation and AI that improve operational efficiency and reduce response time. Predictive threat intelligence platforms analyze large volumes of data within milliseconds to prevent breaches. It supports automated incident reporting that improves decision-making for law enforcement and enterprises. Facial recognition technologies process up to 50 million comparisons daily in high-traffic environments like airports. Robotics and unmanned aerial systems enhance perimeter security in industries such as energy and defense. Automated platforms reduce manpower dependency while ensuring high scalability in large-scale deployments.
Increasing Adoption of Cloud-Based and Remote Monitoring Solutions
The Security Solutions Market experiences strong adoption of cloud-based and remote monitoring solutions that support scalability and flexibility. Enterprises migrate security data to cloud infrastructure to achieve real-time visibility across multiple locations. It enables secure remote access where operators manage surveillance feeds through centralized dashboards. Cloud storage platforms process and archive over 1,000 terabytes of video data daily in large enterprises. The shift toward subscription-based models reduces upfront investment for organizations. Rapid urbanization and expanding enterprise networks strengthen reliance on remote monitoring for continuous operations.
Market Trends
Increasing Integration of Artificial Intelligence and Predictive Analytics
The Security Solutions Market progresses with the rising integration of artificial intelligence and predictive analytics to enhance situational awareness. Organizations deploy AI-driven video surveillance systems that detect abnormal activities with accuracy beyond manual monitoring. It leverages machine learning algorithms to identify suspicious behavior patterns and reduce false alarms. Predictive analytics tools process large datasets to anticipate potential threats before escalation. The trend strengthens the value of proactive defense measures across airports, retail spaces, and industrial facilities. AI-driven automation also improves resource allocation, reducing operational costs while increasing security efficiency.
- For instance, Ingersoll Rand rolled out its Helix™ Connected Platform across 25,000+ industrial air compressor systems in 2024, delivering real-time predictive diagnostic data and early failure alarms to maintenance teams.
Growing Preference for Biometric and Contactless Access Control Systems
The Security Solutions Market observes strong demand for biometric and contactless access control systems driven by rising concerns over identity theft and unauthorized entry. Enterprises adopt fingerprint, iris, and facial recognition technologies for seamless and secure authentication. It aligns with the need for hygienic, touchless solutions in healthcare, commercial buildings, and public facilities. Biometric platforms now support authentication speeds under one second, enabling rapid access while maintaining high accuracy. Cloud-based integration allows centralized management of user data across multiple sites. Expanding smart city projects accelerate adoption of scalable biometric infrastructures that strengthen overall security frameworks.
- For instance, Hikvision MinMoe face recognition terminals have reached sales between 2017 and 2021, equipping facilities worldwide with touch-free authentication solutions that register user identities in approximately 0.2 seconds and maintain over 99% accuracy even in low-light conditions.
Expansion of Cloud-Based Security Platforms and Remote Management
The Security Solutions Market advances through the expansion of cloud-based security platforms that offer scalability, real-time access, and cost efficiency. Enterprises migrate surveillance systems and access control networks to cloud environments to centralize data management. It allows remote monitoring across distributed facilities through secure dashboards and mobile applications. Cloud platforms enable flexible storage, supporting enterprises managing terabytes of video data daily. Subscription-based deployment models reduce upfront investment and increase accessibility for small and medium businesses. Rising digital transformation across industries reinforces adoption of cloud-native security ecosystems.
Increasing Convergence of Physical Security with Cybersecurity Strategies
The Security Solutions Market develops with growing convergence of physical security and cybersecurity strategies to address hybrid threats. Organizations integrate firewalls, intrusion detection, and endpoint protection with access control and surveillance networks. It creates a unified framework that secures both physical premises and digital assets. Multi-layered security strategies protect against ransomware attacks and unauthorized access across connected devices. Regulatory bodies emphasize compliance standards that demand integrated protection measures. Expanding IoT ecosystems amplify the importance of combined security solutions that address vulnerabilities in smart buildings and critical infrastructure.
Market Challenges Analysis
High Implementation Costs and Complexity of Advanced Security Infrastructure
The Security Solutions Market faces challenges related to the high cost and complexity of deploying advanced infrastructure across industries. Enterprises encounter significant expenses in integrating AI-driven surveillance, biometric systems, and cloud-based platforms with legacy environments. It requires substantial investment in hardware, software, and skilled professionals, which limits adoption for small and medium businesses. Complex installation and maintenance processes further slowdown deployment in sectors with limited technical expertise. High bandwidth requirements for video analytics and data-heavy applications create strain on existing networks. Organizations often struggle to balance budget constraints with the need for scalable and future-ready security solutions.
Rising Cybersecurity Threats and Regulatory Compliance Burdens
The Security Solutions Market contends with rising cybersecurity threats that increase vulnerabilities across interconnected systems. It becomes critical to protect surveillance devices, biometric databases, and cloud platforms from ransomware and data breaches. Rapid expansion of IoT ecosystems exposes more endpoints to malicious attacks, demanding continuous monitoring and software updates. Compliance with international standards such as GDPR, HIPAA, and ISO introduces complex obligations that vary across regions. Organizations face financial penalties and reputational risks if they fail to meet evolving regulatory frameworks. Limited awareness of integrated security practices in developing markets amplifies these challenges and delays widespread adoption.
Market Opportunities
Expanding Demand for Smart City Infrastructure and Connected Security Ecosystems
The Security Solutions Market presents strong opportunities through the global rise of smart city projects that integrate digital and physical security frameworks. Governments invest in large-scale surveillance, access control, and traffic monitoring systems to ensure public safety and efficiency. It creates demand for AI-driven analytics, cloud-based platforms, and IoT-enabled devices that support real-time decision-making. Vendors can leverage partnerships with municipalities to deliver scalable solutions that manage high-density urban environments. The shift toward connected infrastructure strengthens the role of integrated command centers that unify multiple security layers. Growing investments in urban modernization open new revenue streams for solution providers.
Increasing Adoption of Cloud-Based and Subscription Security Models
The Security Solutions Market gains opportunities from the rapid adoption of cloud-based security services and subscription-driven models. Enterprises seek flexible solutions that lower upfront costs while providing continuous updates and scalability. It enables organizations to secure remote facilities, manage multi-site operations, and access data through centralized dashboards. Cloud integration supports advanced storage capabilities, handling terabytes of surveillance footage with ease. The shift toward managed services strengthens opportunities for providers offering cybersecurity integration, remote monitoring, and predictive analytics. Growing interest from small and medium businesses ensures broader adoption and long-term market expansion.
Market Segmentation Analysis:
By Product
The Security Solutions Market divides into entrance control, intruder alarms, wireless systems, video surveillance, access control, thermal cameras, and others. Video surveillance leads adoption due to the demand for real-time monitoring in commercial and government facilities. It benefits from AI-enabled cameras that enhance threat detection and reduce false alerts. Access control systems gain traction in enterprises and residential complexes that prioritize identity verification and restricted entry. Thermal cameras see rising demand in healthcare and industrial environments where temperature screening supports safety compliance. Wireless systems expand adoption due to cost efficiency and easier integration with IoT devices. Entrance control solutions remain essential in transportation hubs and corporate premises to ensure regulated access.
- For instance, Godrej & Boyce’s Security Solutions division noted it had secured contracts collectively valued at over 35 crore in fiscal year 2024 for implementing integrated electronic security systems.
By Services
The Security Solutions Market segments by services into remote monitoring, fire protection, video surveillance, access control, and others. Remote monitoring services grow rapidly as enterprises seek 24/7 visibility across multiple locations through centralized command centers. It supports proactive threat detection and faster response in commercial and industrial sectors. Fire protection services remain critical for safety compliance across manufacturing, energy, and utility facilities. Video surveillance services scale with smart city projects where continuous monitoring safeguards public infrastructure. Access control services enhance operational security by managing employee and visitor entry with biometric or card-based solutions. Service providers expand managed offerings to meet evolving enterprise requirements for integrated security frameworks.
- For instance, Chubb Fire & Security (under APi Group) serves more than 1.5 million customer sites across Asia-Pacific, Canada, and Europe, reflecting its scale in offering comprehensive security services-including remote fire and alarm monitoring-for diverse facilities ranging from retail chains to institutional buildings.
By End-User
The Security Solutions Market categorizes end-users into commercial, industrial, energy and utility, transportation, retail, banking and finance, education, residential, government, and others. Commercial enterprises drive significant adoption through demand for access control, video surveillance, and remote monitoring to protect assets and personnel. It finds strong demand in industrial sectors where safety, compliance, and perimeter security are vital. Energy and utility facilities implement advanced intrusion detection and fire protection systems to safeguard critical infrastructure. Transportation hubs adopt entrance control and surveillance to manage passenger flow and ensure safety. Banking and finance prioritize biometric authentication and intrusion alarms to protect sensitive data and assets. Residential users adopt wireless and cloud-based systems for convenience and affordability, while governments deploy comprehensive frameworks to protect public infrastructure and national assets.
Segments:
Based on Product:
- Entrance Control
- Intruder Alarms
- Wireless Systems
- Video Surveillance
Based on Services:
- Remote Monitoring Services
- Fire Protection Services
- Video Surveillance Services
- Access Control Service
Based on End-User:
- Commercial
- Industrial
- Energy & Utility
- Transportation
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis
North America
North America holds the largest market share of the Security Solutions Market at 35%, driven by advanced digital infrastructure, widespread adoption of smart technologies, and strong emphasis on public safety. The region benefits from significant investments in AI-driven video surveillance, access control systems, and cloud-based monitoring solutions. It maintains a leadership position due to the presence of global technology providers and high penetration of IoT-enabled devices. The United States dominates regional growth with large-scale deployments across government, commercial, and residential sectors, supported by federal initiatives for smart city projects. Canada and Mexico contribute through steady adoption in industrial automation, critical infrastructure protection, and retail environments. Stringent regulatory frameworks, including cybersecurity and data privacy standards, reinforce the adoption of integrated security systems. Growing demand for biometric authentication and remote monitoring services strengthens the region’s role as a pioneer in advanced security solutions.
Europe
Europe accounts for 27% of the Security Solutions Market, supported by rising investment in smart infrastructure, transportation security, and compliance-driven adoption. It experiences consistent growth across Germany, the United Kingdom, France, and Italy, where governments emphasize surveillance systems to safeguard public spaces and transport hubs. The European Union’s strict regulations on data protection and safety standards promote the use of integrated security systems. It shows high adoption in industrial and energy sectors that require real-time monitoring, fire protection services, and intrusion alarms. Advanced biometric and access control systems expand rapidly in financial institutions and corporate offices. Countries in Eastern Europe adopt solutions at a growing pace, focusing on border security and critical infrastructure resilience. The region’s growing emphasis on sustainability and green infrastructure creates new opportunities for security systems that align with energy-efficient operations.
Asia-Pacific
Asia-Pacific secures 25% of the Security Solutions Market, emerging as the fastest-growing region due to rapid urbanization, expanding industrial sectors, and government-backed smart city initiatives. China leads adoption with significant investments in large-scale video surveillance projects, while Japan and South Korea prioritize high-tech biometric and thermal camera systems. India accelerates adoption across residential, retail, and banking sectors, driven by digital transformation and rising security concerns. It benefits from cost-effective wireless systems and cloud-based services that appeal to small and medium businesses. The region experiences strong growth in transportation security, particularly in metro projects, airports, and seaports. Governments actively support adoption by funding large surveillance networks to ensure public safety. Increasing investment in AI-driven analytics and IoT-based security devices strengthens Asia-Pacific’s position as a critical growth hub.
Latin America
Latin America contributes 8% to the Security Solutions Market, shaped by demand for video surveillance, access control, and intrusion detection in urban centers. Brazil and Mexico dominate adoption, supported by government initiatives to enhance safety in public areas and reduce crime rates. It faces challenges due to limited infrastructure in rural areas, yet urban growth drives investment in advanced security technologies. Retail and banking sectors prioritize security solutions to combat theft and fraud, increasing demand for biometric access systems. Industrial facilities adopt fire protection and intrusion alarms to safeguard assets. Cloud-based and subscription services gain traction as cost-effective alternatives for enterprises and residential users. Growing awareness of smart home solutions supports expansion in residential adoption across the region.
Middle East and Africa (MEA)
The Middle East and Africa hold 5% of the Security Solutions Market, driven by large-scale infrastructure development, government modernization programs, and rising awareness of security risks. The Middle East leads with investments in smart city projects across the United Arab Emirates, Saudi Arabia, and Qatar. It focuses on integrating AI-driven surveillance, thermal cameras, and access control in airports, malls, and stadiums. Africa demonstrates growing demand for wireless and cloud-based systems that provide affordable and scalable solutions for urban safety. Industrial and energy sectors prioritize intrusion alarms and fire protection to safeguard oil, gas, and utility assets. It gains support from international collaborations and public-private partnerships that accelerate adoption. Growing political and social security concerns further highlight the importance of comprehensive security frameworks in the region.
Key Player Analysis
- Axis Communications A
- Ingersoll Rand Solutions
- ADT Corp.
- Stanley Security Solutions
- Hikvision Digital Technology Co., Ltd.
- Bosch Security Systems
- com
- Godrej & Boyce Manufacturing Company Ltd.
- Allegion
- UTC Fire & Security
Competitive Analysis
The Security Solutions Market features include Hikvision Digital Technology Co., Ltd., Allegion, ADT Corp., UTC Fire & Security, Godrej & Boyce Manufacturing Company Ltd., Bosch Security Systems, Ingersoll Rand Solutions, Alarm.com, Axis Communications A, and Stanley Security Solutions. The Security Solutions Market demonstrates intense competition shaped by technological advancements, service differentiation, and expanding global demand. Companies prioritize the development of integrated platforms that combine video surveillance, access control, intrusion detection, and cloud-based monitoring. It benefits from the integration of artificial intelligence, IoT, and predictive analytics, which enhance efficiency and real-time response capabilities. Providers focus on subscription-based models, remote management services, and scalable solutions to address the needs of both enterprises and residential users. Growing emphasis on regulatory compliance, smart city projects, and cybersecurity integration further drives innovation. Competitive strategies center on expanding product portfolios, strengthening regional presence, and delivering cost-effective yet advanced solutions that cater to diverse end-user requirements.
Recent Developments
- In July 2025, CelcomDigi unveiled a new range of cybersecurity solutions designed to help Malaysian enterprises protect themselves against digital threats. The AI-driven services provided real-time protection across three key areas: Managed Security Services, Strategy and Assessment, and Infrastructure Security.
- In February 2025, Godrej Enterprises Group's Security Solutions business introduced its latest range of premium, tech-enabled home lockers. This move aimed to strengthen its portfolio and expand its market share in the security solutions. The home lockers were designed to blend effortlessly with modern home aesthetics, combining sophisticated design with advanced technology to offer both top-tier security and a touch of elegance.
- In January 2024, Novozymes and Chr. Hansen has completed their merger, resulting in the establishment of Novonesis. As a bio solutions partner, Novonesis aims to enhance business, promote healthier lives, and support a healthier planet. The combined expertise of the company spans over 30 different industries.
- In December 2023, IFF and Kemira (Finland) are collaborating to commercialize renewable polymers from IFF's Designed Enzymatic Biomaterials (DEB) technology, integrating production into Chemigate Ltd’s biorefinery in Finland by mid-2024. This innovation addresses the demand for sustainable alternatives in pulp, paper, water treatment, and other markets. By expanding DEB technology, IFF will offer high-performance, sustainable materials, enhance its enzyme industry presence and support a circular bioeconomy.
Report Coverage
The research report offers an in-depth analysis based on Product, Services, End-User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Security Solutions Market will expand with increasing adoption of AI-driven analytics across surveillance and access control.
- Cloud-based platforms will strengthen remote monitoring and multi-site management for enterprises and households.
- Integration of cybersecurity with physical systems will gain priority to counter hybrid threats.
- Demand for biometric and contactless authentication will rise in commercial, healthcare, and government sectors.
- Smart city projects will create large opportunities for unified and scalable security infrastructures.
- Subscription and managed service models will increase adoption among small and medium businesses.
- IoT-enabled devices will drive growth of connected security ecosystems across industries.
- Thermal imaging and advanced sensors will find wider use in healthcare, transportation, and critical infrastructure.
- Regulatory compliance will continue to influence investment in standardized and certified security frameworks.
- Continuous innovation in automation and predictive intelligence will shape long-term competitiveness in the market.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Integration of AI and Predictive Analytics
The adoption of artificial intelligence and predictive analytics in security solutions enables real-time monitoring, automated threat detection, and proactive incident response, significantly improving the effectiveness and efficiency of surveillance and access control systems.
Smart City Initiatives and Infrastructure Modernization
Government investments in smart city projects and modernization of critical infrastructure are driving demand for integrated security platforms that unify surveillance, access control, and emergency response across urban environments.
Convergence of Cybersecurity with Physical Security
Organizations are increasingly integrating cybersecurity measures with physical security systems, such as biometric authentication and encrypted communications, to address complex hybrid threats and comply with regulatory standards.
Growth of Cloud-Based and Subscription Security Models
The shift toward cloud-based platforms and subscription-based services is making advanced security solutions more accessible and scalable, reducing upfront costs and enabling remote management for enterprises and residential users.
Rising Demand for Biometric and Contactless Authentication
Concerns over identity theft and the need for hygienic, touchless access are accelerating the adoption of biometric and contactless authentication technologies in commercial, healthcare, and government sectors.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Security Solutions Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Security Solutions Market projected to grow between 2025 and 2032?
What are the primary factors fueling the growth of the Security Solutions Market?
Who are the leading companies in the Security Solutions Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Product
- 1.2.1 Entrance Control
- 1.2.2 Intruder Alarms
- 1.2.3 Wireless Systems
- 1.2.4 Video Surveillance
- 1.2.5 Access Control
- 1.2.6 Thermal Cameras
- 1.3 By End-User
- 1.3.1 Commercial
- 1.3.2 Industrial
- 1.3.3 Energy & Utility
- 1.3.4 Transportation
- 1.3.5 Residential
- 1.3.6 Banking and Finance
- 1.3.7 Government
- 1.4 By Services
- 1.4.1 Remote Monitoring Services
- 1.4.2 Fire Protection Services
- 1.4.3 Video Surveillance Services
- 1.4.4 Access Control Service
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 120.5 billion → 2032: USD 184.9 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Security Solutions Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Security Solutions Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Security Solutions Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Security Solutions Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Security Solutions Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Security Solutions Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 Global Security Solutions Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Security Solutions Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 120.5 billion → 2032: USD 184.9 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Security Solutions Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Product - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Entrance Control
- 12.3.7.2 Intruder Alarms
- 12.3.7.3 Wireless Systems
- 12.3.7.4 Video Surveillance
- 12.3.7.5 Access Control
- 12.3.7.6 Thermal Cameras
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By End-User - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Commercial
- 12.4.7.2 Industrial
- 12.4.7.3 Energy & Utility
- 12.4.7.4 Transportation
- 12.4.7.5 Residential
- 12.4.7.6 Banking and Finance
- 12.4.7.7 Government
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Services - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Remote Monitoring Services
- 12.5.7.2 Fire Protection Services
- 12.5.7.3 Video Surveillance Services
- 12.5.7.4 Access Control Service
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Security Solutions End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Security Solutions Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Security Solutions Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Security Solutions Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Hikvision Digital Technology Co., Ltd.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Bosch Security Systems
- 18.4 ADT Corp.
- 18.5 Axis Communications
- 18.6 Allegion
- 18.7 Stanley Security Solutions
- 18.8 Godrej & Boyce Manufacturing Company Ltd.
- 18.9 Ingersoll Rand Solutions
- 18.10 UTC Fire & Security
- 18.11 Alarm.com
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

