
Market Overview
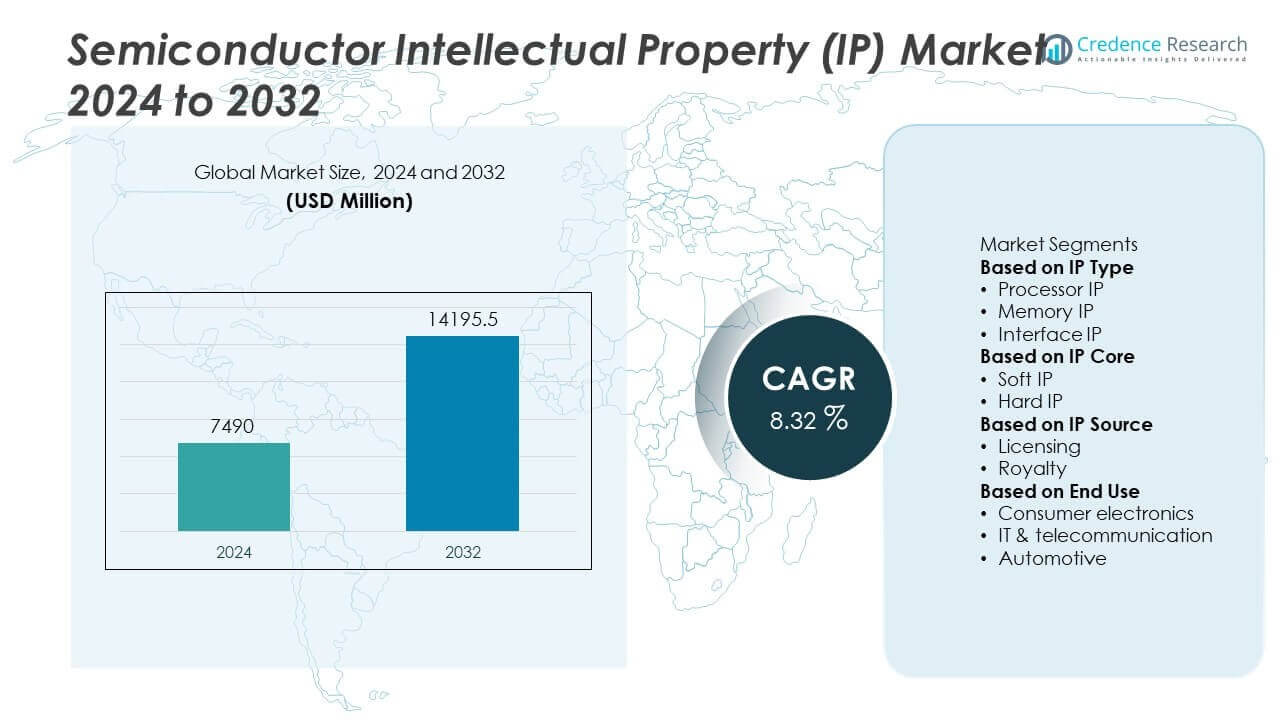
The Semiconductor Intellectual Property (IP) Market was valued at USD 7,490 million in 2024. It is expected to grow to USD 14,195.5 million by 2032, expanding at a CAGR of 8.32% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Semiconductor Intellectual Property (IP) Market Size 2024 | USD 7,490 Million |
| Semiconductor Intellectual Property (IP) Market, CAGR | 8.32% |
| Semiconductor Intellectual Property (IP) Market Size 2032 | USD 14,195.5 Million |
The Semiconductor Intellectual Property (IP) Market grows due to rising SoC complexity, shorter product cycles, and high demand for design reuse. Companies adopt licensed IP cores to reduce costs, accelerate development, and meet performance targets across AI, automotive, and IoT sectors.
Asia-Pacific leads the Semiconductor Intellectual Property (IP) Market due to its strong semiconductor manufacturing base and growing chip design capabilities. Countries like China, Taiwan, South Korea, and India drive demand across consumer electronics, automotive, and industrial applications. North America follows with major contributions from the United States, supported by innovation hubs and large R&D investments in AI and advanced node development. Europe maintains steady demand through its automotive and industrial sectors, focusing on functional safety and compliance. Latin America and the Middle East & Africa represent emerging regions with expanding infrastructure and digital adoption. Key players shaping the global market include Arm Limited, known for its processor IP leadership, Synopsys, Inc., a major provider of interface and security IP, and Cadence Design Systems, Inc., offering comprehensive IP and design tools. Other notable participants include Imagination Technologies and VeriSilicon, both contributing to GPU, multimedia, and application-specific IP innovation across global markets.
Market Insights
- The Semiconductor Intellectual Property (IP) Market was valued at USD 7,490 million in 2024 and is projected to reach USD 14,195.5 million by 2032, growing at a CAGR of 8.32%.
- Increasing SoC complexity and shorter design cycles drive demand for licensed IP cores across end-use sectors.
- Trends show rising adoption of modular IP architectures, domain-specific cores for AI, and security-focused IP in connected systems.
- Arm Limited, Synopsys, and Cadence Design Systems lead the market with strong IP portfolios for processors, interfaces, and memory.
- High integration costs and interoperability issues across advanced process nodes limit seamless IP reuse in some applications.
- Asia-Pacific leads the market due to high semiconductor production and growing local chip design activity, while North America drives innovation in AI and high-performance computing.
- Europe sees steady growth from automotive and industrial sectors, while Latin America and the Middle East & Africa offer emerging opportunities through digital transformation and smart infrastructure.
Market Drivers
Rising SoC Complexity Accelerates IP Core Adoption Across Chip Design Cycles
The growing complexity of System-on-Chip (SoC) design drives higher demand for reusable IP cores. Modern SoCs integrate CPUs, GPUs, memory interfaces, and connectivity modules on a single die. This integration requires verified IP blocks to meet performance and reliability targets. Semiconductor companies depend on third-party IPs to reduce design risks and enable quicker prototyping. It allows design teams to focus on customization and differentiation. The Semiconductor Intellectual Property (IP) Market benefits from this shift toward modular and scalable chip architectures. Pre-verified IP blocks improve time-to-market and reduce testing burdens.
- For instance, Synopsys' DesignWare ARC NPX Neural Processor IP supports significantly higher performance than 8 TOPS for vision and AI workloads, enabling real-time object detection in complex SoCs used in automotive ADAS systems. A more recent model, like the ARC NPX6 NPU IP, can deliver up to 250 TOPS in a single instance, and up to 3,500 TOPS when multiple instances are combined on a single SoC.
Surge in AI, IoT, and 5G Applications Increases Custom IP Requirements
Emerging applications in AI, IoT, and 5G demand custom and optimized semiconductor IP. These technologies require edge computing, low latency, and high throughput capabilities. Standard IPs fail to meet such tailored requirements, driving need for application-specific IP solutions. Vendors offering optimized IPs for neural networks, RF communication, and low-power processing see stronger traction. It enables device makers to deliver differentiated features and performance. The market supports these needs through scalable and configurable IP portfolios. This demand growth continues as connected devices and AI models become more advanced.
- For instance, CEVA's NeuPro-M NPU IP is a highly scalable processor designed for both classic and generative AI inference workloads in edge devices across automotive, surveillance, and other markets. A single core of the NeuPro-M can deliver a processing range from 4 to 400 TOPS, and multi-core clusters can scale to thousands of TOPS.
Rising Design Costs and Shrinking Time-to-Market Push IP Licensing
Escalating design costs at advanced nodes make IP licensing economically attractive. Foundries and fabless players face pressure to deliver faster and cheaper chip iterations. Using licensed IPs reduces verification cycles, speeds up tape-out, and ensures compliance with industry standards. It becomes vital for startups and mid-sized players lacking in-house IP development capabilities. The model also benefits large firms by lowering R&D burden. The market sees greater adoption of licensing models such as royalty-based and subscription-based IP access. It supports cost control and agility in a competitive semiconductor environment.
Growth in Automotive and Consumer Electronics Expands IP Demand
Automotive electronics require functional safety, reliability, and performance across harsh conditions. Semiconductors in ADAS, infotainment, and EV systems need specialized IP cores. Consumer electronics demand multimedia, connectivity, and power efficiency through ready-to-integrate IP blocks. It helps OEMs accelerate innovation and manage component interoperability. The Semiconductor Intellectual Property (IP) Market leverages demand from both sectors to diversify revenue streams. IP providers continue to expand their portfolios to serve these high-volume and performance-sensitive applications.
Market Trends
Shift Toward Design Reuse and Modular IP Architectures Becomes Mainstream
Design reuse has become a core strategy across semiconductor product cycles. Companies increasingly adopt modular IP architectures to improve scalability, reduce errors, and shorten design time. Reusable IP cores lower development costs and enable faster integration across multiple chip generations. It supports flexibility in adding new features without changing the base architecture. This trend strengthens the role of IP vendors that offer configurable and silicon-proven blocks. The Semiconductor Intellectual Property (IP) Market aligns with this shift by delivering modular solutions that support various applications. This evolution enhances time efficiency and ensures predictable design outcomes.
- For instance, Cadence's Tensilica Fusion G3 DSP is a configurable and extensible multi-purpose DSP core. It enables reuse across audio, radar, and AI signal processing subsystems, allowing designers to integrate the same IP core across multiple SoCs. A 2016 benchmark showed the G3 was approximately 5.3 times faster than a competitor's DSP on one specific task, but this is not a universal TOPS rating.
Open-Source Hardware Gains Momentum in IP Development Ecosystem
Open-source hardware is gaining attention as companies seek collaborative development and lower licensing costs. RISC-V is a key example, offering an open instruction set architecture used in processors, AI chips, and microcontrollers. Startups and research institutes benefit from reduced entry barriers and strong community support. It pushes traditional IP vendors to innovate and improve proprietary offerings. The market sees a balance between open IP and secure, optimized commercial solutions. The trend drives adoption in academic, industrial, and government projects where flexibility and transparency are priorities. Open hardware expands access while reshaping commercial IP strategies.
- For instance, Imagination Technologies did launch RISC-V-based Catapult CPUs for edge-AI and microcontrollers in December 2021. However, the company exited the standalone RISC-V CPU business in January 2025 to focus on its GPU and AI products.
Growing Integration of Security IP in Connected Devices and Edge Systems
Rising cyber threats and growing device connectivity drive demand for embedded security IP. Industries focus on securing firmware, hardware root of trust, and encryption features in the design phase. It ensures compliance with safety and privacy standards across critical sectors like automotive, healthcare, and IoT. Vendors integrate tamper detection, secure boot, and authentication modules into IP libraries. The market reflects this trend by expanding security-focused portfolios and offering turnkey compliance support. The Semiconductor Intellectual Property (IP) Market plays a vital role in enabling trust in connected systems. Security IP becomes essential rather than optional in design flows.
AI and ML Workloads Drive Demand for Domain-Specific IP Cores
AI and machine learning models require fast, efficient processing across edge and data center environments. This trend fuels growth in domain-specific IP cores designed for parallel computation, memory access, and acceleration. Chipmakers seek IP blocks optimized for convolution, vector processing, and model inference. It helps reduce power use and boost performance in real-time applications. IP vendors develop cores tailored for AI frameworks and software stacks. The market supports this trend through continuous R&D and close collaboration with AI solution providers. The Semiconductor Intellectual Property (IP) Market evolves to serve new workloads that demand precision and speed.
Market Challenges Analysis
Rising IP Infringement and Licensing Disputes Increase Legal and Operational Risks
The global expansion of semiconductor design has led to a surge in IP infringement cases. Unauthorized use, duplication, or modification of IP cores creates legal complexities and slows development timelines. Smaller firms struggle to protect their designs in regions with weak enforcement. Cross-border disputes delay product launches and increase legal spending for both licensors and licensees. The Semiconductor Intellectual Property (IP) Market must address these risks through stronger licensing frameworks and compliance tools. It requires ongoing investment in digital rights management and monitoring systems to safeguard innovation. Disputes over ownership and royalty terms also complicate partnerships and joint development.
Complex Integration of IP Cores Across Advanced Nodes Creates Validation Bottlenecks
Shrinking process nodes demand precise integration and verification of IP blocks to meet performance targets. As designs move below 5nm, timing closure, power optimization, and signal integrity grow more difficult. Variations in foundry standards and EDA tools often affect IP interoperability. This creates challenges in reuse, especially for analog and mixed-signal IPs. It forces vendors to provide extensive support during customization and post-silicon validation. The Semiconductor Intellectual Property (IP) Market faces delays when IP cores fail to meet new design rule requirements. Solving these challenges requires deeper collaboration among IP providers, foundries, and EDA vendors.
Market Opportunities
Emerging Demand in Edge AI and Wearable Devices Expands IP Scope
Edge AI and wearable devices present strong opportunities for specialized IP development. These applications require low-power, high-efficiency cores that support real-time processing and compact designs. IP vendors can create value by offering configurable, lightweight cores for vision, audio, and biometric processing. The Semiconductor Intellectual Property (IP) Market supports innovation in these segments by enabling rapid prototyping and flexible integration. It opens pathways for growth in consumer electronics, smart health, and industrial IoT. Vendors that deliver optimized IP for low-latency and low-energy use cases can capture new design wins. This shift helps IP providers enter untapped, fast-growing device categories.
Automotive and Industrial Digitalization Fuels Long-Term IP Licensing Demand
The automotive sector’s move toward electrification, automation, and connectivity creates strong demand for domain-specific IP. Industrial digitalization also drives adoption of advanced semiconductors with embedded security, safety, and communication capabilities. IP vendors that provide ASIL-certified cores, functional safety modules, and robust analog IP see stronger traction. The Semiconductor Intellectual Property (IP) Market aligns with this trend by delivering IP portfolios that meet stringent compliance and reliability standards. It enables OEMs and Tier 1 suppliers to reduce development risks and accelerate product launches. This opportunity spans infotainment, EV control systems, and industrial automation platforms. Demand continues to rise with increasing deployment of intelligent systems.
Market Segmentation Analysis:
By IP Type
The market is segmented into processor IP, interface IP, memory IP, and others. Processor IP holds a major share due to strong demand from consumer electronics, smartphones, and automotive segments. It supports integration of CPUs, GPUs, and AI accelerators into SoCs. Interface IP sees rising adoption driven by high-speed protocols like PCIe, USB, HDMI, and MIPI. Memory IP supports SRAM, DRAM controllers, and non-volatile memory blocks across embedded systems. Each type serves a critical role in performance, power efficiency, and system compatibility. The Semiconductor Intellectual Property (IP) Market benefits from this diversified demand across IP categories.
- For instance, Synopsys’ DesignWare Interface IP portfolio includes PCIe 6.0 controller IP operating at 64 GT/s per lane, enabling efficient data throughput in AI and networking SoCs.
By IP Core
IP cores are classified into soft cores, firm cores, and hard cores. Soft cores offer flexibility in synthesis and targeting across various foundries, making them suitable for FPGAs and early prototyping. Hard cores provide fixed layouts optimized for power and performance, ideal for production at advanced nodes. Firm cores balance flexibility and predictability, allowing customization with moderate design effort. Demand for hard IP cores grows in high-performance computing and automotive safety applications. Soft IP continues to dominate in AI, IoT, and academic use cases. It reflects how IP selection aligns with development goals and fabrication constraints.
- For instance, The Arm Cortex-A720 core was announced in 2023 for flagship mobile and automotive designs. However, it provides up to 20% better power efficiency over its predecessor, the Cortex-A715, not a 25% performance increase. The core's focus was on improving efficiency for sustained high performance, with a much smaller performance uplift.
By IP Source
The market divides IP sources into licensing from third-party vendors and internal or in-house developed IP. Third-party licensing remains dominant due to time savings, design validation, and broad support from EDA tool vendors. Companies rely on external IPs to meet design targets quickly and reduce in-house engineering workload. In-house IP development holds relevance for firms with large R&D budgets or proprietary architecture requirements. It allows better control over design, security, and optimization. The Semiconductor Intellectual Property (IP) Market reflects a hybrid sourcing model where firms blend third-party IPs with internal assets to maximize performance and cost efficiency.
Segments:
Based on IP Type
- Processor IP
- Memory IP
- Interface IP
Based on IP Core
- Soft IP
- Hard IP
Based on IP Source
- Licensing
- Royalty
Based on End Use
- Consumer electronics
- IT & telecommunication
- Automotive
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis
North America
North America accounts for approximately 31% of the global Semiconductor Intellectual Property (IP) Market. The United States leads the region, backed by strong R&D investment, large semiconductor players, and a well-developed design ecosystem. Companies in this region actively license processor, interface, and memory IP to accelerate SoC development. Growth is also supported by demand from AI, cloud computing, defense, and automotive sectors. Licensing models are mature, with established players driving consistent adoption. It continues to focus on advanced node development, IP verification, and system integration. North America remains a vital region for innovation-led IP growth.
Asia-Pacific
Asia-Pacific holds the largest share of the global market, contributing more than 34%. Countries like China, Taiwan, South Korea, and Japan drive this growth through robust semiconductor manufacturing and increasing chip design capabilities. The region benefits from strong electronics demand, government support, and rapid expansion in consumer and automotive electronics. China remains a dominant force due to its investments in domestic chip design and IP independence. India shows rising activity through design services and startups, creating more demand for licensed IP cores. The Semiconductor Intellectual Property (IP) Market grows here due to flexible licensing needs, faster product cycles, and scaling of AI, IoT, and 5G. Asia-Pacific will likely sustain its lead through high-volume chip design and manufacturing expansion.
Europe
Europe holds close to 22% of the global market share. The region’s strength lies in its automotive and industrial base, where safety-critical and energy-efficient semiconductors require verified and compliant IP. Countries like Germany, France, and the UK support innovation in electric vehicles, industrial automation, and IoT infrastructure. Demand for functional safety IP, RF interfaces, and analog cores remains high. Firms seek reliable IP for compliance with strict regulatory standards. The region balances in-house IP development with third-party licensing. Growth is steady, fueled by digital transformation and mobility innovation across the continent.
Latin America
Latin America contributes around 7.4% to the global Semiconductor IP market. Brazil and Mexico are key contributors, supported by electronics manufacturing and telecom growth. Demand for IP rises in smartphones, set-top boxes, and smart appliances. Cost-effective and validated IP cores find demand among regional OEMs and integrators. Growth potential remains high in consumer electronics and industrial automation. Regional adoption is limited compared to Asia or North America but shows promise through infrastructure modernization and digital device proliferation.
Middle East & Africa
The Middle East & Africa region accounts for approximately 5% of the total market. Countries in the Gulf Cooperation Council and parts of Africa are exploring IP-based solutions for telecom, healthcare, and industrial sectors. Governments promote digital transformation through smart cities and industrial hubs. Demand exists for secure, energy-efficient IP cores suited for local infrastructure needs. The market remains early-stage, but opportunities grow with expanding internet penetration and regional design activity. Vendors entering early may gain first-mover advantage in tailored IP offerings.
Key Player Analysis
- VeriSilicon
- CEVA, Inc.
- Synopsys, Inc.
- Achronix Semiconductor Corporation
- eMemory Technology Inc.
- Rambus
- Imagination Technologies
- Lattice Semiconductor
- Cadence Design Systems, Inc.
- Arm Limited
Competitive Analysis
The competitive analysis of the Semiconductor Intellectual Property (IP) Market highlights key players including Arm Limited, Synopsys, Inc., Cadence Design Systems, Inc., Imagination Technologies, CEVA, Inc., Lattice Semiconductor, Rambus, eMemory Technology Inc., VeriSilicon, and Achronix Semiconductor Corporation. These companies compete on the basis of portfolio breadth, IP quality, silicon validation, and support for emerging technologies. Processor, interface, and memory IP remain core focus areas, while demand grows for AI-optimized, low-power, and security-integrated cores. Leading firms leverage strategic acquisitions, licensing agreements, and R&D investments to strengthen market presence and address evolving design needs. Integration with advanced EDA tools and compatibility across multiple foundry processes serve as key differentiators. Competitive pressure increases as open-source hardware and regional IP providers expand, challenging established players to maintain innovation pace and customer engagement. Flexibility, compliance readiness, and proven performance continue to shape long-term positioning across global applications.
Recent Developments
- In August 2025, CEVA, Inc. surpassed 20 billion Ceva-powered devices shipped globally, highlighting its dominance in smart edge IP and fueling ongoing innovation in AIoT, automotive, and mobile markets.
- In June 2025, VeriSilicon launched high-performance, scalable GPGPU-AI computing IP tailored for automotive and edge server AI applications.
- In June 2025, VeriSilicon also introduced an ultra‑low‑energy Neural Network Processing Unit (NPU) IP delivering over 40 TOPS for large language model inference on mobile devices.
- In April 2025, Cadence Design Systems, Inc. signed a definitive agreement to acquire Arm’s Artisan foundation IP business, including standard cell libraries and memory compilers for advanced process nodes.
Report Coverage
The research report offers an in-depth analysis based on IP Type, IP Core, IP Source, End Use and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will continue to grow steadily, supported by rising semiconductor demand across sectors.
- Processor IP designs will remain in high demand due to their flexibility and broad use cases.
- Adoption of soft-core IP will increase, offering easier integration across multiple foundry platforms.
- Royalty-based licensing models will dominate, offering scalable revenue for IP vendors.
- Specialized IP for AI, automotive, 5G, and IoT will drive next-phase growth.
- Asia-Pacific will maintain its lead due to strong chip production and expanding design hubs.
- North America will stay competitive through innovation, R&D strength, and ecosystem maturity.
- Demand for IP supporting sub-5nm nodes and integration with advanced EDA tools will rise.
- Open-source IP initiatives will gain traction, encouraging broader collaboration and access.
- New applications in industrial automation, smart healthcare, and edge AI will open fresh IP opportunities.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising SoC Complexity
The increasing complexity of System-on-Chip (SoC) designs is driving demand for reusable, pre-verified IP cores, enabling faster prototyping, reduced design risk, and quicker time-to-market for semiconductor companies.
Surge in AI, IoT, and 5G Applications
Emerging applications in AI, IoT, and 5G require custom and optimized semiconductor IP, pushing vendors to develop domain-specific cores that deliver high performance, low latency, and energy efficiency for next-generation devices.
Escalating Design Costs and Shrinking Time-to-Market
Advanced process nodes have made chip design more expensive and time-sensitive, making IP licensing an attractive option for both startups and established players to reduce R&D costs, accelerate development, and ensure compliance with industry standards.
Growth in Automotive and Consumer Electronics
The proliferation of electronics in automotive and consumer sectors is expanding demand for specialized IP cores that deliver functional safety, multimedia capabilities, and connectivity, supporting innovation and interoperability in high-volume applications.
Adoption of Modular and Reusable IP Architectures
The industry-wide shift toward modular and reusable IP architectures is enabling companies to scale designs efficiently, reduce errors, and integrate new features rapidly, further fueling the adoption of licensed semiconductor IP.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Semiconductor Intellectual Property (IP), and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Semiconductor Intellectual Property (IP) market projected to grow between 2025 and 2032?
Which Semiconductor Intellectual Property (IP) market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Semiconductor Intellectual Property (IP) market?
Who are the leading companies in the Semiconductor Intellectual Property (IP) market?
Which region commanded the largest share of the Semiconductor Intellectual Property (IP) market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End Use
- 1.2.1 Consumer electronics
- 1.2.2 IT & telecommunication
- 1.2.3 Automotive
- 1.3 By IP Core
- 1.3.1 Soft IP
- 1.3.2 Hard IP
- 1.4 By IP Type
- 1.4.1 Processor IP
- 1.4.2 Memory IP
- 1.4.3 Interface IP
- 1.5 By IP Source
- 1.5.1 Licensing
- 1.5.2 Royalty
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 7,490 million → 2032: USD 14,195.5 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Semiconductor Intellectual Property Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Semiconductor Intellectual Property Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Semiconductor Intellectual Property Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Semiconductor Intellectual Property Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Semiconductor Intellectual Property Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Semiconductor Intellectual Property Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Semiconductor Intellectual Property Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Semiconductor Intellectual Property Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 7,490 million → 2032: USD 14,195.5 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Semiconductor Intellectual Property Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End Use - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Consumer electronics
- 12.3.7.2 IT & telecommunication
- 12.3.7.3 Automotive
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By IP Core - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Soft IP
- 12.4.7.2 Hard IP
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By IP Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Processor IP
- 12.5.7.2 Memory IP
- 12.5.7.3 Interface IP
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By IP Source - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Licensing
- 12.6.7.2 Royalty
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Semiconductor Intellectual Property End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Semiconductor Intellectual Property Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Semiconductor Intellectual Property Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Semiconductor Intellectual Property Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Arm Limited
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Synopsys, Inc.
- 18.4 Cadence Design Systems, Inc.
- 18.5 Imagination Technologies
- 18.6 CEVA, Inc.
- 18.7 VeriSilicon
- 18.8 Lattice Semiconductor
- 18.9 Rambus
- 18.10 eMemory Technology Inc.
- 18.11 Achronix Semiconductor Corporation
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

