
Market Overview:
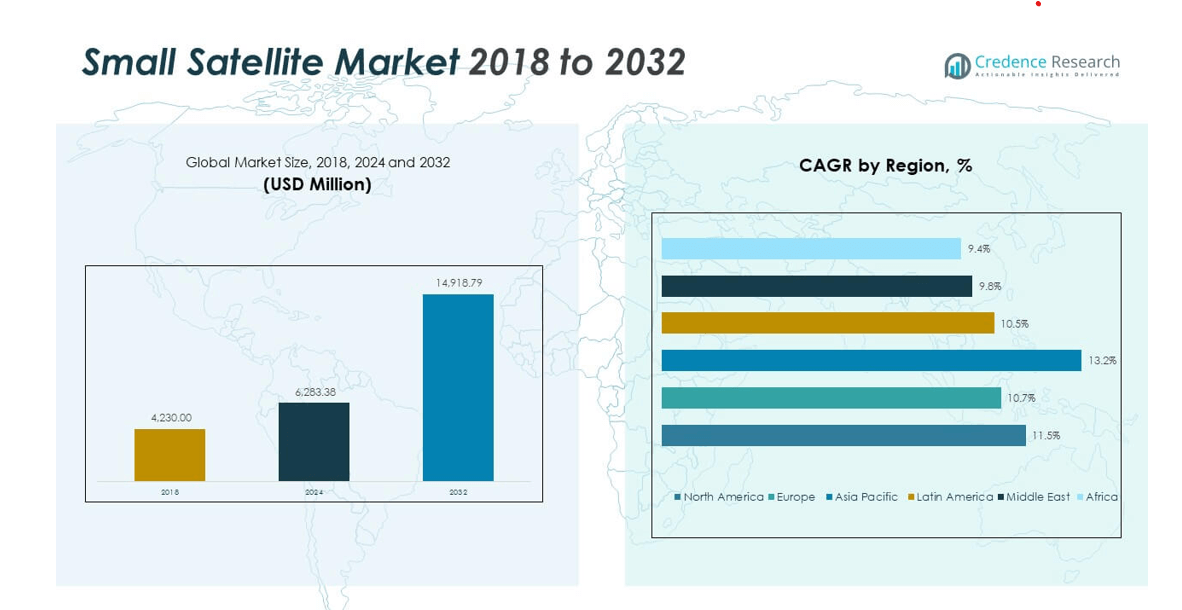
The Global Small Satellite Market size was valued at USD 4,230.00 million in 2018 to USD 6,283.38 million in 2024 and is anticipated to reach USD 14,918.79 million by 2032, at a CAGR of 11.47% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Small Satellite Market Size 2024 | USD 6,283.38 million |
| Small Satellite Market, CAGR | 11.47% |
| Small Satellite Market Size 2032 | USD 14,918.79 million |
Rising demand for low-cost, high-performance satellite systems is driving market expansion. Advancements in miniaturization, reusable launch vehicles, and AI-driven satellite control are enhancing deployment efficiency. Growing applications in Earth observation, communication, and navigation across defense, agriculture, and environmental monitoring sectors further support growth. Investments from private players and government agencies are accelerating satellite launches and fostering innovation.
North America leads the Global Small Satellite Market due to strong space infrastructure and key industry players. Europe follows with increased investments in commercial satellite projects and space exploration programs. Asia-Pacific is emerging rapidly, driven by government initiatives in India, China, and Japan. Latin America and the Middle East show growing participation through small-scale satellite programs supporting communication and weather forecasting.
Market Insights:
- The Global Small Satellite Market was valued at USD 4,230.00 million in 2018, reached USD 6,283.38 million in 2024, and is projected to attain USD 14,918.79 million by 2032, registering a CAGR of 11.47% during the forecast period.
- North America leads with a 42% market share due to strong aerospace infrastructure, major OEMs, and government-backed satellite programs. Europe follows with a 25% share driven by ESA-led missions, while Asia Pacific holds 22% supported by active participation from China, Japan, and India.
- Asia Pacific is the fastest-growing region, expanding at a 13.2% CAGR, supported by government investments in national space programs, commercial satellite launches, and increasing private-sector participation in communication and Earth observation.
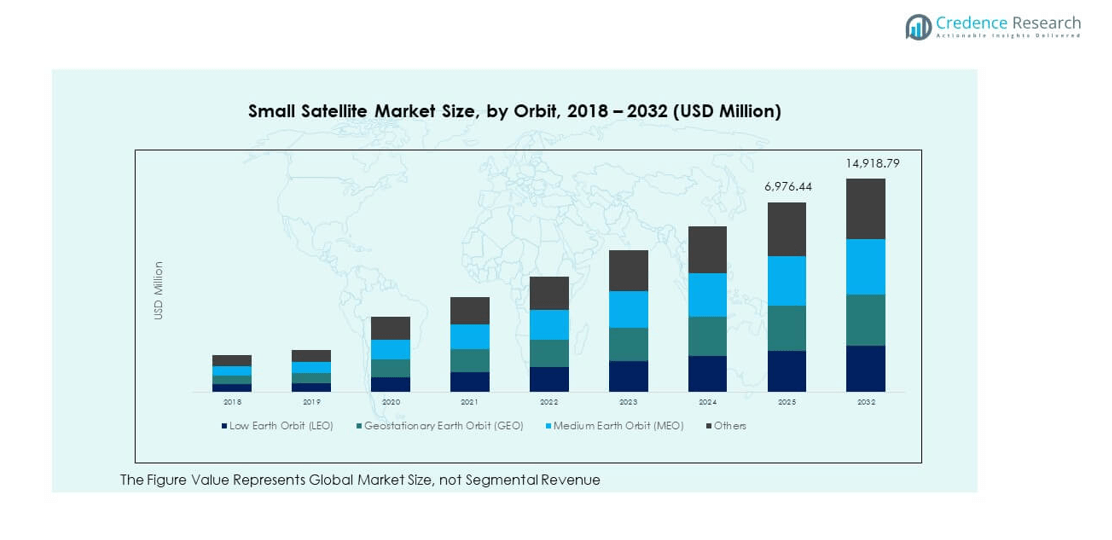
- By orbit, Low Earth Orbit (LEO) accounts for over 55% of total market share, dominating due to its suitability for communication constellations and Earth observation applications.
- Medium Earth Orbit (MEO) and Geostationary Earth Orbit (GEO) collectively represent around 35%, serving navigation, weather, and defense missions, while other orbital categories maintain niche roles in experimental and research-focused deployments.
Market Drivers:
Growing Demand for Affordable Satellite Deployment
The Global Small Satellite Market is driven by the rising need for cost-effective satellite solutions that support rapid deployment and low launch costs. Miniaturized designs allow multiple satellites to be launched together, reducing mission expenses and improving efficiency. Organizations prefer small satellites for Earth observation, communication, and scientific research due to their shorter development cycles. Startups and private players are increasingly investing in these systems. Governments are supporting satellite launches for defense and civilian use. This trend creates a competitive ecosystem that encourages innovation and scalability across the satellite value chain.
- For instance, Airbus SE’s CO3D constellation—developed with CNES—comprises four compact satellites, each weighing around 285–300 kg, equipped with 100% electric propulsion and Anywaves S‑band antennas operating above 265 MHz bandwidth. These satellites generate 50 cm spatial resolution imagery and 10 Gbps laser communication throughput, capable of producing 25 million km² of 3D digital surface models annually, showcasing the efficiency of miniaturized Earth-observation platforms.
Expansion of Commercial Space Activities and Private Investment
Private sector participation continues to transform the small satellite landscape. Companies are investing in reusable launch vehicles and shared launch services to meet commercial demands. Venture funding supports new entrants focusing on satellite manufacturing, data analytics, and communication services. The Global Small Satellite Market benefits from collaboration between startups, universities, and established aerospace firms. Such partnerships accelerate R&D and enable affordable access to space. The commercialization of space-based services expands opportunities in weather monitoring, disaster management, and broadband connectivity.
- For instance, Exolaunch deployed 34 satellites with a combined payload mass exceeding 1,500 kg during the SpaceX Transporter‑12 mission in January 2025, using its EXOpod Nova deployers and CarboNIX ring separators for precise orbital insertion. This success demonstrated high‑throughput deployment capability while reducing integration turnaround by 40%, proving the growing role of agile private launch integration providers.
Rising Adoption in Defense, Communication, and Remote Sensing
Defense and intelligence agencies are adopting small satellites for surveillance, navigation, and secure communication. These systems enhance situational awareness and offer real-time data transmission across missions. The Global Small Satellite Market is gaining traction due to increased military modernization programs. Remote sensing applications also drive demand, providing high-resolution imagery for agriculture, urban planning, and environmental protection. The ability to collect frequent, accurate data strengthens national security and commercial operations. Emerging economies are integrating small satellites into strategic defense frameworks to strengthen border and maritime monitoring.
Advancements in Satellite Design and Launch Technologies
Ongoing technological progress supports miniaturization, higher payload efficiency, and extended lifespan of small satellites. Innovations in propulsion, onboard computing, and power systems enable better performance at lower costs. The Global Small Satellite Market benefits from reusable launch technologies and modular satellite architectures. Companies are introducing flexible platforms that support multiple missions. Enhanced data transmission speed and improved interoperability also contribute to greater adoption. Research on AI integration and autonomous satellite management further improves performance reliability and operational efficiency.
Market Trends:
Growing Integration of Artificial Intelligence and Automation
AI-driven automation is transforming satellite data processing and mission management. The Global Small Satellite Market is seeing rapid integration of AI for autonomous navigation, real-time data analytics, and fault detection. Automated systems reduce human intervention, improving accuracy and mission safety. AI enhances image recognition and weather prediction capabilities for industries relying on satellite insights. Machine learning tools help optimize satellite positioning and resource utilization. This shift enables faster decision-making, lower costs, and improved mission outcomes.
Increased Focus on Constellation-Based Satellite Networks
Satellite constellations are becoming central to communication and Earth observation services. The Global Small Satellite Market benefits from the deployment of multiple interconnected satellites operating in low Earth orbit. Constellations offer continuous global coverage and reduce latency for broadband and IoT applications. Companies like SpaceX and OneWeb are expanding constellation projects to deliver high-speed internet to remote regions. Governments are also supporting constellation missions to improve connectivity. The trend supports scalable network solutions and drives infrastructure investment in satellite ground systems.
- For instance, AST SpaceMobile’s next‑generation BlueBird satellites feature 2,400‑sq‑ft phased array antennas providing up to 120 Mbps of broadband capacity per cell and servicing as many as 2,000 simultaneous connections per spacecraft. This architecture enables direct‑to‑smartphone connectivity leveraging 3GPP standards and low Earth orbit latency to under 40 milliseconds, marking a breakthrough in space‑based mobile networks .
Expansion of Small Satellite Applications in Commercial Sectors
Commercial industries are using small satellites for logistics tracking, asset monitoring, and environmental observation. The Global Small Satellite Market is witnessing greater participation from energy, agriculture, and maritime sectors. These satellites enable real-time data transmission that improves operational efficiency. Businesses adopt small satellites for crop yield forecasting, offshore monitoring, and transportation management. Increased collaboration between tech firms and satellite operators fuels new data service models. This growing commercial utility strengthens revenue diversification across satellite operators and manufacturers.
Emergence of International Collaborations and Government Initiatives
Global cooperation among countries supports shared missions, technology transfer, and joint research programs. The Global Small Satellite Market benefits from coordinated space policies and funding programs. Governments are partnering with private entities for satellite manufacturing and deployment. International alliances promote standardization, reduce costs, and enable access to shared launch infrastructure. This collaborative approach encourages developing nations to build space capabilities. The growing number of cooperative missions enhances knowledge exchange and supports sustainable growth of the small satellite ecosystem.
Market Challenges Analysis:
Regulatory Barriers and Spectrum Management Issues
Regulatory complexities remain a major obstacle for market participants. The Global Small Satellite Market faces challenges related to spectrum allocation, orbital congestion, and licensing. Multiple countries maintain differing space laws, leading to compliance delays and operational risks. Spectrum interference among satellites can impact communication reliability and data accuracy. The growing number of satellite constellations increases the risk of orbital debris. Governments are tightening regulatory frameworks to ensure sustainable space operations. These evolving regulations require companies to adapt quickly to avoid project delays and financial losses.
High Launch Costs and Limited Access to Infrastructure
Despite advances in reusable rockets, launch expenses remain high for small satellite operators. The Global Small Satellite Market still depends on shared launch platforms, which limit scheduling flexibility. Smaller firms face competition for launch slots and payload integration opportunities. Delays in manufacturing and launch readiness further strain project timelines. Limited availability of ground stations and testing facilities also restricts capacity expansion. Companies must invest in in-house infrastructure or partner with larger players to ensure mission success. Such constraints can slow market adoption in developing regions.
Market Opportunities:
Rising Demand for Broadband and IoT Connectivity
The demand for reliable broadband and IoT connectivity across remote areas is creating new prospects. The Global Small Satellite Market is positioned to support global communication coverage through low Earth orbit constellations. Telecom operators are leveraging small satellites to expand service reach in underserved regions. The integration of satellite data with terrestrial networks strengthens connectivity for industries and consumers. Growing interest from logistics, defense, and agriculture sectors enhances investment opportunities for satellite developers.
Expanding Research and Academic Participation
Universities and research institutions are actively contributing to innovation in small satellite development. The Global Small Satellite Market benefits from academic collaborations that focus on advanced materials, propulsion, and communication systems. Educational programs promote low-cost satellite missions and encourage local manufacturing ecosystems. These initiatives help build technical expertise and reduce entry barriers for emerging space economies. Increasing government funding for student-led space projects further supports future market expansion.
Market Segmentation Analysis:
By Subsystem
The Global Small Satellite Market is segmented by subsystem into satellite bus, payload, solar panel, satellite antenna, and others. The satellite bus dominates due to its critical role in supporting power, structure, and thermal control. Payloads are gaining importance as demand for high-resolution imaging and communication grows. Solar panels contribute to improving energy efficiency and satellite endurance, while antennas ensure robust data transmission. Continuous innovations in miniaturized subsystems are enhancing satellite performance and reducing launch costs.
- Forinstance, Lockheed Martin’s LM 400 platform provides payload capacity up to 1,500 kg and 14 kW of power generation within a 2‑meter bus frame, allowing support for communications, Earth observation, and defense payloads on a scalable architecture. These subsystems improve mission lifespan through high‑density batteries and radiation‑hardened electronics, enabling reliable multi‑year LEO operations .
By Application
The application segment includes communication, Earth observation and remote sensing, scientific research, education, technology, and others. Communication leads the segment due to the rising need for global connectivity and broadband coverage. Earth observation and remote sensing are expanding rapidly for climate monitoring, agriculture, and defense applications. Scientific research and educational missions drive innovation in experimental satellite projects.
- For instance, Planet Labs’ Pelican constellation captures imagery at 0.3‑meter resolution from 475 km orbit, improving data latency to within 2–4 hours post‑capture through AI‑enabled ground processing. Each Pelican satellite weighs about 120 kg and generates 600 W of solar power, providing rapid revisit rates for agriculture, climate monitoring, and defense applications .
By Mass and Frequency
The market by mass covers small, mini, micro, nano, and CubeSat satellites. CubeSats and nanosatellites dominate due to affordability and versatility. By frequency, the segmentation includes L, S, C, X, Ku, Ka, Q/V, HF/VHF/UHF, and Laser/Optical bands. The Ku and Ka bands lead due to their strong performance in high-speed communication.
By Orbit and Region
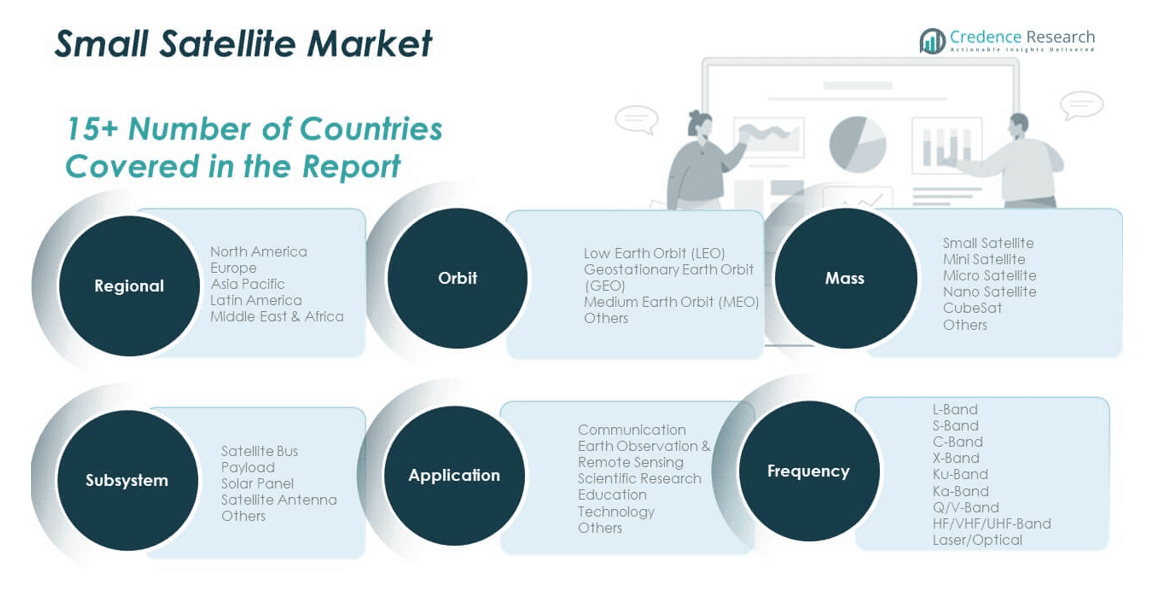
Based on orbit, low Earth orbit (LEO) dominates because of its suitability for observation and communication networks. Geostationary and medium Earth orbits serve strategic defense and telecommunication functions. Regionally, North America leads due to strong industry infrastructure, followed by Europe and Asia Pacific, which show rapid growth from government and private space initiatives.
Segmentation:
By Subsystem
- Satellite Bus
- Payload
- Solar Panel
- Satellite Antenna
- Others
By Application
- Communication
- Earth Observation & Remote Sensing
- Scientific Research
- Education
- Technology
- Others
By Mass
- Small Satellite
- Mini Satellite
- Micro Satellite
- Nano Satellite
- CubeSat
- Others
By Frequency
- L-Band
- S-Band
- C-Band
- X-Band
- Ku-Band
- Ka-Band
- Q/V-Band
- HF/VHF/UHF-Band
- Laser/Optical
By Orbit
- Low Earth Orbit (LEO)
- Geostationary Earth Orbit (GEO)
- Medium Earth Orbit (MEO)
- Others
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
The North America Global Small Satellite Market size was valued at USD 1,810.44 million in 2018 to USD 2,661.60 million in 2024 and is anticipated to reach USD 6,312.17 million by 2032, at a CAGR of 11.5% during the forecast period. North America holds a market share of 42% in the Global Small Satellite Market. The region leads due to advanced infrastructure, established aerospace companies, and strong government initiatives. The United States dominates with major players such as SpaceX, Northrop Grumman, and Lockheed Martin driving innovation. High defense spending and NASA’s commercial partnerships continue to support satellite deployment. Canada contributes through research collaborations and commercial launch services. The region’s focus on broadband connectivity, surveillance, and scientific missions enhances satellite demand. It remains a hub for technological innovation, policy development, and space commercialization.
Europe
The Europe Global Small Satellite Market size was valued at USD 1,112.49 million in 2018 to USD 1,588.27 million in 2024 and is anticipated to reach USD 3,561.90 million by 2032, at a CAGR of 10.7% during the forecast period. Europe accounts for around 25% market share of the Global Small Satellite Market. The region benefits from strong institutional support through the European Space Agency and national programs. Countries such as France, Germany, and the UK lead in R&D and manufacturing. Investments in satellite navigation, communication, and Earth observation drive growth. The region’s emphasis on environmental monitoring and security applications supports long-term demand. Private firms and startups are collaborating to enhance small satellite capabilities. Increasing integration of digital technologies and AI-based satellite control adds momentum.
Asia Pacific
The Asia Pacific Global Small Satellite Market size was valued at USD 776.63 million in 2018 to USD 1,221.78 million in 2024 and is anticipated to reach USD 3,295.57 million by 2032, at a CAGR of 13.2% during the forecast period. Asia Pacific holds about 22% share in the Global Small Satellite Market. The region shows rapid expansion driven by active participation from China, Japan, and India. National space agencies are increasing investments in satellite launch programs. Small satellites are used for communication, resource mapping, and scientific research. The rise of private aerospace companies contributes to faster innovation. Japan and India emphasize cost-efficient launches and satellite miniaturization. Southeast Asian countries are entering the market with academic and defense projects. Growing demand for digital communication and regional navigation systems fuels future growth.
Latin America
The Latin America Global Small Satellite Market size was valued at USD 275.80 million in 2018 to USD 405.84 million in 2024 and is anticipated to reach USD 896.17 million by 2032, at a CAGR of 10.5% during the forecast period. Latin America accounts for 6% of the Global Small Satellite Market share. The region is developing its space ecosystem through partnerships and government initiatives. Brazil and Argentina are leading in Earth observation and weather satellites. Regional collaborations support technological skill-building and knowledge exchange. Growth is influenced by agricultural monitoring and natural resource management needs. Universities and startups are participating in low-cost satellite missions. Access to affordable launch services enables regional expansion. Continuous policy support enhances Latin America’s role in the global space economy.
Middle East
The Middle East Global Small Satellite Market size was valued at USD 137.05 million in 2018 to USD 188.46 million in 2024 and is anticipated to reach USD 395.43 million by 2032, at a CAGR of 9.8% during the forecast period. The region represents about 3% of the Global Small Satellite Market. Growing investments in space programs across the UAE, Israel, and Saudi Arabia strengthen regional capabilities. Governments are focusing on communication, defense, and environmental monitoring missions. The UAE Space Agency and Saudi Space Commission are driving new projects. Israel contributes with advanced small satellite technologies for defense and imaging. Private participation is expanding through academic partnerships and R&D centers. Infrastructure development and technology transfers support steady growth.
Africa
The Africa Global Small Satellite Market size was valued at USD 117.59 million in 2018 to USD 217.43 million in 2024 and is anticipated to reach USD 457.55 million by 2032, at a CAGR of 9.4% during the forecast period. Africa accounts for around 2% of the Global Small Satellite Market. The region is gradually adopting space technology for communication and environmental management. South Africa and Egypt lead with established space agencies and regional projects. Countries are focusing on satellite-based services for agriculture, disaster response, and education. International collaborations provide training and technical support. Growing digitalization and demand for connectivity are stimulating investments. Limited infrastructure remains a challenge, but policy reforms aim to attract private investment. Africa’s emerging market potential is gaining attention from global satellite manufacturers.
Key Player Analysis:
- Airbus SE (Netherlands)
- SpaceMobile
- Exolaunch
- Boeing Co. (US)
- Lockheed Martin Corporation (US)
- Northrop Grumman Corporation (US)
- Planet Labs Inc. (US)
- Spire Global Inc. (US)
- Thales Alenia Space (France)
- Ball Corporation (US)
- Sierra Nevada Corporation (US)
- Maxar Technologies Inc. (Canada)
- GomSpace Group AB (Denmark)
- OneWeb Satellites (US)
- Kepler Communications (Canada)
- OHB SE (Germany)
- Axelspace Corporation (Japan)
Competitive Analysis:
The Global Small Satellite Market is highly competitive, with established aerospace leaders and emerging private firms driving innovation. It is characterized by strong investments in R&D, partnerships, and satellite miniaturization technologies. Companies focus on improving launch efficiency, payload capacity, and communication performance. Leading players such as Airbus SE, Lockheed Martin, and Northrop Grumman dominate through technological expertise and government collaborations. Startups and universities are entering the market through low-cost mission designs. Continuous innovation, faster production cycles, and reusable launch solutions define the current competitive environment.
Recent Developments:
- In October 2025, AST SpaceMobile announced a definitive commercial agreement with Verizon to launch direct-to-cell satellite services for Verizon customers beginning in 2026. This partnership will integrate AST’s space-based broadband technology with Verizon’s terrestrial network, enabling conventional smartphones to connect directly to satellites without specialized equipment. The collaboration marks a significant expansion of AST SpaceMobile’s connectivity offerings and follows earlier trials involving video calls and RCS messaging, representing a major milestone toward nationwide satellite-enabled mobile coverage in the U.S..
- In July 2025, Exolaunch GmbH entered a five-year strategic partnership with the UK-based Orbex to deliver integrated launch services for small satellites. The collaboration covers Orbex’s Prime and Proxima launch vehicles and leverages Exolaunch’s proven satellite deployment systems. Through this partnership, Exolaunch will manage end-to-end payload integration and utilize its EXOtube modular launch platform to optimize satellite constellation deployment. Additionally, Exolaunch opened new hubs in Toulouse and Tokyo in 2025 and secured multiyear launch contracts with SpaceX through 2028, reflecting its global expansion and leadership in satellite deployment operations.
- In July 2025, Boeing Co. secured a substantial $2.8 billion contract from the U.S. Space Force to develop the next generation of secure military satellites under the Evolved Strategic Satellite (ESS) communications program. The satellites will provide jam-resistant communication capabilities supporting U.S. nuclear command and control networks. Boeing will produce two satellites with options for two more under this $12 billion program. The ESS system will replace earlier constellations built by Lockheed Martin, demonstrating Boeing’s growing presence in secure space communications.
Report Coverage:
The research report offers an in-depth analysis based on subsystem, application, mass, frequency, orbit, and region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Increasing private investments will drive technological innovation in satellite manufacturing.
- Demand for low-cost launch services will accelerate small satellite deployment.
- Integration of AI and automation will enhance satellite monitoring and data analytics.
- LEO-based constellations will expand for communication and Earth observation services.
- Government initiatives will boost research and defense satellite missions.
- Emerging economies will increase participation through regional space programs.
- Reusable launch vehicles will lower operational costs and improve sustainability.
- Partnerships among startups and space agencies will speed up new mission launches.
- Advancements in payload design will improve efficiency and mission flexibility.
- Growing global data needs will strengthen commercial satellite applications.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth of the small satellite market?
At what Compound Annual Growth Rate is the Global Small Satellite Market projected to grow between 2025 and 2032?
What are the key drivers of growth in the small satellite market?
How are small satellites used?
Which regions are leading the small satellite market?
Why are small satellites becoming more popular?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Small Satellite Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2018; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Small Satellite Market Snapshot
- 2.1.1 Market Size – Historical (2018) & Forecast (2018-2032) (2018: USD 4,230.00 million → 2032: USD 14,918.79 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Small Satellite Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2018 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2018
- 2.3.2 Top 10 Players by Volume Share – 2018
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Small Satellite Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Small Satellite Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Small Satellite Market Drivers
- 3.3 Small Satellite Market Restraints & Challenges
- 3.4 Small Satellite Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Small Satellite Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Small Satellite Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Small Satellite category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Small Satellite Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Small Satellite Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2018)
- 5.1.2 Global Export Volume by Country (2018)
- 5.1.3 Global Import Value by Country (2018)
- 5.1.4 Global Import Volume by Country (2018)
- 5.1.5 Net Trade Balance by Country (2018)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2018)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Small Satellite market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Small Satellite Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2018
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Small Satellite Market Share Analysis – 2018
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2018)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Small Satellite Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Small Satellite (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Small Satellite Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Small Satellite Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2018 & 2032)
- 7.1.2 Channel Mix Evolution (2018-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Small Satellite Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Small Satellite Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Small Satellite Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Small Satellite Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Small Satellite Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Small Satellite Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Small Satellite Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
