
Market Overview
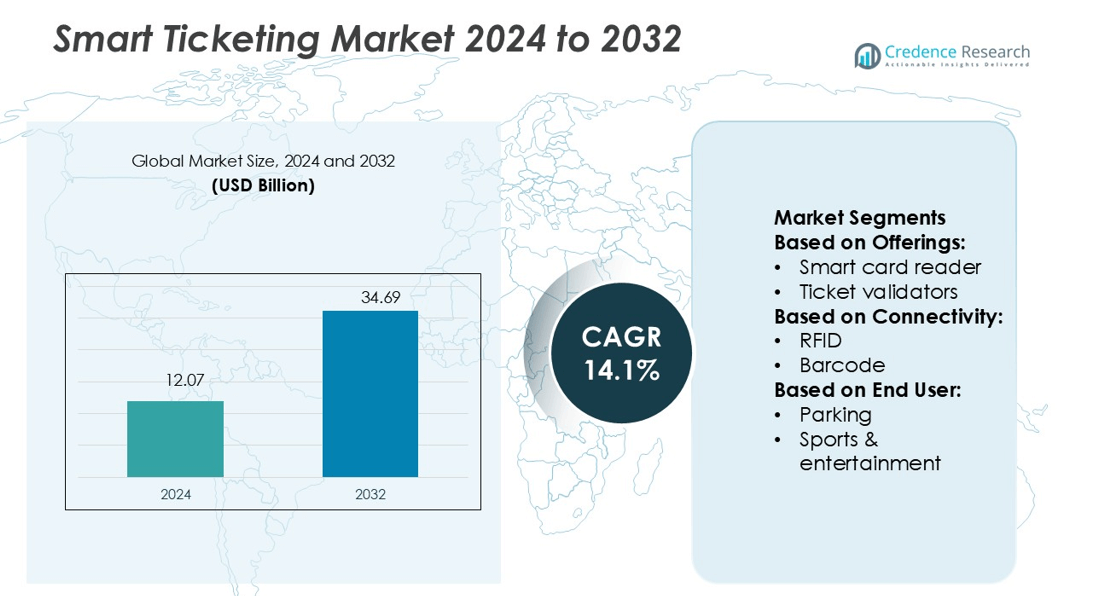
Smart Ticketing Market size was valued USD 12.07 billion in 2024 and is anticipated to reach USD 34.69 billion by 2032, at a CAGR of 14.1% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Smart Ticketing Market Size 2024 | USD 12.07 billion |
| Smart Ticketing Market, CAGR | 14.1% |
| Smart Ticketing Market Size 2032 | USD 34.69 billion |
The smart ticketing market is shaped by top players including Giesecke + Devrient, CPI Card Group, Infineon Technologies, Thales Group (formerly Gemalto), Cubic Corporation, HID Global (Assa Abloy), Siemens, NXP Semiconductors, Conduent, and Confidex. These companies focus on delivering secure, efficient, and scalable solutions by leveraging NFC, RFID, and mobile technologies across transportation, parking, and entertainment sectors. They invest in R&D, partnerships, and large-scale deployments to strengthen global presence. Regionally, Asia-Pacific leads the market with a 33% share, supported by rapid urbanization, government-backed smart city initiatives, and widespread adoption of mobile ticketing systems in metro and rail networks.
Market Insights
- The smart ticketing market size was valued at USD 12.07 billion in 2024 and is projected to reach USD 34.69 billion by 2032, growing at a CAGR of 14.1% during the forecast period.
- Growing demand for contactless payments, mobile ticketing, and e-toll systems drives adoption across transportation, parking, and entertainment sectors, with kiosks and smart machines holding the largest segment share.
- Key players such as Giesecke + Devrient, Infineon Technologies, Thales Group, and Cubic Corporation compete by advancing NFC and RFID technologies, expanding mobile integration, and forming strategic partnerships.
- High implementation costs and data security concerns remain significant restraints, limiting adoption in cost-sensitive markets and raising compliance challenges for operators.
- Asia-Pacific leads with 33% market share due to smart city projects and rapid digitalization, while North America holds 29% and Europe 27%, reflecting mature infrastructure and sustained investment in secure ticketing systems.
Market Segmentation Analysis:
By Offerings
In the smart ticketing market, ticketing machines and smart kiosks hold the largest share at 28%. Their dominance comes from widespread adoption in metro stations, airports, and bus terminals, ensuring quick ticketing and reduced manual operations. Rising investments in digital infrastructure and passenger demand for self-service options drive growth. Kiosks also support integrated payment systems and multilingual interfaces, enhancing accessibility and convenience. Vendors continue to innovate with biometric authentication and QR-based services, strengthening adoption across transportation and entertainment hubs.
- For instance, CPI Card Group’s Card@Once platform supports instant issuance across thousands of financial institutions and locations. A 2023 press release from the company noted it was trusted by over 2,000 financial institutions across nearly 15,000 locations.
By Connectivity
Near-field communication (NFC) dominates the connectivity segment with a 34% share. Its strong growth is driven by the rise of contactless payments and smartphone integration, enabling fast and secure ticketing. NFC-based systems reduce transaction times and minimize queues, boosting customer experience in high-traffic areas. Transportation authorities and event organizers increasingly deploy NFC-enabled gates and readers to streamline access. Support from banks and fintech firms for mobile wallets further strengthens demand. Ongoing expansions in smart transit and parking ecosystems continue to push NFC ahead of barcode and RFID solutions.
- For instance, Infineon’s security IC portfolio for transport ticketing includes the SLE 77CLF601P, which supports multi-application loads with 60 kByte of SOLID FLASH™. The IC is certified for use in transport ticketing and supports high-speed contactless communication, including protocols like ISO/IEC 14443-4.
By End User
Transportation leads the end-user segment with a commanding 41% market share. Railways, metros, and bus networks rely heavily on smart ticketing systems to handle large passenger volumes efficiently. Government-backed initiatives for digital transit systems and reduced cash handling reinforce adoption. Transportation operators invest in integrated e-toll and mobile ticketing platforms to improve revenue assurance and reduce fraud. Smart ticketing also supports multimodal travel by linking buses, trains, and metros under unified payment solutions. Growing urbanization and congestion management policies make transportation the strongest driver of market expansion.
Market Overview
Rising Adoption of Contactless Payment Systems
The adoption of contactless payment systems is a major growth driver in the smart ticketing market. Consumers prefer faster, secure, and convenient payment methods for daily commutes, entertainment, and parking. The integration of NFC-enabled smartphones, wearables, and smart cards enhances ticketing efficiency while reducing physical contact. Transportation operators, supported by government cashless initiatives, invest heavily in modern infrastructure to accommodate these technologies. This shift also reduces operational costs by minimizing manual cash handling. As cashless transactions grow globally, demand for contactless ticketing solutions continues to accelerate.
- For instance, Thales' Biometric Sensor Payment Card (BSPC) embeds a fingerprint sensor that operates without a battery. It wirelessly harvests all its energy from an ISO 14443-compliant POS terminal's magnetic field when the card is held within 4 cm.
Government Initiatives for Smart Transit Systems
Government initiatives to modernize transportation systems drive smart ticketing adoption worldwide. Public transport agencies invest in integrated ticketing platforms to enhance passenger convenience and streamline revenue collection. Smart city projects prioritize digital ticketing for buses, metros, and rail networks, aligning with sustainability and congestion management goals. Subsidies and regulatory frameworks encourage deployment of kiosks, e-toll solutions, and mobile ticketing applications. Such initiatives not only support seamless travel experiences but also reduce fraud and improve operational transparency. This government backing strengthens market growth across urban and intercity transit networks.
- For instance, HID’s Seos 16K credential holds 16,384 bytes of secure memory and supports over 12 distinct application partitions within one card, allowing both fare payment and access control on the same medium. ([HID Global credential specs].
Growing Demand for Seamless Multimodal Travel
The need for unified ticketing solutions across multiple transportation modes significantly fuels market expansion. Passengers expect a single digital platform for buses, trains, metros, and parking services. Smart ticketing systems provide interoperability, reducing the complexity of carrying multiple tickets or cards. Integrated systems also improve data-driven decision-making for operators, enabling optimized scheduling and resource allocation. The growing focus on multimodal transport efficiency, coupled with digitalization trends, encourages authorities to adopt advanced ticketing platforms. This demand for seamless travel experiences ensures steady growth in the global smart ticketing industry.
Key Trends & Opportunities
Integration of Mobile Ticketing Applications
Mobile ticketing applications are emerging as a strong trend, reshaping the passenger experience. The convenience of purchasing and storing tickets on smartphones reduces dependency on physical kiosks and cards. Event organizers and transportation operators leverage mobile apps to expand digital ticketing ecosystems with features like QR validation and real-time journey updates. Integration with mobile wallets enhances accessibility, while push notifications improve customer engagement. As smartphone penetration grows, mobile ticketing adoption provides operators with opportunities to reduce infrastructure costs and enhance user satisfaction.
- For instance, NXP’s PN7150 controller embeds an Arm Cortex-M0 core and supports I²C-host interface while handling all NFC Forum modes with wake-on-RF and low-power polling modes.
Expansion of E-Toll and Smart Parking Systems
E-tolling and smart parking present significant opportunities for market players. With rising urban congestion, governments and private operators adopt automated toll and parking systems to improve traffic flow and reduce waiting times. These solutions integrate RFID and NFC technologies, allowing seamless payment and reducing cash dependency. E-toll platforms also enhance revenue collection accuracy and minimize fraud risks. The growing number of vehicles globally accelerates demand for automated solutions, creating opportunities for vendors to expand offerings beyond public transport ticketing into road infrastructure and parking management.
- For instance, Confidex offers a range of rugged RFID vehicle labels that operate in temperatures from approximately −20 °C to 80 °C, with some hard tags designed for even more extreme temperatures.
Key Challenges
High Implementation and Maintenance Costs
The deployment of smart ticketing systems involves substantial infrastructure investments. Operators must procure ticketing kiosks, validators, and advanced communication networks, which significantly increase upfront costs. Additionally, system integration across legacy platforms and ongoing maintenance require continuous spending. Smaller operators and developing regions face financial barriers in adopting these systems, slowing widespread implementation. These high costs restrict scalability, especially in markets where return on investment depends heavily on passenger volumes. Vendors must develop cost-efficient solutions to address this challenge and encourage broader adoption.
Data Security and Privacy Concerns
Smart ticketing systems rely heavily on digital transactions and user data, raising concerns over cybersecurity and privacy. Sensitive passenger information, including payment credentials and travel history, becomes a target for cyberattacks. Breaches can lead to financial losses, legal liabilities, and damage to consumer trust. Stricter regulatory frameworks require operators to implement advanced encryption and secure authentication measures, which increase compliance costs. Managing these security risks remains a critical challenge for operators and vendors, as system vulnerabilities could slow adoption of digital ticketing solutions.
Regional Analysis
North America
North America holds a 29% share of the smart ticketing market, supported by strong adoption in transportation and entertainment sectors. The United States leads with extensive deployment of NFC-based ticketing in metro and bus networks, along with mobile ticketing for sports and concerts. Government emphasis on digital infrastructure and cashless payments further accelerates adoption. Canada follows with investments in smart parking and e-toll systems to ease urban congestion. High smartphone penetration, combined with consumer demand for contactless solutions, positions North America as a mature and technology-driven market with steady long-term growth prospects.
Europe
Europe accounts for 27% of the smart ticketing market, driven by integrated transit systems across countries like the UK, Germany, and France. Extensive use of smart cards and validators in public transport strengthens its position. European Union initiatives promoting sustainable mobility and cashless systems further expand opportunities. Rail operators and city transport agencies are adopting multimodal ticketing platforms to improve travel convenience. NFC and mobile-based solutions gain traction, particularly in urban hubs. Strong regulatory support, coupled with established public transport infrastructure, makes Europe a frontrunner in adopting innovative smart ticketing technologies for passenger convenience.
Asia-Pacific
Asia-Pacific dominates the global market with a commanding 33% share, led by China, Japan, and India. Rapid urbanization and high population density drive the adoption of smart ticketing in metro, bus, and rail systems. Governments actively invest in smart city projects that integrate mobile ticketing, RFID, and e-toll systems to streamline travel. Rising smartphone usage fuels demand for app-based ticketing platforms, while large-scale transport networks require scalable solutions. Japan and South Korea pioneer NFC and contactless systems, while India accelerates metro ticketing digitalization. Asia-Pacific’s growth is sustained by expanding infrastructure and strong consumer acceptance of digital payments.
Latin America
Latin America contributes 6% of the smart ticketing market, with growing adoption in Brazil, Mexico, and Argentina. The expansion of metro networks and investments in smart parking solutions strengthen regional growth. Brazil drives demand through contactless ticketing in public buses and stadiums, while Mexico focuses on integrating mobile ticketing applications for urban mobility. Despite budgetary constraints, government efforts to modernize transport infrastructure push adoption forward. Rising smartphone penetration supports mobile-based solutions, though limited digital infrastructure in rural areas remains a challenge. Latin America’s market is evolving steadily, with opportunities tied to ongoing transport modernization programs.
Middle East & Africa
The Middle East & Africa region holds a 5% share of the smart ticketing market, driven by infrastructure development in the Gulf Cooperation Council (GCC) countries and South Africa. The UAE and Saudi Arabia invest in smart transit solutions as part of broader smart city initiatives, including metro ticketing, parking systems, and e-toll platforms. South Africa leads African adoption, particularly in bus rapid transit networks. Growing tourism also fuels ticketing adoption in entertainment and transport hubs. However, limited affordability and infrastructure gaps in parts of Africa constrain expansion, keeping growth slower compared to other global regions.
Market Segmentations:
By Offerings:
- Smart card reader
- Ticket validators
By Connectivity:
- RFID
- Barcode
By End User:
- Parking
- Sports & entertainment
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Competitive Landscape
The smart ticketing market is highly competitive, featuring leading players such as Giesecke + Devrient, CPI Card Group, Infineon Technologies, Thales Group (formerly Gemalto), Cubic Corporation, HID Global (Assa Abloy), Siemens, NXP Semiconductors, Conduent, and Confidex. The smart ticketing market is characterized by rapid innovation, strong adoption across transportation networks, and growing reliance on digital platforms. Companies compete by offering advanced solutions that integrate NFC, RFID, and mobile technologies to ensure faster transactions and enhanced security. Market players prioritize seamless multimodal travel experiences, enabling passengers to use a single platform for buses, trains, metros, and parking services. Investments in mobile ticketing applications, e-toll systems, and smart kiosks reflect the shift toward contactless and cashless ecosystems. Strategic collaborations with governments and transport authorities, along with continuous R&D, remain central to strengthening market competitiveness and global reach.
Key Player Analysis
- Giesecke + Devrient
- CPI Card Group
- Infineon Technologies
- Thales Group (formerly Gemalto)
- Cubic Corporation
- HID Global (Assa Abloy)
- Siemens
- NXP Semiconductors
- Conduent
- Confidex
Recent Developments
- In October 2024, the Tasmanian government and its ITS (Intelligent Transport Systems) supplier Cubic Transportation Systems (CTS), a division of Cubic Corporation entered into an agreement for the provision of a safe and efficient smart ticketing system throughout the state.
- In October 2024, Infineon Technologies AG, CPI has designed All-in-One technology with Secora Pay Green, a technology not only minimizing its impact on the environment but even offering new and flexible structures for credit, debit, and prepaid cards for issuers.
- In July 2024, Conduent Transportation signed a major deal with Saint-Étienne Métropole (SEM), which is the public transit authority taking care of over 400,000 inhabitants in Saint-Étienne. Conduent will be the head of the STAR bus and tram network in the three-phase improving process, thereby, providing eco-friendly, cost-effective service to the area.
- In January 2024, Goodyear partnered with TDK for advanced next-generation tire solutions. By integrating TDK's software, sensors, and electrical component experience with Goodyear's tire development, intelligent solutions, and industry knowledge, the companies are planning to launch an effective tire sensing system with a collaborative approach.
Report Coverage
The research report offers an in-depth analysis based on Offerings, Connectivity, End-User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will expand with rising adoption of contactless and mobile payment solutions.
- Governments will continue to promote smart transit systems through digital infrastructure investments.
- Integration of multimodal travel platforms will improve passenger convenience and operational efficiency.
- Mobile ticketing applications will dominate due to increasing smartphone penetration worldwide.
- E-toll and smart parking solutions will witness higher adoption in urban mobility ecosystems.
- Biometric authentication will enhance security and streamline passenger identification in ticketing systems.
- Partnerships between technology providers and transport operators will accelerate innovation.
- Data analytics integration will enable operators to optimize routes and manage revenues effectively.
- Growth in smart city projects will drive large-scale deployments of smart ticketing systems.
- Cloud-based ticketing platforms will gain traction for scalability, flexibility, and cost efficiency.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Adoption of Contactless Payment Systems
The shift towards contactless payments, including NFC-enabled cards and smartphones, is accelerating smart ticketing adoption by offering faster, more secure, and convenient transactions for commuters and event-goers, reducing physical contact and operational costs.
Government Initiatives for Smart Transit
Governments worldwide are investing in digital infrastructure and smart city projects, mandating the deployment of integrated ticketing platforms in public transport to improve efficiency, reduce fraud, and support sustainability goals.
Demand for Seamless Multimodal Travel
Rising urbanization and the need for unified travel experiences are driving the integration of ticketing systems across buses, trains, metros, and parking, enabling passengers to use a single platform for multiple modes of transport.
Expansion of E-Toll and Smart Parking Solutions
Urban congestion and increasing vehicle ownership are prompting the adoption of automated e-toll and smart parking systems, which leverage RFID and NFC technologies to streamline payments and reduce wait times.
Growth in Mobile Ticketing Applications
Increasing smartphone penetration is fueling the use of mobile ticketing apps, allowing users to purchase, store, and validate tickets digitally, thereby reducing reliance on physical kiosks and cards while enhancing user convenience.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Smart Ticketing Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Smart Ticketing Market projected to grow between 2025 and 2032?
Which Smart Ticketing Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Smart Ticketing Market?
Who are the leading companies in the Smart Ticketing Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End User
- 1.2.1 Transportation
- 1.2.2 Parking
- 1.2.3 Sports & entertainment
- 1.3 By Offerings
- 1.3.1 Smart card reader
- 1.3.2 Ticket validators
- 1.3.3 Ticketing machines & kiosks
- 1.3.4 Mobile ticketing applications
- 1.3.5 E-toll solutions
- 1.4 By Connectivity
- 1.4.1 NFC
- 1.4.2 RFID
- 1.4.3 Barcode
- 1.4.4 QR code
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 12.07 billion → 2032: USD 34.69 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Smart Ticketing Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Smart Ticketing Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Smart Ticketing Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Smart Ticketing Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Smart Ticketing Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Smart Ticketing Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 Global Smart Ticketing Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Smart Ticketing Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 12.07 billion → 2032: USD 34.69 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Smart Ticketing Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End User - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Transportation
- 12.3.7.2 Parking
- 12.3.7.3 Sports & entertainment
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Offerings - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Smart card reader
- 12.4.7.2 Ticket validators
- 12.4.7.3 Ticketing machines & kiosks
- 12.4.7.4 Mobile ticketing applications
- 12.4.7.5 E-toll solutions
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Connectivity - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 NFC
- 12.5.7.2 RFID
- 12.5.7.3 Barcode
- 12.5.7.4 QR code
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Smart Ticketing End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Smart Ticketing Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Smart Ticketing Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Smart Ticketing Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Giesecke + Devrient
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 CPI Card Group
- 18.4 Infineon Technologies
- 18.5 Thales Group
- 18.6 Cubic Corporation
- 18.7 HID Global (Assa Abloy)
- 18.8 Siemens
- 18.9 NXP Semiconductors
- 18.10 Conduent
- 18.11 Confidex
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

