
Market Overview
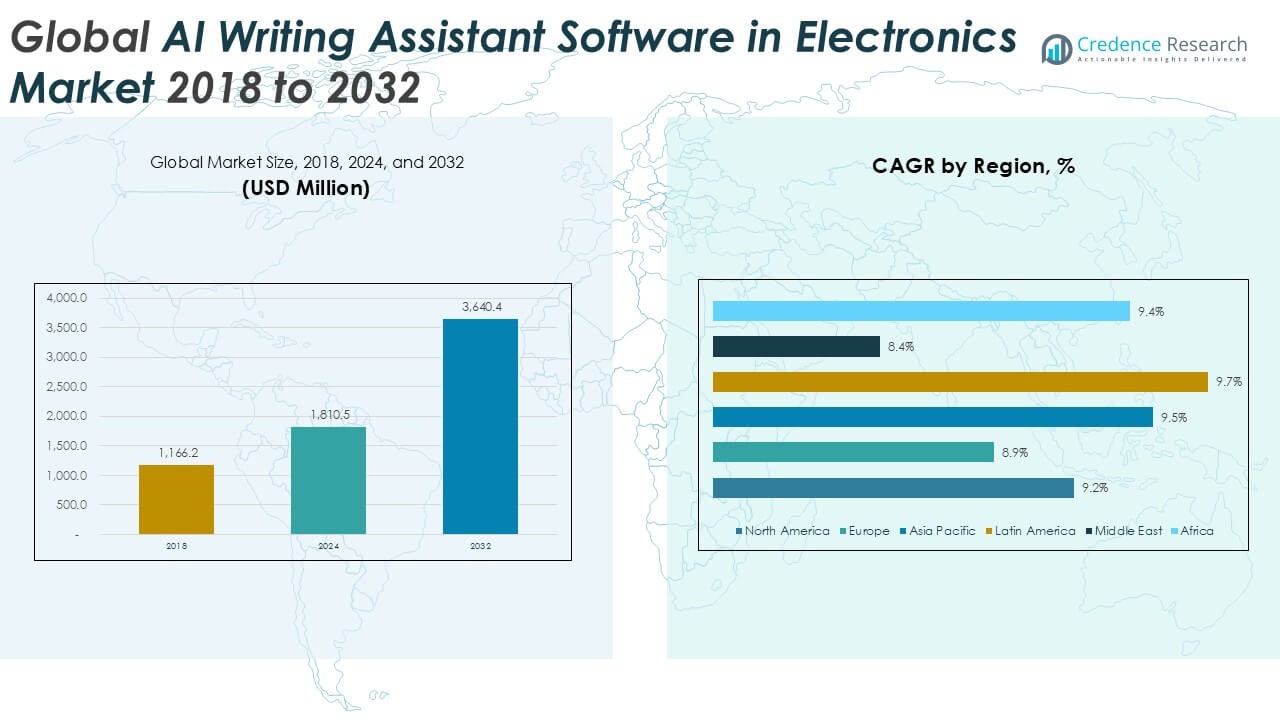
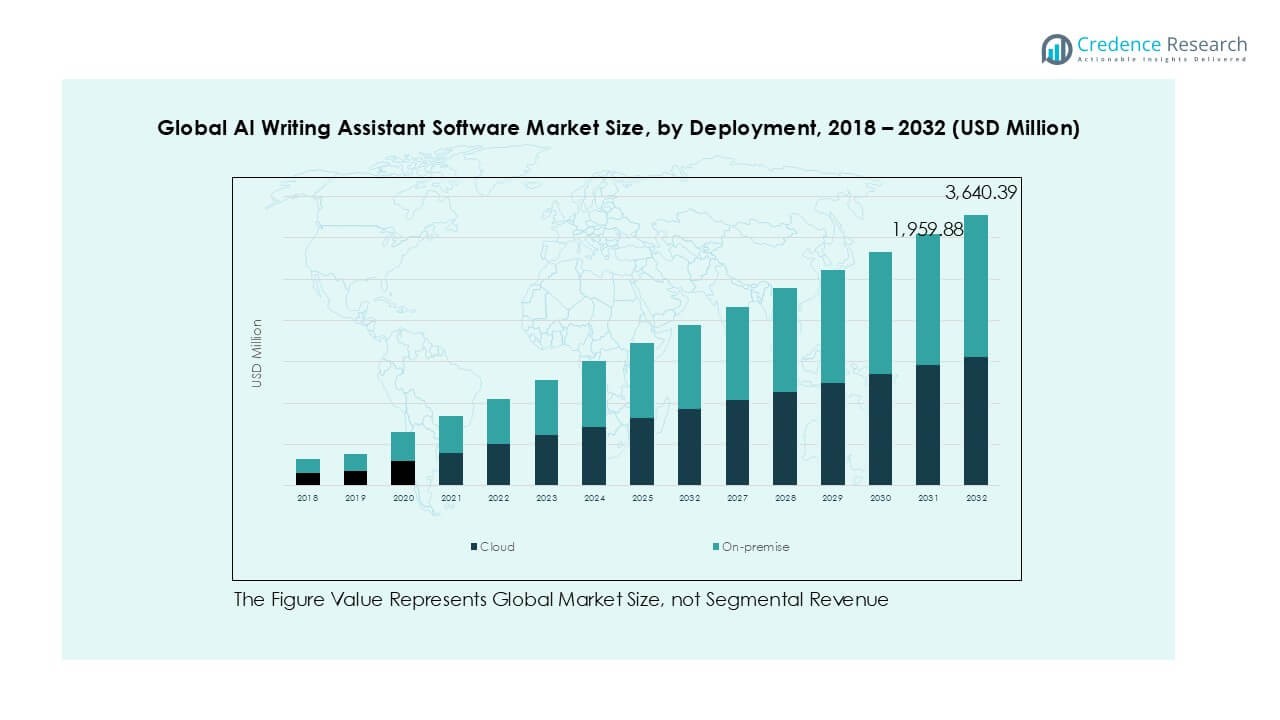
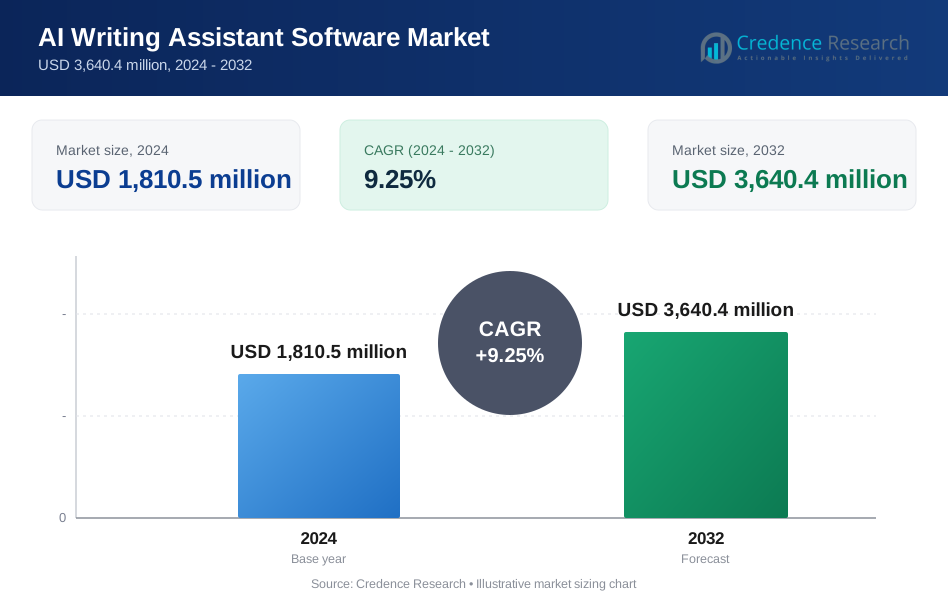
AI Writing Assistant Software market size was valued at USD 1,166.2 million in 2018, growing to USD 1,810.5 million in 2024, and is anticipated to reach USD 3,640.4 million by 2032, at a CAGR of 9.25% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| AI Writing Assistant Software Market Size 2024 | USD 1,810.5 Million |
| AI Writing Assistant Software Market, CAGR | 9.25% |
| AI Writing Assistant Software Market Size 2032 | USD 3,640.4 Million |
The AI writing assistant software market is led by major players including Grammarly Inc., Semrush, Jasper AI Inc., ProWritingAid, and DeepL, supported by emerging providers such as Rytr, Frase Inc., and AI Writer. These companies drive growth through advanced features like contextual recommendations, grammar and spelling checks, and style adjustments, increasingly integrated into cloud-based platforms for global reach. Asia Pacific emerged as the leading region with a 34.8% share in 2018, supported by rapid digitalization and growing e-learning adoption, followed by North America with 27.3% and Europe with 22.1%. Together, these regions account for the bulk of the market’s revenue, reflecting strong adoption among enterprises, individuals, and academic institutions.
Market Insights
- The AI Writing Assistant Software market was valued at USD 1,810.5 million in 2024 and is projected to reach USD 3,640.4 million by 2032, growing at a CAGR of 9.25%.
- Rising demand for error-free, efficient communication in business, academia, and publishing is a key driver boosting adoption, with grammar and spelling checking tools holding the largest feature-based share.
- Cloud deployment leads the market with nearly 70% share, supported by scalability and remote accessibility, while on-premise remains relevant in regulated industries requiring strict data security.
- The competitive landscape includes global leaders like Grammarly, Semrush, Jasper AI, and DeepL, alongside emerging players such as Rytr and Frase Inc., focusing on affordability and niche user segments.
- Regionally, Asia Pacific dominates with 34.8% share in 2018, followed by North America at 27.3% and Europe at 22.1%; Latin America, Middle East, and Africa show high growth potential with CAGRs above 9%.
Market Segmentation Analysis:
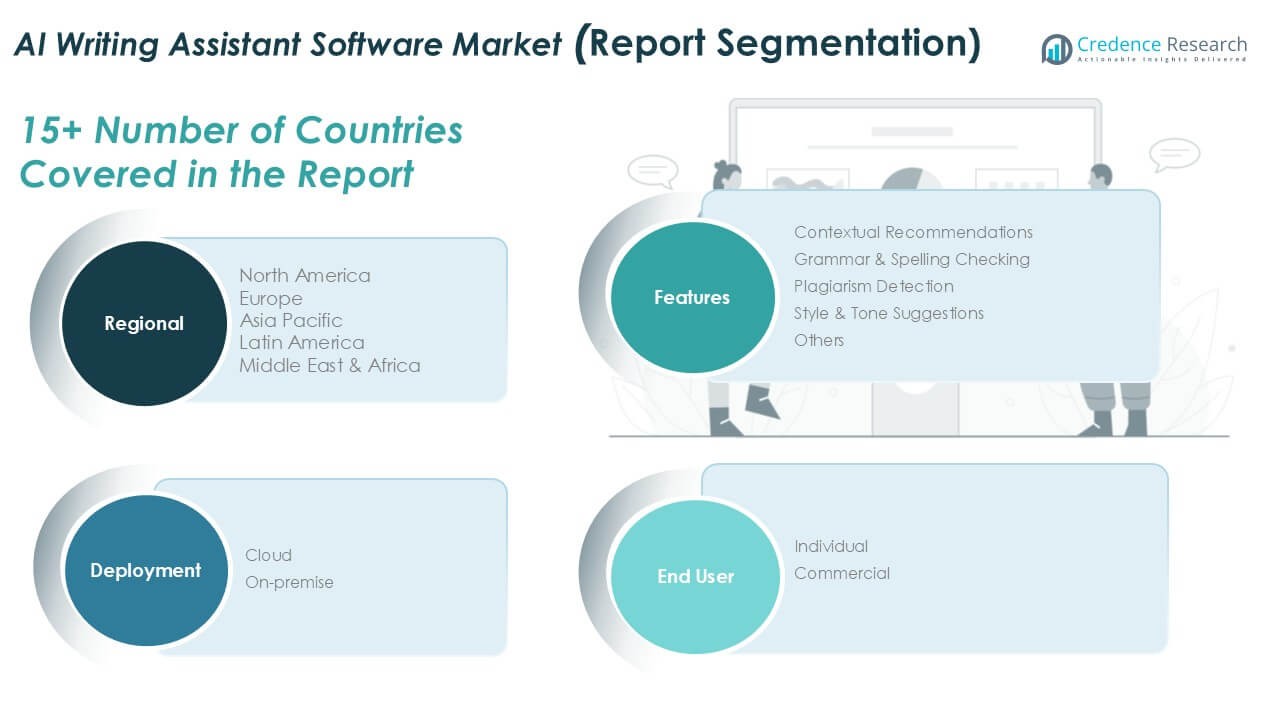
By Feature
The AI writing assistant software market by feature is led by grammar and spelling checking, which accounted for over 35% of revenue share in 2024. This dominance is driven by its wide adoption across individual and professional users seeking error-free content in real-time. Contextual recommendations and style & tone suggestions are also gaining traction as enterprises focus on brand consistency and personalized communication. Meanwhile, plagiarism detection tools see rising demand in academia and publishing, supported by stricter content originality policies. The “others” category includes niche features like translation support and formatting aids.
- For instance, Turnitin has published other usage statistics, such as its AI writing detection feature reviewing over 159 million submissions since its April 2023 launch.
By Deployment
Cloud-based deployment dominated the AI writing assistant software market, holding nearly 70% of the share in 2024. The preference for cloud solutions stems from their scalability, cost-effectiveness, and ability to support remote collaboration across global teams. Enterprises favor cloud platforms for integrating AI into digital workflows, while individuals value the accessibility of subscription-based models. On-premise deployment continues to serve organizations with stricter data security and compliance requirements, particularly in regulated industries. However, the growing emphasis on flexibility and seamless updates ensures cloud remains the preferred model for most users.
- For instance, Grammarly reported surpassing 30 million daily active users in 2023 through its cloud-based platform, highlighting the widespread adoption of subscription-driven AI writing assistants.
By End User
Commercial users led the AI writing assistant software market, capturing about 65% of the share in 2024. Businesses across marketing, publishing, legal, and customer service rely on AI-driven tools to enhance productivity, reduce manual editing, and maintain brand tone consistency. Demand from individuals, although smaller, is expanding due to rising freelance writing, academic needs, and professional communication tasks. The growth in commercial adoption is further supported by enterprises investing in multilingual content generation and real-time assistance to improve engagement. Increasing focus on operational efficiency ensures commercial applications continue as the dominant end-user segment.
Key Growth Drivers
Rising Demand for Error-Free and Efficient Communication
The growing importance of clear, accurate, and fast communication is driving the AI writing assistant software market. Businesses across industries are prioritizing polished content to engage customers, build brand credibility, and maintain professionalism in customer-facing documents. Grammar and spelling checking tools remain the most widely used features, as they reduce manual editing time and ensure error-free outputs. In addition, organizations are integrating these tools into internal communication platforms and customer service workflows to improve efficiency. The surge in remote and hybrid work has further accelerated adoption, as professionals seek real-time assistance to deliver consistent, high-quality content without additional editorial resources. This strong need for accuracy and productivity underpins steady market growth.
- For instance, Microsoft reported that more than 400 million users engaged with Editor in 2023, its AI-powered writing assistant integrated into Office 365 and Teams.
Expansion of Content Marketing and Digital Engagement
The rise of digital platforms and content-driven strategies is a major growth driver for AI writing assistant software. Companies are producing blogs, whitepapers, marketing emails, and social media posts at an unprecedented scale. AI tools offering contextual recommendations, style suggestions, and tone adjustments support marketers in tailoring content for diverse audiences while ensuring consistency with brand guidelines. Plagiarism detection has also gained traction, especially for publishers and marketing agencies handling large volumes of content. The demand for multilingual support further widens opportunities, as businesses expand into global markets. As digital engagement becomes central to customer acquisition and retention, AI-powered writing assistants play a crucial role in delivering personalized and persuasive content efficiently.
- For instance, Jasper AI reported generating over 80,000 pieces of marketing content per day in 2023 across blogs, ads, and social media posts for enterprise clients.
Integration with Advanced AI and Natural Language Processing (NLP)
The evolution of AI and NLP technologies is enhancing the capabilities of writing assistant tools. Modern platforms now deliver context-aware recommendations, detect subtle style variations, and even provide tone modifications aligned with the writer’s intent. These innovations are fueling broader adoption among enterprises seeking advanced, human-like writing support. Cloud-based models also leverage continuous updates to refine accuracy and expand functionality, offering users access to cutting-edge features. Furthermore, the integration of AI writing assistants into enterprise software ecosystems, such as customer relationship management (CRM) systems and productivity suites, has increased usability and relevance. As organizations embrace digital transformation and automation, the sophistication of NLP-driven solutions acts as a significant catalyst for long-term market growth.
Key Trends & Opportunities
Growing Adoption of Cloud-Based Writing Platforms
Cloud deployment is a strong trend shaping the AI writing assistant software market. Businesses and individuals increasingly prefer cloud-based solutions due to their scalability, low upfront cost, and ease of integration with existing digital tools. Subscription models also make advanced AI features accessible to freelancers, students, and small businesses, broadening the user base. The shift toward cloud platforms further allows real-time collaboration across geographies, supporting global teams and remote work environments. Vendors offering multilingual support and seamless integration with productivity tools like email, word processors, and customer engagement platforms are well positioned to capture new opportunities. This trend not only strengthens market penetration but also ensures recurring revenue streams for providers.
- For instance, Grammarly’s cloud-based platform surpassed 30 million daily active users in 2023, with support for over 500,000 enterprise teams globally.
Increasing Use Cases in Education and Academia
The education sector represents a growing opportunity for AI writing assistant software. Students and academic institutions are adopting tools for grammar correction, plagiarism detection, and structured writing assistance. These solutions help improve learning outcomes by enabling students to refine their writing skills while ensuring academic integrity. Universities and online learning platforms are also incorporating AI assistants into coursework and learning management systems to support non-native English speakers and enhance accessibility. The adoption is expected to grow with the rise of e-learning and remote education models. This trend positions AI writing assistants as essential academic tools, further diversifying market applications beyond business and personal use.
Key Challenges
Data Privacy and Security Concerns
One of the main challenges in the AI writing assistant software market is data privacy. Writing assistants often process sensitive information such as business communication, legal documents, or academic submissions. Concerns arise over how this data is stored, analyzed, and protected, especially with cloud-based deployments. Enterprises in regulated industries such as healthcare and finance are hesitant to adopt these solutions due to potential compliance risks. Vendors must ensure robust encryption, compliance with regulations like GDPR, and transparent data usage policies to address these concerns. Without proper safeguards, trust issues could slow adoption rates, particularly among large organizations handling confidential content.
Limitations in Accuracy and Context Understanding
Despite advancements in NLP, AI writing assistants still face challenges in delivering perfect contextual understanding. Complex sentences, domain-specific terminology, and nuanced language often result in misinterpretations or inaccurate suggestions. These limitations can lead to over-reliance on AI and potential errors in critical business or academic documents. While tools continue to improve, users often require human oversight to ensure final content quality. This challenge highlights the need for hybrid solutions that combine automation with editorial control. Failure to address accuracy and contextual gaps could hinder adoption among professionals demanding precise, industry-specific outputs.
Regional Analysis
North America
North America held a 27.3% market share in 2018, valued at USD 319.77 million, and grew to USD 494.74 million in 2024. The region is projected to reach USD 990.19 million by 2032, expanding at a CAGR of 9.2%. Strong adoption of AI in enterprises, widespread use of digital platforms, and high demand for advanced grammar and contextual recommendation tools support growth. The U.S. dominates the regional market with a focus on AI integration in business communication, academic institutions, and publishing. The region remains a leader due to advanced technology adoption and established software ecosystems.
Europe
Europe captured a 22.1% share in 2018, with the market valued at USD 257.85 million, rising to USD 392.47 million in 2024. It is forecast to reach USD 768.12 million by 2032 at a CAGR of 8.9%. The region benefits from increasing adoption of AI-powered writing tools across corporate, academic, and publishing sectors. Stringent compliance standards also drive interest in secure on-premise deployments. Countries like Germany, the UK, and France lead adoption, supported by growing demand for multilingual content creation. Europe’s digital transformation strategies and e-learning expansion further strengthen the regional outlook.
Asia Pacific
Asia Pacific led the market with a 34.8% share in 2018, valued at USD 405.61 million, growing to USD 638.31 million in 2024. The market is projected to reach USD 1,306.54 million by 2032, with the fastest CAGR of 9.5%. Growth is fueled by rapid digitalization, strong e-learning demand, and increasing use of AI tools by freelancers and enterprises. China, India, and Japan drive the expansion, supported by rising smartphone penetration and large-scale adoption of cloud solutions. The region benefits from a fast-growing content creation ecosystem, positioning Asia Pacific as the leading global market in the forecast period.
Latin America
Latin America accounted for a 9% market share in 2018, valued at USD 103.91 million, and increased to USD 165.51 million in 2024. It is projected to reach USD 344.02 million by 2032, advancing at a CAGR of 9.7%, the highest among all regions. Growth is driven by the rise of digital businesses, expanding e-learning platforms, and increased focus on professional communication quality. Brazil and Mexico dominate adoption, supported by growing awareness of AI-powered writing tools. The market’s expansion is also linked to SMEs adopting cost-effective cloud-based writing solutions to enhance productivity and competitiveness.
Middle East
The Middle East represented a 4.8% share in 2018, valued at USD 55.74 million, growing to USD 82.97 million in 2024. The region is expected to reach USD 157.26 million by 2032, registering a CAGR of 8.4%. Adoption is primarily driven by enterprises in the UAE and Saudi Arabia investing in AI-based solutions for corporate communication and education. Government-led digital transformation programs also support demand. However, slower technological penetration compared to developed regions limits growth pace. Increasing integration of AI into workplace productivity tools is expected to boost market uptake over the forecast period.
Africa
Africa held a 2% share in 2018, with the market valued at USD 23.32 million, increasing to USD 36.52 million in 2024. It is forecast to reach USD 74.26 million by 2032, growing at a strong CAGR of 9.4%. Rising internet penetration, expansion of digital education, and the increasing freelance workforce drive adoption. South Africa and Nigeria are leading contributors, while smaller economies are gradually embracing cloud-based writing assistants. Limited awareness and infrastructure challenges remain barriers, but opportunities from e-learning platforms and mobile-first users position Africa as an emerging growth market with promising potential.
Market Segmentations:
By Feature
- Contextual Recommendations
- Grammar & Spelling Checking
- Plagiarism Detection
- Style & Tone Suggestions
- Others
By Deployment
- Cloud
- On-premise
By End User
- Individual
- Commercial
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the AI writing assistant software market is highly dynamic, with established technology firms and emerging startups competing to enhance their offerings. Leading players such as Semrush, Grammarly Inc., ProWritingAid, Jasper AI Inc., and DeepL dominate due to their strong brand presence, diversified portfolios, and integration with productivity platforms. Startups like Rytr, AI Writer, and Frase Inc. are gaining traction with cost-effective solutions tailored for freelancers and SMEs. Vendors are focusing on expanding feature sets, such as contextual recommendations and plagiarism detection, while investing in cloud-based delivery models to reach wider audiences. Strategic partnerships, product innovations, and AI-driven advancements in natural language processing are common growth strategies. Companies are also emphasizing multilingual support and enterprise-focused solutions to strengthen adoption across global markets. Intense competition is expected to push continuous innovation, driving user-centric solutions that combine accuracy, security, and efficiency.
Key Player Analysis
- Semrush
- ProWritingAid (Orpheus Technology)
- Jasper AI Inc.
- DeepL
- Grammarly Inc.
- AI Writer
- Rytr
- Keywee Inc.
- Cvent
- Frase Inc.
- Other Key Players
Recent Developments
- In July 2024, Proton, a privacy app developer, launched Proton Scribe, an AI writing assistant. This tool helps users write, redraft, and proofread emails with simple prompts. Proton Scribe uses Mistral 7B, an open-source language model from the French AI startup, Mistral. This new feature aims to make email communication more efficient and secure for users.
- In March 2024, GetResponse, a global email marketing platform, introduced an AI email writing assistant. This tool helps users save time, overcome writer's block, and create engaging email content faster. The AI assistant is built into GetResponse's drag-and-drop email editor and uses an OpenAI-powered text generator. With ready-to-use prompts and text optimization options, users can quickly generate compelling email copy tailored to their audience.
- In 2023, Google started working on a new AI product called ‘Genesis’. The main goal of Genesis AI, which functions as a writing assistant, is to make journalistic tasks easier and more efficient, allowing reporters to dedicate their time to more intricate challenges.
- In 2023, Springer Nature introduced Curie, a scientific writing assistant powered by AI, created to aid researchers, particularly those who are not native English speakers, in enhancing their scientific writing. Curie has been taught using academic papers from over 447 different fields and over 1 million revisions.
Report Coverage
The research report offers an in-depth analysis based on Feature, Deployment, End User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will expand steadily as businesses and individuals adopt AI-driven writing solutions.
- Demand will grow due to the rising need for error-free communication across industries.
- Integration with advanced natural language processing will make tools more context-aware and accurate.
- Cloud-based platforms will remain dominant as users prefer flexible and scalable models.
- Grammar and spelling checking will continue as the leading feature segment by share.
- Commercial end users will drive adoption, supported by strong enterprise content needs.
- Asia Pacific will maintain leadership, fueled by digitalization and e-learning expansion.
- North America will remain a major hub, supported by early technology adoption.
- Data privacy concerns and accuracy limitations will challenge providers to improve solutions.
- Vendors will compete on innovation, multilingual support, and integration with productivity ecosystems.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Demand for Error-Free and Efficient Communication
Businesses, academic institutions, and publishers are increasingly adopting AI writing assistants to ensure high-quality, error-free content, reducing manual editing time and improving professionalism in communications.
Expansion of Content Marketing and Digital Engagement
The surge in digital marketing, blogging, and social media has driven organizations to use AI writing tools for generating large volumes of consistent, brand-aligned content, supporting customer acquisition and engagement strategies.
Growth of Cloud-Based Platforms
The preference for cloud deployment, offering scalability, remote accessibility, and cost-effectiveness, has accelerated adoption among enterprises and individuals, especially with the rise of remote and hybrid work environments.
Integration of Advanced AI and NLP Technologies
Continuous advancements in AI and natural language processing have enabled writing assistants to provide more context-aware, accurate, and human-like suggestions, increasing their value for complex business and academic use cases.
Rising Adoption in Education and Academia
Educational institutions and students are leveraging AI writing assistants for grammar correction, plagiarism detection, and structured writing support, enhancing learning outcomes and academic integrity, especially in e-learning environments.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for AI Writing Assistant Software market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the AI Writing Assistant Software market projected to grow between 2025 and 2032?
Which AI Writing Assistant Software market segment held the largest share in 2024?
What are the primary factors fueling the growth of the AI Writing Assistant Software market?
Who are the leading companies in the AI Writing Assistant Software market?
Which region commanded the largest share of the AI Writing Assistant Software market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Feature
- 1.2.1 Grammar & Spelling Checking
- 1.2.2 Contextual Recommendations
- 1.2.3 Plagiarism Detection
- 1.2.4 Style & Tone Suggestions
- 1.2.5 Others
- 1.3 By End User
- 1.3.1 Commercial
- 1.3.2 Individual
- 1.4 By Deployment
- 1.4.1 Cloud
- 1.4.2 On-premise
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 1,810.5 million → 2032: USD 3,640.4 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global AI Writing Assistant Software Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global AI Writing Assistant Software Market Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Supply Chain Structure and Procurement Trends
- 5.4 Supply-Demand Gap and Bottlenecks
- 5.5 Import Dependence and Sourcing Structure
- 5.6 Regional Supply and Demand Concentration
Chapter 6 Global AI Writing Assistant Software Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Pricing by Product and Market Segment
- 6.5 Geographic Pricing Differences
- 6.6 Key Input, Energy, Labor and Logistics Costs
- 6.7 Contract Pricing and Purchasing Models
- 6.8 Pricing Sensitivity and Competitive Positioning
- 6.9 Price, Margin and Profitability Implications
Chapter 7 Global AI Writing Assistant Software Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global AI Writing Assistant Software Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global AI Writing Assistant Software Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Data Protection, AI and Cybersecurity Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global AI Writing Assistant Software Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global AI Writing Assistant Software Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 1,810.5 million → 2032: USD 3,640.4 million)
- 11.1.2 Historical Market Size
- 11.1.3 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 CAGR and Year-on-Year Growth
- 11.2.3 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global AI Writing Assistant Software Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Feature - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Base-Year Market Share, 2024
- 12.3.5 Segment CAGR and Growth Drivers
- 12.3.6 Subsegment Market Size and Forecast
- 12.3.6.1 Grammar & Spelling Checking
- 12.3.6.2 Contextual Recommendations
- 12.3.6.3 Plagiarism Detection
- 12.3.6.4 Style & Tone Suggestions
- 12.3.6.5 Others
- 12.3.7 Subsegment Pricing and Adoption Trends
- 12.3.8 Leading Suppliers and Competition
- 12.3.9 Regional Demand and Opportunities
- 12.4 By End User - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Base-Year Market Share, 2024
- 12.4.5 Segment CAGR and Growth Drivers
- 12.4.6 Subsegment Market Size and Forecast
- 12.4.6.1 Commercial
- 12.4.6.2 Individual
- 12.4.7 Subsegment Pricing and Adoption Trends
- 12.4.8 Leading Suppliers and Competition
- 12.4.9 Regional Demand and Opportunities
- 12.5 By Deployment - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Base-Year Market Share, 2024
- 12.5.5 Segment CAGR and Growth Drivers
- 12.5.6 Subsegment Market Size and Forecast
- 12.5.6.1 Cloud
- 12.5.6.2 On-premise
- 12.5.7 Subsegment Pricing and Adoption Trends
- 12.5.8 Leading Suppliers and Competition
- 12.5.9 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global AI Writing Assistant Software End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global AI Writing Assistant Software Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global AI Writing Assistant Software Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global AI Writing Assistant Software Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Grammarly Inc.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Financial Performance and Investment
- 18.2.6 Market Share and Competitive Position
- 18.2.7 Technology and Innovation Capabilities
- 18.2.8 Strategic Alliances or Partnerships
- 18.2.9 Recent Developments
- 18.2.10 Growth Strategy and Outlook
- 18.3 Semrush
- 18.4 Jasper AI Inc.
- 18.5 ProWritingAid
- 18.6 DeepL
- 18.7 Rytr
- 18.8 Frase Inc.
- 18.9 AI Writer
- 18.10 Turnitin
- 18.11 Google
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

