
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Aerial Imaging Market Size 2024 | USD 2745.8 Million |
| Aerial Imaging Market, CAGR | 14.80% |
| Aerial Imaging Market Size 2032 | USD 9509.24 Million |
Market Overview
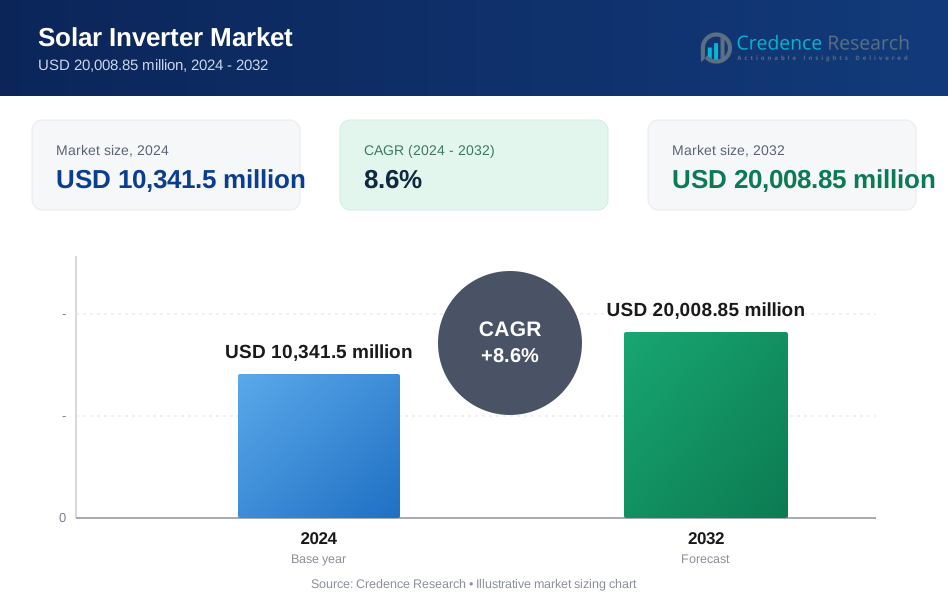
The global solar inverter market is projected to grow from USD 10,341.5 million in 2024 to USD 20,008.85 million by 2032, reflecting a compound annual growth rate (CAGR) of 8.6%.
The solar inverter market is driven by the increasing demand for renewable energy solutions and the growing adoption of solar power systems worldwide. Rising environmental concerns and government incentives for clean energy are fueling this growth. Technological advancements, such as the development of more efficient and cost-effective inverters, are further accelerating market expansion. Additionally, the shift towards decentralized energy generation, coupled with the integration of smart grid technologies, is driving the demand for advanced solar inverters. These trends are expected to continue, making solar inverters a critical component of the global transition to sustainable energy.
The global solar inverter market is highly competitive, with key players spanning multiple regions. In North America, companies like SunPower Corporation and Solectria Renewables LLC lead the market, focusing on innovative solutions for both residential and commercial sectors. In Europe, SMA Solar Technology AG and ABB Ltd. dominate, emphasizing high-efficiency inverters for diverse applications. In Asia-Pacific, SolarEdge Technologies Inc. and Sineng Electric Co. Ltd. drive growth with cost-effective, scalable solutions. These players focus on technological advancements and regional demand, aiming to enhance grid integration, energy efficiency, and affordability in solar power systems globally.
Market Drivers
Government Support and Subsidies
Governments around the world are offering various incentives, including tax credits, rebates, and feed-in tariffs, to drive the adoption of solar power systems. For instance, India has implemented the National Solar Mission, which provides substantial subsidies and incentives for solar power installations. These financial subsidies lower the upfront cost of installation and make solar power more financially attractive for consumers. This support has a direct impact on the demand for solar inverters, as they are integral components of solar power systems.
Technological Advancements and Grid Integration
Continuous innovation in inverter technology has led to the development of more efficient, reliable, and intelligent inverters. For instance, the latest models boast efficiency ratings upwards of 99% due to advancements in semiconductor materials like silicon carbide (SiC) and gallium nitride (GaN). Microinverters, string inverters, and hybrid inverters are offering greater flexibility and improved performance. Moreover, as solar power penetration increases, efficient grid integration and energy storage solutions are becoming more crucial. Solar inverters play a vital role in managing the flow of solar power into the grid and enabling seamless integration with energy storage systems, ensuring a reliable energy supply.
Rising Demand for Renewable Energy
Increasing global awareness of climate change and the need for sustainable energy sources are driving the rapid adoption of solar power. Governments worldwide are implementing supportive policies and offering incentives to promote renewable energy, further stimulating the demand for solar inverters. These initiatives aim to reduce dependence on fossil fuels and accelerate the transition to cleaner energy solutions, positioning solar power as a key player in global energy strategies.
Falling Costs of Solar Technology
Technological advancements and economies of scale have significantly reduced the cost of solar panels and inverters. For instance, solar photovoltaic costs have fallen by 90% in the last decade. As these costs continue to decline, solar energy becomes more affordable for both residential and commercial applications. The ongoing reduction in costs has made solar power increasingly competitive with traditional fossil fuel-based electricity generation, enabling wider adoption across various market segments.
Market Trends
Increasing Demand for Renewable Energy and Technological Advancements
The global shift toward sustainable energy sources and growing concerns about climate change are driving the widespread adoption of solar power systems. Government policies and incentives, including feed-in tariffs and tax breaks, are further stimulating demand for solar inverters as they enable smoother transitions to clean energy. For instance, the Ministry of New and Renewable Energy in India has implemented various schemes to promote solar energy adoption, such as the New Solar Power Scheme for PVTG Habitation. Technological advancements in inverter types are also shaping the market. Microinverters, offering module-level power electronics, optimize energy production, particularly in shaded or partially shaded environments. String inverters, though more traditional, are evolving with enhanced efficiency, reliability, and advanced features like rapid shutdown and anti-islanding protection. Central inverters, suitable for large-scale installations, are becoming increasingly efficient and compact, supporting the demand for more powerful solar energy solutions.
Integration with Energy Storage and Focus on Efficiency
The integration of solar inverters with battery storage systems is gaining momentum, enabling energy storage for later use, especially during peak demand periods or grid outages. This combination supports grid resilience and helps meet the growing energy needs of both residential and commercial applications. Moreover, solar inverters are becoming increasingly intelligent, with smart grid capabilities allowing them to communicate with the grid and optimize energy flow. This enhances grid stability and supports advanced grid management strategies. At the same time, continuous technological advancements and economies of scale are driving down the cost of solar inverters, making solar energy more affordable for a broader range of consumers. As manufacturers focus on improving efficiency and reliability, the demand for high-performance inverters with robust designs, capable of minimizing maintenance costs and extending their lifespan, continues to rise. Emerging markets, especially in developing countries with abundant solar resources, are expected to become significant contributors to market growth.
Market Challenges Analysis
Technical Challenges in Solar Inverter Integration and Performance
Grid integration remains a significant technical challenge as solar power becomes a larger part of the global energy mix. For instance, a report by the National Renewable Energy Laboratory highlights that inverters must be designed to manage the fluctuations and stability issues that arise when large volumes of solar power are fed into the grid. Ensuring that inverters can operate efficiently in diverse environmental conditions is another challenge. They need to withstand extreme temperatures, humidity, and electrical surges while maintaining high performance and long-term reliability. Additionally, excessive heat can negatively impact inverter efficiency and lifespan, making proper thermal management essential. Over time, key components like capacitors and transistors may degrade, affecting the inverter’s performance, which makes regular maintenance and monitoring essential to mitigate potential failures. Manufacturers are actively working on these challenges to ensure that inverters can function effectively in diverse and demanding environments.
Market Challenges Impacting Adoption and Expansion
While the cost of solar power has decreased over the years, the initial investment for solar systems, including inverters, remains a significant hurdle for many consumers. The high upfront cost can deter potential adopters, especially in markets with limited financial incentives. Additionally, the complexity of installation and maintenance is a challenge. Installing solar systems and ensuring they run efficiently requires skilled technicians, and a shortage of these professionals in certain regions can hinder the widespread adoption of solar technologies. Furthermore, the lack of standardized communication protocols and interoperability between different system components complicates integration, leading to potential inefficiencies. Another issue is the impact of global supply chain disruptions, particularly semiconductor shortages, which can delay the production and delivery of inverters, thus affecting availability and pricing. These market challenges must be addressed for solar power to continue expanding globally.
Market Segmentation Analysis:
By Type:
The solar inverter market is segmented into three primary types: central inverters, micro-inverters, and string inverters, each catering to different applications. Central inverters are commonly used in large-scale solar power plants due to their high efficiency and ability to handle vast amounts of electricity. These inverters are centralized, reducing installation and maintenance costs for large systems. Micro-inverters, on the other hand, are installed at the module level, providing optimized energy conversion for each individual solar panel. This makes them ideal for residential installations, particularly in areas with partial shading, as they minimize power loss. String inverters, the most widely used, are designed for both residential and commercial systems, offering a balance of cost and efficiency. They connect a series of solar panels into strings, with a single inverter managing the output of all panels. As solar power systems grow in popularity, these inverter types play a crucial role in ensuring efficient energy conversion.
By System Type:
Solar inverters are further categorized based on the type of system they support: off-grid and on-grid. On-grid systems are designed to operate in conjunction with the utility grid, allowing excess energy generated by solar panels to be fed back into the grid. These systems rely heavily on inverters for seamless integration with the grid, ensuring proper voltage and frequency regulation. In contrast, off-grid systems are designed for remote areas without access to the electrical grid. These inverters work with battery storage systems to store excess power for use during times when solar generation is low. As the adoption of solar energy grows, both off-grid and on-grid systems are expected to play a significant role in the transition to cleaner energy, with inverters serving as a critical component for optimal performance and grid stability.
Segments:
Based on Type:
- Central Inverter
- Micro-Inverter
- String Inverter
Based on System Type:
- Off Grid
- On Grid
Based on Phase:
- Single Phase
- Three Phase
Based on End-Use:
- Residential
- Commercial and Industrial
- Utilities
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
North America holds a significant share, accounting for approximately 30% of the global solar inverter. The demand for solar inverters in this region is driven by increasing government support for renewable energy, particularly in the United States, which has seen a surge in residential and commercial solar installations. State-level incentives, along with the federal government's push for clean energy, have further bolstered the adoption of solar power and, consequently, solar inverters. Moreover, the growing trend of smart grids and energy storage integration has accelerated the need for efficient and advanced inverters, contributing to the region's market dominance.
Asia-Pacific
Asia Pacific, on the other hand, is poised to maintain its leading position in the solar inverter market, contributing nearly 40%. The region benefits from high solar energy potential, particularly in countries like China and India, which are aggressively pursuing renewable energy goals to reduce dependence on fossil fuels. China, as the world's largest solar market, is expected to continue driving the growth of solar inverter demand. Moreover, the rapidly expanding infrastructure in India and other developing countries in the region is fueling investments in solar power projects, further propelling the need for solar inverters. The adoption of on-grid and off-grid solar systems, along with government subsidies and policies promoting clean energy, is set to ensure sustained market growth in Asia Pacific in the coming years.
Key Player Analysis
- Delta Electronics (Taiwan)
- ABB Ltd (Switzerland)
- SunPower Corporation (US)
- Canadian Solar Inc. (Canada)
- Power Electronics (Spain)
- SolarEdge Technologies Inc. (Israel)
- Sineng Electric Co. Ltd. (China)
- SMA Solar Technology AG (Germany)
- Solectria Renewables LLC (US)
- Hitachi Hi-Rel Power Electronics Pvt. Ltd (India)
Competitive Analysis
The solar inverter market is highly competitive, with key players such as Delta Electronics, ABB Ltd, SunPower Corporation, Canadian Solar Inc., SolarEdge Technologies Inc., SMA Solar Technology AG, Sineng Electric Co. Ltd., Power Electronics, Solectria Renewables LLC, and Hitachi Hi-Rel Power Electronics. Companies focus on developing inverters with higher efficiency, longer lifespan, and improved grid compatibility. The market is segmented into central inverters, micro-inverters, and string inverters, with each type serving distinct applications, such as residential, commercial, and utility-scale solar projects. Additionally, the market sees innovation in smart grid technologies and the integration of inverters with energy storage systems to enhance energy management. As solar power adoption increases globally, the competitive landscape continues to evolve, with manufacturers striving to offer cost-effective, high-performance solutions to meet diverse customer needs.
Recent Developments
- In May 2024, Sungrow, a leading global PV inverter provider, was named the top solar inverter brand in Australia for 2023 by Sunwiz, a leading solar industry authority. This recognition highlights Sungrow's technological prowess, product excellence, and strong market position in the competitive Australian solar PV inverter market.
- In July 2024, AEG, a German company, has introduced new hybrid inverters designed for use in high-voltage rooftop PV systems. These inverters operate on three-phase power.
- In October 2023, Fuji Electric India, a leader in the automation industry and cutting-edge energy-efficient solutions for industry operations showed the Central solar inverter PV 1500 series at the Renewable Energy India Expo held from October 4th to 6th at Greater Noida.
- In September 2023, WattPower, one of the major renewable energy firms globally, unveiled a modernized solar inverter production plant located in Tamil Nadu’s district of Chennai as a significant move forward in India’s solar energy sector. With its new string PV inverters, it desires to make an impact on the Indian solar PV industry.
- In July 2023, LG Energy Solution Ltd., a South Korea-based battery manufacturer, introduced new hybrid inverters suitable for private electric power plants. These inverters are designed to work on both low-voltage and high-voltage setups and come with an integrated backup feature that will easily blend with their own line of batteries.
- In April 2023, SolaX Power, which is famous for manufacturing solar inverters, publicized X1-Hybrid LV, another single-phase low-voltage hybrid inverter meant for residential applications. This new technology has been devised for the efficient operation of low-voltage solar photovoltaic (PV) systems.
- In July 2023, Spinkraft Ventures Private Limited, Roofsol Energy Pvt Ltd, and Wattpower Systems Pvt Ltd together signed a ground-breaking 60 MW supply agreement. Inverters, crucial parts that transform the direct current (DC) generated by solar panels into alternating current (AC) for use in electrical systems, are to be delivered as part of the deal. As it involves one of India's top open-access developers, this project is of utmost importance. Open access permits the direct delivery of electricity from renewable energy projects to particular customers or entities, eschewing the use of the established grid infrastructure.
Market Concentration & Characteristics
The solar inverter market is moderately concentrated, with a few leading players holding significant shares, while numerous smaller companies cater to niche applications or regional markets. The market characteristics include rapid technological innovation, driven by the demand for more efficient and reliable inverters that can support both on-grid and off-grid systems. Companies are focusing on enhancing product features, such as integration with smart grids, energy storage systems, and improved energy management capabilities. Additionally, the market sees a strong emphasis on cost reduction through economies of scale, making solar energy more accessible to consumers. As a result, the market is highly competitive, with companies striving to balance affordability, performance, and technological advancement to capture market share. Furthermore, regulatory frameworks and government incentives significantly influence market dynamics, creating opportunities for new entrants while encouraging established players to upgrade their offerings continuously.
Report Coverage
The research report offers an in-depth analysis based on Type, System Type, Phase, End-Use and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The demand for solar inverters will continue to rise as renewable energy adoption accelerates globally.
- Technological advancements will focus on improving inverter efficiency, reliability, and integration with smart grid systems.
- The market will see increased adoption of micro-inverters and hybrid inverters for greater energy optimization.
- Energy storage integration with solar inverters will become more common, allowing better management of solar power.
- Cost reduction will remain a key focus, making solar energy more affordable for residential and commercial users.
- Off-grid solar inverters will experience higher demand, particularly in remote areas with limited grid access.
- Innovations in inverter design will aim at improving scalability for both small and large-scale solar installations.
- Government incentives and subsidies will continue to drive solar inverter adoption, particularly in emerging markets.
- The rise of energy management solutions will lead to more intelligent inverters capable of real-time monitoring and optimization.
- Solar inverter manufacturers will increasingly focus on expanding their product portfolios to meet the needs of diverse applications, from residential to industrial.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Government Support and Subsidies
Global and regional governments are providing tax credits, rebates, and feed-in tariffs to encourage solar adoption, directly boosting demand for solar inverters as essential system components.
Technological Advancements and Grid Integration
Continuous innovation in inverter technology, such as higher efficiency ratings and smart grid compatibility, is making solar inverters more reliable and attractive for both new and existing solar installations.
Falling Costs of Solar Technology
Declining prices for solar panels and inverters, driven by economies of scale and improved manufacturing, are making solar energy more affordable and accelerating market penetration across residential, commercial, and utility sectors.
Integration with Energy Storage
The growing trend of pairing solar inverters with battery storage systems is enabling better energy management and grid resilience, increasing the value proposition of advanced inverter solutions.
Decentralized Energy Generation
The shift toward decentralized and distributed energy systems, including rooftop and community solar, is driving demand for flexible and intelligent inverter solutions that can efficiently manage variable power flows.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the size of Solar Inverter Market?
What factors are driving the growth of the Solar Inverter market?
What are the key segments within the Solar Inverter market?
Who are the major players in this market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Central Inverter
- 1.2.2 Micro-Inverter
- 1.2.3 String Inverter
- 1.3 By Phase
- 1.3.1 Single Phase
- 1.3.2 Three Phase
- 1.4 By End-Use
- 1.4.1 Residential
- 1.4.2 Commercial and Industrial
- 1.4.3 Utilities
- 1.5 By System Type
- 1.5.1 Off Grid
- 1.5.2 On Grid
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 10,341.5 million → 2032: USD 20,008.85 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Solar Inverter Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Solar Inverter Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Solar Inverter Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Solar Inverter Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Solar Inverter Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Solar Inverter Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 Global Solar Inverter Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Solar Inverter Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 10,341.5 million → 2032: USD 20,008.85 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Solar Inverter Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Central Inverter
- 12.3.7.2 Micro-Inverter
- 12.3.7.3 String Inverter
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Phase - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Single Phase
- 12.4.7.2 Three Phase
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By End-Use - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Residential
- 12.5.7.2 Commercial and Industrial
- 12.5.7.3 Utilities
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By System Type - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Off Grid
- 12.6.7.2 On Grid
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Solar Inverter End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Solar Inverter Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Solar Inverter Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Solar Inverter Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Delta Electronics
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 ABB Ltd
- 18.4 SunPower Corporation
- 18.5 Canadian Solar Inc.
- 18.6 SolarEdge Technologies Inc.
- 18.7 Sineng Electric Co. Ltd.
- 18.8 SMA Solar Technology AG
- 18.9 Power Electronics
- 18.10 Solectria Renewables LLC
- 18.11 Hitachi Hi-Rel Power Electronics Pvt. Ltd
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

