
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
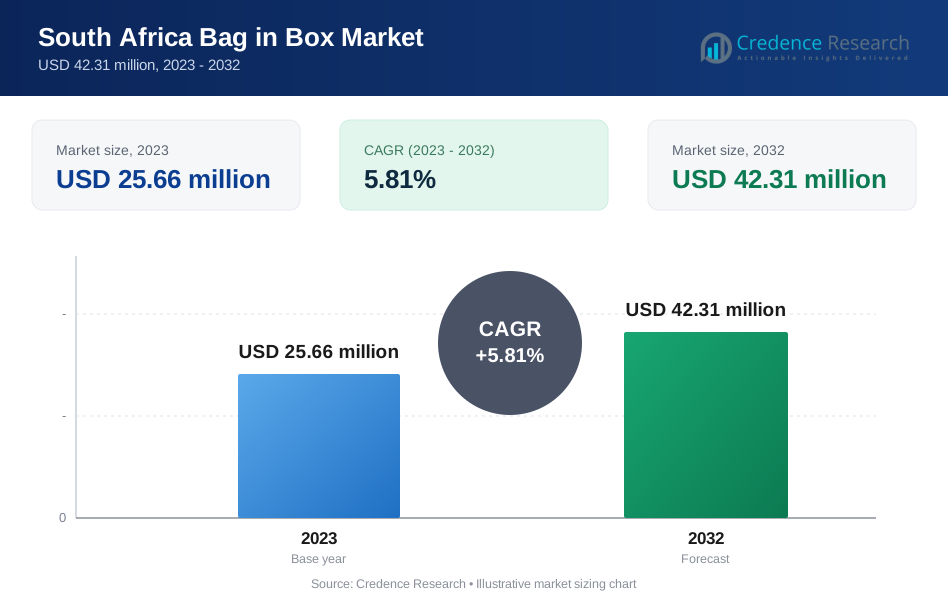
| South Africa Bag in Box Market Size 2023 | USD 25.66 Million |
| South Africa Bag in Box Market, CAGR | 5.81% |
| South Africa Bag in Box Market Size 2032 | USD 42.31 Million |
Market Overview
The South Africa Bag in Box Market is projected to grow from USD 25.66 million in 2023 to an estimated USD 42.31 million by 2032, registering a compound annual growth rate (CAGR) of 5.81% from 2024 to 2032. This growth is driven by the increasing adoption of cost-effective and eco-friendly packaging solutions for liquid products across various sectors.
Key market drivers include the growing demand for sustainable packaging options, with bag-in-box systems emerging as an environmentally friendly alternative to traditional rigid packaging. The increasing use of such solutions in sectors like beverages, particularly wine and fruit juices, and in industrial applications, bolsters market growth. Trends such as innovations in barrier films and dispensing solutions also drive the popularity of bag-in-box packaging, improving shelf life and reducing waste while meeting changing consumer and industry preferences.
Geographically, the market is primarily concentrated in major urban centers where demand for innovative packaging is high. Key players in the South Africa Bag in Box Market include Smurfit Kappa Group, Liquibox Corporation, DS Smith PLC, and CDF Corporation, who continue to focus on enhancing product capabilities and expanding their regional footprint to maintain competitiveness in a rapidly evolving market landscape.
Market Drivers
Rising Demand for Sustainable Packaging Solutions
One of the primary drivers of the South Africa Bag-in-Box Market is the increasing demand for sustainable packaging solutions. Environmental concerns have prompted consumers, industries, and regulatory bodies to prioritize eco-friendly alternatives to traditional packaging materials. Bag-in-box systems offer a lightweight, recyclable option with reduced carbon emissions during production and transportation. This type of packaging uses less material compared to rigid alternatives, reducing packaging waste and aligning with South Africa’s environmental goals. As businesses strive to meet sustainability targets and comply with stringent environmental regulations, the adoption of bag-in-box packaging is accelerating. Additionally, the growing emphasis on circular economies has encouraged companies to choose packaging formats that minimize resource use and promote recycling, further boosting the market for bag-in-box solutions.For instance, in the beverage sector, bag-in-box packaging has gained significant traction due to its ability to preserve product freshness and extend shelf life. This packaging format is particularly popular for wine, as it prevents oxidation and maintains the quality of the product over time. The wine industry in South Africa has embraced bag-in-box solutions, leveraging its lightweight design and cost-effectiveness to offer competitively priced products while ensuring the preservation of wine quality.
Growth in the Beverage Industry
The increasing consumption of wine, fruit juices, and other beverages in South Africa is a significant driver for the bag-in-box market. This packaging format is particularly popular for liquid products because of its convenience, cost-effectiveness, and ability to preserve product freshness for extended periods. Bag-in-box packaging prevents oxidation, maintains taste quality, and ensures longer shelf life, making it an ideal choice for the beverage sector. As consumer preferences shift toward premium packaging solutions that offer a combination of aesthetics, usability, and enhanced preservation, the bag-in-box format continues to witness growing adoption. The wine industry, in particular, has embraced bag-in-box packaging due to its practicality, lightweight nature, and low production costs, allowing manufacturers to offer cost-competitive products while preserving wine quality.
Advancements in Packaging Technology
Technological innovations in bag-in-box packaging have made it more functional, durable, and appealing to both consumers and businesses. Improvements in barrier films, dispensing taps, and vacuum-sealed bags have significantly enhanced the overall performance of bag-in-box systems, providing superior protection against light, air, and contamination. Such advancements enhance the shelf life of products and make them suitable for a broader range of applications, including dairy, liquid detergents, and edible oils. Additionally, the introduction of user-friendly and spill-resistant dispensing systems has improved consumer convenience, driving demand further. Technology-driven innovations have enabled companies to differentiate themselves in a highly competitive market by providing customers with enhanced product features and value-added services, positioning bag-in-box packaging as a preferred choice for various industries.
Cost-Effective Packaging Solutions
Cost efficiency is a crucial factor driving the growth of the South Africa Bag in Box Market. The packaging industry has witnessed increasing demand for affordable solutions that minimize overall production and transportation costs. Bag-in-box systems are cost-effective due to their low raw material requirements, lightweight nature, and efficient storage capabilities. Unlike rigid containers, bag-in-box packaging reduces the total cost of ownership by lowering shipping costs and optimizing storage space. This packaging format is also easily scalable, allowing manufacturers to offer tailored solutions for different product volumes while minimizing waste. The cost advantage extends to end-users, who benefit from reduced pricing for products packaged in bag-in-box systems, ultimately driving greater adoption. As a result, manufacturers are increasingly adopting this flexible packaging solution as a cost-effective alternative that meets the demands of cost-conscious markets while maintaining product quality and performance.
Market Trends
Increasing Preference for Eco-Friendly and Lightweight Packaging**
A prevailing trend in the South Africa Bag in Box Market is the heightened focus on environmentally friendly and lightweight packaging solutions. As sustainability becomes a key concern for both consumers and businesses, bag-in-box packaging has emerged as a preferred choice due to its eco-conscious design and minimal environmental impact. This type of packaging significantly reduces plastic consumption compared to traditional rigid containers, and its recyclable components align well with circular economy principles. Consumers increasingly value products packaged in environmentally friendly ways, leading manufacturers to adopt bag-in-box solutions as part of their broader sustainability goals. The lightweight nature of these systems also contributes to lower transportation costs and reduced greenhouse gas emissions, further strengthening their market appeal. As regulatory bodies and policymakers advocate for sustainable packaging, the demand for bag-in-box solutions is expected to continue on a positive trajectory. For instance, companies adopting bag-in-box solutions have observed a significant reduction in their carbon footprint, with some reporting up to an 80% decrease compared to traditional packaging methods. This shift is particularly noted among industries like beverage production, where the transition to bag-in-box aligns with broader environmental sustainability goals.
Technological Innovations Enhancing Product Features and Consumer Convenience**
Technological advancements in the South Africa Bag in Box Market are transforming the overall user experience and extending product functionality. Recent innovations have focused on improving barrier films, enhancing the durability and protective qualities of the bags to better preserve product quality and freshness. Moreover, innovations in dispensing mechanisms, such as more efficient, user-friendly taps, are creating added value by enhancing consumer convenience and minimizing spillage. Manufacturers are also developing smart packaging solutions equipped with features like tamper-evident seals and oxygen barrier technology to cater to industries requiring high levels of product integrity. This trend reflects a shift toward offering more sophisticated, functional, and customizable bag-in-box solutions tailored to the needs of diverse end-users, including beverage producers, liquid food processors, and industrial goods manufacturers. The drive for innovation ensures that the market remains competitive, responsive to changing consumer demands, and aligned with advancements in packaging technology. For instance, the compact design of bag-in-box packaging reduces transportation costs and storage space, making it an economical choice for businesses looking to optimize logistics while minimizing environmental impact.
Market Restraints and Challenges
Limited Recycling Infrastructure and Environmental Concerns**
Despite the environmentally friendly potential of bag-in-box packaging, limited recycling infrastructure in South Africa poses a significant challenge to the market’s growth. While some bag-in-box components, such as cardboard outer boxes, are recyclable, the inner bags and taps often require specialized recycling processes that are not widely available in many parts of the country. This creates challenges in achieving comprehensive waste management and can lead to higher disposal costs for consumers and businesses. Furthermore, as consumer awareness of environmental issues continues to grow, any perceived shortcomings in recyclability may negatively impact the adoption of bag-in-box solutions. Stakeholders must address these concerns by developing more widely accessible recycling programs and investing in sustainable material innovations to alleviate environmental apprehensions and solidify their eco-friendly positioning.
Competition from Alternative Packaging Solutions
The South Africa Bag in Box Market faces strong competition from other packaging solutions, including rigid containers, plastic bottles, and flexible pouches. These alternatives often provide comparable convenience and functionality, making it challenging for bag-in-box packaging to differentiate itself. Rigid containers, for example, may offer superior durability and ease of storage in certain applications, while flexible pouches continue to gain popularity due to their portability and aesthetic appeal. Additionally, the cost of raw materials and fluctuations in pricing for bag-in-box packaging components may impact its competitiveness. As market players grapple with these challenges, they must innovate and highlight the distinct advantages of bag-in-box solutions, such as superior product preservation and sustainability benefits, to maintain and expand their market share against competing packaging formats.
Market Segmentation Analysis
By Component
The market is segmented into bags, boxes, and fitments. Bags form the core of bag-in-box packaging, designed to hold and protect liquid or semi-liquid products while maintaining freshness and quality. Boxes provide structural support, ensuring durability during transportation and storage. Fitments, such as taps or spouts, enhance user convenience and minimize spillage during dispensing. Each of these components contributes to the overall functionality and performance of bag-in-box packaging, with innovations in materials and design driving demand.
By Capacity
Bag-in-box packaging is available in a range of capacities, with segments categorized into 5 to 10 liters, 10 to 15 liters, 15 to 20 liters, and others. The 5 to 10 liters segment is particularly popular for consumer products like beverages, offering convenience and manageable sizes for household use. Larger capacities, such as the 15 to 20 liters segment, cater primarily to industrial and bulk distribution applications, providing cost-effective and efficient packaging solutions for commercial-scale needs.
Segments
Based on component
- Bags
- Boxes
- Fitments
Based on Capacity
- 5 to 10 liters
- 10 to 15 liters
- 15 to 20 liters
- Others
Based on End use
- Food
- Beverages
- Chemicals
- Industrial
- Others
Based on material state
- Semi-liquid
- Liquid
Based on tap
- With Tap
- Without Tap
Based on region
- Gauteng
- Western Cape
- KwaZulu-Natal
- Eastern Cape
- Other Regions
Regional Analysis
Gauteng (35%):
Gauteng is the dominant region in the South Africa Bag in Box Market, accounting for approximately 35% of the market share. The province’s position as South Africa’s economic powerhouse is a key driver, with a high concentration of businesses, industries, and affluent consumers. Gauteng's strong demand for beverages, liquid foods, and industrial products has fueled growth in bag-in-box packaging as manufacturers and distributors seek cost-effective and sustainable solutions. The region also benefits from well-developed infrastructure, enabling efficient logistics and distribution.
Western Cape (25%):
Western Cape holds around 25% of the market share, driven by a strong presence in the beverage sector, particularly wine production. The region is home to South Africa’s largest wine-producing areas, making bag-in-box packaging a popular choice due to its practicality, cost savings, and ability to preserve product quality. The increasing emphasis on sustainability and the region’s focus on eco-friendly solutions further contribute to the demand for bag-in-box systems. Western Cape’s emphasis on innovation and high-quality packaging also makes it a key market for premium bag-in-box solutions.
Key players
- Gerresheimer AG
- ITC Limited
- Westrock India
- Hitech Plast (Hitech Group)
- Jindal Poly Films Limited
- Manjushree Technopack Ltd
- THE PACK CORPORATION
- Scholle IPN
Competitive Analysis
The South Africa Bag in Box Market is highly competitive, with key players like Gerresheimer AG, ITC Limited, and Scholle IPN leading the charge. These companies have established strong market presence through innovative packaging solutions and diverse product portfolios catering to the beverage, food, and industrial sectors. Gerresheimer AG is recognized for its high-quality, customizable packaging solutions, while Scholle IPN focuses on sustainable and innovative technologies for liquid packaging. ITC Limited and Westrock India offer robust offerings in both cost-effective and premium packaging solutions, ensuring they cater to a wide range of end-user needs. The competition is further intensified by regional players like Hitech Plast and Manjushree Technopack, who focus on regional market penetration with cost-effective, reliable products. Each company is vying for dominance by leveraging unique business strategies, technological advancements, and sustainable practices to capture market share in this rapidly growing segment.
Recent Developments
- In April 2024, Gerresheimer made a solid start to the financial year with organic revenue growth of 2.8% and an organic increase in adjusted EBITDA of 5.9%. The company's focus on innovation and customization includes the introduction of advanced dispensing systems that improve product flow and reduce waste, as well as the development of eco-friendly packaging materials, aligning with the trend towards sustainability.
- In November 2024, ITC Limited announced a collaboration with Frugalpac, a British sustainable packaging company, to bring paper Frugal Bottles to India and South Asia, including South Africa. This partnership aims to promote and grow the demand for sustainable packaging solutions in the region.
Market Concentration and Characteristics
The South Africa Bag in Box Market exhibits a moderate to high level of market concentration, with a few dominant players such as Gerresheimer AG, Scholle IPN, and ITC Limited leading the industry. These companies hold significant market share due to their established brand presence, diverse product portfolios, and ability to innovate with sustainable and cost-effective packaging solutions. The market is characterized by a strong focus on technology-driven advancements, such as improved barrier films, enhanced dispensing systems, and environmentally friendly materials. Smaller regional players also contribute to market dynamics, offering competitive pricing and tailored solutions to niche sectors. Overall, the market is driven by a mix of large multinational corporations and local suppliers, each vying to meet the growing demand for eco-friendly, versatile, and efficient packaging in the beverage, food, and industrial sectors.
Report Coverage
The research report offers an in-depth analysis based on Component, Capacity, End use, Material, Tap and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The South Africa Bag in Box Market is expected to grow steadily, driven by increasing demand for cost-effective and sustainable packaging solutions, with a CAGR of 5.81% from 2024 to 2032.
- Sustainability will remain a key driver as both businesses and consumers continue to prioritize eco-friendly packaging, with bag-in-box systems offering reduced material usage and recyclability.
- Advancements in packaging technology, such as improved barrier films and enhanced dispensing systems, will further boost the market by offering better product preservation and user convenience.
- The beverage industry, particularly wine, fruit juices, and liquid foods, will continue to be a major contributor, as bag-in-box packaging maintains its dominance due to cost-effectiveness and longer shelf life.
- As industries look for efficient, large-scale packaging solutions, the demand for bag-in-box packaging for chemicals and industrial liquids will see a significant rise.
- Regional markets, particularly outside major urban centers, will experience increased penetration, driven by rising awareness and the cost advantages of bag-in-box packaging.
- Convenience in packaging, especially with innovations such as spill-resistant taps and easy dispensing, will drive greater consumer adoption in both domestic and industrial sectors.
- With growing environmental regulations, businesses will be pushed to adopt sustainable packaging formats like bag-in-box to meet legal requirements and consumer expectations for greener solutions.
- Competition will intensify as both local and global players, such as Scholle IPN, Gerresheimer AG, and regional manufacturers, vie for market share by offering innovative and customized packaging solutions.
- Packaging manufacturers will focus on offering more tailored solutions to meet the specific needs of different sectors, providing a higher degree of customization to attract diverse customers.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the market size of the South Africa Bag in Box Market in 2023 and 2032?
What are the key drivers of growth in the South Africa Bag in Box Market?
Which industries are driving the demand for bag-in-box packaging in South Africa?
Who are the key players in the South Africa Bag in Box Market?
How does bag-in-box packaging contribute to sustainability?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 South Africa Bag in Box Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2023; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global South Africa Bag in Box Market Snapshot
- 2.1.1 Market Size – Historical (2023) & Forecast (2023-2032) (2023: USD 25.66 million → 2032: USD 42.31 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 South Africa Bag in Box Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2023 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2023
- 2.3.2 Top 10 Players by Volume Share – 2023
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. South Africa Bag in Box Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 South Africa Bag in Box Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 South Africa Bag in Box Market Drivers
- 3.3 South Africa Bag in Box Market Restraints & Challenges
- 3.4 South Africa Bag in Box Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 South Africa Bag in Box Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 South Africa Bag in Box Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, South Africa Bag in Box category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 South Africa Bag in Box Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. South Africa Bag in Box Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2023)
- 5.1.2 Global Export Volume by Country (2023)
- 5.1.3 Global Import Value by Country (2023)
- 5.1.4 Global Import Volume by Country (2023)
- 5.1.5 Net Trade Balance by Country (2023)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2023)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the South Africa Bag in Box market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 South Africa Bag in Box Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2023
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 South Africa Bag in Box Market Share Analysis – 2023
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2023)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 South Africa Bag in Box Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in South Africa Bag in Box (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New South Africa Bag in Box Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global South Africa Bag in Box Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2023 & 2032)
- 7.1.2 Channel Mix Evolution (2023-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America South Africa Bag in Box Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe South Africa Bag in Box Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific South Africa Bag in Box Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America South Africa Bag in Box Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East South Africa Bag in Box Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa South Africa Bag in Box Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. South Africa Bag in Box Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
