
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| South Korea Thermal Insulation Material Market Size 2023 | USD 2.99 million |
| South Korea Thermal Insulation Material Market, CAGR | 5.80 |
| South Korea Thermal Insulation Material Market Size 2032 | USD 4.97 million |
Market Overview
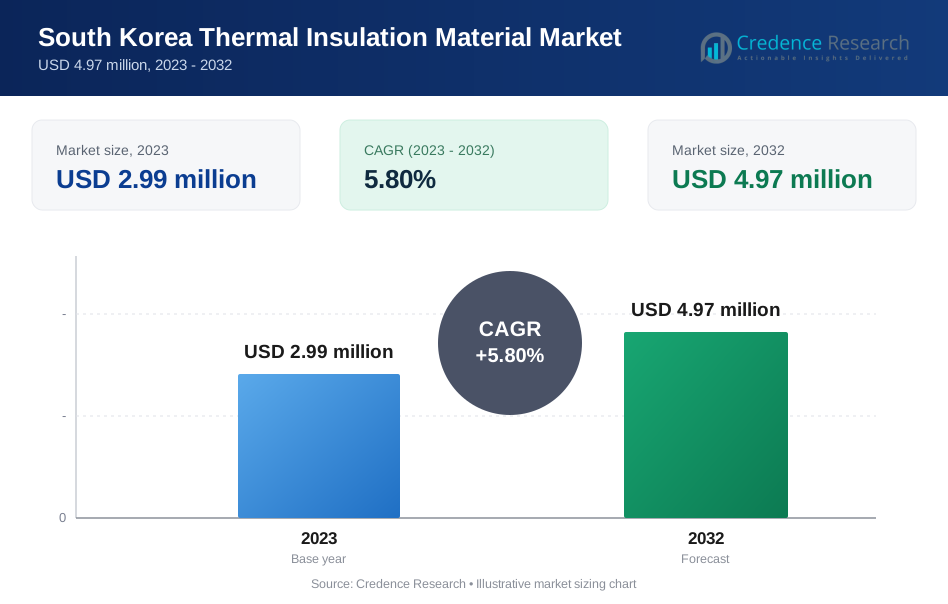
South Korea Thermal Insulation Material market size was valued at USD 2.99 million in 2023 and is anticipated to reach USD 4.97 million by 2032, at a CAGR of 5.80% during the forecast period (2023-2032).
The South Korea Thermal Insulation Material Market is driven by increasing demand for energy-efficient buildings, stringent government regulations promoting sustainable construction, and growing awareness of insulation benefits in reducing energy consumption. Rising urbanization and industrialization further fuel market expansion, as residential, commercial, and industrial sectors prioritize thermal insulation to enhance energy efficiency and lower operational costs. Additionally, advancements in insulation technologies, such as eco-friendly and high-performance materials, support market growth. Key trends include the adoption of sustainable insulation solutions, including recycled and bio-based materials, in response to stringent environmental regulations. The shift toward green building certifications and smart insulation systems also contributes to market expansion. Moreover, rising investments in infrastructure development and retrofitting projects to improve building efficiency drive demand for advanced insulation materials. With continuous innovation and regulatory support, the market is expected to experience steady growth, reinforcing its role in South Korea’s sustainable construction initiatives.
The South Korea Thermal Insulation Material Market is driven by increasing urbanization and industrial expansion across key regions, including Seoul, Gyeonggi Province, Busan, Ulsan, and Daegu. The demand for insulation materials is growing due to strict energy efficiency regulations, rising construction activities, and sustainability initiatives. Rapid infrastructure development, particularly in commercial buildings, industrial facilities, and residential complexes, is fostering the adoption of fiberglass, stone wool, foam, and eco-friendly insulation solutions. Key players operating in the market include BASF SE, Asahi Kasei Corporation, Saint-Gobain SA, Recticel, Kingspan Group, Rockwool International A/S, Owens Corning, Knauf Insulation, Evonik, and DuPont. These companies focus on product innovation, regulatory compliance, and sustainability-driven solutions to meet South Korea’s growing demand for high-performance insulation materials. Additionally, advancements in modular construction and smart insulation technologies are further driving competition and market expansion.
Market Insights
- The South Korea Thermal Insulation Material Market was valued at USD 2.99 million in 2023 and is expected to reach USD 4.97 million by 2032, growing at a CAGR of 5.80% during the forecast period.
- Rising demand for energy-efficient buildings and government regulations promoting sustainable construction are driving market growth.
- Increasing adoption of eco-friendly and high-performance insulation materials, such as bio-based and nanotechnology-based solutions, is shaping market trends.
- Major players, including BASF SE, Saint-Gobain, Owens Corning, Kingspan Group, and Rockwool International, are investing in product innovation and sustainability initiatives.
- High raw material costs and installation expenses pose challenges, affecting overall market penetration.
- Seoul and Gyeonggi Province dominate the market due to urbanization and infrastructure development, while Busan and Ulsan drive demand from the marine and industrial sectors.
- Advancements in smart insulation technologies and modular construction methods present new growth opportunities.
Market Drivers
Rising Demand for Energy-Efficient Buildings
The increasing focus on energy efficiency in the construction sector is a significant driver of the South Korea Thermal Insulation Material Market. With rising energy costs and growing concerns about carbon emissions, residential, commercial, and industrial buildings are incorporating advanced insulation materials to reduce energy consumption. For instance, a study on old public buildings in South Korea showed that green remodeling significantly reduced heating energy requirements by approximately 68.95% and cooling energy by about 35.21%. The South Korean government has implemented stringent building codes and energy efficiency regulations, encouraging the adoption of thermal insulation solutions. Additionally, initiatives such as the Green Building Certification and Energy Performance Standards promote the use of high-performance insulation materials to enhance thermal efficiency. These factors collectively drive market growth by increasing demand for insulation in both new construction projects and retrofitting initiatives.
Government Regulations and Sustainability Initiatives
Stringent environmental policies and sustainability initiatives play a pivotal role in the expansion of the thermal insulation material market in South Korea. The government has introduced various regulations mandating energy-efficient building designs and construction practices to meet carbon neutrality goals. For example, South Korea has finalized a comprehensive roadmap to achieve carbon neutrality across key industries, reinforcing its commitment to ESG principles and sustainable growth. Policies such as the Korean Green New Deal and the Low Carbon, Green Growth Act have accelerated the adoption of sustainable insulation materials, including recycled and bio-based products. Additionally, incentives such as tax benefits, subsidies, and grants for green building projects encourage builders and developers to integrate thermal insulation solutions. The push toward sustainable urban development and eco-friendly infrastructure further strengthens market demand for insulation materials that comply with regulatory standards.
Advancements in Insulation Material Technologies
Technological advancements in insulation materials significantly contribute to market expansion. Innovations in high-performance materials, such as aerogels, vacuum insulation panels, and phase-change materials, enhance thermal resistance while maintaining lightweight and eco-friendly properties. Manufacturers are also focusing on nanotechnology-based insulation solutions, which offer superior thermal performance and durability. The growing preference for smart insulation systems, which integrate IoT-enabled sensors to monitor temperature and energy efficiency, is further driving demand. Additionally, the increasing availability of fire-resistant and moisture-resistant insulation materials ensures enhanced safety and durability, making them suitable for various applications in extreme weather conditions. These advancements enable the development of cost-effective, high-performance insulation solutions, boosting market adoption across multiple industries.
Growing Infrastructure Development and Retrofitting Projects
The rapid expansion of infrastructure development and renovation projects in South Korea fuels the demand for thermal insulation materials. The government's continued investments in smart cities, commercial complexes, and residential housing projects have led to an increased need for efficient insulation solutions. For example, the mandatory green remodeling of about 30,000 old public buildings nationwide starting from 2025 underscores the need for retrofitting to improve thermal efficiency and meet updated energy standards. Additionally, the aging building stock in urban areas necessitates retrofitting to improve thermal efficiency, reduce energy consumption, and meet updated energy standards. The rising popularity of modular and prefabricated construction methods also drives insulation material demand, as these techniques require pre-installed insulation for enhanced energy efficiency. Moreover, the growth of industrial sectors such as manufacturing, cold storage, and logistics has increased the adoption of thermal insulation in warehouses and production facilities. These factors collectively contribute to the expansion of the South Korea Thermal Insulation Material Market, ensuring sustained growth in the coming years.
Market Trends
Adoption of Eco-Friendly and Sustainable Insulation Materials
The South Korea thermal insulation material market is witnessing a strong shift toward eco-friendly and sustainable insulation solutions. Increasing regulatory pressure to reduce carbon footprints and enhance energy efficiency has led to a surge in demand for recycled, bio-based, and low-emission insulation materials. For instance, the Korean government's initiatives, such as the Act on Promotion of Purchase of Green Products, have successfully stimulated the market for eco-friendly products, resulting in a significant reduction in CO2 emissions through public sector purchases. Manufacturers are focusing on developing natural fiber-based insulation such as cellulose, wool, and hemp, which offer excellent thermal resistance with minimal environmental impact. Additionally, low-VOC (volatile organic compound) insulation materials are gaining popularity due to their benefits in improving indoor air quality. As the government enforces stricter green building regulations and sustainability initiatives, the demand for environmentally responsible insulation solutions continues to grow, driving innovation and investment in next-generation thermal insulation technologies.
Technological Advancements in High-Performance Insulation
Advancements in high-performance insulation materials are revolutionizing the market, offering superior thermal efficiency, durability, and lightweight properties. The increasing adoption of aerogels, vacuum insulation panels (VIPs), and phase-change materials (PCMs) is enhancing energy efficiency across residential, commercial, and industrial applications. Nanotechnology-based insulation solutions are also gaining traction due to their ability to deliver superior thermal conductivity and fire resistance. Moreover, the integration of smart insulation technologies, such as IoT-enabled sensors for real-time thermal monitoring, is improving energy management in modern buildings. These advancements not only enhance building performance but also align with South Korea’s long-term sustainability goals, driving widespread adoption in both new constructions and retrofitting projects.
Growing Popularity of Prefabricated and Modular Construction
The increasing adoption of prefabricated and modular construction techniques is significantly influencing the demand for advanced insulation materials in South Korea. Prefabrication and modular building methods require pre-installed insulation to enhance energy efficiency and structural integrity. As South Korea experiences rapid urbanization and an increasing demand for affordable and energy-efficient housing, off-site construction methods are gaining prominence. This trend is particularly strong in commercial and industrial sectors, where modular structures offer cost-effective and time-efficient solutions. The emphasis on high-performance insulation in prefabricated buildings is expected to further drive demand for innovative insulation materials that meet thermal efficiency, fire resistance, and durability requirements.
Expanding Retrofitting and Energy-Efficiency Upgrades
A significant trend in the South Korea thermal insulation material market is the increasing focus on building retrofitting and energy-efficiency upgrades. With a large portion of the country’s building stock being older and energy-inefficient, the government is promoting renovation initiatives to enhance thermal performance and reduce energy consumption. Programs such as subsidized energy retrofitting grants encourage property owners to upgrade insulation systems, particularly in commercial and residential buildings. Additionally, stricter building codes and energy performance standards are pushing developers and businesses to adopt high-quality insulation materials in renovation projects. As retrofitting initiatives gain momentum, the demand for innovative and sustainable insulation solutions is expected to accelerate, ensuring long-term market growth.
Market Challenges Analysis
High Initial Costs and Installation Complexities
One of the primary challenges in the South Korea Thermal Insulation Material Market is the high initial costs associated with advanced insulation materials and their installation. While energy-efficient insulation solutions offer long-term savings, the upfront expenses can be a deterrent, particularly for small-scale builders and homeowners. For instance, the high cost of installing advanced insulation materials like vacuum insulation panels (VIPs) can be prohibitive due to their complex manufacturing process and the need for specialized installation skills, which increases labor costs and handling difficulties. Premium insulation materials such as aerogels, vacuum insulation panels (VIPs), and phase-change materials (PCMs) come with higher production costs, making them less accessible to budget-conscious consumers. Additionally, installation complexities further add to the total cost, as specialized expertise is often required to ensure proper insulation performance. Poorly installed insulation can lead to thermal bridging and reduced efficiency, necessitating additional repairs and maintenance. As a result, despite the benefits of thermal insulation, many construction projects opt for cheaper, lower-performance alternatives, slowing down the widespread adoption of advanced insulation technologies.
Stringent Regulations and Environmental Compliance Challenges
The stringent environmental regulations in South Korea present both opportunities and challenges for the thermal insulation material market. While sustainability-driven policies encourage the adoption of eco-friendly insulation materials, compliance with evolving standards can be a hurdle for manufacturers. Strict energy efficiency codes and emissions reduction targets require companies to invest in R&D for low-carbon and recyclable insulation materials, which can significantly increase operational costs. Moreover, meeting fire safety and building performance regulations adds another layer of complexity, as insulation materials must balance thermal efficiency, durability, and fire resistance without compromising environmental sustainability. Smaller manufacturers often struggle to keep up with these evolving compliance requirements, leading to delays in product development and market entry. Additionally, navigating the certification and approval process for new insulation technologies can be time-consuming, further restricting market expansion. Addressing these regulatory challenges is essential for ensuring sustainable growth and innovation in the South Korean thermal insulation material market.
Market Opportunities
The South Korea Thermal Insulation Material Market presents significant opportunities driven by the country’s increasing focus on energy efficiency and sustainability. The government’s commitment to carbon neutrality and green building initiatives has created a favorable environment for the adoption of advanced insulation materials. Stricter building energy codes and incentives for sustainable construction encourage developers to invest in high-performance thermal insulation solutions, such as recycled, bio-based, and nanotechnology-based materials. Additionally, the growing demand for net-zero energy buildings (NZEBs) and LEED-certified structures further supports the expansion of eco-friendly insulation products. With rising urbanization and infrastructure development, there is a strong push toward integrating insulation in both new construction projects and retrofitting initiatives, creating long-term growth opportunities for manufacturers and suppliers.
Moreover, advancements in smart insulation technologies and the adoption of modular construction methods are expanding market potential. The rise of IoT-enabled insulation systems, which provide real-time thermal performance monitoring, enhances energy management capabilities in modern buildings. Additionally, the increasing popularity of prefabricated and modular buildings requires pre-installed, high-performance insulation, driving demand for lightweight, durable, and fire-resistant materials. The expanding industrial sector, particularly in cold storage, logistics, and manufacturing, is also fueling the need for high-efficiency insulation solutions to maintain optimal thermal conditions. As the market continues to evolve, companies investing in product innovation, regulatory compliance, and sustainable manufacturing practices will be well-positioned to capitalize on these growth opportunities, reinforcing South Korea’s commitment to energy efficiency and environmental responsibility.
Market Segmentation Analysis:
By Material Type:
The South Korea Thermal Insulation Material Market is segmented by material type into fiberglass, stone wool, foam, and wood fiber, each offering unique advantages for different applications. Fiberglass insulation remains one of the most widely used materials due to its cost-effectiveness, lightweight structure, and excellent thermal resistance. It is commonly utilized in residential and commercial buildings for wall, roof, and HVAC insulation. Stone wool, known for its superior fire resistance and soundproofing capabilities, is gaining traction in high-risk industrial applications and commercial construction projects. The foam insulation segment, including polyurethane (PU), expanded polystyrene (EPS), and extruded polystyrene (XPS), is witnessing rapid growth due to its high energy efficiency and moisture resistance, making it ideal for cold storage facilities, HVAC systems, and building exteriors. Additionally, wood fiber insulation, an eco-friendly alternative, is gaining attention as sustainable construction trends rise, driven by government regulations promoting green buildings. These diverse material options allow consumers to choose insulation solutions tailored to their specific needs, supporting overall market growth.
By Temperature:
Based on temperature range, the market is categorized into 0-100°C, 100-500°C, and 500°C and above, with each segment catering to distinct industrial and commercial applications. The 0-100°C segment is predominantly used in residential and light commercial buildings, where moderate insulation is required to maintain energy efficiency and indoor comfort. Materials such as fiberglass and foam-based insulation dominate this segment due to their affordability and ease of installation. The 100-500°C segment serves industries such as automotive, manufacturing, and power generation, where higher thermal resistance is needed to withstand extreme operating conditions. Stone wool and high-density foam insulation are widely used in this category. Meanwhile, the 500°C and above segment primarily caters to high-temperature industrial processes, including steel, petrochemicals, and heavy manufacturing, where stone wool and advanced ceramic-based insulation materials provide enhanced fire protection and heat resistance. The growing demand for specialized insulation in high-temperature environments continues to drive innovation and expansion in this segment.
Segments:
Based on Material Type:
- Fiberglass
- Stone Wool
- Foam
- Wood Fiber
Based on Temperature:
- 0-100 °C
- 100-500°C
- 500°C and above
Based on End-use:
- Construction
- Automotive
- HVAC
- Industrial
- Others
Based on the Geography:
- Seoul Metropolitan Region
- Gyeonggi Province
- Busan and Ulsan Regions
- Daegu Region
Regional Analysis
Seoul Metropolitan Region
The Seoul Metropolitan Region holds the largest market share in the South Korea Thermal Insulation Material Market, accounting for approximately 35% of the total market. As the country’s economic and administrative hub, Seoul is home to high-rise commercial buildings, residential complexes, and industrial facilities, all of which require advanced insulation solutions for energy efficiency and environmental compliance. The rapid adoption of green building certifications, including LEED and South Korea’s G-SEED, has further propelled demand for high-performance insulation materials. Additionally, government regulations aimed at reducing carbon emissions in urban areas are driving investment in eco-friendly insulation solutions, such as fiberglass, stone wool, and bio-based foams. Renovation of older buildings with energy-efficient insulation is also a growing trend, contributing to sustained market expansion in this region.
Gyeonggi Province
Gyeonggi Province follows closely behind, capturing around 28% of the market share due to its expanding industrial base and rapid urbanization. As South Korea’s most populous province, Gyeonggi is experiencing a surge in residential and commercial construction, increasing the demand for thermal insulation materials. The province is also a hub for industrial manufacturing and logistics centers, where high-temperature insulation solutions play a crucial role in maintaining energy efficiency. Additionally, government incentives for sustainable construction and retrofitting projects are pushing developers to adopt fire-resistant and moisture-proof insulation materials, such as stone wool and high-density foam panels. As infrastructure development continues and prefabricated construction gains popularity, the demand for innovative and cost-effective insulation solutions is expected to grow significantly in this region.
Busan and Ulsan Regions
The Busan and Ulsan Regions collectively contribute to approximately 20% of the market share, driven by their strong industrial presence and expanding commercial infrastructure. Busan, South Korea’s largest port city, requires specialized insulation materials for marine and shipping applications, where thermal resistance and moisture control are critical. Additionally, Ulsan, a major center for petrochemicals, shipbuilding, and heavy industries, generates significant demand for high-temperature insulation materials that can withstand extreme operating conditions. The growing push for energy efficiency in industrial facilities, along with the rising adoption of fire-resistant and eco-friendly insulation materials, is expected to drive market growth in these regions. Increasing government investments in smart city projects and sustainable urban development further present opportunities for market expansion.
Daegu Region
The Daegu Region holds a market share of around 17%, supported by its expanding construction sector and growing industrial activities. As a key center for textile manufacturing and electronics production, Daegu requires specialized insulation solutions to enhance energy efficiency and fire safety in factories and production units. The region’s rising focus on green infrastructure and sustainable building projects is also encouraging developers to incorporate advanced insulation materials in both new and existing structures. Additionally, increasing government initiatives to upgrade aging buildings with high-performance insulation are driving the adoption of fiberglass, foam-based, and wood fiber insulation solutions. With continued industrial growth and urban development, Daegu’s market share is expected to see steady expansion in the coming years.
Key Player Analysis
- BASF SE
- Asahi Kasei Corporation
- Saint Gobain SA
- Recticel
- Kingspan Group
- Rockwool International A/S
- Owens Corning
- Knauf Insulation
- Evonik
- I. du Pont de Nemours and Company
- Berkshire Hathaway (Johns Manville)
- Bayer AG
- Dow Chemicals Company
- Kingspan Group PLC
- Others
Competitive Analysis
The South Korea Thermal Insulation Material Market is highly competitive, with key players such as BASF SE, Asahi Kasei Corporation, Saint-Gobain SA, Recticel, Kingspan Group, Rockwool International A/S, Owens Corning, Knauf Insulation, Evonik, and DuPont leading the industry. These companies focus on product innovation, sustainable manufacturing, and compliance with energy efficiency regulations to strengthen their market position. For instance, BASF is committed to developing energy-efficient buildings in Korea by introducing highly efficient thermal insulation materials and technologies to the construction industry. Leading players are investing in advanced insulation technologies, such as bio-based materials, aerogels, and nanotechnology-enhanced insulation, to improve thermal performance and sustainability. Additionally, strategic mergers, acquisitions, and partnerships help expand their market reach and distribution networks. Companies are also enhancing their presence in smart insulation solutions, integrating IoT-enabled monitoring for better energy efficiency. Price competitiveness remains a key factor, with manufacturers focusing on cost-effective production and localized supply chains to meet increasing demand. As South Korea tightens energy regulations, firms investing in fire-resistant, eco-friendly, and high-performance insulation materials are expected to gain a competitive edge.
Recent Developments
- In February 2025,BASF introduced Basotect® EcoBalanced, a melamine resin foam with a reduced Product Carbon Footprint (PCF).
- In February 2025,Asahi Kasei is set to present SunForce™, an easy-to-process particle foam for composite foam core applications, at JEC World 2025 in Paris.
- In September 2024, Kingspan announced Kyle McEnroe as the Managing Director at Kingspan Insulation North America.
- In May 2023, Knauf Insulation GmbH introduced Ominifit slab 32, designed for use in external wall systems of residential buildings and rain-screen facades.
Market Concentration & Characteristics
The South Korea Thermal Insulation Material Market exhibits a moderate to high market concentration, with a mix of global leaders and regional manufacturers competing for market share. Established players focus on technological advancements, product diversification, and sustainability initiatives to maintain a competitive edge. The market is characterized by strong regulatory compliance, as the government enforces stringent energy efficiency and environmental standards, driving demand for high-performance and eco-friendly insulation materials. Additionally, the industry is witnessing a shift toward smart insulation solutions, integrating IoT and energy monitoring technologies to enhance efficiency. Economies of scale and localized manufacturing play a crucial role in cost competitiveness, with major firms leveraging strategic partnerships and acquisitions to expand their reach. Despite the dominance of large corporations, small and medium-sized enterprises (SMEs) are gaining traction by offering customized and cost-effective solutions tailored to South Korea’s growing infrastructure needs.
Report Coverage
The research report offers an in-depth analysis based on Material Type, Temperature, End-use and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market is expected to witness steady growth due to increasing demand for energy-efficient buildings and stringent environmental regulations.
- Adoption of eco-friendly and sustainable insulation materials will rise as South Korea focuses on carbon neutrality and green construction.
- Advancements in nanotechnology and aerogel-based insulation will enhance thermal performance and durability.
- Smart insulation solutions integrating IoT and energy monitoring systems will gain traction in commercial and residential buildings.
- Government incentives and subsidies for energy-efficient infrastructure will drive market expansion.
- Rising construction activities in urban and industrial areas will boost the demand for high-performance insulation materials.
- Key players will continue investing in research and development to introduce innovative and cost-effective insulation solutions.
- Fire-resistant and moisture-resistant insulation materials will become more prominent due to increasing safety regulations.
- Price volatility of raw materials may pose challenges, encouraging manufacturers to explore alternative sustainable sources.
- Strategic collaborations, mergers, and acquisitions will shape market dynamics and enhance competitive positioning.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the South Korea Thermal Insulation Material Market?
What factors are driving the growth of the South Korea Thermal Insulation Material Market?
What are the key segments within the South Korea Thermal Insulation Material Market?
Who are the major players in the South Korea Thermal Insulation Material Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 South Korea Thermal Insulation Material Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2023; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global South Korea Thermal Insulation Material Market Snapshot
- 2.1.1 Market Size – Historical (2023) & Forecast (2023-2032) (2023: USD 2.99 million → 2032: USD 4.97 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 South Korea Thermal Insulation Material Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2023 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2023
- 2.3.2 Top 10 Players by Volume Share – 2023
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. South Korea Thermal Insulation Material Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 South Korea Thermal Insulation Material Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 South Korea Thermal Insulation Material Market Drivers
- 3.3 South Korea Thermal Insulation Material Market Restraints & Challenges
- 3.4 South Korea Thermal Insulation Material Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 South Korea Thermal Insulation Material Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 South Korea Thermal Insulation Material Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, South Korea Thermal Insulation Material category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 South Korea Thermal Insulation Material Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. South Korea Thermal Insulation Material Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2023)
- 5.1.2 Global Export Volume by Country (2023)
- 5.1.3 Global Import Value by Country (2023)
- 5.1.4 Global Import Volume by Country (2023)
- 5.1.5 Net Trade Balance by Country (2023)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2023)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the South Korea Thermal Insulation Material market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 South Korea Thermal Insulation Material Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2023
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 South Korea Thermal Insulation Material Market Share Analysis – 2023
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2023)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 South Korea Thermal Insulation Material Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in South Korea Thermal Insulation Material (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New South Korea Thermal Insulation Material Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global South Korea Thermal Insulation Material Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2023 & 2032)
- 7.1.2 Channel Mix Evolution (2023-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America South Korea Thermal Insulation Material Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe South Korea Thermal Insulation Material Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific South Korea Thermal Insulation Material Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America South Korea Thermal Insulation Material Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East South Korea Thermal Insulation Material Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa South Korea Thermal Insulation Material Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. South Korea Thermal Insulation Material Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
