
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Space-Based Air Traffic Control Market Size 2024 | USD 12,660 million |
| Space-Based Air Traffic Control Market, CAGR | 8.3% |
| Space-Based Air Traffic Control Market Size 2032 | USD 23,959 million |
Market Overview:
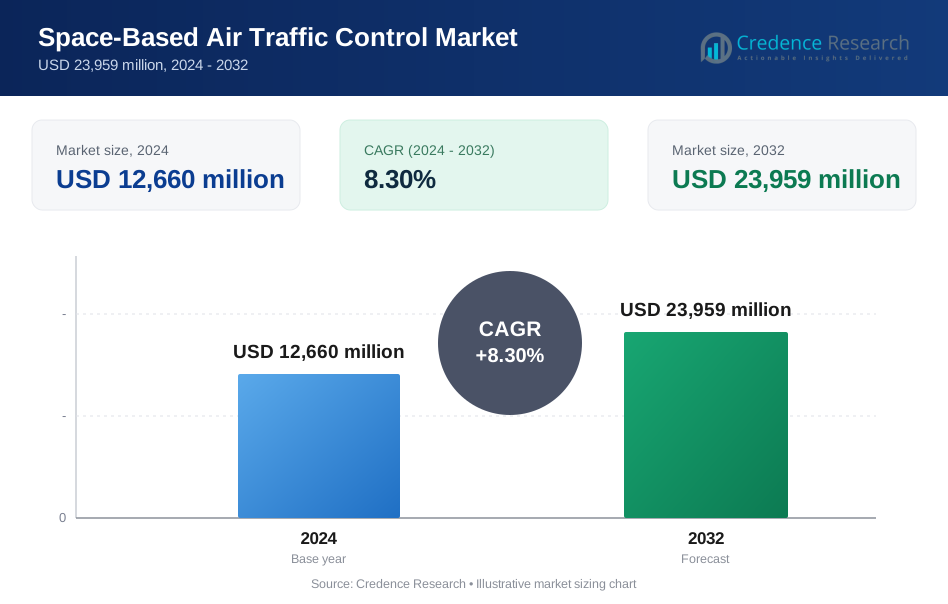
Space-Based Air Traffic Control Market size was valued at USD 12,660 million in 2024 and is anticipated to reach USD 23,959 million by 2032, at a CAGR of 8.3% during the forecast period (2024-2032).
Key drivers of the Space-Based Air Traffic Control Market include the rising number of commercial flights, the need to reduce flight delays and optimize airspace usage, and growing concerns over aviation safety. Governments and aviation authorities are prioritizing investments in space-based surveillance systems to enhance air traffic management and support next-generation airspace modernization programs. The increasing collaboration between satellite service providers and air navigation service providers (ANSPs) is further propelling adoption. These systems also contribute to fuel efficiency by supporting optimized flight paths, which aligns with the global emphasis on reducing carbon emissions in aviation. Furthermore, the adoption of these systems enhances situational awareness and operational decision-making for pilots and controllers. Advancements in satellite communication technologies are lowering latency and improving data transmission reliability.
Regionally, North America dominates the market, supported by early technology adoption, strong aerospace infrastructure, and continuous modernization efforts by the Federal Aviation Administration (FAA). Europe follows closely, driven by the Single European Sky ATM Research (SESAR) initiative and high air traffic density. The Asia-Pacific region is expected to witness the fastest growth due to rapid expansion in air travel, emerging economies’ investments in aviation infrastructure, and increasing demand for seamless air traffic monitoring across vast and often remote areas. Countries like China, India, and Japan are leading regional development through policy support and strategic investments. In contrast, Latin America and Africa are emerging markets where adoption is gaining momentum through international collaboration and funding.
Market Insights:
- The Space-Based Air Traffic Control Market is projected to grow from USD 12,660 million in 2024 to USD 23,959 million by 2032, driven by rising commercial flight operations and global airspace modernization.
- Governments and aviation authorities are investing in satellite-based systems to reduce delays, improve safety, and enable efficient use of congested airspace.
- The integration of ADS-B and satellite technologies helps airlines optimize flight paths, reduce fuel burn, and cut emissions, aligning with environmental goals.
- Real-time global tracking enhances situational awareness for pilots and controllers, lowering the risk of mid-air incidents and improving decision-making.
- North America leads with 42% share, supported by FAA initiatives and strong aerospace infrastructure; Europe follows with 28%, driven by the SESAR program.
- Asia-Pacific holds 19% share and is expected to grow fastest due to infrastructure development, air traffic growth, and government-led modernization efforts.
- High implementation costs and regulatory fragmentation remain key challenges, but global collaboration and technological innovation continue to push adoption forward.
Market Drivers:
Rising Global Air Traffic Volume Necessitates Enhanced Surveillance Solutions
The Space-Based Air Traffic Control Market is driven by the sharp rise in global air travel and the corresponding increase in commercial flight operations. Traditional radar-based systems face limitations in providing comprehensive, uninterrupted surveillance, especially over oceans and remote regions. The growing complexity of air traffic demands precise, real-time tracking to ensure safety and efficiency. Space-based solutions offer global coverage, addressing these critical surveillance gaps. Airlines and aviation regulators are turning to satellite-enabled monitoring to support increased demand and maintain operational control. The market is gaining traction as stakeholders prioritize seamless communication and aircraft visibility across all regions.
Strong Push for Airspace Optimization and Flight Efficiency
Efficient airspace utilization is a critical goal for modern air traffic management, driving the adoption of space-based systems. These technologies help reduce congestion and optimize flight routes, cutting unnecessary fuel consumption and minimizing delays. The Space-Based Air Traffic Control Market supports this objective by enabling flexible and precise navigation across densely trafficked corridors. Airlines benefit from cost savings and improved scheduling through the use of satellite-based Automatic Dependent Surveillance–Broadcast (ADS-B). Governments view these systems as essential to managing growing traffic volumes without expanding ground infrastructure. It offers a scalable solution to optimize existing airspace resources.
- For instance, NAV CANADA and NATS were the first air navigation service providers to implement Aireon’s space-based ADS-B service over the North Atlantic in 2019, resulting in reduced separation minima, enhanced safety, increased airspace capacity, and more flights receiving preferred routes and flight levels, all while reducing carbon emissions and fuel burn for airlines.
Increased Focus on Aviation Safety and Regulatory Compliance
Global aviation authorities are enforcing stricter regulations to improve aircraft safety and surveillance standards. Incidents involving lost aircraft and communication blackouts have amplified the demand for continuous, real-time tracking. The Space-Based Air Traffic Control Market addresses these issues by providing uninterrupted monitoring regardless of geography. It ensures better situational awareness for both pilots and air traffic controllers, reducing the risk of mid-air collisions and flight deviations. International aviation organizations endorse space-based surveillance as a mandatory upgrade for next-generation safety standards. Airlines and air navigation service providers (ANSPs) are accelerating investments to meet compliance deadlines.
- For instance, the Federal Aviation Administration (FAA) in the United States, the European Union Aviation Safety Agency (EASA), Australia’s Civil Aviation Safety Authority, the Directorate General of Civil Aviation (DGCA) in India, and the Civil Aviation Administration of China (CAAC) have all mandated or are phasing in requirements for ADS-B Out equipage in controlled airspace, ensuring continuous position broadcasting and regulatory compliance for aircraft operating in their jurisdictions.
Technological Advancements in Satellite Infrastructure and Communication
Rapid progress in satellite technology has made space-based air traffic control more reliable and economically viable. Low-Earth orbit (LEO) satellite constellations are enhancing signal clarity, reducing latency, and improving system responsiveness. The Space-Based Air Traffic Control Market benefits from these innovations, which support high-resolution data transfer and wider coverage. It enables accurate aircraft tracking even in data-sparse regions, strengthening global air traffic management capabilities. Commercial satellite operators and aerospace firms are forming strategic partnerships to expand infrastructure and service offerings. The market is evolving with continuous R&D in secure, high-bandwidth communication protocols.
Market Trends:
Integration of Artificial Intelligence and Automation in Air Traffic Management Systems
The Space-Based Air Traffic Control Market is witnessing a shift toward intelligent automation and AI-driven decision-making tools. AI algorithms are being deployed to analyze real-time flight data, predict traffic patterns, and identify potential safety risks. This advancement enhances situational awareness and enables faster, data-backed responses to dynamic airspace conditions. Automation is streamlining traffic coordination and reducing human error, which improves overall system reliability. It is helping air navigation service providers manage increasing flight volumes with greater precision and fewer delays. The market is adopting AI-powered platforms to optimize routing and support autonomous or semi-autonomous aircraft operations.
- For instance, Project ASTRA (a partnership including SkySoft-ATM, skyguide, INGENAV, University of Malta, and Deep Blue) is developing AI tools to predict and resolve air traffic hotspots, while Project Bluebird (a collaboration between NATS, The Alan Turing Institute, and University of Exeter) is running live trials of AI agents controlling UK airspace. London Heathrow Airport is piloting the AIMEE AI system to assist air traffic controllers in managing runway activity.
Rising Adoption of Low-Earth Orbit Satellite Constellations for Global Coverage
Satellite infrastructure is evolving rapidly with the deployment of low-Earth orbit (LEO) satellite constellations that offer low-latency and high-resolution coverage. The Space-Based Air Traffic Control Market is leveraging this trend to expand surveillance capabilities across previously inaccessible regions. These LEO networks are supporting real-time tracking of aircraft in transoceanic and polar routes, where ground-based radar is ineffective. It is enabling continuous communication between aircraft and air traffic controllers, even in remote and oceanic zones. Satellite providers are investing in next-generation systems to enhance data bandwidth, coverage density, and signal resilience. This trend is accelerating the market’s transition from legacy systems to fully space-enabled infrastructure.
- For instance, Thales, Spire Global, and ESSP have signed a memorandum of cooperation to develop an air traffic management service based on a constellation of over 100 satellites, while Aireon, using the Iridium NEXT LEO constellation, provides real-time global air traffic surveillance with its space-based ADS-B technology.Market Challenges Analysis:
High Capital Requirements and Operational Complexity Limit Adoption
The Space-Based Air Traffic Control Market faces significant barriers due to the high costs of satellite deployment, system installation, and infrastructure upgrades. Implementing space-based surveillance demands large-scale investment in satellite constellations, communication networks, and control systems. Many governments and aviation authorities in emerging economies lack the financial capacity to support such transitions. It also requires specialized technical expertise, which creates additional burdens for organizations with limited resources. Long project timelines and expensive maintenance further deter widespread implementation. These cost-related constraints slow adoption in both commercial and defense aviation sectors.
- For instance, Aireon has successfully deployed a global satellite-based ADS-B system, achieving near-global coverage and enabling airlines to meet international aircraft tracking regulations, demonstrating the feasibility and benefits of such large-scale investments in space-based air traffic surveillance.
Regulatory Fragmentation and System Integration Challenges Impede Progress
Inconsistent regulatory frameworks across international aviation jurisdictions complicate the deployment of space-based systems. The Space-Based Air Traffic Control Market must navigate varying rules related to data security, communication standards, and satellite coordination. It struggles to achieve seamless interoperability with legacy radar infrastructure, especially in regions that rely heavily on ground-based systems. Technical gaps between systems cause delays in information sharing and reduce surveillance effectiveness. Regulatory misalignment among countries complicates cross-border coordination, leading to inefficiencies in managing global airspace. These issues pose a major hurdle to achieving universal coverage and synchronized air traffic management.
Market Opportunities:
Expansion of Air Travel in Emerging Economies Opens New Growth Avenues
Rising air traffic in emerging markets presents a major opportunity for the Space-Based Air Traffic Control Market. Rapid infrastructure development in regions such as Asia-Pacific, Latin America, and Africa is increasing demand for advanced air traffic surveillance systems. These areas often lack comprehensive radar coverage, making satellite-based systems a practical solution. Governments are actively investing in aviation modernization to support growing domestic and international flight operations. It offers a scalable approach to managing expanding airspace without extensive ground infrastructure. Increased airline activity in these regions creates a strong foundation for market growth.
Demand for Seamless Global Coverage Encourages International Collaboration
Growing demand for uninterrupted global aircraft tracking creates opportunities for international partnerships and joint ventures. The Space-Based Air Traffic Control Market stands to benefit from collaborative efforts between satellite operators, air navigation service providers, and aviation authorities. It enables harmonized systems that support real-time data exchange across borders. Shared investments in space-based infrastructure can reduce costs and accelerate deployment. Increasing focus on aviation safety and environmental efficiency encourages governments to support cooperative surveillance solutions. These collaborations strengthen global connectivity and improve overall air traffic management capabilities.
Market Segmentation Analysis:
By Technology
The Space-Based Air Traffic Control Market is segmented into Automatic Dependent Surveillance–Broadcast (ADS-B), satellite communication, and global navigation satellite systems (GNSS). ADS-B holds the largest share due to its ability to provide continuous, real-time aircraft tracking, even over oceanic and remote regions. Satellite communication supports reliable two-way connectivity between aircraft and ground stations, essential for uninterrupted surveillance. GNSS enhances navigation accuracy and supports efficient routing, which improves overall traffic management. Each technology contributes to improved safety, coverage, and operational efficiency.
By Application
The market includes commercial aviation, military aviation, and unmanned aerial systems (UAS). Commercial aviation leads this segment, driven by rising passenger volumes and the need to manage high-density flight corridors efficiently. The military aviation sector is expanding its use of satellite-based systems to enhance surveillance and coordination in contested or isolated airspaces. UAS operations are growing in both civil and defense contexts, requiring reliable space-based monitoring. The application segment reflects the broad utility of these systems across different flight platforms and airspace needs.
By Component
The component segment comprises space-based infrastructure, ground stations, and receivers. Space-based infrastructure includes satellites and communication payloads, which form the core of the surveillance network. It ensures global coverage and continuous tracking capabilities. Ground stations serve as the processing hubs, receiving and distributing surveillance data to air traffic controllers. Receivers installed on aircraft capture signals and ensure data exchange across the network. Each component is essential to maintaining system performance and airspace integrity.
Segmentations:
By Technology
- Automatic Dependent Surveillance–Broadcast (ADS-B)
- Satellite Communication
- Global Navigation Satellite Systems (GNSS)
By Application
- Commercial Aviation
- Military Aviation
- Unmanned Aerial Systems (UAS)
By Component
- Space-Based Infrastructure
- Ground Stations
- Receivers
By End-User
- Air Navigation Service Providers (ANSPs)
- Airport Authorities
- Airlines
- Military Organizations
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America Leads with Early Adoption and Advanced Infrastructure
North America holds 42% of the global Space-Based Air Traffic Control Market, making it the largest regional contributor. The United States and Canada lead due to strong aerospace capabilities and early deployment of satellite-based systems. The Federal Aviation Administration (FAA) has integrated space-based surveillance into national airspace modernization programs. Canada supports regional leadership through widespread use of Automatic Dependent Surveillance–Broadcast (ADS-B) in remote territories. It benefits from a well-established network of aerospace companies, favorable policies, and consistent government funding. The region continues to drive innovation through public-private partnerships and high system reliability standards.
Europe Advances with Regional Integration and Sustainable Air Traffic Solutions
Europe accounts for 28% of the global Space-Based Air Traffic Control Market, supported by high traffic density and strong policy coordination. The Single European Sky ATM Research (SESAR) initiative plays a key role in promoting satellite-based air traffic solutions. Leading countries such as Germany, France, and the United Kingdom are investing in efficient and sustainable surveillance technologies. It enhances regional interoperability, enabling seamless coordination across national borders. Space-based systems support fuel efficiency and emission reduction efforts, aligning with Europe’s environmental goals. Regulatory harmonization and investment in innovation contribute to steady market expansion.
Asia-Pacific Emerges with Rapid Growth and Infrastructure Investments
Asia-Pacific holds 19% of the global Space-Based Air Traffic Control Market and is set to grow rapidly in the coming years. China, India, and Japan are expanding their aviation networks and adopting space-based technologies to improve flight safety and coverage. It addresses surveillance gaps in vast, remote, and underserved regions. Regional governments are prioritizing aviation modernization through satellite infrastructure investment and policy support. Increasing air travel demand and infrastructure upgrades are boosting adoption. Asia-Pacific is becoming a key growth engine for the market, supported by long-term strategic planning and regional cooperation.
Key Player Analysis:
- BAE Systems plc
- Saab AB
- Raytheon Technologies Corporation
- Thales Group
- Boeing Company
- Collins Aerospace
- Northrop Grumman Corporation
- Lockheed Martin Corporation
- Honeywell International Inc.
- Airbus SE
- Frequentis AG
- Indra Sistemas, S.A.
- L3Harris Technologies, Inc.
- Leonardo S.p.A.
- General Dynamics Corporation
Competitive Analysis:
The Space-Based Air Traffic Control Market features a competitive landscape dominated by leading aerospace and satellite technology companies. Key players include Aireon LLC, Thales Group, L3Harris Technologies, Northrop Grumman, and Honeywell Aerospace. The market is driven by continuous innovation in satellite communication, real-time tracking systems, and integration capabilities. It attracts investment from both private and government sectors focused on airspace modernization. Companies are forming strategic alliances with air navigation service providers to expand global surveillance coverage and deliver interoperable solutions. New entrants are focusing on niche technologies such as low-Earth orbit satellite networks and AI-powered analytics to differentiate offerings. It maintains a high degree of technological intensity, where performance, reliability, and regulatory compliance determine competitive advantage. Players that provide scalable infrastructure and seamless integration into national air traffic management systems strengthen their market position. Strong R&D capabilities and partnerships define the leadership in this evolving domain.
Recent Developments:
- In May 2025, Thales and Aireon announced a partnership to integrate AireonFLOW data with Thales’ TopSky – Flow Manager, delivering advanced strategic air traffic flow management solutions to reduce congestion and improve predictability for air navigation service providers.
- In June 2024, Thales, Spire Global, and ESSP announced a partnership to develop a constellation of over 100 satellites for real-time space-based air traffic surveillance, aiming for operational launch by 2027.
- In March 2024, Lockheed Martin launched Pony Express 2, a pair of small satellites demonstrating tactical communications, mesh networking, and RF sensing, which support secure, delay-tolerant data relay for air and space operations.
Market Concentration & Characteristics:
The Space-Based Air Traffic Control Market shows a moderate to high level of concentration, with a few established players controlling a significant portion of global deployments. It relies heavily on advanced satellite infrastructure, high initial investment, and long-term government contracts, which create high entry barriers. Leading companies focus on technological innovation, data accuracy, and global coverage to maintain their competitive edge. The market is characterized by strategic collaborations between aerospace firms and air navigation service providers. It demands strict regulatory compliance and system interoperability to support seamless international air traffic management. Continuous advancements in satellite communication and real-time data processing define its dynamic nature. Demand for global surveillance coverage and increased emphasis on airspace safety are reinforcing consolidation trends. The entry of private space firms and cross-sector alliances is also influencing the competitive structure.
Report Coverage:
The research report offers an in-depth analysis based on Technology, Application, Component, End-User and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Global aviation authorities are prioritizing space-based surveillance to enhance safety and efficiency in increasingly congested airspace.
- The integration of artificial intelligence and automation into air traffic management systems is expected to optimize flight operations and reduce human error.
- Deployment of low-Earth orbit satellite constellations will expand real-time tracking capabilities, especially over remote and oceanic regions.
- Emerging economies in Asia-Pacific, Latin America, and Africa are investing in space-based systems to modernize their aviation infrastructure.
- The rise of unmanned aerial systems (UAS) and urban air mobility solutions necessitates advanced traffic control mechanisms to ensure safe integration into existing airspace.
- Collaborations between satellite service providers and air navigation service providers are fostering the development of interoperable and scalable surveillance solutions.
- Environmental concerns are driving the adoption of space-based systems that enable optimized flight paths, reducing fuel consumption and emissions.
- Regulatory bodies are working towards standardizing protocols to facilitate seamless global implementation of space-based air traffic control technologies.
- Continuous advancements in satellite communication technologies are enhancing data transmission reliability and latency, crucial for real-time air traffic management.
- The market is poised for significant growth as stakeholders across the aviation industry recognize the benefits of transitioning to space-based surveillance systems.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current and projected size of the Space-Based Air Traffic Control Market?
What are the main factors driving growth in this market?
Which regions are leading in adoption of space-based air traffic control?
What role do satellite technologies play in this market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Space-Based Air Traffic Control Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Space-Based Air Traffic Control Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 12,660 million → 2032: USD 23,959 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Space-Based Air Traffic Control Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Space-Based Air Traffic Control Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Space-Based Air Traffic Control Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Space-Based Air Traffic Control Market Drivers
- 3.3 Space-Based Air Traffic Control Market Restraints & Challenges
- 3.4 Space-Based Air Traffic Control Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Space-Based Air Traffic Control Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Space-Based Air Traffic Control Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Space-Based Air Traffic Control category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Space-Based Air Traffic Control Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Space-Based Air Traffic Control Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Space-Based Air Traffic Control market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Space-Based Air Traffic Control Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Space-Based Air Traffic Control Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Space-Based Air Traffic Control Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Space-Based Air Traffic Control (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Space-Based Air Traffic Control Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Space-Based Air Traffic Control Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Space-Based Air Traffic Control Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Space-Based Air Traffic Control Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Space-Based Air Traffic Control Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Space-Based Air Traffic Control Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Space-Based Air Traffic Control Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Space-Based Air Traffic Control Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Space-Based Air Traffic Control Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
