
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Spinal Muscular Atrophy Market Size 2024 | USD 2006.5 Million |
| Spinal Muscular Atrophy Market, CAGR | 13.1% |
| Spinal Muscular Atrophy Market Size 2032 | USD 5372.04 Million |
Market Overview:
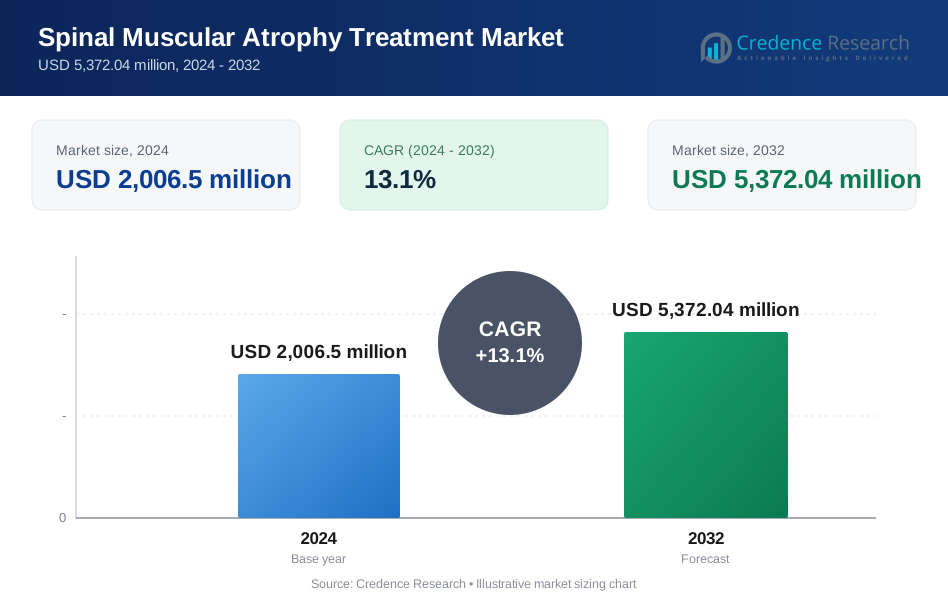
The Spinal Muscular Atrophy Market is projected to grow from USD 2006.5 million in 2024 to an estimated USD 5372.04 million by 2032, with a compound annual growth rate (CAGR) of 13.1% from 2024 to 2032.
Several key factors are driving the expansion of the SMA market. One primary driver is the growing prevalence of SMA due to enhanced diagnostic capabilities and improved awareness among healthcare providers and patients. With the adoption of newborn screening programs, SMA is being detected earlier, enabling timely interventions that can slow disease progression. Furthermore, advancements in gene therapy and innovative treatments, such as antisense oligonucleotide (ASO) therapies, are transforming the SMA treatment landscape. For instance, drugs like Spinraza (nusinersen), Zolgensma (onasemnogene abeparvovec), and Evrysdi (risdiplam) are gaining traction as they target the underlying causes of SMA, providing better clinical outcomes for patients. Additionally, increased funding for SMA research and development by governments and non-profit organizations is driving market growth. These investments are promoting the development of new therapies and treatments, expanding the range of options available for SMA patients.
The SMA market demonstrates a varied regional distribution, with North America holding a significant share due to high awareness levels, advanced healthcare infrastructure, and substantial investment in research and development. The United States, in particular, leads in terms of market share, driven by the availability of advanced therapies, strong healthcare coverage, and government support for rare disease research. Europe follows closely, with countries like Germany, the United Kingdom, and France experiencing steady demand due to well-established healthcare systems and growing adoption of genetic testing. In the Asia-Pacific region, the market is expected to witness the fastest growth, especially in countries such as Japan, China, and South Korea, where improving healthcare infrastructure and rising healthcare expenditure are enabling better access to SMA treatments. Latin America and the Middle East & Africa are anticipated to see moderate growth as awareness and healthcare access improve, though economic constraints may limit access to high-cost therapies in certain areas.
Market Drivers:
Growing Prevalence and Early Diagnosis through Newborn Screening:
One of the primary drivers of the Spinal Muscular Atrophy (SMA) market is the growing prevalence of the condition, coupled with improved diagnostic capabilities. Advances in genetic testing and the increasing adoption of newborn screening programs are allowing healthcare providers to identify SMA at an early stage. In several countries, SMA is now part of standard newborn screening, enabling early detection that paves the way for timely and effective treatment. For instance, in the United States, newborn screening for SMA was added to the Recommended Uniform Screening Panel (RUSP) in 2018. SMA affects between 1 in 6,000 to 1 in 11,000 live births. Early diagnosis is critical in SMA, as treatment at an earlier stage can significantly slow disease progression and improve long-term patient outcomes. This proactive approach to screening is expanding the patient pool eligible for SMA treatments, thereby driving demand and supporting market growth.
Advancements in Gene Therapy and Innovative Treatments:
Gene therapy and novel therapeutic approaches are revolutionizing the SMA treatment landscape. Traditional SMA treatments focused on managing symptoms; however, recent advancements target the underlying genetic causes of the disease. Therapies like Zolgensma (onasemnogene abeparvovec), an innovative gene therapy, have shown transformative potential by replacing or repairing defective genes to halt or reverse the disease’s progression. For instance, drugs like Spinraza (nusinersen) and Evrysdi (risdiplam) utilize antisense oligonucleotide (ASO) therapies that enhance the production of the SMN protein, which is crucial for motor neuron survival. SMA is estimated to affect roughly 10,000 children and adults in the United States. These advanced therapies offer enhanced efficacy and are increasingly recognized by healthcare providers as standards of care, further supporting market expansion as new drugs are approved and adopted.
Increased Funding and Research & Development Investments:
The SMA market benefits significantly from heightened funding and investment in research and development, fueled by both government and non-profit organizations. With SMA classified as a rare disease, there is considerable support for its research, as stakeholders seek to address unmet medical needs and provide new hope for patients. Government agencies, advocacy groups, and private investors are directing funds toward developing innovative treatments and improving existing therapies. This robust funding environment is fostering collaborations between biotech companies and research institutions, accelerating the pace of clinical trials and bringing new treatment options to market. As a result, the increased investment in SMA research and development is expanding therapeutic possibilities and contributing to the market's long-term growth.
Rising Awareness and Patient Advocacy Initiatives:
Rising awareness about SMA, driven by patient advocacy groups, is another key driver of market growth. Organizations such as Cure SMA and the SMA Foundation are actively working to educate the public, patients, and healthcare providers about SMA. Through outreach programs, events, and social media campaigns, these organizations highlight the importance of early diagnosis, available treatments, and the need for continued research funding. Patient advocacy has also played a role in shaping healthcare policies and influencing insurance coverage for high-cost treatments, making SMA therapies more accessible. Increased awareness not only reduces stigma but also encourages timely medical intervention, further propelling demand for SMA therapies as more individuals seek diagnosis and treatment.
Market Trends:
Shift Toward Gene Therapy and Precision Medicine:
One of the most prominent trends in the Spinal Muscular Atrophy (SMA) market is the shift toward gene therapy and precision medicine. Gene therapy offers a promising approach for SMA patients by addressing the disease at its genetic root, aiming to replace or repair faulty genes to prevent disease progression. With the approval of Zolgensma, a gene therapy that targets the defective SMN1 gene, patients now have access to treatments that offer long-term benefits with a single administration. For instance, in a clinical trial involving 15 infants with SMA, gene therapy enabled 11 of the infants to sit by themselves. This trend towards gene-based therapies highlights a move from traditional symptom management to treatments that potentially alter the disease’s natural course. As more gene therapies are researched and brought to market, the SMA landscape is expected to evolve, providing more targeted and personalized treatment options for patients.
Increasing Adoption of Antisense Oligonucleotide (ASO) Therapies:
The adoption of antisense oligonucleotide (ASO) therapies is on the rise, reflecting a broader trend in the SMA market toward innovative therapeutic approaches. ASO therapies, like Spinraza (nusinersen) and Evrysdi (risdiplam), work by modifying gene expression to increase the production of the SMN protein, which is deficient in SMA patients. These therapies have shown considerable promise, particularly for younger patients and those in early stages of the disease. Due to their proven efficacy, ASO therapies are becoming more widely accepted and are even being integrated into early treatment regimens. Additionally, ongoing research into next-generation ASO therapies is expected to enhance these treatments’ effectiveness and broaden their applicability to various SMA types and stages, reinforcing their role as a cornerstone of SMA care.
Growth of Newborn Screening and Early Intervention:
Another significant trend in the SMA market is the expansion of newborn screening programs, which enable earlier diagnosis and intervention. In recent years, more countries have incorporated SMA into their standard newborn screening panels, reflecting an increased emphasis on early detection. For instance, based on screening data, experts estimate that screening all newborns in the United States for SMA would find about 364 babies with the disorder each year. Early intervention has been shown to greatly improve treatment outcomes, as SMA is most responsive to therapies in its initial stages. Newborn screening allows healthcare providers to start treatment shortly after diagnosis, maximizing the potential for improved motor function and quality of life for affected infants. This trend is expected to continue as more countries recognize the value of early diagnosis and allocate resources toward implementing widespread screening programs, ultimately increasing the number of patients eligible for early treatment.
Collaborations and Partnerships for Enhanced R&D:
The SMA market is also seeing a rise in collaborations and partnerships among pharmaceutical companies, research institutions, and non-profit organizations. These partnerships aim to accelerate research and development, improve access to treatments, and address the unmet needs of SMA patients. Companies are increasingly joining forces to pool resources and expertise, conducting joint clinical trials and sharing data to expedite the development of new treatments. In addition to industry collaborations, partnerships with non-profit organizations and advocacy groups are helping drive awareness and promote patient-centric care models. This collaborative approach is essential in the rare disease space, where extensive research and funding are critical to advancing new therapies. As partnerships continue to grow, the pace of innovation in the SMA market is expected to accelerate, bringing more effective treatments to patients more quickly.
Market Restraints and Challenges:
High Treatment Costs and Limited Accessibility:
One of the primary challenges in the Spinal Muscular Atrophy (SMA) market is the high cost associated with advanced therapies. Gene therapies, such as Zolgensma, and other innovative treatments like Spinraza and Evrysdi are priced at premium levels, making them inaccessible for many patients, particularly in low- and middle-income regions. Although these therapies offer significant benefits, their high price tags can limit market penetration. Insurance coverage can alleviate some of these costs; however, in many regions, these therapies remain largely unaffordable. Additionally, even in countries with robust healthcare systems, access to these treatments may be restricted by reimbursement limitations, further constraining the market.
Complex and Lengthy Regulatory Approval Processes:
The SMA market also faces regulatory challenges, as the approval processes for gene and advanced therapies are often lengthy and complex. Regulatory agencies, such as the U.S. Food and Drug Administration (FDA) and the European Medicines Agency (EMA), require extensive clinical trial data to ensure safety and efficacy, which can delay new treatments from reaching the market. These hurdles are particularly pronounced for gene therapies, where long-term efficacy and safety data are essential. This regulatory complexity can slow down the pace of innovation and deter smaller companies from investing in SMA therapies. Additionally, variations in regulatory requirements across different countries can complicate the approval process, hindering global market expansion and slowing patient access to new therapies.
Limited Awareness and Delayed Diagnosis in Emerging Markets:
Despite advancements in newborn screening programs, limited awareness and delayed diagnosis remain significant challenges in emerging markets. In these regions, access to genetic testing and specialized care is often limited, and SMA may not be widely recognized among healthcare providers. Consequently, patients in these areas are often diagnosed at later stages, which can reduce the effectiveness of available treatments. Furthermore, limited awareness of SMA among the general public and healthcare providers contributes to underdiagnosis and misdiagnosis, ultimately affecting the number of patients who can benefit from timely intervention. This lack of awareness and diagnostic infrastructure in emerging markets can hinder the growth of the SMA market, as fewer patients receive early diagnosis and appropriate care.
Potential Safety Concerns and Long-Term Efficacy:
Another challenge in the SMA market is the potential for safety concerns and questions around the long-term efficacy of gene and antisense oligonucleotide therapies. While these treatments have shown positive outcomes in clinical trials, long-term effects are still being studied. Adverse events and unexpected side effects can emerge over time, particularly with gene therapies, which alter genetic material. Additionally, uncertainty about the durability of these treatments’ benefits may cause hesitation among healthcare providers and patients, impacting the market's growth. Addressing these safety concerns through ongoing research and post-market surveillance is essential for building trust and expanding the market for SMA therapies.
Market Segmentation Analysis:
By Type, the market is divided into Type I, Type II, Type III, and Type IV SMA. Type I represents the most severe form and accounts for a significant portion of the market due to early diagnosis and high demand for intensive treatments. Type II and Type III patients also contribute substantially, as they require ongoing therapeutic interventions to manage symptoms, while Type IV, being the mildest form, comprises a smaller segment with fewer treatment needs.
By Treatment, the market is segmented into gene therapies and disease-modifying drugs. Gene therapy, such as Zolgensma, targets the underlying genetic causes of SMA and has shown transformative potential, especially for Type I. Disease-modifying drugs like Spinraza and Evrysdi are widely prescribed for different SMA types, providing broader treatment options across age groups.
By Age Group, the market includes treatments for infants and adults. Infant patients, particularly those with Type I, drive significant demand as early intervention is critical. The adult segment, comprising Types II, III, and IV, benefits from ongoing treatments that improve quality of life and maintain motor function.
By Route of Administration, SMA treatments are available as oral medications and injectables. Injectable treatments, like Spinraza, are often used for young patients requiring targeted delivery, while oral options, such as Evrysdi, offer convenient home-based therapy, particularly for older children and adults.
By Distribution Channel, the market is segmented into hospital pharmacies, retail pharmacies, and online pharmacies. Hospital pharmacies hold a major share due to the need for specialist care in administering treatments, while retail and online pharmacies are increasingly popular for accessible and ongoing medication supply, especially for oral treatments.
Segmentation:
By Type:
- Type I
- Type II
- Type III
- Type IV
By Treatment:
- Gene Therapy,
- Disease-modifying drugs
By Age Group:
- Infant,
- Adult
By Route of Administration:
- Oral,
- Injectables
By Distribution Channel:
- Hospital Pharmacies
- Retail Pharmacies
- Online Pharmacies
- North America
- US
- Canada
- Mexico
- Europe
- Germany
- France
- UK
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
Regional Analysis:
North America
North America holds the largest share of the SMA market, accounting for approximately 40% of the global market. This dominance is driven by advanced healthcare systems, high levels of awareness, and substantial investment in SMA research and development. The United States, in particular, is a major contributor due to strong insurance coverage and access to innovative treatments, such as gene therapy and disease-modifying drugs. Newborn screening programs in the U.S. have facilitated early diagnosis, leading to an increased number of patients eligible for early intervention therapies. Canada also plays a role in the market, benefiting from a robust healthcare infrastructure and growing adoption of SMA therapies.
Europe
Europe represents around 30% of the global SMA market, driven by countries such as Germany, the United Kingdom, and France. The region’s large aging population and well-established healthcare systems contribute to steady demand for SMA treatments. Many European countries have integrated SMA into newborn screening programs, enabling early diagnosis and treatment, which improves patient outcomes. Additionally, supportive government policies and funding for rare disease research bolster market growth. However, market expansion can sometimes be tempered by variations in healthcare reimbursement policies across different countries, which may affect access to certain high-cost therapies.
Asia-Pacific
The Asia-Pacific region is experiencing rapid growth in the SMA market and is expected to account for around 15% of the global market share. This growth is primarily driven by increasing healthcare expenditures, improved access to medical services, and rising awareness about rare diseases. Countries such as Japan, China, and South Korea are leading the region’s market due to their advanced healthcare infrastructure and increasing investments in SMA research. Additionally, rising disposable incomes and government initiatives to improve access to rare disease treatments are contributing to market expansion. As SMA awareness and access to diagnostics improve, the Asia-Pacific market is expected to see continued growth, with a focus on both local treatment options and imported therapies.
Latin America
Latin America holds approximately 8% of the global SMA market share. The region’s market growth is supported by improving healthcare infrastructure and rising awareness of rare diseases, especially in countries like Brazil, Mexico, and Argentina. However, economic constraints and limited access to advanced therapies can hinder market expansion. Despite these challenges, ongoing efforts to improve healthcare access and increase awareness of SMA are expected to support moderate growth in this region.
Middle East & Africa
The Middle East & Africa account for around 7% of the global SMA market share. Although awareness and access to SMA treatments are gradually improving, challenges such as limited healthcare infrastructure and economic disparities persist. In wealthier countries, like the UAE and Saudi Arabia, there is increasing access to advanced SMA treatments and diagnostics. However, in many parts of the region, the availability of high-cost therapies remains limited. Growth in this region is expected to be moderate as healthcare access and awareness improve, particularly in urban areas where there is greater access to specialist care.
Key Player Analysis:
- Astellas Pharma Inc.
- Biogen
- Chugai Pharmaceutical Co.
- CYTOKINETICS
- Hoffmann-La Roche Ltd
- Genentech
- Ionis Pharmaceuticals
- NMD PHARMA A/S
- Novartis AG
- PTC Therapeutics
Competitive Analysis:
The Spinal Muscular Atrophy (SMA) market is highly competitive, with major players including Biogen, Novartis, and Roche leading due to their innovative treatments and extensive global presence. Biogen’s Spinraza (nusinersen), a widely used antisense oligonucleotide therapy, has set a strong market foundation with proven efficacy. Novartis’s gene therapy, Zolgensma (onasemnogene abeparvovec), has also gained significant traction as a one-time treatment targeting the genetic root of SMA, especially in pediatric cases. Roche’s Evrysdi (risdiplam), an oral medication, offers the convenience of at-home treatment and is rapidly gaining market share, particularly among older children and adults. These companies maintain competitive advantages through substantial R&D investments, strategic partnerships, and advocacy efforts supporting rare disease awareness. While the market is dominated by these key players, smaller biotech firms and generics manufacturers are emerging, especially in regions seeking cost-effective alternatives. As the market evolves, competition will likely intensify, with new entrants focusing on innovative therapies and broader accessibility.
Recent Developments:
- In June 2023, Biogen Inc., a multinational biotechnology company, unveiled new data on SPINRAZA (nusinersen) addressing key concerns within the spinal muscular atrophy (SMA) community. This data was presented at the SMA Research & Clinical Care Meeting hosted by Cure SMA in Orlando, U.S. SPINRAZA, approved in over 60 countries, is used to treat newborns, children, and adults with SMA, and has been administered to over 14,000 patients worldwide as a foundational SMA therapy.
- In March 2023, Novartis, a global pharmaceutical corporation, shared new findings demonstrating the transformative and long-lasting benefits of Zolgensma (onasemnogene abeparvovec), a one-time gene therapy for SMA. Recent data from two Long-Term Follow-Up (LTFU) trials, LT-001 and LT-002, indicated that Zolgensma remains efficacious and durable across various patient demographics, with a consistently favorable benefit-risk profile.
- In February 2023, Biohaven Ltd. announced it had received Fast Track designation from the U.S. Food and Drug Administration (FDA) for taldefgrobep alfa, an anti-myostatin adnectin intended for SMA treatment. This designation enables expedited development and review, allowing Biohaven more frequent FDA interactions to accelerate the availability of taldefgrobep alfa, aimed at addressing unmet medical needs in SMA care.
Market Concentration & Characteristics:
The Spinal Muscular Atrophy (SMA) market is moderately concentrated, with a few major pharmaceutical companies holding a significant share due to their pioneering treatments and extensive global reach. Key players like Biogen, Novartis, and Roche dominate, driven by their flagship therapies such as Spinraza, Zolgensma, and Evrysdi, which target different SMA types and age groups. These companies have leveraged substantial R&D investments and strong distribution networks to secure their market positions, particularly in North America and Europe. The market is characterized by a high degree of innovation, with a focus on gene therapies and disease-modifying treatments that address SMA’s underlying genetic causes. As awareness of SMA grows and diagnostic capabilities improve, the market has seen increased demand for early intervention therapies, particularly among infants diagnosed through newborn screening. Despite high treatment costs, the market is expected to expand as new players explore cost-effective alternatives and access to advanced therapies broadens in emerging regions.
Report Coverage:
The research report offers an in-depth analysis based on By Type, By Treatment, By Age Group, By Route of Administration and By Distribution Channel. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Expanding newborn screening programs worldwide will drive earlier diagnoses, increasing the number of patients eligible for early intervention treatments.
- Advances in gene therapy will lead to more targeted, potentially one-time treatments, enhancing long-term patient outcomes.
- Increased R&D investment will bring innovative therapies to market, addressing unmet needs across various SMA types and age groups.
- Rising awareness and advocacy efforts will encourage policy changes, improving access to high-cost SMA treatments.
- Development of next-generation antisense oligonucleotide therapies will enhance treatment efficacy and broaden applicability to different SMA stages.
- Growth in telemedicine and digital health tools will support patient monitoring, improving treatment adherence and long-term care.
- Expanding healthcare infrastructure in emerging markets will enable broader access to SMA treatments, driving global market growth.
- Greater competition among key players and new entrants will push innovation and may lead to more cost-effective treatment options.
- Partnerships and collaborations will accelerate clinical trials, bringing treatments to market more quickly and efficiently.
- Increased insurance coverage and government support for rare diseases will boost patient access to advanced SMA therapies.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth of the SMA Market?
What factors are driving market growth?
Which regions hold the largest market shares?
What challenges does the SMA market face?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Spinal Muscular Atrophy Treatment Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Spinal Muscular Atrophy Treatment Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 2,006.5 million → 2032: USD 5,372.04 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Spinal Muscular Atrophy Treatment Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Spinal Muscular Atrophy Treatment Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Spinal Muscular Atrophy Treatment Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Spinal Muscular Atrophy Treatment Market Drivers
- 3.3 Spinal Muscular Atrophy Treatment Market Restraints & Challenges
- 3.4 Spinal Muscular Atrophy Treatment Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Spinal Muscular Atrophy Treatment Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Spinal Muscular Atrophy Treatment Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Spinal Muscular Atrophy Treatment category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Spinal Muscular Atrophy Treatment Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Spinal Muscular Atrophy Treatment Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Spinal Muscular Atrophy Treatment market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Spinal Muscular Atrophy Treatment Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Spinal Muscular Atrophy Treatment Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Spinal Muscular Atrophy Treatment Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Spinal Muscular Atrophy Treatment (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Spinal Muscular Atrophy Treatment Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Spinal Muscular Atrophy Treatment Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Spinal Muscular Atrophy Treatment Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Spinal Muscular Atrophy Treatment Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Spinal Muscular Atrophy Treatment Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Spinal Muscular Atrophy Treatment Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Spinal Muscular Atrophy Treatment Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Spinal Muscular Atrophy Treatment Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Spinal Muscular Atrophy Treatment Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
