
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Stair Lifts and Climbing Devices Market Size 2024 | USD 2,202.5 Million |
| Stair Lifts and Climbing Devices Market, CAGR | 12.2% |
| Stair Lifts and Climbing Devices Market Size 2032 | USD 5,531.7 Million |
Market Overview:
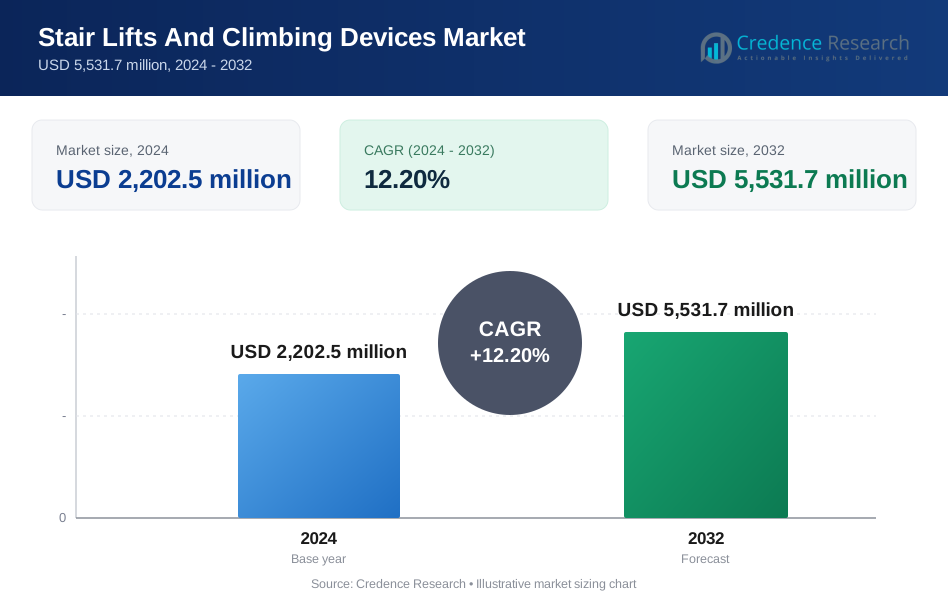
The global Stair Lifts and Climbing Devices Market size was valued at USD 2,202.5 million in 2024 and is anticipated to reach USD 5,531.7 million by 2032, at a CAGR of 12.2% during the forecast period (2024-2032).
The expansion of the stair lifts and climbing devices market is fueled by the aging global population and the increasing prevalence of musculoskeletal conditions, including arthritis and mobility impairments. World Health Organization (WHO) reports that over 1.7 billion people globally suffer from musculoskeletal disorders, driving demand for assistive mobility solutions. Governments and healthcare organizations are actively promoting accessibility solutions through subsidies and financial support, making these devices more accessible. Additionally, technological advancements, such as automated stair lifts with smart controls, foldable designs, and customizable features, are improving user convenience and broadening the appeal of these products. Rising disposable incomes and healthcare infrastructure improvements in developing economies further boost demand for these devices.
North America leads the market, accounting for the largest share due to high awareness levels, advanced healthcare infrastructure, and favorable reimbursement policies in the U.S. and Canada. For instance, Medicare and private insurance programs cover a significant portion of stair lift installation costs, encouraging adoption among elderly and disabled individuals. Europe follows closely, supported by strict accessibility regulations and an aging population, particularly in Germany, the UK, and France, where over 20% of the population is aged 65 and above. The Asia-Pacific region is the fastest-growing, driven by rapid urbanization, increasing healthcare investments, and a growing elderly population. For instance, Japan, with nearly 30% of its population over 65, has seen a surge in demand for home mobility solutions. Meanwhile, Latin America and the Middle East & Africa are gradually adopting these technologies, driven by modernization efforts and improving healthcare access, highlighting the global adoption and adaptability of stair lifts and climbing devices.
Market Insights:
- The market is projected to grow from USD 2,202.5 million in 2024 to USD 5,531.7 million by 2032, driven by rising demand for mobility solutions.
- The increasing global aging population and prevalence of mobility challenges significantly drive market growth.
- Smart features like automated controls, foldable designs, and customizations enhance user convenience and adoption.
- The high initial cost of stair lifts and climbing devices can limit adoption, particularly in developing economies.
- Leads the market due to advanced healthcare infrastructure and favorable reimbursement policies.
- Strong demand is supported by strict accessibility regulations and a growing elderly population.
- The fastest-growing region, driven by urbanization, healthcare investments, and rising disposable incomes in China and India.
Market Drivers:
Aging Population and Mobility Needs
The growing elderly population and rising prevalence of mobility challenges significantly drive demand for stair lifts and climbing devices. For instance, 35% of individuals aged 70 and the majority of those over 85 experience mobility limitations, increasing the need for assistive solutions. Studies indicate that one in five elderly individuals faces mobility impairments, with women twice as likely to require mobility assistance compared to men. Additionally, osteoporosis and osteoarthritis, which affect one in three people over age 65, contribute to higher demand for stair lifts, as mobility impairment rates continue to rise globally.
Technological Innovations
Advancements in smart integration capabilities and safety features have revolutionized stair lift systems, making them more efficient and user-friendly. Additionally, technological improvements in healthcare mobility solutions now enable remote monitoring and real-time data access, allowing healthcare providers to better assist individuals with limited mobility.
Healthcare Infrastructure Development
The expansion of healthcare infrastructure and increased focus on patient mobility solutions are key factors driving market growth. Additionally, mobility limitations are linked to increased healthcare costs, with an average increase of $2,773 per beneficiary, making investment in stair lifts and climbing devices a cost-effective solution for improving accessibility and reducing long-term healthcare expenditures.
Government Support and Accessibility Regulations
Strong governmental initiatives and accessibility regulations are propelling market expansion, particularly in aging populations where mobility limitations are prevalent. For instance, mobility limitations affect about 35% of persons aged 70, and four out of ten women aged 75 and older require mobility assistance compared to two out of ten men in the same age group. These regulations and support programs are driving higher adoption of stair lifts, improving accessibility in both residential and public spaces while addressing the increasing mobility challenges faced by aging populations worldwide.
Market Trends
Smart Technology Integration
The adoption of intelligent features is transforming stair lift operations, making them more energy-efficient and user-friendly. For instance, modern stair lift systems reduce energy consumption by 5-10% through smart controls, enhancing sustainability while maintaining high performance. Advanced obstacle detection sensors operate with 99.9% accuracy, ensuring immediate safety interventions. Additionally, built-in emergency call features allow instant communication in case of emergencies, while momentary activation switches and automatic seat locks provide instant stops and enhanced stability during use.
Environmental Sustainability
Manufacturers are prioritizing eco-friendly initiatives, reducing operational costs and environmental impact. DC-powered systems allow continued functionality during power outages, improving reliability for users. Additionally, companies are adopting zero waste-to-landfill policies and 100% renewable electricity usage, while introducing buy-back programs to extend product life cycles and minimize waste, reinforcing sustainability in stair lift production.
Enhanced Safety Features
Safety remains a top priority in modern stair lift designs, integrating advanced features to ensure user protection. For instance, modern stair lifts incorporate seat belts, automatic seat locks, and arm position switches, significantly reducing risks during operation. Obstruction sensors equipped with footrest bumper switches enable bi-directional movement if obstacles are detected, preventing accidents or abrupt stops. Additionally, smart monitoring capabilities provide multiple safety interlocks, ensuring the lift operates only when all safety conditions are met.
Space Optimization and Modularity
The industry is shifting towards compact, space-efficient solutions, catering to a variety of residential and commercial applications. Modular systems offer customization options while maintaining essential safety features, such as swivel seats that lock securely in position for added user stability. Additionally, powered footrests facilitate smooth operation without requiring users to bend, improving accessibility while optimizing space utilization in modern living environments.
Market Challenges Analysis
High Installation and Maintenance Costs
The substantial upfront costs of stair lifts and climbing devices pose significant barriers to adoption, particularly in regions with strict regulatory standards. For instance, regulatory requirements from the Bureau of Indian Standards (BIS) mandate that installations meet specific technical specifications and safety standards, adding 25-30% to implementation costs. Additionally, the Lifting Operations and Lifting Equipment Regulations (LOLER) require regular maintenance and safety checks, particularly for devices installed at vertical heights of 3 meters or more, further increasing operational expenses for users and service providers. The existence of multiple regulatory frameworks across different regions creates significant market entry challenges
Limited Insurance Coverage
The lack of comprehensive insurance coverage and reimbursement policies restricts market accessibility for individuals requiring mobility assistance. For instance, the World Health Organization (WHO) estimates that approximately 15% of the global population requires mobility aids, yet insurance programs often fail to provide adequate financial support for stair lift installations. This leads to significant out-of-pocket expenses for users, particularly affecting elderly and disabled individuals with limited financial resources. The installation of stair lifts and climbing devices requires highly specialized expertise, as custom solutions must be designed to accommodate varying building structures and safety regulations. For instance, the Maharashtra Lifts Act and similar state-specific regulations require that only licensed contractors perform stair lift installation and maintenance, ensuring compliance with safety guidelines. Additionally, authorities such as the Electrical Inspector (Lifts) impose strict safety compliance measures, increasing the complexity and cost of implementation for both residential and commercial applications.
Market Opportunities
The Stair Lifts and Climbing Devices Market presents significant growth opportunities driven by the increasing need for mobility solutions for aging populations and individuals with physical disabilities. With the global elderly population projected to exceed 1.5 billion by 2050, the demand for assistive devices that enhance accessibility and independence is expected to surge. Governments worldwide are introducing subsidies and grants to encourage the installation of stair lifts in residential and public spaces, creating a favorable environment for market expansion. Technological advancements, such as automated stair lifts with voice control, mobile app integration, and energy-efficient designs, further enhance user experience, offering manufacturers an opportunity to differentiate their products in a competitive landscape.
Emerging economies in Asia-Pacific, Latin America, and the Middle East & Africa present untapped potential due to rapid urbanization and improving healthcare access. Rising disposable incomes in these regions are enabling consumers to invest in advanced mobility solutions, while government-led initiatives to improve infrastructure accessibility further drive adoption. The growing trend of aging-in-place, where elderly individuals prefer to remain in their homes, is fueling the demand for compact and customizable stair lifts. Companies that focus on cost-effective solutions tailored to regional needs, along with durable and easy-to-install devices, can capitalize on this expanding market. The integration of sustainable materials and energy-efficient designs also aligns with global sustainability goals, presenting a promising avenue for future growth.
Market Segmentation Analysis:
By Lift Type
The Stair Lifts and Climbing Devices Market is segmented based on lift type, including straight stair lifts, curved stair lifts, and platform lifts. Straight stair lifts account for the largest market share, as they are cost-effective, easy to install, and suitable for standard staircases. For instance, straight stair lifts hold over 45% of the market due to their simpler installation process and affordability compared to customized solutions. Curved stair lifts, designed for complex staircases with turns and landings, require customized rail systems, making them more expensive but essential for homes with unique architectural layouts. Platform lifts, often used in public buildings and wheelchair-accessible spaces, are gaining traction due to increasing regulatory mandates on accessibility compliance.
By End User
The market is also segmented by end user, including residential, healthcare facilities, and public infrastructure. Residential applications dominate the market, as more elderly individuals prefer aging in place and require home mobility solutions. For instance, the global aging population has led to a 30% rise in stair lift installations in private homes over the past five years. Healthcare facilities and public infrastructure are also key segments, as hospitals, nursing homes, and government buildings integrate accessibility solutions to comply with disability regulations.
By Region
Regionally, North America dominates the market, driven by high awareness levels, advanced healthcare infrastructure, and favorable reimbursement policies. For instance, Medicare and private insurance programs in the U.S. cover significant portions of stair lift costs, encouraging wider adoption. Europe follows closely, supported by stringent accessibility regulations and an aging population, particularly in Germany, the UK, and France, where over 20% of the population is aged 65 and above. The Asia-Pacific region is the fastest-growing, fueled by rapid urbanization, increasing healthcare investments, and a rising elderly population. Meanwhile, Latin America and the Middle East & Africa are gradually adopting these technologies, driven by modernization efforts and improving healthcare access.
Segmentations:
By Lift Type:
- Stair Lifts
- Stair Climbing Wheelchairs
- Other Device Types
By End-Use:
- Hospitals
- Homecare
- Other End-uses
By Region:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
North America holds 35% of the global market share, driven by a well-established healthcare infrastructure, high awareness of mobility solutions, and supportive government programs. Additionally, Canada’s aging population, which comprises over 18% of the total population, has led to increased public investments in residential accessibility solutions, reinforcing market growth across the region.
Europe
Europe accounts for 30% of the market share, supported by stringent accessibility regulations and a growing elderly population. Additionally, Germany’s focus on inclusive living environments has resulted in significant installations of platform lifts in commercial and public buildings, ensuring enhanced mobility for individuals with disabilities. France and other European nations continue to advance accessibility measures through government subsidies and infrastructure investments, boosting market adoption across various sectors.
Asia-Pacific
Asia-Pacific emerges as the fastest-growing region, contributing 25% of the global market share, fueled by rapid urbanization, rising disposable incomes, and increasing healthcare investments. Meanwhile, Japan, known for its aging society, continues to innovate in compact and energy-efficient stair lifts, addressing space constraints and energy consumption concerns while catering to its elderly population. India is also experiencing strong growth in stair lift adoption, driven by expanding healthcare infrastructure and increased consumer awareness of home accessibility solutions.
Latin America & Middle East & Africa
Latin America and the Middle East & Africa collectively hold 10% of the market share, showcasing gradual adoption fueled by infrastructure modernization and expanded healthcare access. In the Middle East & Africa, countries like the UAE and South Africa are integrating advanced climbing devices into residential and public settings, driven by rising disposable incomes and growing awareness of mobility solutions. These regions present strong growth potential as accessibility investments continue to expand, improving quality of life for mobility-impaired individuals.
Key Player Analysis:
- Stannah Stairlifts Ltd.
- ThyssenKrupp Access Solutions
- Handicare Group AB
- Acorn Stairlifts Inc.
- Bruno Independent Living Aids, Inc.
- Otolift Stairlifts
- Platinum Stairlifts Ltd.
- Savaria Corporation
- Harmar Mobility LLC
- TK Home Solutions (formerly Thyssenkrupp Home Solutions)
Competitive Analysis:
The Stair Lifts and Climbing Devices Market is highly competitive, with key players such as Stannah Stairlifts Ltd., ThyssenKrupp Access Solutions, and Handicare Group AB dominating the industry through strong distribution networks and advanced product portfolios. These companies focus on innovation, offering automated controls, foldable designs, and energy-efficient stair lifts to enhance user experience. Mid-tier players like Otolift Stairlifts and Platinum Stairlifts Ltd. cater to niche demands, specializing in custom-designed solutions for curved and space-efficient stairlifts. Additionally, manufacturers are expanding into emerging markets, particularly in Asia-Pacific and Latin America, to capitalize on increasing demand fueled by urbanization and aging populations. The competitive landscape is further influenced by strategic partnerships and government-supported accessibility initiatives, driving continuous product development and market expansion.
Recent Developments:
- In April 2024, Stannah introduced Uplifts by Stannah, a dedicated homelift brand aimed at enhancing home accessibility with versatile and elegant solutions.
- In February 2024, Harmar launched the UP Stairlift in the United States, featuring internet connectivity for diagnostics and standard features like power seat swivel and power footrest.
- In September 2024, Platinum Stairlifts introduced uScan, an innovative application utilizing augmented reality technology for precise staircase measurements, streamlining the installation process.
- As of 2024, Otolift continues to lead in stairlift innovation, offering cutting-edge technology with precise measurements and augmented reality visualizations for a personalized user experience.
Market Concentration & Characteristics:
The Stair Lifts and Climbing Devices Market is moderately fragmented, with a mix of established global leaders and regional players competing to address diverse consumer needs. Prominent companies like Stannah Stairlifts Ltd., ThyssenKrupp Access Solutions, and Handicare Group AB dominate the market due to their extensive product portfolios, strong brand presence, and robust distribution networks. These players focus on innovation, offering advanced features such as automated controls, energy-efficient systems, and customizable designs to cater to varied user requirements. Mid-sized firms like Otolift Stairlifts and Platinum Stairlifts Ltd. are gaining traction by providing cost-effective and bespoke solutions for niche markets. The market is characterized by growing technological advancements, increasing demand for aging-in-place solutions, and rising awareness of accessibility needs. Partnerships with healthcare organizations and government-supported programs further enhance market penetration, ensuring a dynamic competitive landscape.
Report Coverage:
The research report offers an in-depth analysis based on lift type, end-use, and region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The demand for stair lifts and climbing devices will continue to grow, driven by the rising global aging population and increasing awareness of accessibility solutions.
- Technological advancements such as smart controls, app integration, and foldable designs will enhance user experience and drive adoption.
- Emerging markets in Asia-Pacific, Latin America, and the Middle East & Africa will present significant growth opportunities due to urbanization and improving healthcare infrastructure.
- The growing trend of aging-in-place will push demand for compact and customizable stair lifts tailored for residential use.
- Integration of sustainable materials and energy-efficient systems will align with global sustainability goals, attracting environmentally conscious consumers.
- Partnerships with healthcare providers and government agencies will increase the availability of financial assistance programs, boosting market penetration.
- Increased adoption of platform lifts in public and commercial spaces will support the inclusivity initiatives of governments and organizations worldwide.
- Rising disposable incomes in developing economies will enable greater investments in advanced mobility solutions, expanding the customer base.
- Enhanced safety features such as automated stops and sensors will address consumer concerns, driving broader acceptance of climbing devices.
- Manufacturers will increasingly focus on modular and easy-to-install designs to cater to the growing demand for cost-effective and user-friendly solutions.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Stair Lifts and Climbing Devices Market?
What factors are driving the growth of the Stair Lifts and Climbing Devices Market?
What are some challenges faced by the Stair Lifts and Climbing Devices Market?
Who are the major players in the Stair Lifts and Climbing Devices Market?
Which segment is leading the market share?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Stair Lifts And Climbing Devices Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Stair Lifts And Climbing Devices Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 2,202.5 million → 2032: USD 5,531.7 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Stair Lifts And Climbing Devices Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Stair Lifts And Climbing Devices Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Stair Lifts And Climbing Devices Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Stair Lifts And Climbing Devices Market Drivers
- 3.3 Stair Lifts And Climbing Devices Market Restraints & Challenges
- 3.4 Stair Lifts And Climbing Devices Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Stair Lifts And Climbing Devices Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Stair Lifts And Climbing Devices Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Stair Lifts And Climbing Devices category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Stair Lifts And Climbing Devices Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Stair Lifts And Climbing Devices Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Stair Lifts And Climbing Devices market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Stair Lifts And Climbing Devices Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Stair Lifts And Climbing Devices Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Stair Lifts And Climbing Devices Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Stair Lifts And Climbing Devices (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Stair Lifts And Climbing Devices Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Stair Lifts And Climbing Devices Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Stair Lifts And Climbing Devices Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Stair Lifts And Climbing Devices Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Stair Lifts And Climbing Devices Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Stair Lifts And Climbing Devices Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Stair Lifts And Climbing Devices Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Stair Lifts And Climbing Devices Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Stair Lifts And Climbing Devices Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
