
Market Overview:
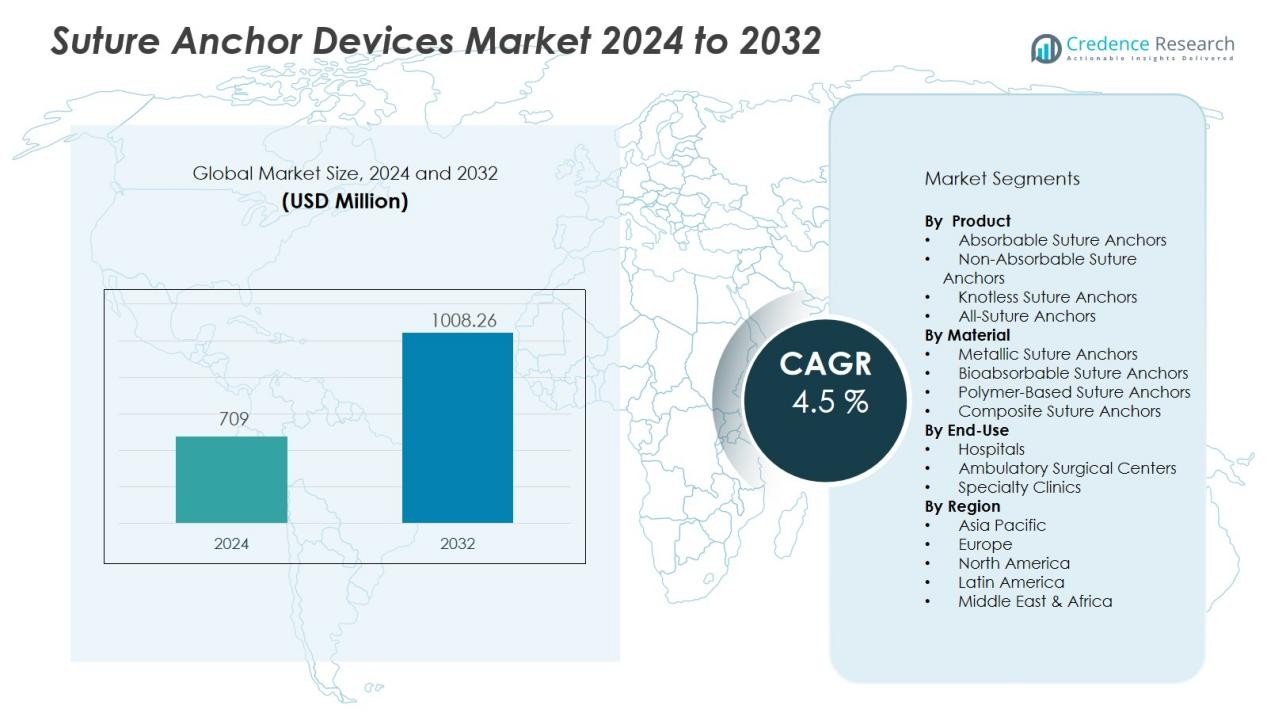
The Suture anchor devices market size was valued at USD 709 million in 2024 and is anticipated to reach USD 1008.26 million by 2032, at a CAGR of 4.5 % during the forecast period (2024-2032).
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2024 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Suture anchor devices market Size 2024 | USD 709 Million |
| Suture anchor devices market , CAGR | 4.5 % |
| Suture anchor devices market Size 2032 | USD 1008.26 Million |
Key market drivers include the growing incidence of sports-related injuries, trauma cases, and degenerative joint diseases such as rotator cuff tears and shoulder dislocations. Surgeons prefer suture anchor devices for their ability to deliver reliable fixation, faster healing, and reduced postoperative complications. Advancements in bioabsorbable and all-suture anchor technologies further enhance procedural outcomes and patient recovery times, fueling greater adoption in both routine and complex orthopedic surgeries.
Regionally, North America leads the suture anchor devices market, benefiting from a well-established healthcare infrastructure, high volume of sports medicine procedures, and robust reimbursement policies. Europe follows closely due to an aging population and expanding orthopedic care. The Asia-Pacific region is poised for the fastest growth, driven by rising healthcare investments, increasing awareness, and a large patient base requiring musculoskeletal interventions.
Market Insights:
- The suture anchor devices market reached USD 709 million in 2024 and is expected to hit USD 1,008.26 million by 2032, registering a 4.5% CAGR.
- Increased sports injuries, trauma cases, and degenerative joint diseases drive strong demand for suture anchor devices in both routine and complex orthopedic surgeries.
- Advancements in bioabsorbable and all-suture anchor technologies improve procedural outcomes, patient recovery, and device adoption.
- Surgeons and patients increasingly prefer minimally invasive procedures, supporting wider use of suture anchors in arthroscopic shoulder, knee, and hip repairs.
- North America leads the market with over 40% share, driven by advanced healthcare systems, high surgical volumes, and robust reimbursement frameworks.
- Europe follows with a 30% share, propelled by its aging population, public health infrastructure, and rapid uptake of advanced orthopedic solutions.
- Asia-Pacific shows the fastest growth, benefiting from healthcare modernization, rising awareness, increased investments, and a large patient base needing musculoskeletal interventions.
Market Drivers:
Surge in Sports Injuries and Orthopedic Procedures Elevates Demand:
The suture anchor devices market is expanding due to the increasing prevalence of sports injuries and a higher volume of orthopedic surgeries. Growing participation in professional and recreational sports has led to a rise in ligament, tendon, and joint injuries that require surgical intervention. Medical professionals are relying on suture anchor devices to ensure secure fixation and optimal healing outcomes. The expanding patient pool continues to propel adoption in both routine and complex musculoskeletal repair procedures.
- For instance, Arthrex’s SutureLoc™ implant was the first knotless, all-suture retensionable anchor specifically engineered for arthroscopic meniscal root repair, earning a Silver award at the 2024 Edison Awards and contributing to more than 1,000 new products the company develops annually
Technological Advancements Enhance Surgical Outcomes:
Innovations in suture anchor materials and designs are transforming the market landscape. Manufacturers are introducing bioabsorbable and all-suture anchors that promote better tissue integration and lower the risk of adverse reactions. It now offers improved flexibility, easier insertion, and enhanced fixation strength, addressing the diverse needs of orthopedic and arthroscopic procedures. These advancements support surgeons in delivering faster recovery and improved patient satisfaction.
- For instance, the Mitek ESP poly-L-lactic acid absorbable anchor reached a pull-out strength of 30 lbf by six weeks post-implantation in a ram femur model.
Preference for Minimally Invasive Solutions Drives Adoption:
Surgeons and patients are choosing minimally invasive procedures to reduce hospital stays and speed up rehabilitation. The suture anchor devices market benefits from this shift, with products designed for arthroscopic use gaining traction in shoulder, knee, and hip repairs. It provides smaller incision options and enables less postoperative pain, making these devices preferred in both ambulatory and inpatient settings. Health systems recognize the efficiency and cost-effectiveness of these solutions.
Rising Aging Population and Chronic Disease Burden Influence Growth:
A growing geriatric population and the rising burden of chronic musculoskeletal conditions support long-term market expansion. Older adults often present with degenerative joint diseases, rotator cuff tears, and weakened ligaments that require surgical repair. The suture anchor devices market meets the needs of this demographic by delivering durable, reliable fixation options. Increased life expectancy and greater healthcare access are set to sustain demand over the forecast period.
Market Trends:
Rapid Adoption of Bioabsorbable and All-Suture Anchor Technologies:
The shift toward bioabsorbable and all-suture anchor technologies defines a key trend in the suture anchor devices market. Hospitals and surgical centers are selecting bioabsorbable anchors to eliminate the need for removal and reduce long-term complications. Surgeons favor all-suture anchors for their flexibility, lower profile, and strong fixation in soft tissue repairs. It supports improved post-operative outcomes and patient comfort. Research and development investments are leading to next-generation devices with enhanced biocompatibility and performance. Regulatory approvals for innovative materials and products fuel commercial availability and physician adoption worldwide.
- For instance, Acuitive Technologies’ CITREFIX Knotless Suture Anchor achieved FDA 510(k) clearance in 2021 for its use of novel CITREGEN material, a synthetic polymer designed to aid natural tissue regeneration and reduce chronic inflammation, based on more than 15 years of academic research and five years of proprietary development.
Integration of Advanced Imaging and Navigation Tools in Orthopedic Surgery:
Another notable trend is the integration of advanced imaging and navigation tools in orthopedic and arthroscopic procedures. Surgeons now utilize intraoperative imaging and computer-assisted navigation to improve precision when placing suture anchors. It ensures optimal device positioning, reduces surgical risks, and enhances long-term repair integrity. The suture anchor devices market reflects this trend through partnerships between device manufacturers and digital health companies. Companies continue to launch anchors that are compatible with real-time imaging and robotic-assisted systems. Hospitals and specialty clinics prioritize these integrated solutions to achieve better clinical outcomes and strengthen patient satisfaction.
- For instance, Medtronic’s O-arm® imaging with its navigation platform reduced the anchor penetration rate in glenoid zone III from 40.9% to 15.7% in a pilot arthroscopic capsulolabral repair study involving 20 surgeries.
Market Challenges Analysis:
Stringent Regulatory Requirements and High Approval Costs Hinder Market Expansion:
Stringent regulatory requirements and high approval costs create significant barriers for new entrants in the suture anchor devices market. Companies must meet rigorous quality, safety, and clinical efficacy standards before product launches. It faces lengthy and expensive approval timelines across major markets such as the United States and Europe. Compliance with evolving regulations requires ongoing investments in research, documentation, and product testing. Smaller manufacturers often struggle to compete with established players due to resource constraints. Delays in regulatory clearance can limit market reach and slow innovation.
Cost Sensitivity and Reimbursement Challenges Affect Adoption Rates:
Cost sensitivity among healthcare providers and variable reimbursement policies challenge market growth. Hospitals and surgical centers operate within budgetary constraints that affect procurement decisions. The suture anchor devices market must address concerns about cost-effectiveness while demonstrating clinical value. It encounters disparities in insurance coverage and reimbursement rates across regions, which impact access to advanced devices. Pricing pressures can reduce margins and affect the pace of technology adoption, especially in price-sensitive emerging markets. These financial challenges require strategic adaptation by industry players.
Market Opportunities:
Emergence of Minimally Invasive and Outpatient Orthopedic Procedures Creates Growth Prospects:
The emergence of minimally invasive and outpatient orthopedic procedures creates significant growth prospects for the suture anchor devices market. Hospitals and ambulatory surgical centers increasingly favor arthroscopic techniques that require advanced fixation solutions. It addresses the demand for devices that enable shorter recovery periods and lower complication risks. Surgeons prefer these devices for their ease of use and ability to facilitate rapid patient turnover. Health systems benefit from cost savings and improved operational efficiency by expanding their minimally invasive surgery offerings. The growing trend toward same-day discharge supports wider market adoption.
Untapped Potential in Emerging Markets and Sports Medicine Applications:
Expanding healthcare infrastructure and rising awareness of sports injury management present new opportunities in emerging regions. The suture anchor devices market can capture growth by targeting countries with increasing healthcare spending and evolving orthopedic care standards. It supports the needs of both trauma and sports medicine specialists who require reliable fixation devices. Manufacturers introducing affordable and innovative products can gain early market leadership in these high-potential geographies. Stronger physician education and training initiatives will accelerate technology adoption. Strategic collaborations with local distributors and healthcare providers further expand reach and market share.
Market Segmentation Analysis:
By Product:
The suture anchor devices market segments by product into absorbable and non-absorbable anchors, with knotless and all-suture designs gaining traction. It sees strong demand for knotless anchors due to reduced surgical time and simplified procedures. All-suture anchors appeal to surgeons for their flexibility and minimal invasiveness, especially in arthroscopic repairs. Non-absorbable anchors maintain relevance for procedures requiring long-term fixation. Manufacturers focus on expanding portfolios to address diverse orthopedic and sports medicine needs.
- For example, the Arthrex FiberTak all-suture anchor requires only a 1.8mm diameter bone tunnel, preserving more bone while maintaining excellent fixation strength comparable to traditional solid anchors.
By Material:
Material segmentation includes metallic, bioabsorbable, and polymer-based anchors. The market sees rapid growth in bioabsorbable and composite materials, driven by the need for biocompatibility and elimination of removal procedures. Metallic anchors remain in demand for their strength and reliability in high-load applications. It continues to witness product launches featuring advanced polymers and hybrid materials that optimize strength, healing, and patient safety.
- For instance, Smith+Nephew's HEALICOIL KNOTLESS bioabsorbable anchor utilizes the REGENESORB material, which is designed to be absorbed and replaced by bone within 24 months, optimizing healing and patient safety.
By End-Use:
End-use segmentation covers hospitals, ambulatory surgical centers, and specialty clinics. Hospitals account for the largest share, supported by high procedure volumes and access to advanced surgical technology. Ambulatory surgical centers register notable growth, driven by demand for minimally invasive and outpatient orthopedic procedures. Specialty clinics increasingly adopt advanced suture anchor devices for targeted musculoskeletal and sports injury management. The suture anchor devices market aligns product development and distribution strategies to cater to each end-use segment’s unique requirements.
Segmentations:
By Product:
- Absorbable Suture Anchors
- Non-Absorbable Suture Anchors
- Knotless Suture Anchors
- All-Suture Anchors
By Material:
- Metallic Suture Anchors
- Bioabsorbable Suture Anchors
- Polymer-Based Suture Anchors
- Composite Suture Anchors
By End-Use:
- Hospitals
- Ambulatory Surgical Centers
- Specialty Clinics
By Region:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
- Smith & Nephew, plc.
- Arthrex, Inc.
- Stryker
- Johnson & Johnson Services, Inc.
- Zimmer Biomet Holdings, Inc.
- CONMED Corporation
- Enovis Corporation
- Medtronic
- Parcus Medical, LLC
- OrthoMed, Inc.
Key Player Analysis:
North America :
North America holds a market share exceeding 40% in the suture anchor devices market, supported by a mature healthcare system and high volumes of orthopedic and sports medicine procedures. It benefits from advanced surgical technologies, widespread adoption of minimally invasive techniques, and strong reimbursement frameworks. The region features a high concentration of specialized surgeons and well-equipped hospitals. Continuous investments in research and product innovation keep North America at the forefront of clinical advancements. Regulatory clarity and established quality standards streamline device approvals. Sports-related injuries and an active population further boost demand for suture anchor solutions.
Europe :
Europe secures a market share of roughly 30%, driven by a rising geriatric population and increased prevalence of musculoskeletal disorders. The suture anchor devices market in Europe benefits from expanding access to orthopedic care and robust public health systems. Countries such as Germany, France, and the United Kingdom contribute significantly to market demand through strong surgical infrastructure and established medical training programs. The adoption of bioabsorbable and advanced suture anchor devices continues to gain traction in both public and private hospitals. Regulatory harmonization across the European Union accelerates product launches. Ongoing emphasis on quality of life improvements supports steady growth in the region.
Asia-Pacific :
Asia-Pacific accounts for nearly 20% market share and demonstrates the fastest growth rate among all regions. Healthcare infrastructure modernization and rising awareness of advanced orthopedic procedures drive strong demand in China, India, Japan, and Southeast Asia. The suture anchor devices market capitalizes on growing investments from both public and private sectors. A large, underserved patient base and increasing sports participation further expand procedural volumes. Manufacturers introduce cost-effective and innovative solutions to meet diverse clinical needs. Partnerships with local healthcare providers enhance distribution and accelerate technology adoption across emerging economies.
Competitive Analysis:
The suture anchor devices market features intense competition, led by established global players such as Smith & Nephew, plc., Arthrex, Inc., Stryker, Johnson & Johnson Services, Inc., Zimmer Biomet Holdings, Inc., and CONMED Corporation. These companies invest in research and development to introduce innovative products that address evolving clinical needs. It emphasizes advancements in bioabsorbable, knotless, and all-suture anchors to strengthen market share and differentiate portfolios. Firms focus on strategic acquisitions, partnerships, and physician training to expand global reach and support clinical adoption. Regulatory compliance and product quality remain critical for maintaining competitive advantage. The suture anchor devices market values robust distribution networks and after-sales support, ensuring customer loyalty and consistent procurement across hospitals and surgical centers.
Recent Developments:
- In June 2025, marked Arthrex’s launch of the Synergy Power™ system, a battery-powered surgical instrument platform for sports medicine, arthroplasty, trauma, and distal extremities procedures.
- In April 2025, Johnson & Johnson Services, Inc. completed the acquisition of Intra-Cellular Therapies, Inc.
- In April 2025, Zimmer Biomet Holdings, Inc. completed the acquisition of Paragon 28, a leader in foot and ankle orthopedics.
Market Concentration & Characteristics:
The suture anchor devices market demonstrates moderate to high market concentration, with a few leading multinational companies holding significant shares. It features a mix of established medical device firms and emerging players focused on technological innovation and specialty products. Competitive dynamics center on product quality, regulatory compliance, clinical outcomes, and distribution reach. Major companies invest in research, product launches, and global expansion to strengthen their positions. The suture anchor devices market emphasizes high standards for safety, efficacy, and biocompatibility, driving continual product improvement. Strategic alliances, acquisitions, and physician training programs play a critical role in shaping market structure and competitive advantages.
Report Coverage:
The research report offers an in-depth analysis based on Product, Material, End-Use and Region. It details leading Market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current Market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven Market expansion in recent years. The report also explores Market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on Market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the Market.
Future Outlook:
- Demand for suture anchor devices will rise with increasing orthopedic and sports medicine procedures worldwide.
- Technological innovation will focus on bioabsorbable, all-suture, and knotless anchor designs to improve clinical outcomes.
- Surgeons will adopt minimally invasive arthroscopic techniques, further driving product utilization in joint repairs.
- Healthcare systems will prioritize solutions that offer quicker patient recovery and reduced postoperative complications.
- Emerging economies in Asia-Pacific and Latin America will provide new growth opportunities as healthcare infrastructure expands.
- Leading manufacturers will strengthen market positions through product launches, acquisitions, and global partnerships.
- Physician education and advanced training programs will accelerate adoption of new anchor technologies in both public and private sectors.
- Rising awareness of sports injuries and the need for effective musculoskeletal repair will sustain market momentum.
- Hospitals and ambulatory surgical centers will increase procurement of advanced anchor devices for both trauma and elective procedures.
- Integration of digital health and navigation tools in orthopedic surgery will enhance precision and improve long-term outcomes for patients.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Incidence of Sports Injuries and Trauma
Increasing participation in sports and physical activities has led to a higher prevalence of ligament, tendon, and joint injuries, driving demand for suture anchor devices in both routine and complex orthopedic surgeries.
Technological Advancements in Anchor Materials and Designs
Innovations such as bioabsorbable and all-suture anchors offer improved biocompatibility, flexibility, and fixation strength, resulting in better patient outcomes and faster recovery, which accelerates adoption among surgeons.
Preference for Minimally Invasive and Arthroscopic Procedures
Surgeons and patients increasingly favor minimally invasive techniques, such as arthroscopy, which require advanced suture anchor devices for smaller incisions, reduced postoperative pain, and quicker rehabilitation.
Aging Population and Chronic Musculoskeletal Disorders
The growing geriatric population is more susceptible to degenerative joint diseases and rotator cuff tears, increasing the need for reliable fixation solutions like suture anchors in orthopedic repairs.
Expansion of Healthcare Infrastructure in Emerging Markets
Modernization of healthcare systems, rising awareness, and increased investments in regions like Asia-Pacific and Latin America are expanding access to advanced orthopedic procedures, fueling market growth.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for suture anchor devices, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the suture anchor devices market projected to grow between 2024 and 2032?
Which suture anchor devices market segment held the largest share in 2024?
What are the primary factors fueling the growth of the suture anchor devices market?
Who are the leading companies in the suture anchor devices market?
Which region commanded the largest share of the suture anchor devices market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End-Use
- 1.2.1 Hospitals
- 1.2.2 Ambulatory Surgical Centers
- 1.2.3 Specialty Clinics
- 1.3 By Product
- 1.3.1 Absorbable Suture Anchors
- 1.3.2 Non-Absorbable Suture Anchors
- 1.3.3 Knotless Suture Anchors
- 1.3.4 All-Suture Anchors
- 1.4 By Material
- 1.4.1 Metallic Suture Anchors
- 1.4.2 Bioabsorbable Suture Anchors
- 1.4.3 Polymer-Based Suture Anchors
- 1.4.4 Composite Suture Anchors
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 709 million → 2032: USD 1,008.26 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Suture Anchor Devices Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Suture Anchor Devices Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Suture Anchor Devices Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Suture Anchor Devices Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Suture Anchor Devices Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Suture Anchor Devices Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Suture Anchor Devices Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Suture Anchor Devices Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 709 million → 2032: USD 1,008.26 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Suture Anchor Devices Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End-Use - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Hospitals
- 12.3.7.2 Ambulatory Surgical Centers
- 12.3.7.3 Specialty Clinics
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Product - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Absorbable Suture Anchors
- 12.4.7.2 Non-Absorbable Suture Anchors
- 12.4.7.3 Knotless Suture Anchors
- 12.4.7.4 All-Suture Anchors
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Material - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Metallic Suture Anchors
- 12.5.7.2 Bioabsorbable Suture Anchors
- 12.5.7.3 Polymer-Based Suture Anchors
- 12.5.7.4 Composite Suture Anchors
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Suture Anchor Devices End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Suture Anchor Devices Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Suture Anchor Devices Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Suture Anchor Devices Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Smith & Nephew plc
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Arthrex, Inc.
- 18.4 Stryker
- 18.5 Johnson & Johnson Services, Inc.
- 18.6 Zimmer Biomet Holdings, Inc.
- 18.7 CONMED Corporation
- 18.8 Enovis Corporation
- 18.9 Medtronic
- 18.10 Parcus Medical, LLC
- 18.11 OrthoMed, Inc.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

