
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Chronic Pain Market Size 2023 | USD 434.62 Million |
| Chronic Pain Market, CAGR | 3.56% |
| Chronic Pain Market Size 2032 | USD 605.72 Million |
Market Overview
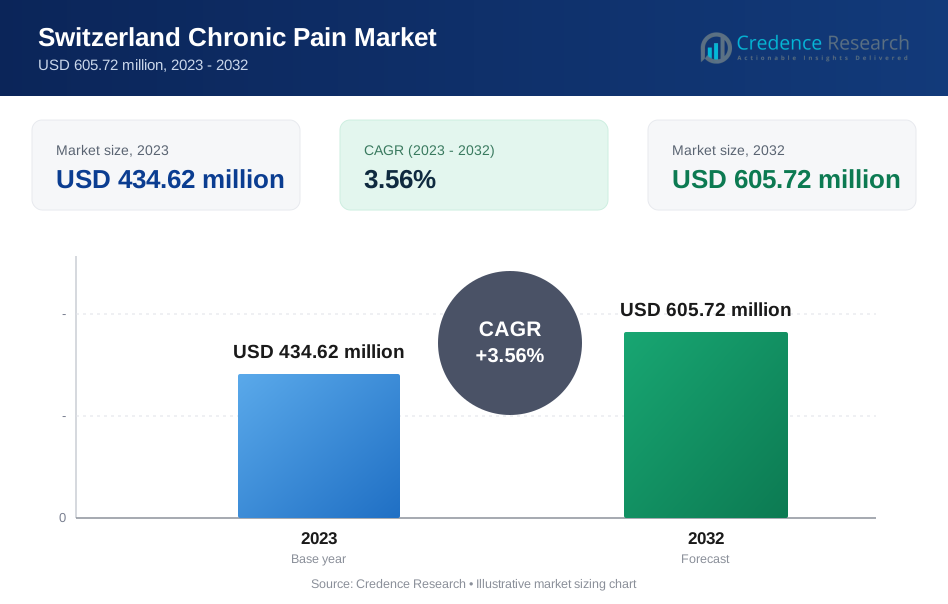
The Chronic Pain Market in Switzerland is projected to grow from USD 434.62 million in 2023 to USD 605.72 million by 2032, registering a compound annual growth rate (CAGR) of 3.56% during the forecast period.
The Switzerland chronic pain market is driven by the increasing prevalence of chronic pain conditions, such as back pain, arthritis, and neuropathic pain, among the aging population. Advances in pain management therapies, including the growing adoption of opioid alternatives, biologics, and non-invasive treatments, are also fueling market growth. Additionally, a rising awareness of chronic pain's impact on quality of life is encouraging both healthcare providers and patients to seek better management solutions. The integration of digital health technologies and telemedicine is another key trend, providing patients with more accessible care options and remote monitoring capabilities. Moreover, ongoing research and development in personalized medicine and pain management innovations are further shaping the market's trajectory. As healthcare systems in Switzerland evolve to address these challenges, the demand for effective and tailored chronic pain treatments is expected to grow, supporting market expansion.
Switzerland's chronic pain market is characterized by strong healthcare infrastructure and growing demand for effective pain management solutions across the country. Key players in the Swiss market include leading pharmaceutical and biotechnology companies such as Abbott Laboratories, Pfizer Inc., and Eli Lilly & Company, which offer a broad range of pain management drugs. Other prominent players include Cara Therapeutics and F. Hoffmann-La Roche AG, known for their advanced treatment options in neuropathic and cancer-related pain. Additionally, companies like Merck & Co. Inc. and Sanofi (via Chattem) play significant roles in providing both pharmacological and non-pharmacological solutions. The healthcare landscape in Switzerland is marked by an increasing shift towards personalized treatment approaches, digital health solutions, and non-invasive therapies, driving collaboration among these key players. With a focus on advanced pain management technologies and holistic treatments, these companies contribute to the ongoing development and accessibility of chronic pain care in Switzerland.
Market Insights
- The Switzerland chronic pain market was valued at USD 434.62 million in 2023 and is projected to reach USD 605.72 million by 2032, growing at a CAGR of 3.56%.
- Aging population is a key driver, leading to an increased prevalence of chronic pain conditions.
- Rising healthcare expenditure and government investments in pain management therapies also fuel market growth.
- Technological advancements, including neuromodulation devices and minimally invasive procedures, are expanding treatment options.
- Lack of awareness and misdiagnosis remain significant challenges in timely treatment.
- Geographic disparities, particularly in rural areas, limit access to specialized pain care.
- German-speaking Switzerland holds the largest market share, while French-speaking Switzerland is experiencing steady growth in demand for innovative pain management solutions.
Market Drivers
Aging Population
Switzerland’s aging population significantly impacts the chronic pain market, with the increasing prevalence of conditions such as arthritis, fibromyalgia, and neuropathic pain. As the population continues to age, the number of individuals suffering from chronic pain conditions rises, placing greater demand on healthcare services and treatments. For instance, a study found that almost half of people over 65 living at home report at least one chronic illness, with a significant portion suffering from multiple chronic conditions. This demographic shift is expected to continue driving market growth as more people require effective pain management solutions to improve their quality of life. The rising prevalence of these conditions among older adults is contributing to higher healthcare expenditure, as long-term pain management becomes a necessity.
Rising Healthcare Expenditure
The aging population in Switzerland leads to a considerable increase in healthcare expenditure, especially in the management of chronic pain. The Swiss government is investing heavily in healthcare, including pain management therapies and devices, to meet the growing demand. For instance, healthcare spending in Switzerland is particularly high, with a significant portion attributed to the elderly population. In addition to public sector funding, private insurance plans often cover chronic pain treatments, making these therapies more accessible to a larger segment of the population. This financial support plays a crucial role in driving the market, as it allows for broader utilization of effective pain management options.
Growing Awareness and Patient Advocacy
Growing awareness of chronic pain conditions and the increasing presence of patient advocacy groups have empowered individuals to seek more effective treatments. As patients become more informed about available therapies, there is a greater demand for timely intervention and tailored pain management solutions. For instance, the Swiss Pain Society actively promotes research and education in pain management, helping to raise awareness and improve care standards. Early diagnosis and intervention play a key role in improving long-term outcomes and reducing healthcare costs. This shift towards proactive pain management is driving market growth, as more individuals take charge of their health and demand better care options.
Technological Advancements
Technological advancements are transforming the chronic pain management landscape in Switzerland. Innovative therapies, such as minimally invasive procedures, drug delivery systems, and neuromodulation devices, are offering new and improved treatment options for chronic pain sufferers. Furthermore, the rise of digital health solutions, including telemedicine and mobile health applications, is enhancing patient access to pain management services. These technologies enable remote consultations, real-time monitoring, and personalized treatment plans, significantly improving the overall patient experience and contributing to market expansion.
Market Trends
Growing Emphasis on Interdisciplinary Pain Management
Healthcare providers are increasingly adopting an interdisciplinary approach to managing chronic pain, recognizing the need for collaboration among various specialists such as pain physicians, neurologists, psychiatrists, and physical therapists. This collaborative approach enables healthcare teams to address the multifaceted nature of chronic pain, which often includes both physical and psychological components. By combining expertise from different medical fields, treatment plans are becoming more comprehensive, offering patients a more holistic solution to their pain management. This trend is particularly important as chronic pain conditions often require long-term management strategies that focus not only on symptom relief but also on improving patients' overall well-being and quality of life. The growing emphasis on interdisciplinary care is enhancing treatment outcomes, as it provides patients with personalized and well-rounded care plans designed to address the root causes of their pain.
Rise of Digital Health Solutions and Technological Advancements
The rise of digital health solutions is significantly transforming chronic pain management in Switzerland. Tools for remote monitoring of pain symptoms, medication adherence, and treatment progress are providing patients and healthcare providers with valuable insights into treatment effectiveness. For instance, digital health solutions like telemedicine and mobile health applications are enhancing patient access to pain management services, especially in rural or underserved areas. Telehealth services, including virtual consultations with pain specialists, are improving access to care, especially in rural or underserved areas, where specialized pain management services may not be readily available. Additionally, mobile apps are offering personalized pain management plans, symptom tracking, and educational resources, empowering patients to take control of their pain treatment. Alongside digital solutions, advancements in pain management technologies, such as neuromodulation devices (spinal cord stimulators and peripheral nerve stimulators), are becoming more effective in managing chronic pain. Minimally invasive procedures, like radiofrequency ablation and nerve blocks, are gaining popularity due to their reduced recovery time and lower risks, providing patients with more accessible options. Furthermore, innovative drug delivery systems, including transdermal patches and implantable pumps, are offering targeted pain relief, reducing the reliance on oral medications and minimizing side effects. This integration of digital health and advanced technologies is significantly enhancing the overall patient experience, making chronic pain management more efficient and effective.
Market Challenges Analysis
Underdiagnosis, Misdiagnosis, and Access to Specialized Care
Chronic pain remains one of the most challenging conditions to diagnose accurately, primarily due to its subjective nature. The absence of objective diagnostic tests for many chronic pain conditions often leads to delays in diagnosis and treatment. For instance, a study found that chronic pain is highly persistent, with almost two-thirds of those who reported chronic pain still experiencing it a year later. This issue is compounded by limited awareness among healthcare providers, who may not recognize or properly address chronic pain, contributing to underdiagnosis. Moreover, patients may face significant barriers in accessing specialized care, especially in rural areas where pain specialists are scarce. Geographic disparities in healthcare access mean that many individuals in underserved regions must travel long distances or wait extended periods to receive treatment. Long wait times for appointments with pain specialists exacerbate the problem, delaying the initiation of care and potentially worsening the patient's symptoms. The combination of underdiagnosis and inadequate access to specialized care can result in prolonged suffering for patients and suboptimal treatment outcomes.
Stigma, Treatment Costs, and the Opioid Crisis
Patients with chronic pain often encounter stigma and misconceptions that hinder effective treatment. Social stigma surrounding chronic pain, including perceptions that it is psychological or exaggerated, can lead to discrimination, isolation, and a diminished quality of life. For instance, individuals with chronic pain often face stigmatizing remarks such as "It's all in your head" or "You just want attention". Misconceptions about the nature of pain further complicate diagnosis and treatment, preventing patients from receiving appropriate care. Additionally, the high cost of advanced pain management therapies, such as implantable devices and specialized medications, poses a significant barrier to treatment. The financial burden of chronic pain can prevent patients from accessing necessary therapies, particularly those with limited financial resources. Limited insurance coverage for non-pharmacological treatments like physical therapy and psychological interventions adds to the difficulty, as reimbursement challenges can deter the adoption of these evidence-based solutions. Meanwhile, the ongoing opioid crisis adds another layer of complexity. The misuse and abuse of opioids have led to stricter regulations on opioid prescriptions, which, while essential for controlling the epidemic, can also limit access to effective pain relief for patients who rely on these medications for legitimate pain management.
Market Opportunities
Expansion of Non-Pharmacological Treatment Options
There are significant market opportunities in Switzerland’s chronic pain sector, particularly in the growing demand for non-pharmacological treatments. As healthcare providers and patients seek alternatives to traditional medications, therapies such as physical therapy, cognitive behavioral therapy (CBT), acupuncture, and mindfulness-based interventions are gaining acceptance. This shift towards holistic, personalized pain management presents a growing market for evidence-based treatments that address both the physical and psychological aspects of chronic pain. Additionally, the integration of digital health solutions, including telehealth platforms and mobile apps for pain management, offers innovative avenues for providing patients with personalized care and monitoring. The increasing recognition of the efficacy of these approaches offers a promising opportunity for healthcare providers and technology companies to capitalize on the rising demand for non-invasive and accessible pain relief options.
Technological Advancements and Patient-Centered Care
The rapid advancements in pain management technologies also present a significant opportunity for growth in the Swiss chronic pain market. Technologies such as neuromodulation devices, including spinal cord stimulators and peripheral nerve stimulators, are becoming more effective and widely adopted. The demand for minimally invasive procedures, like radiofrequency ablation and nerve blocks, is also on the rise due to their reduced recovery times and lower risks compared to traditional surgeries. Furthermore, a growing focus on patient-centered care, including personalized treatment plans, pain assessment tools, and patient education, is reshaping the approach to chronic pain management. The opportunity lies in creating tailored solutions that combine cutting-edge technologies with patient empowerment, ultimately improving treatment outcomes. As Switzerland's healthcare system continues to prioritize patient-centric care, the market for innovative pain management solutions is poised for substantial growth.
Market Segmentation Analysis:
By Indication:
The chronic pain market in Switzerland is segmented by indication, with each category reflecting distinct treatment approaches. Neuropathic pain, caused by nerve damage, is a major contributor to chronic pain cases, often treated with anticonvulsants and antidepressants. Arthritis pain and chronic back pain are among the most common pain conditions, resulting in significant demand for pain management solutions. Arthritis pain is frequently managed with non-steroidal anti-inflammatory drugs (NSAIDs) and opioids, while back pain treatments typically involve a combination of opioids, NSAIDs, and physical therapy. Cancer pain represents another important segment, requiring advanced therapeutic approaches such as opioids and anticonvulsants to address both nociceptive and neuropathic components. Finally, migraine, a type of chronic headache, is often treated with specific medications like NSAIDs and anticonvulsants, targeting both the prevention and acute relief of symptoms. These segments are expected to continue driving demand for chronic pain therapies as the prevalence of these conditions increases, particularly in the aging population.
By Drug Class:
The drug class segment of Switzerland’s chronic pain market includes several therapeutic categories aimed at addressing various pain mechanisms. Opioids, while controversial due to addiction risks, remain a key treatment for moderate to severe pain, particularly in cancer and neuropathic pain. Non-steroidal anti-inflammatory drugs (NSAIDs) are commonly used for arthritis and back pain, offering an effective solution for reducing inflammation and pain. Anticonvulsants and antidepressants are increasingly prescribed for neuropathic pain, offering neurogenic pain relief by stabilizing nerve activity and balancing mood disorders. Additionally, the market includes other specialized drug classes (referred to as Drug Class 5) that address specific types of chronic pain with targeted mechanisms, providing effective treatment for individual patient needs. As the demand for personalized medicine grows, the preference for tailored drug regimens will drive innovation within these drug classes, contributing to market growth and diversification of treatment options.
Segments:
Based on Indication:
- Neuropathic Pain
- Arthritis Pain
- Chronic Back Pain
- Cancer Pain
- Migraine
Based on Drug Class:
- Opioids
- Non-Steroidal
- Anticonvulsants
- Antidepressants
- Drug Class 5
Based on Application:
- Musculoskeletal
- Neuropathy
- Oncology
- Others
Based on Distribution Channel:
- Hospital Pharmacies
- Retail Pharmacies
- Others
Based on the Geography:
- German-speaking Switzerland
- French-speaking Switzerland
Regional Analysis
German-speaking Switzerland
German-speaking Switzerland holds the largest market share in the chronic pain sector, accounting for approximately 60% of the total market. This region benefits from a robust healthcare infrastructure and high levels of healthcare spending, particularly in urban areas such as Zurich, Basel, and Bern. These cities house some of Switzerland’s leading medical institutions and pain management centers, which contribute to the region’s dominance in the chronic pain market. The aging population in German-speaking Switzerland further drives demand for chronic pain treatments, particularly for conditions such as arthritis, neuropathic pain, and chronic back pain. Moreover, the region has seen significant adoption of advanced pain management technologies like neuromodulation devices and minimally invasive procedures. These technologies are widely available and accessible to patients, who are increasingly seeking more effective and less invasive treatment options. The high level of awareness of chronic pain conditions, supported by patient advocacy groups and healthcare professionals, is also contributing to the market’s growth in this region. As a result, German-speaking Switzerland remains the key contributor to the overall market, with continued growth expected due to the expansion of non-pharmacological treatment options and digital health solutions.
French-speaking Switzerland
French-speaking Switzerland represents the second-largest segment of the chronic pain market, accounting for approximately 30% of the total market share. This region, including cities such as Geneva and Lausanne, has a well-developed healthcare system with increasing investment in pain management services. While the market share is smaller compared to the German-speaking part of the country, French-speaking Switzerland is experiencing significant growth, driven by similar trends seen nationwide, including the aging population and the increasing prevalence of chronic pain conditions. In addition, the region is embracing digital health technologies, such as telemedicine platforms and mobile health apps, which are improving access to care and making treatment more accessible, particularly in rural areas. French-speaking Switzerland also has a growing focus on interdisciplinary care and non-pharmacological treatments, such as physical therapy, acupuncture, and cognitive behavioral therapy, as patients and healthcare providers seek more holistic approaches to chronic pain management. The combination of these factors is contributing to a steady increase in market share, with a promising outlook for future expansion in the region.
Key Player Analysis
- Abbott Laboratories
- Pfizer Inc.
- Eli Lilly & Company
- Cara Therapeutics
- Chattem (Sanofi)
- Endo International plc
- Merck & Co. Inc.
- Hoffmann-La Roche AG
- Novaremed AG
- Company 11
- Company 12
- Company 13
- Company 14
Competitive Analysis
The Switzerland chronic pain market is highly competitive, with several key players leading the charge in providing effective pain management solutions. Abbott Laboratories, Pfizer Inc., Eli Lilly & Company, Cara Therapeutics, Chattem (Sanofi), Endo International plc, Merck & Co. Inc., F. Hoffmann-La Roche AG, and Novaremed AG are some of the prominent companies shaping the market. The market is characterized by strong competition among pharmaceutical firms focusing on drug development for various types of pain conditions such as neuropathic pain, arthritis, chronic back pain, and cancer-related pain. In recent years, there has been a significant shift toward personalized medicine, with companies developing targeted therapies that cater to individual patient needs. This trend has intensified competition, as companies strive to offer more effective, tailored treatments for chronic pain. Additionally, the growing demand for non-pharmacological treatments, such as neuromodulation devices and minimally invasive procedures, has prompted companies to invest heavily in advanced pain management technologies. The increasing use of digital health solutions, including telemedicine and mobile apps, is another area where competition is intensifying. Companies are focusing on expanding their digital offerings to improve patient access to care and enhance treatment adherence. As the market continues to evolve, players are expected to adopt strategic collaborations, product diversification, and cutting-edge technology to maintain a competitive edge in the growing chronic pain sector in Switzerland.
Recent Developments
- In July 2024, Boston Scientific Corporation announced positive five-year results for the Intracept Intraosseous Nerve Ablation System, presented at the American Society of Pain & Neuroscience (ASPN) conference in Miami Beach, Florida. The data, pooled from three clinical trials, highlight the effectiveness of the Intracept system in treating vertebrogenic low back pain, a condition caused by damage to vertebral endplates.
- In April 2024, Vertex Pharmaceuticals announced significant progress in its suzetrigine pain program, an oral selective NaV1.8 pain signal inhibitor that is poised to become the first new class of medicine for acute and neuropathic pain in over two decades. Following positive Phase 3 results in January 2024, the FDA granted New Drug Application (NDA) submission for suzetrigine in moderate-to-severe acute pain.
- In February 2024, CinCor Pharma, Inc. was acquired by AstraZeneca. Cincor is a clinical stage biopharmaceutical company based out of USA that is focused on developing novel treatments for severe hypertension and chronic kidney disease.
- In January 2024, Bayer AG disclosed its plan to strengthen its pharmaceutical and consumer health businesses. This move will bolster the company’s American market presence.
- In January 2024, Sanofi announced its acquisition of Inhibrx, Inc., aiming to incorporate a potential best-in-class rare disease asset for Alpha-1 Antitrypsin Deficiency into its pipeline.
- In December 2023, Forever Cheer, a pharmaceutical company holding more than 10 global patents, selected Hong Kong as the launchpad for its innovative pain management drugs, aiming to expand its global footprint and significantly impact the healthcare industry
- In August 2023, MOBE and Override, digital health innovators, partnered to introduce a shared savings program for chronic pain management. This initiative focuses on providing personalized pain treatment through data analytics and behavioral health coaching, with the goal of reducing healthcare costs.
Market Concentration & Characteristics
The market concentration in the Switzerland chronic pain sector is moderate, with a mix of both established global pharmaceutical companies and emerging players contributing to its growth. While large multinational corporations dominate the market with their extensive portfolios of pain management drugs, smaller firms are carving out niches by focusing on innovative treatments and advanced technologies. These include neuromodulation devices, minimally invasive procedures, and personalized medicine approaches, which cater to the rising demand for more targeted, effective, and less invasive pain management solutions. The characteristics of the market are influenced by several key factors, including the aging population, increasing healthcare expenditure, and the growing preference for non-pharmacological treatments. The sector is witnessing a shift towards a more holistic approach, integrating both pharmacological and non-pharmacological therapies to address chronic pain comprehensively. There is also a notable trend towards patient-centric care, with treatment plans increasingly tailored to individual needs. Digital health solutions, such as telemedicine platforms and mobile apps, are becoming integral to the market, enhancing accessibility to pain management services. The market is also marked by a strong regulatory framework, which ensures the safety and efficacy of treatments, fostering confidence among healthcare providers and patients alike. As demand for chronic pain treatments rises, competition within the market is expected to intensify.
Report Coverage
The research report offers an in-depth analysis based on Indication, Drug Class, Application, Distribution Channel and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Switzerland chronic pain market is expected to grow steadily, driven by an aging population and the increasing prevalence of chronic pain conditions.
- Technological advancements, such as neuromodulation devices and minimally invasive procedures, will continue to shape the future of pain management.
- The demand for personalized pain management solutions will rise, leading to tailored treatment plans for patients.
- Digital health solutions, including telemedicine and mobile apps, will play a crucial role in improving patient access to care and treatment adherence.
- Non-pharmacological treatments, such as physical therapy, acupuncture, and cognitive behavioral therapy, will see increased adoption in managing chronic pain.
- Growing patient advocacy and awareness will result in more individuals seeking timely diagnosis and effective treatment options.
- The market will witness greater collaboration between pharmaceutical companies, healthcare providers, and tech firms to create integrated care models.
- Regulatory support and the development of new pain management therapies will enhance treatment options for patients.
- There will be a continued focus on addressing the opioid crisis through alternative pain management strategies.
- Increased investment in healthcare infrastructure will improve access to specialized pain care, particularly in rural areas.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Switzerland Chronic Pain Market?
What factors are driving the growth of the Switzerland Chronic Pain Market?
What are the key segments within the Switzerland Chronic Pain Market?
What are some challenges faced by the Switzerland Chronic Pain Market?
Who are the major players in the Switzerland Chronic Pain Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Switzerland Chronic Pain Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2023; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Switzerland Chronic Pain Market Snapshot
- 2.1.1 Market Size – Historical (2023) & Forecast (2023-2032) (2023: USD 434.62 million → 2032: USD 605.72 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Switzerland Chronic Pain Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2023 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2023
- 2.3.2 Top 10 Players by Volume Share – 2023
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Switzerland Chronic Pain Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Switzerland Chronic Pain Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Switzerland Chronic Pain Market Drivers
- 3.3 Switzerland Chronic Pain Market Restraints & Challenges
- 3.4 Switzerland Chronic Pain Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Switzerland Chronic Pain Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Switzerland Chronic Pain Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Switzerland Chronic Pain category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Switzerland Chronic Pain Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Switzerland Chronic Pain Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2023)
- 5.1.2 Global Export Volume by Country (2023)
- 5.1.3 Global Import Value by Country (2023)
- 5.1.4 Global Import Volume by Country (2023)
- 5.1.5 Net Trade Balance by Country (2023)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2023)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Switzerland Chronic Pain market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Switzerland Chronic Pain Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2023
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Switzerland Chronic Pain Market Share Analysis – 2023
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2023)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Switzerland Chronic Pain Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Switzerland Chronic Pain (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Switzerland Chronic Pain Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Switzerland Chronic Pain Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2023 & 2032)
- 7.1.2 Channel Mix Evolution (2023-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Switzerland Chronic Pain Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Switzerland Chronic Pain Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Switzerland Chronic Pain Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Switzerland Chronic Pain Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Switzerland Chronic Pain Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Switzerland Chronic Pain Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Switzerland Chronic Pain Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
