
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Thin Film and Printed Batteries Market Size 2024 | USD 230.78 Million |
| Thin Film and Printed Batteries Market, CAGR | 20% |
| Thin Film and Printed Batteries Market Size 2032 | USD 992.31 Million |
Market Overview:
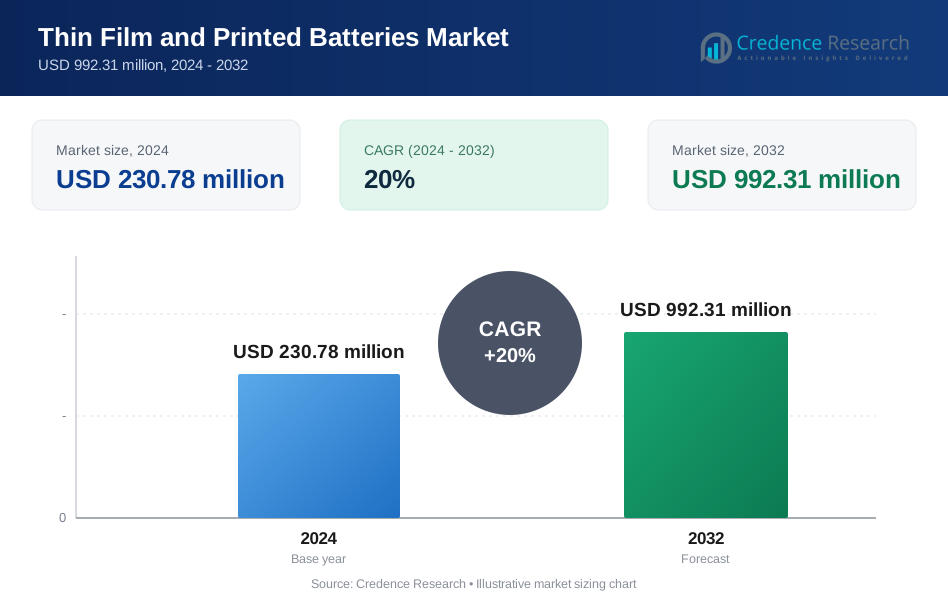
The Thin Film and Printed Batteries Market is projected to grow from USD 230.78 million in 2024 to an estimated USD 992.31 million by 2032, with a compound annual growth rate (CAGR) of 20% from 2024 to 2032.
The market is primarily driven by the increasing miniaturization of electronic devices and the escalating demand for energy-efficient power sources. Thin film and printed batteries offer enhanced flexibility, reduced weight, and superior integration capabilities, making them ideal for emerging technologies such as IoT and smart textiles. The rising penetration of wearable technology, including fitness trackers and health monitoring devices, has further amplified the need for ultra-thin energy storage. Additionally, advancements in materials science, such as the use of solid electrolytes and printable battery components, are fostering innovations that expand application potential. The growing emphasis on sustainability and environmental impact reduction also supports market growth, as these batteries are often designed using eco-friendly and recyclable materials.
North America and Europe dominate the Thin Film and Printed Batteries Market, accounting for a significant share due to high levels of R&D investment and a strong presence of key industry players. In North America, the United States leads, driven by the rapid adoption of IoT and wearable technologies. Europe exhibits robust growth, particularly in healthcare and automotive applications, with Germany and the Nordic countries at the forefront. The Asia-Pacific region is emerging as a lucrative market, spurred by advancements in electronics manufacturing in countries like China, Japan, and South Korea. Meanwhile, Latin America and the Middle East & Africa show gradual adoption, with opportunities arising from increasing investments in renewable energy and industrial automation. This regional diversity underscores the global appeal and versatility of thin film and printed batteries.
Market Insights:
- The market is driven by the miniaturization of electronic devices and the rising demand for energy-efficient, flexible, and lightweight power sources.
- Thin film and printed batteries are ideal for emerging technologies like IoT and smart textiles due to their superior integration capabilities and customizable designs.
- Wearable technology, including fitness trackers and medical monitoring devices, is a key growth area, amplifying the demand for ultra-thin energy storage solutions.
- Advances in materials science, such as solid electrolytes and printable components, enhance energy density and expand application potential across industries.
- North America and Europe dominate the market, accounting for a combined 65% share, driven by R&D investments and industrial adoption in wearables, IoT, and healthcare.
- The Asia-Pacific region is emerging as a high-growth market, supported by advancements in electronics manufacturing and growing IoT adoption in China, Japan, and South Korea.
- Sustainability and environmental concerns are shaping the market, with a strong push for eco-friendly and recyclable battery materials to meet global environmental goals.
Market Drivers:
Increasing Adoption of Miniaturized and Flexible Devices
The rising demand for compact and flexible devices in industries such as consumer electronics, healthcare, and wearables is a primary driver for the Thin Film and Printed Batteries Market. These batteries are lightweight, ultra-thin, and customizable, making them ideal for powering devices such as fitness trackers, medical implants, and IoT sensors. For instance, Enfucell, a company specializing in printed batteries, produces ultra-thin batteries that are less than 1 mm thick, making them perfect for wearable devices. As wearable technology continues to penetrate mainstream consumer markets, the need for energy storage solutions that can integrate seamlessly with innovative designs grows. Their ability to maintain performance despite size constraints positions thin film and printed batteries as an essential component for the next generation of electronics.
Rapid Growth in IoT and Smart Device Applications
The proliferation of Internet of Things (IoT) devices across various sectors, including industrial automation, healthcare, and smart homes, has significantly boosted the demand for efficient energy solutions. Thin film and printed batteries enable long-lasting, stable power supply to IoT sensors and smart devices, which often operate in compact or unconventional spaces. For example, Blue Spark Technologies offers printed batteries that power smart labels and IoT sensors, providing reliable energy in a thin and flexible form factor. Their thin and flexible nature allows them to be integrated into diverse form factors, from smart labels to connected clothing. As IoT adoption accelerates globally, the requirement for innovative battery solutions capable of supporting remote and low-power operations drives market growth.
Advances in Materials and Manufacturing Technologies
Technological advancements in materials science and manufacturing processes are expanding the application potential of thin film and printed batteries. Innovations such as solid-state electrolytes, advanced printing techniques, and nanomaterial coatings enhance energy density, stability, and performance. For instance, Imprint Energy uses zinc-based solid-state electrolytes to create flexible batteries that are safer and more stable than traditional lithium-ion batteries. These breakthroughs are enabling the production of batteries that are not only more efficient but also environmentally friendly. Furthermore, cost reductions achieved through scalable manufacturing technologies have made these batteries increasingly competitive, encouraging adoption across a broader range of industries, including automotive and renewable energy.
Sustainability and Environmental Awareness
Growing environmental concerns and the emphasis on sustainable practices are pivotal factors driving the market for thin film and printed batteries. Many of these batteries are developed using eco-friendly materials and processes, making them an attractive alternative to traditional lithium-ion batteries. For example, Printed Energy produces batteries using environmentally friendly materials that reduce the overall carbon footprint. Their reduced weight and compact design contribute to lower energy consumption during transportation and manufacturing. As industries and consumers prioritize reducing their carbon footprint, the adoption of sustainable energy storage solutions such as thin film and printed batteries aligns with global efforts to address climate change and resource conservation, further propelling market growth.
Market Trends:
Increasing Integration in Wearable Devices
The adoption of thin film and printed batteries in wearable technology is transforming the market. Devices such as fitness trackers, smartwatches, and medical monitoring equipment require compact, lightweight, and flexible power solutions. For instance, the number of connected wearable devices has grown substantially from 722 million in 2019 to 835 million in 2020, then to 929 million in 2021, and reached 1,110 million devices worldwide in 2022. companies like Flexel LLC and Jenax developed specialized printed thin-film batteries achieving less than 0.5mm thickness for these applications. Thin film and printed batteries offer ultra-thin profiles, meeting the size and weight constraints of wearable devices. Advances in materials have improved their energy density, enhancing device performance and user satisfaction. As wearable technology continues to innovate, the need for advanced energy storage solutions is expected to grow rapidly.
Expanding Applications in Healthcare
Thin film and printed batteries are gaining traction in the healthcare industry due to their suitability for medical devices and diagnostic tools. Their flexibility, biocompatibility, and compact size make them ideal for implantable devices, biosensors, and disposable health monitors. For example, printed batteries are being used in disposable biosensors for glucose monitoring, enabling patients to track their blood sugar levels conveniently and accurately. As telemedicine and remote healthcare services expand, these batteries are increasingly powering portable diagnostic tools. This trend reflects the growing reliance on efficient and reliable energy solutions to support the evolution of healthcare technology.
Growing Use in Smart Packaging and Logistics
The adoption of these batteries in smart packaging and logistics is another key trend. Thin film and printed batteries are being embedded into smart labels and tags for real-time tracking, temperature monitoring, and condition reporting of goods. Their low-profile design allows integration into packaging materials, enhancing transparency and efficiency in supply chains. For instance, BrightVolt has manufactured and shipped over 15 million ultra-thin lithium polymer batteries with thicknesses less than 0.45 mm, specifically designed for smart labels and interactive packaging applications. With the rising demand for smart logistics solutions globally, the market for energy storage systems in packaging technology is expanding significantly.
Emergence in Renewable Energy and Smart Grids
Renewable energy and smart grid applications are driving the use of thin film and printed batteries in decentralized energy systems. These batteries are being utilized in energy harvesting technologies, such as solar-powered sensors and wireless devices, due to their compatibility with small-scale renewable energy solutions. For instance, thin film batteries are being integrated into solar-powered IoT sensors for monitoring renewable energy systems in remote areas. These sensors, equipped with thin film batteries, ensure reliable performance by harvesting solar energy and storing it efficiently for uninterrupted operation, even during low-light conditions. As investments in renewable energy infrastructure grow, these batteries are becoming critical to advancing sustainable and energy-efficient technologies across industries.
Market Challenges Analysis:
High Production Costs and Limited Scalability
The high production costs associated with thin film and printed batteries remain a significant restraint to market growth. Advanced manufacturing processes, including precision printing and material deposition, require specialized equipment and expertise, leading to elevated production expenses. Additionally, the scalability of these technologies poses a challenge, as producing large volumes while maintaining consistent quality is complex and resource-intensive. These factors limit affordability and adoption, particularly among smaller manufacturers and cost-sensitive industries.
Limited Energy Density and Performance Constraints
Despite advancements in technology, thin film and printed batteries often exhibit lower energy densities compared to conventional lithium-ion batteries. This limitation restricts their application in devices requiring higher power outputs or longer operational lifespans, such as electric vehicles and industrial equipment. While suitable for low-power applications, the gap in performance compared to traditional batteries reduces their competitiveness in broader markets. Addressing these performance constraints is critical to unlocking their full potential.
Regulatory and Standardization Challenges
The lack of uniform regulatory frameworks and industry standards for thin film and printed batteries presents a barrier to market growth. Variations in safety, quality, and environmental compliance requirements across regions complicate product development and global market entry. These inconsistencies increase costs and prolong time-to-market for manufacturers, particularly for applications in sensitive industries such as healthcare and consumer electronics.
Supply Chain and Material Availability Issues
The supply chain for key materials used in thin film and printed batteries, such as advanced polymers and rare earth metals, is susceptible to disruptions. Limited availability of high-quality raw materials and dependency on specific suppliers create risks that can affect production timelines and costs. Additionally, the lack of established distribution networks in emerging markets hinders widespread adoption, further restraining growth in these regions.
Market Opportunities:
The Thin Film and Printed Batteries Market offers significant opportunities driven by the rising demand for innovative energy storage solutions across industries. The increasing adoption of wearable technology, IoT devices, and portable medical devices necessitates compact, flexible, and lightweight power sources. Thin film and printed batteries, with their customizable form factors, align perfectly with these requirements. The IoT sector alone is projected to surpass USD 1 trillion by 2030, creating vast opportunities for battery integration in smart home systems, industrial automation, and logistics applications. Additionally, the healthcare sector is increasingly relying on advanced medical devices and biosensors, further driving demand for biocompatible and reliable battery solutions.
Emerging markets in the Asia-Pacific, Latin America, and Middle East & Africa regions present untapped potential for growth. In Asia-Pacific, rapid industrialization and the expansion of electronics manufacturing in countries like China, Japan, and South Korea are fueling demand. Similarly, Latin America and the Middle East & Africa are witnessing growth in renewable energy projects and smart logistics, where thin film and printed batteries can play a pivotal role. As industries prioritize sustainability, the market is poised to benefit from innovations in eco-friendly materials and energy-efficient manufacturing processes. Companies that focus on technological advancements, cost reduction, and regional partnerships will be well-positioned to capitalize on the growing demand for thin film and printed batteries in both established and emerging markets.
Market Segmentation Analysis:
The Thin Film and Printed Batteries Market is segmented by type, voltage, capacity, rechargeability, application, and region, reflecting the diverse requirements and applications of these advanced energy storage solutions.
By Type
Thin film batteries dominate the market due to their lightweight, ultra-thin design, and high adaptability in applications like wearables and medical devices. Printed batteries are gaining traction for their cost-effective manufacturing and scalability, making them ideal for disposable or single-use applications such as smart packaging and cards.
By Voltage
The segment between 1.5V and 3V holds a significant share, as it aligns with the voltage requirements of most IoT devices and wearable electronics. Batteries below 1.5V cater to low-power applications, while those above 3V are used in more energy-intensive devices.
By Capacity
Batteries with capacities between 10 mAh and 100 mAh dominate the market, serving IoT sensors and medical devices. Batteries below 10 mAh support applications like smart cards, while those above 100 mAh are used in industrial and higher-power consumer electronics.
By Rechargeability
Primary batteries, being cost-effective and lightweight, are widely used in disposable applications like smart packaging. Secondary batteries are preferred for rechargeable applications, including wearables and medical devices, offering sustainability and longer lifecycle benefits.
By Application
Consumer electronics and medical devices lead due to rising demand for compact and flexible energy solutions. Smart cards, packaging, and wireless sensors represent emerging opportunities as industries adopt IoT and smart technology.
Segmentation:
By Type:
- Thin Films Batteries
- Printed Batteries
By Voltage:
- Below 1.5V
- Between 1.5V and 3V
- Above 3V
By Capacity:
- Below 10 mAh
- Between 10 mAh and 100 mAh
- Above 100 mAh
By Rechargeabilty:
- Primary Batteries
- Secondary Batteries
By Application:
- Consumer Electronics
- Smart Cards
- Smart Packaging
- Medical Devices
- Wireless Sensors
- Others
By Region:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
The Thin Film and Printed Batteries Market showcases diverse growth dynamics across regions, driven by varying levels of technological advancement, industrial demand, and regulatory support. North America, Europe, and Asia-Pacific dominate the market, while Latin America and the Middle East & Africa are emerging as promising regions.
North America
North America accounts for approximately 35% of the global market, fueled by significant R&D investments and the integration of advanced energy storage technologies across industries. The United States leads with the highest adoption of thin film and printed batteries in wearables, IoT applications, and healthcare devices, with wearable technology projected to grow by over 15% annually in the region. Canada contributes with advancements in eco-friendly battery designs for medical devices and consumer electronics.
Europe
Europe holds about 30% of the market share, driven by strong environmental policies and a focus on sustainable energy systems. Germany and the Netherlands lead in renewable energy and automotive applications, with Germany’s investment in energy storage systems projected to grow. The European Union’s regulations on reducing electronic waste and promoting circular economy practices bolster market growth. Additionally, the region’s smart packaging market, growing at a CAGR of 12%, increases demand for thin film batteries for tracking and monitoring purposes.
Asia-Pacific
The Asia-Pacific region captures roughly 25% of the global market, driven by advancements in electronics manufacturing in China, Japan, and South Korea. China leads in battery production, producing over 50% of global electronics and increasingly investing in sustainable energy technologies. Japan and South Korea are at the forefront of R&D for flexible and high-capacity batteries, particularly for wearable and portable devices. The adoption of IoT devices, projected to grow by 18% annually in the region, and the increasing use of smart labels in logistics further enhance the demand for innovative energy solutions.
Latin America and Middle East & Africa
Latin America and the Middle East & Africa collectively hold about 10% of the market, with growth driven by industrial automation and renewable energy initiatives. Brazil leads in Latin America, with over 30% growth in smart logistics applications, while Mexico is advancing in consumer electronics manufacturing. In the Middle East & Africa, renewable energy projects, such as solar-powered grids expected to grow by 20% annually, are creating opportunities for thin film and printed batteries.
Key Player Analysis:
- Cymbet Corporation (US),
- Enfucell (Finland),
- Ilika plc (UK),
- Jenax Inc. (South Korea),
- Molex, LLC (US),
- NGK Insulators, Ltd. (Japan),
- ProLogium Technology Co., Ltd. (Taiwan),
- Renata SA (Switzerland),
- Samsung SDI Co., Ltd. (South Korea),
- Ultralife Corporation (US),
- VARTA AG (Germany),
Competitive Analysis:
The Thin Film and Printed Batteries Market is moderately competitive, with a mix of established companies and innovative startups driving market growth. Leading players, such as Blue Spark Technologies, Enfucell, and Cymbet Corporation, leverage their strong R&D capabilities to develop advanced and customizable battery solutions. These companies focus on catering to high-demand applications in wearables, IoT devices, and medical devices, positioning themselves as key innovators in the market. Startups and regional players are also gaining traction by targeting niche applications and emphasizing cost-effective production methods. Partnerships and collaborations between battery manufacturers, electronics companies, and IoT developers are enhancing supply chains and expanding product portfolios. Blue Spark Technologies and Enfucell. These companies have partnered to develop advanced thin film battery solutions for wearable medical devices. The market is characterized by continuous technological advancements, particularly in materials and printing techniques, which are intensifying competition. Players focusing on scalability, sustainability, and regional market penetration are likely to secure a competitive edge in this evolving and dynamic market.
Recent Developments:
- In September 2024, Molex advanced data center infrastructure with the introduction of their VaporConnect Optical Feedthrough Modules, specifically designed for two-phase immersion cooling systems. This innovation enhances data center efficiency and offers improved upgradability options for modular installations.
- In June 2024, NGK Insulators, Ltd. launched the NAS MODEL L24, an upgraded sodium-sulfur battery system. This system features significantly reduced degradation rates and provides approximately 20% cost savings in modular substation storage systems, offering a more economical solution for power infrastructure.
- Also in June 2024, VARTA AG began full-scale production of their modular DC high-voltage storage system, wall, at their Neunheim facility. Deliveries commenced in mid-July 2024, marking a major milestone in modular energy storage innovation.
- In May 2023, ProLogium Technology announced plans for a €5.2 billion solid-state battery gigafactory in Dunkirk, France. This project aims to enhance modular substation technology and drive advancements in energy storage solutions, demonstrating the company’s commitment to cutting-edge innovation.
Market Concentration & Characteristics:
The Thin Film and Printed Batteries Market is moderately fragmented, featuring a mix of global leaders, niche specialists, and emerging startups. While a few established players, such as Blue Spark Technologies, Enfucell, and ProLogium, dominate through technological advancements and extensive R&D investments, smaller companies are carving out niches with cost-effective solutions and application-specific products. The market is characterized by rapid innovation, driven by increasing demand for lightweight, flexible, and customizable battery solutions across industries like IoT, healthcare, and wearables. Companies are leveraging advancements in materials science and scalable manufacturing techniques to improve energy density, reduce costs, and enhance sustainability. Despite its fragmentation, the market exhibits collaborative tendencies, with partnerships and joint ventures common among stakeholders to accelerate product development and broaden market reach. The combination of innovation, adaptability, and collaboration defines the competitive dynamics of the Thin Film and Printed Batteries Market.
Report Coverage:
The research report offers an in-depth analysis based on By Type, By Voltage, By Capacity, By Rechargeabilty and By Application. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The market is expected to witness sustained growth, driven by increasing demand for compact and flexible energy storage in wearables and IoT devices.
- Advancements in materials science, including solid-state electrolytes, will improve energy density and expand application potential.
- Cost reductions through scalable manufacturing technologies will make these batteries more competitive across industries.
- The healthcare sector will increasingly adopt thin film and printed batteries for portable diagnostic tools and implantable medical devices.
- Integration into smart packaging and logistics applications will grow, supporting real-time tracking and monitoring solutions.
- Asia-Pacific will emerge as a high-growth region, fueled by electronics manufacturing and IoT adoption in China, Japan, and South Korea.
- Collaboration between manufacturers and technology companies will accelerate innovation and market penetration.
- Sustainability initiatives will drive the development of eco-friendly and recyclable battery materials.
- Increased investment in renewable energy and smart grids will open new opportunities for energy harvesting applications.
- Market competition will intensify as startups and established players innovate to meet evolving consumer and industrial needs.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Miniaturization and Flexibility in Electronics
The ongoing trend toward smaller, lighter, and more flexible electronic devices - such as wearables, medical implants, and IoT sensors - demands ultra-thin, customizable batteries that can be seamlessly integrated, driving adoption of thin film and printed batteries.
Rapid Expansion of IoT and Smart Devices
The proliferation of IoT devices across industries like healthcare, logistics, and smart homes requires compact, reliable, and long-lasting power sources, making thin film and printed batteries essential for powering sensors and connected devices in space-constrained environments.
Advancements in Materials and Manufacturing
Innovations in solid-state electrolytes, printable battery components, and scalable manufacturing processes are improving energy density, safety, and cost-effectiveness, expanding the range of applications and making these batteries more competitive with traditional technologies.
Sustainability and Environmental Concerns
Growing emphasis on eco-friendly, recyclable materials and reduced carbon footprints is encouraging the adoption of thin film and printed batteries, which are often designed with sustainability in mind and align with global environmental goals.
Growth in Wearable and Medical Technology
The surge in wearable health monitors, fitness trackers, and portable diagnostic tools is fueling demand for ultra-thin, biocompatible batteries that can power these devices reliably without adding bulk or weight.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth of the Thin Film and Printed Batteries market?
What drives the demand for thin film and printed batteries?
Which regions dominate the market?
What challenges does the market face?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Thin Film Batteries
- 1.2.2 Printed Batteries
- 1.3 By Voltage
- 1.3.1 Below 1.5V
- 1.3.2 Between 1.5V and 3V
- 1.3.3 Above 3V
- 1.4 By Capacity
- 1.4.1 Below 10 mAh
- 1.4.2 Between 10 mAh and 100 mAh
- 1.4.3 Above 100 mAh
- 1.5 By Application
- 1.5.1 Consumer Electronics
- 1.5.2 Smart Cards
- 1.5.3 Smart Packaging
- 1.5.4 Medical Devices
- 1.5.5 Wireless Sensors
- 1.5.6 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 230.78 million → 2032: USD 992.31 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Thin Film and Printed Batteries Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Thin Film and Printed Batteries Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Thin Film and Printed Batteries Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Thin Film and Printed Batteries Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Thin Film and Printed Batteries Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Thin Film and Printed Batteries Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Thin Film and Printed Batteries Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Thin Film and Printed Batteries Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 230.78 million → 2032: USD 992.31 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Thin Film and Printed Batteries Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Thin Film Batteries
- 12.3.7.2 Printed Batteries
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Voltage - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Below 1.5V
- 12.4.7.2 Between 1.5V and 3V
- 12.4.7.3 Above 3V
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Capacity - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Below 10 mAh
- 12.5.7.2 Between 10 mAh and 100 mAh
- 12.5.7.3 Above 100 mAh
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Application - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Consumer Electronics
- 12.6.7.2 Smart Cards
- 12.6.7.3 Smart Packaging
- 12.6.7.4 Medical Devices
- 12.6.7.5 Wireless Sensors
- 12.6.7.6 Others
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Thin Film and Printed Batteries End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Thin Film and Printed Batteries Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Thin Film and Printed Batteries Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Thin Film and Printed Batteries Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Cymbet Corporation
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Enfucell
- 18.4 Ilika plc
- 18.5 Jenax Inc.
- 18.6 Molex, LLC
- 18.7 NGK Insulators, Ltd.
- 18.8 ProLogium Technology Co., Ltd.
- 18.9 Renata SA
- 18.10 Samsung SDI Co., Ltd.
- 18.11 VARTA AG
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

