
Market Overview
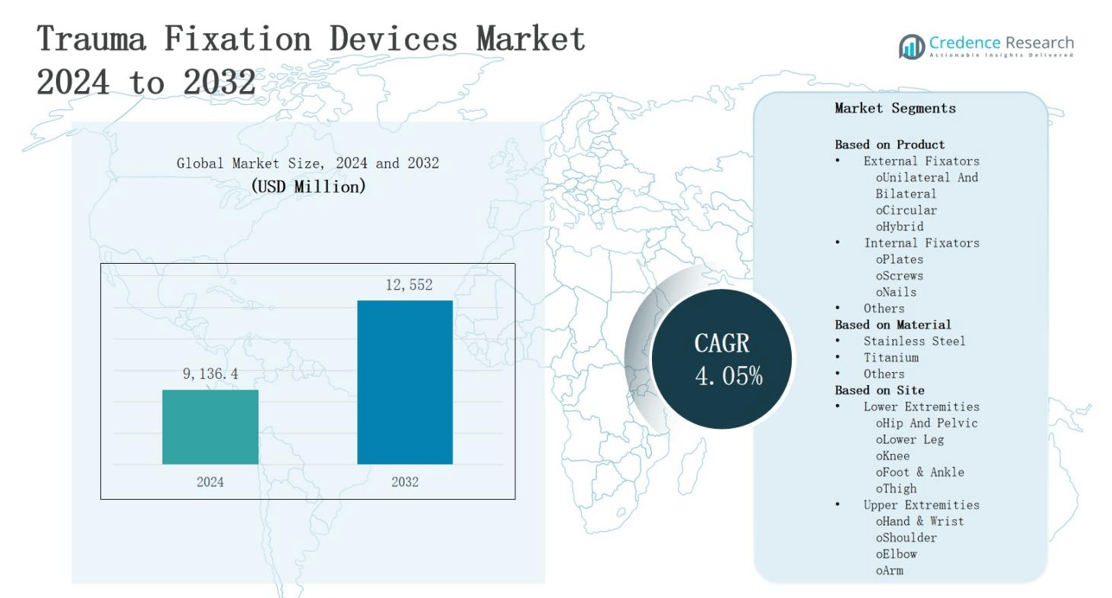
The trauma fixation devices market is projected to grow from USD 9,136.4 million in 2024 to USD 12,552 million by 2032, registering a CAGR of 4.05% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Trauma Fixation Devices Market Size 2024 | USD 9,136.4 million |
| Trauma Fixation Devices Market, CAGR | 4.05% |
| Trauma Fixation Devices Market Size 2032 | USD 12,552 million |
The trauma fixation devices market grows with rising incidence of road accidents, sports injuries, and age-related fractures driving demand for advanced surgical solutions. Increasing adoption of minimally invasive fixation techniques, coupled with technological innovations in bioabsorbable and 3D-printed implants, enhances treatment outcomes and patient recovery. Growing prevalence of osteoporosis and musculoskeletal disorders further strengthens market adoption, while expanding healthcare infrastructure in emerging economies improves access to trauma care. Key trends include the integration of robotics and navigation-assisted surgeries, shift toward patient-specific implants, and rising preference for lightweight, biocompatible materials that ensure higher efficiency and reduced post-operative complications.
The trauma fixation devices market demonstrates strong geographical diversity across North America, Europe, Asia Pacific, Latin America, and the Middle East & Africa. North America leads with advanced infrastructure and innovation, while Europe benefits from strict safety standards and an aging population. Asia Pacific grows rapidly through medical tourism and healthcare expansion, Latin America strengthens with modernization efforts, and the Middle East & Africa gain from rising investments. Key players include Johnson & Johnson, Stryker, Zimmer Biomet, Smith+Nephew, Arthrex, Orthofix US, and B Braun Melsungen.
Market Insights
- The trauma fixation devices market is projected to grow from USD 9,136.4 million in 2024 to USD 12,552 million by 2032, at a CAGR of 4.05%.
- Rising incidence of road accidents, sports injuries, and age-related fractures drives strong demand for advanced surgical fixation solutions.
- Growing prevalence of osteoporosis and musculoskeletal disorders increases long-term reliance on fixation systems across hospitals and clinics.
- Technological advancements such as bioabsorbable implants, 3D printing, and robotics enhance precision, safety, and patient recovery outcomes.
- High device costs, regulatory delays, and risks of post-operative complications present challenges for market penetration.
- North America leads with 35% share, followed by Europe at 28%, Asia Pacific at 22%, Latin America at 9%, and Middle East & Africa at 6%.
- Key players including Johnson & Johnson, Stryker, Zimmer Biomet, Smith+Nephew, Arthrex, Orthofix US, and B Braun Melsungen drive growth through innovation and global expansion.
Market Drivers
Rising Incidence of Road Accidents and Sports Injuries
The trauma fixation devices market expands with the increasing frequency of road accidents and sports-related injuries worldwide. Growing urbanization and motorization drive higher accident rates, which directly increase the need for surgical interventions. Sports activities across professional and recreational levels also contribute significantly to fracture cases requiring fixation. The demand for rapid and reliable orthopedic solutions strengthens adoption. It continues to rely on innovative devices that reduce recovery time and improve patient outcomes.
- For instance, DePuy Synthes (Johnson & Johnson) introduced its UNIUM Power Tool System designed for trauma and small bone procedures, enabling surgeons to perform fixation surgeries with greater precision and reduced invasiveness.
Growing Burden of Osteoporosis and Musculoskeletal Disorders
The trauma fixation devices market benefits from the rising prevalence of osteoporosis and degenerative bone conditions, particularly in aging populations. Weakening bone structure in elderly individuals increases susceptibility to fractures, fueling the use of fixation systems. The global burden of musculoskeletal disorders adds to this demand, requiring long-term corrective solutions. It supports sustained growth as healthcare providers prioritize efficient devices. This demographic shift creates consistent demand across hospitals, specialty clinics, and orthopedic centers.
- For instance, the United States estimates that about 10.2 million adults have osteoporosis, with over 80% being women, highlighting the increased need for orthopedic interventions in this demographic.
Technological Advancements in Surgical Fixation Systems
The trauma fixation devices market grows with rapid technological improvements, including bioabsorbable implants, 3D-printed fixation systems, and minimally invasive surgical tools. These innovations enhance surgical precision and reduce complications while improving patient comfort. Surgeons increasingly adopt navigation-assisted and robotic-guided fixation procedures to achieve greater accuracy. It fosters higher acceptance across advanced healthcare facilities. The focus on product innovation drives competitive differentiation while addressing evolving patient and surgeon expectations in orthopedic trauma care.
Expanding Healthcare Infrastructure and Access in Emerging Economies
The trauma fixation devices market strengthens with improved healthcare infrastructure in developing regions. Rising investments in hospitals, trauma centers, and specialized orthopedic units expand treatment availability. Growing medical tourism in Asia and the Middle East further supports demand for advanced fixation devices. It aligns with increased government initiatives to enhance orthopedic care. Expanding insurance coverage and affordability of surgical procedures also improve access. This structural growth encourages wider adoption across both urban and rural healthcare systems.
Market Trends
Adoption of Minimally Invasive and Navigation-Assisted Procedures
The trauma fixation devices market experiences strong momentum with the growing adoption of minimally invasive surgical techniques supported by advanced navigation and imaging technologies. Surgeons prefer these approaches to reduce tissue damage, shorten hospital stays, and improve post-operative recovery. Navigation-assisted procedures enhance accuracy in implant placement and fixation, minimizing surgical risks. It enables healthcare providers to deliver higher standards of patient care. This trend accelerates demand for specialized fixation systems designed for precision-based trauma surgeries.
- For instance, the Less Invasive Stabilization System (LISS) plate is inserted through small incisions using image intensifier monitoring to stabilize distal femur fractures, preserving soft tissue and promoting improved healing.
Integration of Biocompatible and Bioabsorbable Materials
The trauma fixation devices market advances with the rising use of biocompatible and bioabsorbable materials, designed to improve patient outcomes and reduce long-term complications. Bioabsorbable implants dissolve naturally, eliminating the need for secondary removal surgeries, which enhances patient convenience and safety. Manufacturers focus on lightweight, durable materials that support bone healing without adverse reactions. It reflects a broader shift toward sustainable solutions. Growing clinical evidence supporting bioabsorbable technology drives confidence among surgeons and accelerates adoption.
- For instance, DePuy Synthes offers bioabsorbable fixation devices such as Rapidsorb®, which is composed of PLLA and PGA and designed to provide strength for up to 12 months while naturally dissolving to avoid secondary surgeries
Emergence of 3D Printing and Patient-Specific Implants
The trauma fixation devices market benefits from innovations in 3D printing, enabling the creation of patient-specific implants tailored to unique anatomical requirements. Customization enhances surgical accuracy, reduces complications, and accelerates recovery timelines. Hospitals and research centers increasingly adopt 3D-printed implants for complex trauma cases. It positions personalized care as a key differentiator in orthopedic surgery. Ongoing collaborations between medical device manufacturers and additive manufacturing companies drive advancements in design, cost-efficiency, and clinical outcomes.
Shift Toward Robotics and Digital Health Integration
The trauma fixation devices market evolves with the rising use of robotics, AI, and digital health platforms in orthopedic trauma care. Robotic-assisted surgeries enhance precision in fixation procedures, while AI-driven planning tools improve surgical decision-making. Digital monitoring systems allow post-operative tracking of patient progress, reducing readmissions. It aligns with the broader digital transformation of healthcare delivery. Growing investments in robotic systems and AI-powered platforms signal a future where technology defines orthopedic trauma management.
Market Challenges Analysis
High Cost of Advanced Devices and Surgical Procedures
The trauma fixation devices market faces challenges from the high cost of advanced implants, surgical instruments, and associated procedures. Many patients, particularly in developing economies, cannot afford expensive fixation systems, limiting widespread adoption. Hospitals and healthcare systems also face budgetary constraints, which restrict procurement of premium devices. It creates disparities in access between high-income and low-income regions. The financial burden of revision surgeries or implant replacements further intensifies the challenge. These cost barriers slow market penetration despite growing clinical demand.
Regulatory Hurdles and Risk of Post-Operative Complications
The trauma fixation devices market encounters obstacles from stringent regulatory requirements that delay product approvals and increase development costs. Companies must adhere to complex compliance standards, lengthening the time needed to bring innovations to market. Post-operative risks such as infections, implant failures, and delayed bone healing also undermine patient confidence. It puts pressure on manufacturers to improve product safety and reliability. The combination of regulatory delays and clinical risks creates uncertainty for both providers and patients.
Market Opportunities
Rising Demand in Emerging Economies and Expanding Healthcare Infrastructure
The trauma fixation devices market holds significant opportunities in emerging economies where healthcare infrastructure is rapidly improving. Investments in trauma centers, orthopedic facilities, and advanced surgical units increase accessibility to fixation systems. Rising medical tourism in Asia and the Middle East creates a favorable environment for adoption of innovative devices. It aligns with growing insurance coverage and expanding reimbursement policies that improve affordability. Manufacturers focusing on cost-effective solutions can capture substantial demand in these regions.
Advancements in Technology and Growing Focus on Personalized Implants
The trauma fixation devices market benefits from technological innovations such as 3D printing, robotics, and AI-assisted surgical planning. Personalized implants designed to fit individual anatomical structures enhance clinical outcomes and reduce recovery time. Increasing research in bioabsorbable materials supports long-term opportunities by addressing safety and convenience. It encourages collaborations between medical device companies, research institutions, and hospitals. Growing acceptance of digital monitoring and navigation-assisted systems strengthens the scope for advanced, patient-centric orthopedic trauma solutions.
Market Segmentation Analysis:
By Product
The trauma fixation devices market is segmented into external fixators, internal fixators, and others. External fixators include unilateral and bilateral, circular, and hybrid systems, widely used for severe fractures requiring temporary stabilization. Internal fixators dominate due to high adoption of plates, screws, and nails that provide permanent fixation and better healing outcomes. It benefits from rising demand for minimally invasive fixation systems. Growth in advanced product designs enhances clinical performance and drives higher acceptance across orthopedic practices.
- For instance, locking plates, made from surgical grade titanium or stainless steel, are widely used to maintain bone alignment in complex fractures, minimizing stress on the bone and promoting faster healing.
By Material
The trauma fixation devices market is categorized into stainless steel, titanium, and others. Stainless steel maintains strong demand for its cost-effectiveness and durability, making it suitable for developing regions. Titanium records higher adoption in advanced healthcare systems due to superior biocompatibility, lighter weight, and reduced risk of allergic reactions. It strengthens patient outcomes by supporting faster bone integration. Increasing use of novel composite materials also reflects industry efforts to improve long-term safety and efficiency.
- For instance, DePuy Synthes offers titanium-based fixation devices, and multiple clinical studies have shown titanium plates are associated with lower device failure rates and fewer complications compared to stainless steel, especially in distal femur fracture repairs .
By Site
The trauma fixation devices market is divided into lower extremities and upper extremities applications. Lower extremities, including hip and pelvic, lower leg, knee, foot and ankle, and thigh fractures, account for the largest share due to higher frequency of road accidents and osteoporosis-related injuries. Upper extremities, comprising hand and wrist, shoulder, elbow, and arm, also show strong growth driven by sports-related trauma. It creates steady demand for customized fixation devices that address site-specific surgical needs effectively.
Segments:
Based on Product
- External Fixators
- Unilateral And Bilateral
- Circular
- Hybrid
- Internal Fixators
-
- Plates
- Screws
- Nails
- Others
Based on Material
- Stainless Steel
- Titanium
- Others
Based on Site
- Lower Extremities
- Hip And Pelvic
- Lower Leg
- Knee
- Foot & Ankle
- Thigh
- Upper Extremities
-
- Hand & Wrist
- Shoulder
- Elbow
- Arm
Based on End-use
- Hospitals
- Ambulatory Surgical Centers
- Orthopedic Centers
- Others
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
North America holds the largest share of the trauma fixation devices market at 35%, driven by advanced healthcare infrastructure and high adoption of innovative orthopedic technologies. Strong presence of leading manufacturers and increasing investments in research support continuous product innovation. Rising incidence of osteoporosis and sports-related injuries contributes significantly to device demand. It benefits from favorable reimbursement policies that enhance accessibility to advanced surgical procedures. Growing use of robotics and navigation-assisted systems further strengthens regional growth.
Europe
Europe accounts for 28% of the trauma fixation devices market, supported by rising geriatric population and strong emphasis on patient safety standards. Well-established healthcare systems and extensive adoption of minimally invasive procedures enhance the use of advanced fixation devices. Regulatory frameworks encourage the availability of high-quality implants across the region. It reflects steady demand across countries with aging populations. Growing focus on sustainability in medical devices also creates opportunities for bioabsorbable fixation systems.
Asia Pacific
Asia Pacific represents 22% of the trauma fixation devices market, with growth fueled by rising medical tourism, expanding healthcare infrastructure, and increasing road accidents. Governments invest heavily in trauma care centers and orthopedic facilities to meet rising demand. Countries such as China and India experience higher adoption of cost-effective fixation solutions. It benefits from increasing insurance coverage and affordability of surgical procedures. Rapid urbanization and a growing middle-class population further stimulate demand for orthopedic trauma care.
Latin America
Latin America holds 9% of the trauma fixation devices market, supported by expanding healthcare modernization and growing awareness of advanced trauma care solutions. Rising prevalence of traffic-related injuries creates steady demand for both internal and external fixators. Brazil and Mexico lead adoption with government-backed initiatives in orthopedic healthcare. It experiences growth as private hospitals increase investments in advanced surgical equipment. Rising collaborations with international manufacturers also improve access to innovative trauma fixation technologies.
Middle East & Africa
The Middle East & Africa account for 6% of the trauma fixation devices market, with growth supported by increasing healthcare investments and rising medical tourism in Gulf countries. Growing demand for orthopedic treatments in urban centers drives adoption of fixation systems. It benefits from gradual improvements in healthcare infrastructure across African nations. Rising prevalence of musculoskeletal injuries further strengthens demand. Collaborations between regional healthcare providers and global manufacturers enhance availability of advanced fixation devices.
Key Player Analysis
- Wright Medical Group
- Medicon eG.
- Smith+Nephew
- Arthrex
- Johnson & Johnson
- Orthofix US
- Implanet
- Zimmer Biomet
- Integra Lifescience
- B Braun Melsungen
- Bioretec
- Stryker
- KLS Martin Group
- CONMED
Competitive Analysis
The trauma fixation devices market is highly competitive with a mix of global leaders and specialized players driving innovation and market expansion. It is shaped by companies focusing on advanced technologies, biocompatible materials, and minimally invasive solutions to strengthen clinical outcomes and surgeon adoption. Major players such as Johnson & Johnson, Stryker, Zimmer Biomet, Smith+Nephew, and Arthrex maintain strong positions through broad product portfolios, global distribution networks, and continuous R&D investments. Firms like Wright Medical Group, Orthofix US, Integra Lifescience, and CONMED emphasize niche expertise in fixation systems tailored for complex trauma cases. B Braun Melsungen, KLS Martin Group, and Medicon eG. expand their presence by offering cost-effective devices that appeal to diverse healthcare systems. Emerging companies such as Bioretec and Implanet focus on bioabsorbable implants and patient-specific solutions, adding competition through specialized innovations. It remains characterized by strategic collaborations, product launches, and acquisitions that enhance technological capabilities and global market reach while addressing rising demand for safe, efficient, and patient-centric trauma care solutions.
Recent Developments
- In 2024, Johnson & Johnson’s DePuy Synthes launched the VOLT™ Plating System and the TriLEAP™ Lower Extremity Anatomic Plating System, designed to improve anatomical precision and support minimally invasive trauma procedures.
- In August 2024, Stryker introduced the Pangea Plating System, a versatile variable-angle internal fixation platform tailored to diverse orthopedic trauma cases.
- In February 2025, Bioretec received CE Mark approval for its RemeOs™ Trauma Screws, developed using a proprietary magnesium alloy that provides strong, bioabsorbable fixation.
- In June 2023, Acuitive Technologies Inc. announced the inaugural surgical use of its Citrelock ACL Tendon Fixation Device with a novel design incorporating resorbable technology for tendon fixation procedures.
Market Concentration & Characteristics
The trauma fixation devices market reflects moderate to high concentration with global leaders maintaining strong positions through diversified product portfolios, extensive distribution networks, and continuous innovation. It is characterized by a mix of multinational corporations and specialized regional players competing on technology, pricing, and clinical outcomes. Leading companies invest heavily in research and development to introduce bioabsorbable materials, 3D-printed implants, and minimally invasive systems, enhancing their competitive advantage. The market also shows strong regulatory influence, requiring compliance with stringent approval standards that favor established players with robust resources. It remains driven by rising global demand, yet price sensitivity in developing regions creates opportunities for cost-effective solutions. Competitive dynamics are defined by mergers, acquisitions, and strategic partnerships that expand market reach and strengthen product offerings. It continues to evolve with growing adoption of robotics, navigation-assisted systems, and patient-specific implants that differentiate players in a steadily expanding orthopedic landscape.
Report Coverage
The research report offers an in-depth analysis based on Product, Material, Site, End-Use and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Rising accident rates and aging populations will continue driving global demand for trauma fixation devices.
- Hospitals will increasingly adopt minimally invasive fixation systems to improve patient safety and faster recovery.
- Surgeons will prefer bioabsorbable and biocompatible materials that reduce complications and eliminate removal procedures.
- 3D printing technologies will accelerate personalized implant development, offering patient-specific solutions for complex trauma cases.
- Robotics and AI-guided navigation systems will enhance surgical precision and significantly improve long-term patient outcomes.
- Emerging economies will witness growing adoption supported by expanding trauma centers and government healthcare investments.
- Medical tourism in Asia and Middle East will boost demand for advanced orthopedic trauma fixation devices.
- Strategic partnerships and acquisitions among global manufacturers will strengthen innovation pipelines and expand market presence.
- Increasing healthcare digitalization will support integration of real-time monitoring systems for post-surgical trauma recovery.
- Manufacturers will focus on cost-effective devices to penetrate low-income markets while ensuring reliable trauma care.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Incidence of Road Accidents and Sports Injuries
Increasing rates of road accidents and sports-related trauma globally are leading to a higher number of fractures and musculoskeletal injuries, directly boosting demand for trauma fixation devices in both emergency and elective surgical settings.
Growing Burden of Osteoporosis and Musculoskeletal Disorders
The aging population and rising prevalence of osteoporosis and degenerative bone diseases are increasing the frequency of fragility fractures, necessitating long-term reliance on fixation systems for effective treatment and recovery.
Technological Advancements in Fixation Systems
Innovations such as bioabsorbable implants, 3D-printed patient-specific devices, and robotics-assisted surgeries are improving surgical precision, reducing complications, and enhancing patient outcomes, thereby accelerating market adoption.
Expanding Healthcare Infrastructure in Emerging Economies
Significant investments in trauma centers, orthopedic facilities, and healthcare modernization in developing regions are improving access to advanced fixation devices, supporting market growth through increased treatment availability and affordability.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for trauma fixation devices market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the trauma fixation devices market projected to grow between 2025 and 2032?
What are the primary factors fueling the growth of the trauma fixation devices market?
Who are the leading companies in the trauma fixation devices market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Site
- 1.2.1 Lower Extremities
- 1.2.2 Upper Extremities
- 1.3 By End-use
- 1.3.1 Hospitals
- 1.3.2 Ambulatory Surgical Centers
- 1.3.3 Orthopedic Centers
- 1.3.4 Others
- 1.4 By Product
- 1.4.1 External Fixators
- 1.4.2 Internal Fixators
- 1.4.3 Others
- 1.5 By Material
- 1.5.1 Stainless Steel
- 1.5.2 Titanium
- 1.5.3 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 9,136.4 million → 2032: USD 12,552 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Trauma Fixation Devices Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Trauma Fixation Devices Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Trauma Fixation Devices Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Trauma Fixation Devices Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Trauma Fixation Devices Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Trauma Fixation Devices Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Trauma Fixation Devices Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Trauma Fixation Devices Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 9,136.4 million → 2032: USD 12,552 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Trauma Fixation Devices Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Site - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Lower Extremities
- 12.3.7.2 Upper Extremities
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By End-use - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Hospitals
- 12.4.7.2 Ambulatory Surgical Centers
- 12.4.7.3 Orthopedic Centers
- 12.4.7.4 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Product - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 External Fixators
- 12.5.7.2 Internal Fixators
- 12.5.7.3 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Material - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Stainless Steel
- 12.6.7.2 Titanium
- 12.6.7.3 Others
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Trauma Fixation Devices End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Trauma Fixation Devices Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Trauma Fixation Devices Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Trauma Fixation Devices Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Johnson & Johnson
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Stryker
- 18.4 Zimmer Biomet
- 18.5 Smith+Nephew
- 18.6 Arthrex
- 18.7 Orthofix US
- 18.8 B Braun Melsungen
- 18.9 Wright Medical Group
- 18.10 Integra Lifesciences
- 18.11 CONMED
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

