
Market Overview
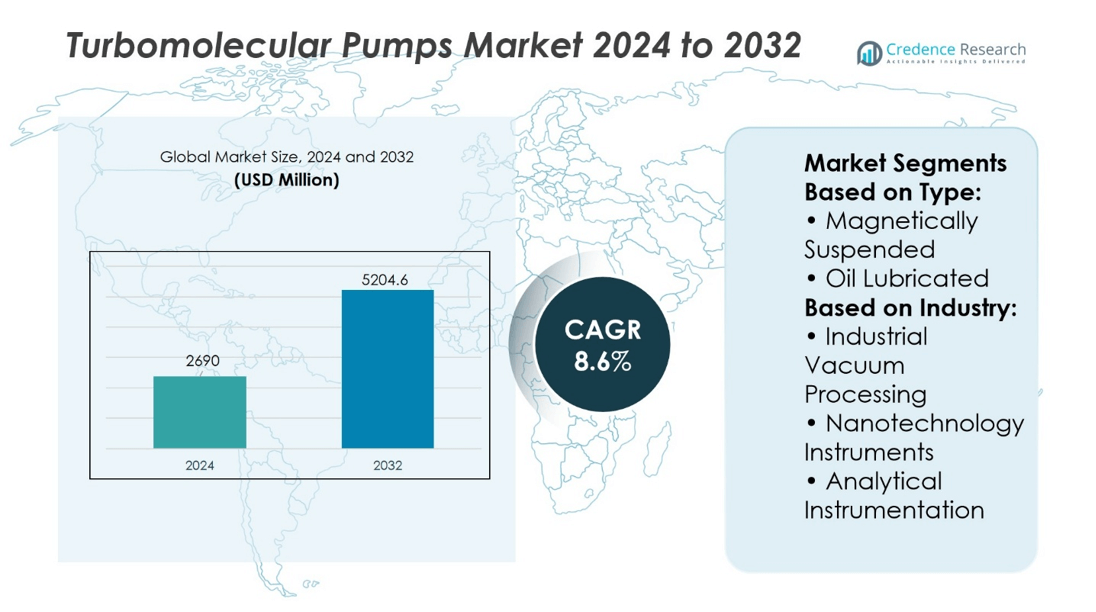
Turbomolecular Pumps Market size was valued at USD 2690 million in 2024 and is anticipated to reach USD 5204.6 million by 2032, at a CAGR of 8.6% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Turbomolecular Pumps Market Size 2024 | USD 2690 million |
| Turbomolecular Pumps Market, CAGR | 8.6% |
| Turbomolecular Pumps Market Size 2032 | USD 5204.6 million |
The Turbomolecular Pumps Market grows with rising demand for ultra-high-vacuum solutions in semiconductor manufacturing, nanotechnology, and advanced analytical instrumentation. It benefits from increasing adoption in aerospace testing, industrial coating, and research laboratories requiring contamination-free environments. Energy-efficient designs, compact form factors, and hybrid pump configurations drive product innovation. Integration of smart monitoring and predictive maintenance enhances operational reliability, aligning with the shift toward Industry 4.0 practices. Expanding applications in renewable energy research and high-precision manufacturing further strengthen market potential, while advancements in rotor design and magnetic bearing technology support performance improvements across diverse industrial and scientific sectors.
The Turbomolecular Pumps Market shows strong presence across Asia-Pacific, North America, and Europe, with Asia-Pacific leading due to extensive semiconductor and electronics manufacturing. North America benefits from advanced aerospace, research, and analytical sectors, while Europe is supported by industrial manufacturing and nanotechnology research. Key players include Shimadzu Corporation, Busch LLC, Pfeiffer Vacuum GmbH, Edwards, KYKY Technology Co. LTD, EBARA Technologies, Inc., Ulvac, Inc., Osaka Vacuum GmbH, Leybold USA Inc, and Agilent, each focusing on innovation, energy efficiency, and application-specific solutions.
Market Insights
- The Turbomolecular Pumps Market size was valued at USD 2690 million in 2024 and is projected to reach USD 5204.6 million by 2032, at a CAGR of 8.6%.
- Rising demand for ultra-high-vacuum solutions in semiconductor manufacturing, nanotechnology, and analytical instrumentation drives growth.
- Energy-efficient designs, compact configurations, and hybrid pump models shape ongoing product innovation.
- Competition remains strong with leading players focusing on advanced rotor designs, magnetic bearings, and predictive maintenance integration.
- High initial investment and sensitivity to operating conditions limit adoption in certain industrial sectors.
- Asia-Pacific leads the market, followed by North America and Europe, supported by sector-specific strengths in manufacturing, aerospace, and research.
- Expanding adoption in renewable energy research, high-precision manufacturing, and industrial coating processes boosts long-term market potential.
Market Drivers
Increasing Demand for High-Vacuum Environments in Semiconductor Manufacturing
The Turbomolecular Pumps Market grows with the expanding semiconductor industry, which requires ultra-clean and high-vacuum conditions for wafer fabrication. It enables precise control over contamination levels, critical for producing advanced microchips. Equipment manufacturers integrate these pumps into etching, deposition, and inspection systems to maintain required vacuum levels. Rising production of microprocessors, memory devices, and sensors strengthens the need for consistent, reliable vacuum performance. It supports higher yield rates and improved device quality. Leading suppliers focus on delivering pumps with optimized rotor designs and lower vibration for better integration into sensitive semiconductor processes.
- Edwards Vacuum recently celebrated a major production milestone with the delivery of their 250,000th STP turbomolecular pump, highlighting the widespread use of these pumps in the semiconductor industry.
Advancement in Analytical Instrumentation Across Research and Industrial Sectors
The Turbomolecular Pumps Market benefits from growing use in analytical equipment such as mass spectrometers and electron microscopes. It achieves stable, high-vacuum performance, essential for accurate measurement and imaging. Research laboratories and industrial quality control facilities adopt these pumps to ensure repeatable, high-precision results. The shift toward more complex and miniaturized analytical systems drives demand for compact, high-efficiency pump models. It contributes to faster analysis cycles and enhanced throughput. Manufacturers respond by developing units with reduced maintenance requirements to support continuous operation in demanding environments.
- For instance, Edwards Vacuum has shipped over 320,000 turbomolecular pumps and pumping stations across sectors including analytical instrumentation.
Expansion of Space Exploration and Satellite Development Activities
The Turbomolecular Pumps Market experiences growth from the aerospace sector’s increasing satellite launches and space missions. It provides the vacuum conditions necessary for testing spacecraft components and simulating space environments. Facilities use these pumps in thermal-vacuum chambers to validate performance of satellite subsystems. Growing private and governmental investment in satellite constellations amplifies the requirement for dependable high-vacuum systems. It helps ensure mission reliability and compliance with strict testing protocols. Pump manufacturers design models capable of operating under extended duty cycles to match aerospace application needs.
Rising Adoption in Vacuum Coating Processes for Industrial Applications
The Turbomolecular Pumps Market supports a broad range of vacuum coating applications in optics, automotive, and electronics industries. It enables precise deposition of thin films for lenses, displays, and functional coatings. Production lines use these pumps to maintain uniform vacuum levels, ensuring consistent coating thickness and quality. Increasing demand for energy-efficient coatings, including low-emissivity glass and solar control films, stimulates pump adoption. It plays a role in improving process stability and reducing defect rates. Manufacturers enhance pump durability and performance to meet high-volume industrial production requirements.
Market Trends
Integration of Energy-Efficient Designs to Reduce Operational Costs
The Turbomolecular Pumps Market witnesses a shift toward energy-efficient models that lower power consumption without compromising performance. It addresses the operational cost concerns of end users in semiconductor, research, and industrial sectors. Manufacturers adopt advanced rotor balancing techniques and optimized motor control systems to improve efficiency. Demand grows for pumps with variable speed operation to match vacuum requirements in real time. It reduces heat generation and extends equipment lifespan. Suppliers highlight these features to meet sustainability goals and enhance competitive positioning.
- For instance, Pfeiffer Vacuum has deployed over 180,000 energy-optimized HiPace turbomolecular pumps in semiconductor and analytical installations worldwide.
Miniaturization and Compact Form Factors for Space-Constrained Applications
The Turbomolecular Pumps Market sees increased demand for compact designs suitable for integration into portable and space-limited systems. It responds to the needs of analytical instruments, portable mass spectrometers, and mobile vacuum testing units. Engineers focus on reducing pump weight and footprint while retaining high pumping speeds. Miniaturized pumps enable greater flexibility in system design and transportation. It supports applications in field-based research, environmental monitoring, and mobile laboratories. Manufacturers expand product portfolios with lightweight, high-speed models to address this niche but growing segment.
- For instance, Agilent Technologies has produced over 50,000 TPS-mini integrated turbo pumping units, each combining a 70 L/s turbomolecular pump.
Integration of Smart Monitoring and Predictive Maintenance Capabilities
The Turbomolecular Pumps Market incorporates digital features that enhance operational reliability and maintenance planning. It includes embedded sensors that track vibration, temperature, and rotational speed in real time. Predictive analytics software interprets this data to forecast potential issues before failures occur. Users benefit from reduced unplanned downtime and optimized service intervals. It aligns with the broader industry adoption of Industrial Internet of Things (IIoT) technologies. Manufacturers develop pumps with integrated communication interfaces for seamless data exchange with plant monitoring systems.
Adoption of Hybrid Pump Configurations for Broader Application Coverage
The Turbomolecular Pumps Market experiences a trend toward hybrid designs that combine turbomolecular and backing pump technologies in a single unit. It provides wider operating ranges and eliminates the need for separate roughing systems. Such integration simplifies installation, reduces system complexity, and lowers maintenance requirements. Hybrid pumps serve applications in semiconductor fabrication, surface analysis, and high-vacuum coating. It delivers consistent performance across varying pressure ranges, improving operational flexibility. Manufacturers invest in developing multi-stage hybrid systems to meet diverse industry demands.
Market Challenges Analysis
High Initial Investment and Maintenance Complexity Limiting Broader Adoption
The Turbomolecular Pumps Market faces challenges from the significant upfront costs associated with advanced high-vacuum systems. It demands precision engineering, specialized materials, and stringent manufacturing tolerances, all contributing to higher prices. Smaller laboratories, startups, and cost-sensitive industries often delay adoption due to budget constraints. Maintenance requires skilled technicians familiar with high-speed rotor assemblies and delicate bearing systems, which raises operational expenses. It increases the total cost of ownership and can deter long-term commitments. Manufacturers work to address these concerns by offering modular designs and extended service intervals, yet the challenge remains significant in price-sensitive markets.
Sensitivity to Operating Conditions and Limited Durability in Harsh Environments
The Turbomolecular Pumps Market also contends with performance limitations in environments with high particulate levels, corrosive gases, or frequent power fluctuations. It operates most effectively in clean, controlled conditions, which restricts deployment in certain industrial settings. Exposure to contaminants can degrade rotor balance and bearing life, leading to costly downtime. It requires integration with pre-pumping stages and filtration systems to maintain performance, which adds complexity. Durability issues under harsh operational demands push end users to consider alternative vacuum technologies. Manufacturers invest in protective coatings, magnetic bearings, and advanced sealing systems to mitigate these operational risks, but the constraints remain a barrier in some sectors.
Market Opportunities
Expansion in Emerging Semiconductor and Electronics Manufacturing Hubs
The Turbomolecular Pumps Market has strong growth potential in emerging semiconductor production regions across Asia-Pacific, Eastern Europe, and the Middle East. It benefits from increasing investments in advanced fabrication plants and electronics assembly facilities. Governments and private investors commit significant resources to developing domestic chip production capabilities, creating new demand for high-vacuum systems. The pumps support precise deposition, etching, and inspection processes essential to producing high-performance devices. It also aligns with national strategies to secure semiconductor supply chains and reduce reliance on imports. Manufacturers can capitalize on this trend by establishing localized production and service facilities to meet rising regional demand.
Rising Adoption in Renewable Energy and Advanced Materials Research
The Turbomolecular Pumps Market holds opportunities in research applications related to solar cells, hydrogen fuel systems, and novel material coatings. It enables controlled environments for thin-film deposition, surface modification, and advanced coating technologies. Universities, R&D centers, and clean energy startups expand their infrastructure to support next-generation energy solutions, creating steady demand for reliable vacuum performance. The pumps’ ability to deliver stable, ultra-high-vacuum conditions enhances process quality and repeatability. It positions the technology as a critical enabler for innovation in energy-efficient products and sustainable materials. Manufacturers can strengthen their market position by partnering with research institutions and energy technology developers to integrate customized solutions.
Market Segmentation Analysis:
By Type
The Turbomolecular Pumps Market divides into magnetically suspended and oil lubricated types, each addressing distinct operational requirements. Magnetically suspended pumps operate without physical contact between rotor and bearings, reducing wear and enabling long service life. It supports ultra-clean applications where the absence of lubricants prevents contamination, making them ideal for semiconductor manufacturing and high-purity research. Oil lubricated pumps offer a cost-effective alternative with robust performance in less sensitive environments. They provide reliable vacuum generation for industrial processes where minor contamination risk is acceptable. It ensures versatility across market segments by accommodating both high-specification and cost-conscious users.
- For instance, Leybold's Turbovac MAG iS maglev series has seen over 10,000 units shipped, highlighting its success in research and industrial settings.
By Industry
The Turbomolecular Pumps Market serves industrial vacuum processing in sectors such as coating, metallurgy, and electronics production. It enables precise control over deposition and treatment processes, ensuring uniform product quality. Manufacturers use these pumps in large-scale coating chambers for glass, optics, and automotive components. It supports consistent vacuum levels critical to adhesion, durability, and functional performance of applied coatings. High pumping speeds and stable operation allow for greater throughput and reduced process times. This segment benefits from ongoing demand for advanced materials and surface treatments in multiple industries.
- For instance, Edwards Vacuum has supplied over 70,000 turbomolecular pumps to vacuum-coating lines in flat-panel display and solar-cell deposition systems.
Segments:
Based on Type:
- Magnetically Suspended
- Oil Lubricated
Based on Industry:
- Industrial Vacuum Processing
- Nanotechnology Instruments
- Analytical Instrumentation
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis
North America
North America accounts for 28% share of the Turbomolecular Pumps Market, driven by strong demand from the semiconductor, aerospace, and analytical instrumentation sectors. The region benefits from established semiconductor fabrication hubs in the United States, which require advanced high-vacuum solutions for wafer processing and inspection. It also supports extensive aerospace research and satellite development programs that utilize these pumps for thermal-vacuum testing. Growth in biotechnology and life sciences research further boosts adoption in analytical instruments such as mass spectrometers and electron microscopes. Leading manufacturers maintain significant service networks across the region to ensure operational reliability for critical applications. Continuous investment in R&D and manufacturing capacity strengthens North America’s competitive positioning.
Europe
Europe holds 25% share of the Turbomolecular Pumps Market, supported by a strong base of industrial manufacturing, research institutions, and space exploration initiatives. The region is home to major nanotechnology and advanced materials research centers, which rely on ultra-high-vacuum systems for precision experimentation. It also has a mature semiconductor ecosystem in countries like Germany, France, and the Netherlands, where demand for contamination-free processing drives pump usage. European aerospace and defense sectors contribute to consistent procurement for vacuum testing facilities. Manufacturers in the region emphasize sustainable design and energy-efficient pump technologies to align with environmental regulations. Robust collaborations between industry and academia create steady opportunities for innovation in this market.
Asia-Pacific
Asia-Pacific commands the largest share at 35% of the Turbomolecular Pumps Market, fueled by rapid expansion in semiconductor manufacturing, electronics production, and nanotechnology research. Countries such as China, Japan, South Korea, and Taiwan dominate global semiconductor output, necessitating high-volume deployment of turbomolecular pumps. It also benefits from a growing network of research laboratories and universities investing in advanced analytical instrumentation. The presence of large-scale electronics and display panel manufacturing further amplifies demand. Regional governments actively support technology infrastructure development, which encourages adoption across multiple industries. Local manufacturing capabilities and competitive pricing from regional suppliers enhance accessibility for both domestic and international buyers.
Latin America
Latin America represents 7% share of the Turbomolecular Pumps Market, with demand primarily concentrated in industrial vacuum processing and research applications. Brazil and Mexico lead adoption due to their growing automotive, aerospace, and materials processing sectors. It supports industrial coating processes, metallurgy, and quality control laboratories. Expansion of research and development facilities, particularly in academic institutions, creates niche opportunities for analytical instrumentation integration. Limited domestic manufacturing of high-end vacuum systems leads to reliance on imports from North America, Europe, and Asia-Pacific. Strategic partnerships with global suppliers help bridge this gap and ensure technical support for regional end users.
Middle East & Africa
The Middle East & Africa accounts for 5% share of the Turbomolecular Pumps Market, with activity centered in research facilities, energy projects, and specialized industrial processes. Countries in the Gulf Cooperation Council invest in advanced testing infrastructure for aerospace and defense applications. South Africa and Israel show demand from nanotechnology research and high-precision manufacturing. It also finds applications in energy sector laboratories, including those focused on renewable technologies and petrochemical analysis. Limited regional production capacity encourages imports, while international manufacturers often collaborate with local distributors to expand market presence. Growing interest in scientific research and technology innovation underpins steady long-term demand in this region.
Key Player Analysis
- Shimadzu Corporation
- Busch LLC
- Pfeiffer Vacuum GmbH
- Edwards
- KYKY Technology Co. LTD
- EBARA Technologies, Inc.
- Ulvac, Inc
- Osaka Vacuum GmbH
- Leybold USA Inc
- Agilent
Competitive Analysis
The Turbomolecular Pumps Market features such as Shimadzu Corporation, Busch LLC, Pfeiffer Vacuum GmbH, Edwards, KYKY Technology Co. LTD, EBARA Technologies, Inc., Ulvac, Inc., Osaka Vacuum GmbH, Leybold USA Inc, and Agilent. The Turbomolecular Pumps Market is characterized by intense competition, with manufacturers focusing on technological innovation, product reliability, and application-specific performance. Companies differentiate through advancements in rotor design, magnetic bearing technology, and energy-efficient motor control systems to meet the stringent requirements of industries such as semiconductors, nanotechnology, analytical instrumentation, and industrial vacuum processing. Global players invest in expanding manufacturing capabilities and establishing service networks to ensure quick response times and technical support. Strategic initiatives such as mergers, acquisitions, and collaborative partnerships enable access to new markets and strengthen supply chains. The market also sees a growing emphasis on digital integration, with pumps incorporating real-time monitoring and predictive maintenance to enhance operational uptime. Sustainability, cost efficiency, and long-term service contracts are emerging as critical factors influencing competitive positioning.
Recent Developments
- In February 2024, Shimadzu Corporation and Shimadzu Scientific Instruments (SSI) announced the development of an innovative technique, double isotope-mediated liquid chromatography.
- In January 2024, Agilent and Incyte announced a collaboration to develop Advanced Companion Diagnostics in Hematology and Oncology.
- In February 2023, ULVAC Technologies acquired KYKY Vacuum for an undisclosed amount.
Market Concentration & Characteristics
The Turbomolecular Pumps Market exhibits a moderately concentrated structure, with a limited number of global manufacturers holding a substantial share due to the high technical expertise and capital investment required for production. It is defined by advanced engineering capabilities, stringent quality standards, and strong intellectual property portfolios that create significant entry barriers for new competitors. Leading producers maintain competitive advantage through innovation in rotor dynamics, magnetic bearing systems, and energy-efficient drive technologies. The market serves specialized applications in semiconductor fabrication, nanotechnology, analytical instrumentation, and industrial vacuum processing, where reliability and precision are critical. It operates under a high degree of customer specification, often requiring tailored designs and application-specific performance parameters. Global distribution networks and localized service facilities play an important role in maintaining operational uptime for end users. The competitive landscape is further shaped by long-term supplier relationships, integration of predictive maintenance features, and adherence to evolving environmental and energy-efficiency regulations.
Report Coverage
The research report offers an in-depth analysis based on Type, Industry and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand will rise with the expansion of semiconductor fabrication facilities in emerging and established markets.
- Adoption will grow in nanotechnology research due to the need for ultra-high-vacuum conditions.
- Manufacturers will focus on compact, high-speed pump designs for space-limited applications.
- Integration of smart monitoring systems will improve predictive maintenance capabilities.
- Energy-efficient models will gain preference to align with sustainability objectives.
- Hybrid pump configurations will see increased use for broader pressure range coverage.
- The aerospace sector will boost demand through satellite and space exploration projects.
- Vacuum coating applications will expand in automotive, optics, and electronics industries.
- Localized production and service centers will strengthen supply chain resilience.
- Collaborations with research institutions will drive product innovation and application diversity.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Expansion of Semiconductor Manufacturing
The rapid growth of semiconductor fabrication facilities, especially in Asia-Pacific, is driving demand for turbomolecular pumps to maintain ultra-high-vacuum conditions essential for wafer processing and contamination control.
Advancements in Analytical Instrumentation
Increasing use of mass spectrometers, electron microscopes, and other high-precision analytical tools in research and industrial quality control requires stable, high-vacuum environments, boosting adoption of turbomolecular pumps.
Growth in Aerospace and Satellite Testing
Rising satellite launches and space exploration activities necessitate reliable high-vacuum systems for component testing and simulation, fueling demand for turbomolecular pumps in aerospace sectors.
Adoption in Industrial Vacuum Coating
Industries such as optics, automotive, and electronics rely on turbomolecular pumps for precise vacuum coating processes, ensuring consistent thin-film deposition and improved product quality.
Shift Toward Energy-Efficient and Smart Pump Designs
End users are increasingly seeking energy-efficient, compact, and digitally integrated turbomolecular pumps to reduce operational costs, enhance predictive maintenance, and align with sustainability and Industry 4.0 initiatives.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Turbomolecular Pumps Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Turbomolecular Pumps Market projected to grow between 2025 and 2032?
What are the primary factors fueling the growth of the Turbomolecular Pumps Market?
Who are the leading companies in the Turbomolecular Pumps Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Magnetically Suspended
- 1.2.2 Oil Lubricated
- 1.3 By Industry
- 1.3.1 Industrial Vacuum Processing
- 1.3.2 Nanotechnology Instruments
- 1.3.3 Analytical Instrumentation
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 2690 million → 2032: USD 5204.6 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Turbomolecular Pumps Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Turbomolecular Pumps Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Turbomolecular Pumps Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Turbomolecular Pumps Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Turbomolecular Pumps Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Turbomolecular Pumps Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Turbomolecular Pumps Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Turbomolecular Pumps Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 2690 million → 2032: USD 5204.6 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Turbomolecular Pumps Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Magnetically Suspended
- 12.3.7.2 Oil Lubricated
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Industry - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Industrial Vacuum Processing
- 12.4.7.2 Nanotechnology Instruments
- 12.4.7.3 Analytical Instrumentation
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global Turbomolecular Pumps End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Turbomolecular Pumps Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Turbomolecular Pumps Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Turbomolecular Pumps Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Shimadzu Corporation
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Busch LLC
- 18.4 Pfeiffer Vacuum GmbH
- 18.5 Edwards
- 18.6 KYKY Technology Co. LTD
- 18.7 EBARA Technologies, Inc.
- 18.8 Ulvac, Inc.
- 18.9 Osaka Vacuum GmbH
- 18.10 Leybold USA Inc
- 18.11 Agilent
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

