
Market Overview
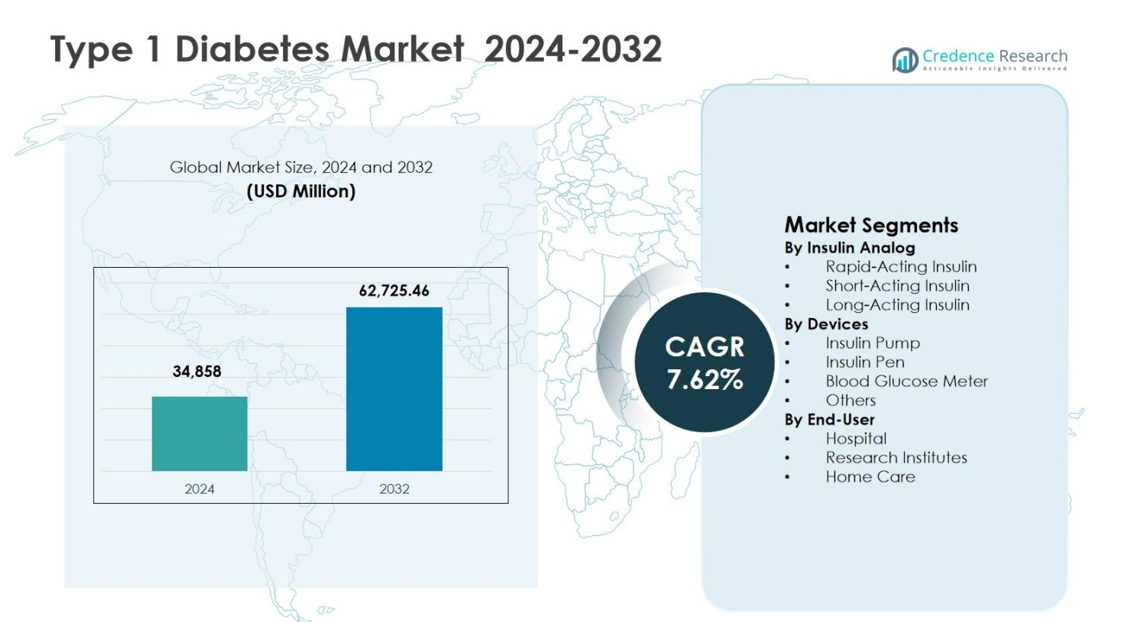
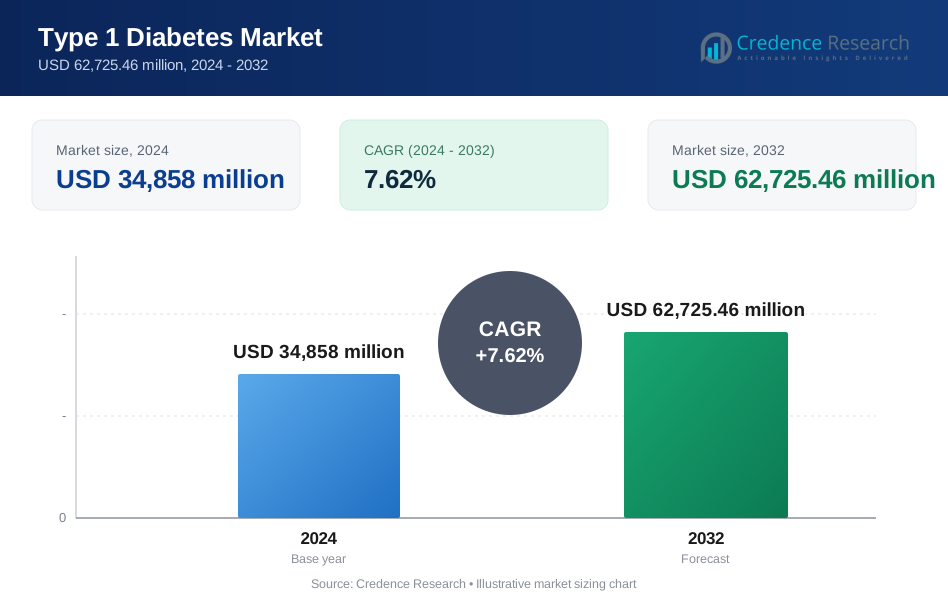
The Type 1 Diabetes Market size was valued at USD 34,858 million in 2024 and is anticipated to reach USD 62,725.46 million by 2032, expanding at a CAGR of 7.62% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Type 1 Diabetes Market Size 2024 | USD 34,858 million |
| Type 1 Diabetes Market, CAGR | 7.62% |
| Type 1 Diabetes Market Size 2032 | USD 62,725.46 million |
The Type 1 Diabetes Market is driven by the strong presence of leading pharmaceutical and medical device companies such as Sanofi S.A., Novo Nordisk A/S, Eli Lilly and Company, Abbott Laboratories, Medtronic plc, Dexcom, Inc., and Roche Holding AG, which focus on advanced insulin analogs, delivery systems, and glucose monitoring technologies. These players emphasize innovation, portfolio expansion, and digital integration to improve glycemic control and patient outcomes. Regionally, North America led the Type 1 Diabetes Market with a 38.4% share in 2024, supported by high disease prevalence, advanced healthcare infrastructure, strong reimbursement frameworks, and early adoption of insulin pumps and continuous glucose monitoring systems, reinforcing the region’s dominance in overall market revenue.
Market Insights
- The Type 1 Diabetes Market was valued at USD 34,858 million in 2024 and is projected to reach USD 62,725.46 million by 2032, growing at a CAGR of 7.62% during the forecast period, driven by sustained demand for insulin therapies and diabetes management devices.
- Growth in the Type 1 Diabetes Market is supported by rising global prevalence, early diagnosis rates, and continuous dependence on lifelong insulin therapy, increasing demand across insulin analogs, devices, and monitoring solutions.
- Key trends in the Type 1 Diabetes Market include higher adoption of long-acting insulin, which held a 48.6% segment share in 2024, and increasing use of insulin pens with a 42.9% share, driven by convenience, accuracy, and home-based care preference.
- The market landscape is shaped by established players focusing on insulin innovation, automated delivery systems, and glucose monitoring technologies, while high treatment costs and long-term therapy adherence challenges act as major restraints.
- Regionally, North America led the Type 1 Diabetes Market with a 38.4% share in 2024, followed by Europe at 27.1% and Asia Pacific at 22.8%, reflecting strong healthcare access and rising adoption of advanced diabetes care solutions.
Market Segmentation Analysis:
By Insulin Analog:
The Type 1 Diabetes Market by insulin analog is led by Long-Acting Insulin, which accounted for 48.6% market share in 2024, driven by its ability to provide stable basal insulin coverage and reduce the risk of hypoglycemia. Rapid-acting insulin followed with strong adoption due to its effectiveness in postprandial glucose control, particularly among intensive insulin therapy patients. Growth in this segment is supported by rising global prevalence of type 1 diabetes, increasing preference for advanced insulin regimens, and continuous product innovations aimed at improving glycemic stability and patient adherence.
- For instance, Eli Lilly's insulin lispro enabled reduced postprandial excursions and similar or improved HbA1c with lower severe hypoglycemia risk versus regular insulin across pediatric type 1 groups.
By Devices:
Within the devices segment, Insulin Pens dominated the Type 1 Diabetes Market with a 42.9% share in 2024, supported by ease of use, dosing accuracy, portability, and high patient acceptance in home-care settings. Insulin pumps are gaining traction due to improved glucose control and integration with continuous glucose monitoring systems, while blood glucose meters maintain steady demand for routine monitoring. Key growth drivers include rising adoption of self-management devices, increasing awareness of diabetes care technologies, and favorable reimbursement policies across developed healthcare systems.
- For instance, Medtronic's MiniMed 780G insulin pump, approved for type 1 diabetes patients aged 7 and above, automatically adjusts insulin delivery every 5 minutes based on CGM data, achieving up to 80% Time in Range in real-world adult studies without increasing hypoglycemia.
By End-User:
The Home Care segment emerged as the dominant end-user, capturing 54.3% of the Type 1 Diabetes Market share in 2024, driven by the chronic nature of the disease and the growing preference for self-administered insulin therapies. Hospitals continue to play a critical role in diagnosis and acute management, while research institutes contribute to clinical trials and therapeutic advancements. Expansion of home-based diabetes management programs, increasing availability of user-friendly devices, and rising healthcare cost optimization initiatives are key drivers supporting sustained growth in this segment.
Key Growth Drivers
Rising Global Prevalence of Type 1 Diabetes
The increasing incidence of type 1 diabetes across both pediatric and adult populations remains a primary growth driver for the Type 1 Diabetes Market. Improved diagnostic capabilities, expanding screening programs, and better disease awareness have led to higher identification rates worldwide. Lifestyle changes, genetic predisposition, and environmental triggers continue to contribute to disease onset. This expanding patient pool directly increases long-term demand for insulin analogs, monitoring devices, and supportive care solutions, sustaining consistent market expansion across developed and emerging healthcare systems.
- For instance, Abbott’s FreeStyle Libre sensor-based glucose monitoring system has shown in large real‑world studies in France and Sweden that wider use in people with type 1 diabetes is associated with significant HbA1c reductions and fewer hospitalizations, supporting sustained uptake of CGM in routine care.
Technological Advancements in Insulin Delivery and Monitoring
Rapid innovation in insulin delivery systems and glucose monitoring technologies significantly accelerates market growth. Advanced insulin pumps, smart insulin pens, and integrated continuous glucose monitoring systems enable precise dosing, improved glycemic control, and reduced complication risks. These innovations enhance patient convenience and treatment outcomes, driving higher adoption rates. Ongoing digital integration, including data-driven insulin management platforms and mobile health applications, further strengthens patient engagement and supports personalized diabetes management, boosting overall market penetration.
- For instance, Dexcom's G7 continuous glucose monitor delivers real-time interstitial glucose readings every 5 minutes to smartphones or receivers, with a 10-day waterproof sensor/transmitter.
Favorable Healthcare Policies and Reimbursement Support
Supportive healthcare policies and expanding reimbursement frameworks play a critical role in driving the Type 1 Diabetes Market. Governments and private insurers increasingly recognize the long-term cost benefits of effective diabetes management, leading to broader coverage for insulin therapies and diabetes devices. Improved access to advanced treatments reduces financial barriers for patients and encourages early adoption. Additionally, public health initiatives promoting diabetes care infrastructure and access to essential medicines continue to strengthen market growth globally.
Key Trends & Opportunities
Shift Toward Home-Based and Self-Managed Care
A strong shift toward home-based diabetes management represents a major trend in the Type 1 Diabetes Market. Patients increasingly prefer self-administered insulin therapies supported by easy-to-use devices and remote monitoring solutions. This trend improves treatment adherence, reduces hospital visits, and lowers overall healthcare costs. The growing availability of compact insulin pens, portable pumps, and digital monitoring tools creates significant opportunities for manufacturers to develop patient-centric solutions tailored to long-term home care needs.
- For instance, Insulet's Omnipod 5 tubeless pump delivers automated insulin via a wearable pod controlled by smartphone, enabling discreet home wear nearly anywhere an injection occurs.
Advancements in Disease-Modifying and Adjunct Therapies
Ongoing research into disease-modifying therapies and adjunct treatments presents significant growth opportunities. Innovations targeting immune modulation, beta-cell preservation, and improved insulin sensitivity aim to complement traditional insulin therapy. These advancements have the potential to improve long-term outcomes and reduce complications. Increasing clinical trial activity and investment in next-generation biologics and combination therapies position the market for long-term innovation-driven expansion beyond conventional insulin-based treatment approaches.
- For instance, Provention Bio's teplizumab, an anti-CD3 monoclonal antibody, delayed the onset of clinical type 1 diabetes by a median of two years in high-risk individuals in the TN-10 trial. Treated participants showed preserved C-peptide levels, indicating sustained beta-cell function, compared to placebo.
Key Challenges
High Treatment Costs and Affordability Constraints
The high cost of insulin therapies and advanced diabetes devices remains a significant challenge for the Type 1 Diabetes Market. Despite reimbursement support in certain regions, many patients face financial strain due to long-term treatment requirements. Price disparities across regions limit access in low- and middle-income countries, slowing adoption of innovative therapies. Persistent affordability concerns continue to create barriers to equitable healthcare access and restrain overall market growth potential.
Risk of Complications and Therapy Adherence Issues
Maintaining consistent therapy adherence remains a major challenge in managing type 1 diabetes. Complex insulin regimens, fear of hypoglycemia, and lifestyle-related factors can hinder proper disease management. Poor adherence increases the risk of long-term complications, including cardiovascular and renal conditions, leading to higher healthcare burdens. Addressing these challenges requires continuous patient education, simplified treatment protocols, and improved device usability to ensure sustained treatment effectiveness.
Regional Analysis
North America
North America dominated the Type 1 Diabetes Market with a 38.4% market share in 2024, supported by high disease prevalence, advanced healthcare infrastructure, and strong adoption of innovative insulin therapies and devices. The United States represents the largest contributor due to widespread use of long-acting insulin, insulin pumps, and continuous glucose monitoring systems. Favorable reimbursement frameworks, strong presence of leading pharmaceutical and medical device companies, and high patient awareness levels continue to drive treatment adherence. Ongoing investments in digital diabetes management platforms further strengthen the region’s leadership position.
Europe
Europe accounted for a 27.1% share of the Type 1 Diabetes Market in 2024, driven by well-established public healthcare systems and strong government support for chronic disease management. Countries such as Germany, the United Kingdom, and France contribute significantly through broad access to insulin analogs and advanced delivery devices. Rising pediatric diabetes cases and growing adoption of home-based insulin administration continue to support demand. Regulatory emphasis on early diagnosis, structured diabetes care programs, and increasing clinical research activity further enhance regional market stability and long-term growth prospects.
Asia Pacific
Asia Pacific held a 22.8% market share in 2024, reflecting rapid growth fueled by increasing diagnosis rates, improving healthcare access, and expanding urban populations. Countries including China, India, and Japan are witnessing rising awareness of type 1 diabetes management and gradual adoption of modern insulin therapies. Government initiatives aimed at strengthening diabetes care infrastructure and expanding insurance coverage support market expansion. The growing availability of affordable insulin products and portable monitoring devices is accelerating penetration across both urban and semi-urban healthcare settings.
Latin America
Latin America captured a 6.9% share of the Type 1 Diabetes Market in 2024, supported by gradual improvements in healthcare access and increasing focus on chronic disease management. Brazil and Mexico represent the primary contributors, driven by rising patient awareness and expanding public healthcare programs. Demand for insulin pens and blood glucose monitoring devices continues to grow as self-care adoption increases. However, cost sensitivity and uneven reimbursement coverage remain key factors influencing therapy access and treatment adoption across the region.
Middle East & Africa
The Middle East & Africa region accounted for a 4.8% market share in 2024, driven by improving diagnostic capabilities and expanding healthcare investments in key countries. Saudi Arabia, the United Arab Emirates, and South Africa lead regional demand due to growing diabetes awareness and modernization of healthcare infrastructure. Increasing government initiatives to improve access to essential insulin therapies and diabetes education programs support market growth. Despite progress, limited access in rural areas and affordability constraints continue to shape regional market dynamics.
Market Segmentations:
By Insulin Analog
- Rapid-Acting Insulin
- Short-Acting Insulin
- Long-Acting Insulin
By Devices
- Insulin Pump
- Insulin Pen
- Blood Glucose Meter
- Others
By End-User
- Hospital
- Research Institutes
- Home Care
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The Type 1 Diabetes Market is characterized by strong competition among established pharmaceutical and medical device companies, with Sanofi S.A. and Novo Nordisk A/S leading through extensive insulin analog portfolios and global distribution networks. Eli Lilly and Company continues to strengthen its position with advancements in rapid- and long-acting insulin therapies, while Abbott Laboratories, Dexcom, Inc., and Roche Holding AG drive innovation in blood glucose monitoring and integrated diabetes management solutions. Device-focused players such as Medtronic plc, Insulet Corporation, and Tandem Diabetes Care enhance market dynamics through advanced insulin pumps and automated delivery systems. Strategic investments in research, digital health integration, and geographic expansion enable these companies to strengthen market presence and sustain long-term growth.
Key Player Analysis
- Sanofi S.A.
- AstraZeneca PLC
- Novartis AG
- Pfizer Inc.
- Macrogenics, Inc.
- DiaVacs, Inc.
- Biodel, Inc.
- Boehringer Ingelheim GmbH
- Mannkind Corporation
- Abbott Laboratories
Recent Developments
- In September 2025, Medtronic plc received expanded FDA clearance for its MiniMed 780G system to integrate with Abbott’s glucose sensors, enhancing automated insulin delivery capabilities.
- In September 2025, Sanofi received approval from China's National Medical Products Administration for Tzield (teplizumab), the first disease-modifying therapy to delay stage 3 type 1 diabetes onset in adult and pediatric patients aged eight and older with stage 2 T1D.
- In July 2025, Sequel Med Tech launched its twiist automated insulin delivery system, initially compatible with Abbott's FreeStyle Libre 3 Plus CGM, offering personalized management for type 1 diabetes patients aged six and up with features like iiSure technology for accurate delivery
Report Coverage
The research report offers an in-depth analysis based on Insulin Analog, Devices, End User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Type 1 Diabetes Market will continue to expand due to rising global diagnosis rates across pediatric and adult populations.
- Advancements in long-acting and ultra-rapid insulin analogs will improve glycemic control and patient adherence.
- Adoption of automated insulin delivery systems integrated with continuous glucose monitoring will increase steadily.
- Home-based and self-managed diabetes care will gain further traction, reducing dependence on hospital-based treatment.
- Digital health platforms and data-driven insulin management tools will enhance personalized therapy approaches.
- Ongoing research into disease-modifying and adjunct therapies will reshape long-term treatment strategies.
- Emerging markets will experience faster adoption of insulin therapies supported by improving healthcare access.
- Strategic collaborations between pharmaceutical and device manufacturers will accelerate innovation.
- Regulatory support and expanding reimbursement coverage will improve access to advanced diabetes treatments.
- Focus on patient-centric device design and education will strengthen long-term treatment outcomes.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Global Prevalence of Type 1 Diabetes
The increasing incidence of type 1 diabetes in both pediatric and adult populations, driven by improved diagnostics and greater disease awareness, is expanding the patient pool and sustaining long-term demand for insulin therapies and monitoring devices.
Technological Advancements in Insulin Delivery and Monitoring
Innovations such as automated insulin pumps, smart pens, and continuous glucose monitoring systems are enhancing glycemic control, patient convenience, and adherence, thereby accelerating market growth and adoption of advanced diabetes management solutions.
Shift Toward Home-Based and Self-Managed Care
The growing preference for self-administered insulin therapies and home-based monitoring, supported by user-friendly devices and digital health integration, is increasing treatment adherence and reducing reliance on hospital-based care.
Favorable Healthcare Policies and Reimbursement Support
Expanding reimbursement frameworks and supportive healthcare policies are improving patient access to advanced insulin analogs and diabetes devices, reducing financial barriers and encouraging early adoption of innovative treatments.
Ongoing Research in Disease-Modifying and Adjunct Therapies
Active clinical research into immune modulation, beta-cell preservation, and adjunct therapies is opening new avenues for improved long-term outcomes, complementing traditional insulin therapy and driving innovation-driven market expansion.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size of the Type 1 diabetes market? What is the projected market size of the Type 1 diabetes market by 2032?
What is the projected compound annual growth rate (CAGR) for the Type 1 diabetes market?
What is type 1 diabetes, and how is it characterized?
What are some key drivers of growth in the Type 1 diabetes market?
Who are the leading companies in the Type 1 Diabetes Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Devices
- 1.2.1 Insulin Pump
- 1.2.2 Insulin Pen
- 1.2.3 Blood Glucose Meter
- 1.2.4 Others
- 1.3 By End-User
- 1.3.1 Hospital
- 1.3.2 Research Institutes
- 1.3.3 Home Care
- 1.4 By Insulin Analog
- 1.4.1 Rapid-Acting Insulin
- 1.4.2 Short-Acting Insulin
- 1.4.3 Long-Acting Insulin
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 34,858 million → 2032: USD 62,725.46 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Type 1 Diabetes Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Type 1 Diabetes Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Type 1 Diabetes Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Type 1 Diabetes Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Type 1 Diabetes Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Type 1 Diabetes Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Type 1 Diabetes Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Type 1 Diabetes Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 34,858 million → 2032: USD 62,725.46 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Type 1 Diabetes Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Devices - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Insulin Pump
- 12.3.7.2 Insulin Pen
- 12.3.7.3 Blood Glucose Meter
- 12.3.7.4 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By End-User - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Hospital
- 12.4.7.2 Research Institutes
- 12.4.7.3 Home Care
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Insulin Analog - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Rapid-Acting Insulin
- 12.5.7.2 Short-Acting Insulin
- 12.5.7.3 Long-Acting Insulin
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Type 1 Diabetes End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Type 1 Diabetes Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Type 1 Diabetes Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Type 1 Diabetes Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Sanofi S.A.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Novo Nordisk A/S
- 18.4 Eli Lilly and Company
- 18.5 Abbott Laboratories
- 18.6 Medtronic plc
- 18.7 Dexcom, Inc.
- 18.8 Roche Holding AG
- 18.9 Insulet Corporation
- 18.10 Tandem Diabetes Care
- 18.11 Pfizer Inc.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

