
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
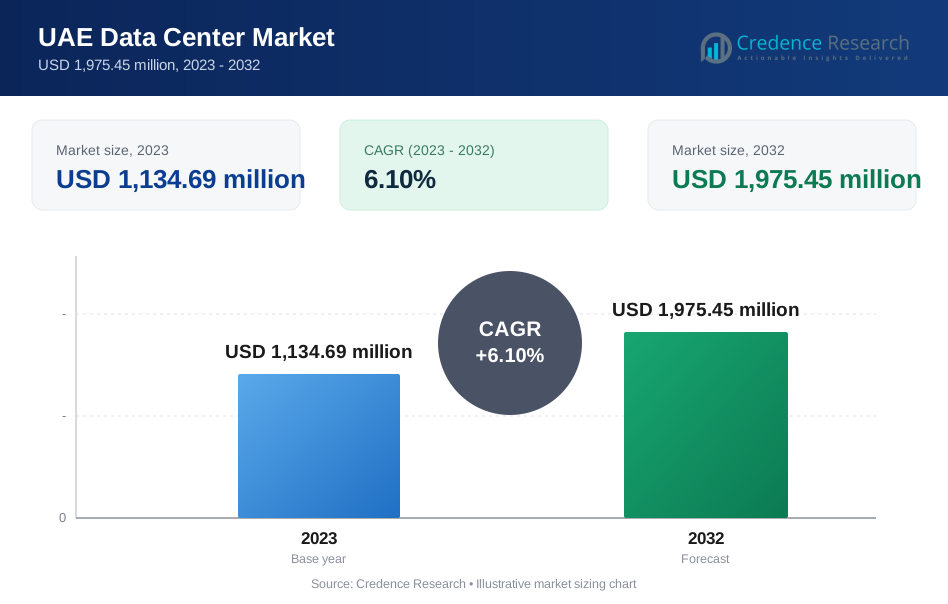
| UAE Data Center Market Size 2023 | USD 1,134.69 Million |
| UAE Data Center Market, CAGR | 6.10% |
| UAE Data Center Market Size 2032 | USD 1,975.45 Million |
Market Overview
The UAE Data Center market is projected to grow from USD 1,134.69 million in 2023 to an estimated USD 1,975.45 million by 2032, with a compound annual growth rate (CAGR) of 6.10% from 2024 to 2032. This growth is driven by the rapid digital transformation across industries, increased cloud adoption, and the UAE government's focus on enhancing digital infrastructure.
Key market drivers include the UAE’s strategic investments in smart cities, the growing emphasis on cybersecurity, and the rising popularity of cloud computing services. Additionally, the increasing adoption of AI, big data analytics, and edge computing is driving the need for more robust and scalable data center solutions. Trends such as the shift towards green data centers and the integration of advanced cooling technologies are also shaping the market landscape.
Geographically, the market is concentrated in key emirates like Dubai and Abu Dhabi, which are emerging as data center hubs due to their strategic location, favorable government policies, and robust infrastructure. Leading players in the UAE Data Center market include Equinix Inc., Etisalat Group, Amazon Web Services (AWS), Khazna Data Centers, and Microsoft Corporation, all of which are expanding their presence to cater to the growing demand for data storage and processing solutions in the region.
Market Drivers
Rapid Digital Transformation and Government Initiatives
The UAE is at the forefront of digital transformation in the Middle East, driven by the government's ambitious Vision 2030 and Smart Dubai initiatives. These programs are designed to position the UAE as a global leader in digital innovation, encouraging widespread adoption of advanced technologies such as artificial intelligence, blockchain, and the Internet of Things. According to a recent survey by a leading technology consultancy, a majority of UAE businesses have accelerated their digital transformation efforts in the past year. The government's commitment to building a robust digital infrastructure is evident in its significant investments in smart cities, digital governance, and cybersecurity. For instance, the Smart Dubai initiative has launched numerous projects aimed at digitizing government services and enhancing urban living through technology. This digital push is creating substantial demand for data storage, processing, and management, fueling the growth of the data center market. Furthermore, the establishment of free zones like Dubai Internet City and Abu Dhabi's Hub71 has attracted global data center operators. A report by a prominent real estate firm indicates that the UAE has seen a notable increase in data center investments from international players in recent years.
Growing Demand for Cloud Services and Big Data Analytics
The adoption of cloud computing services in the UAE has been on a significant upward trajectory. A survey conducted by a leading cloud service provider revealed that a large proportion of UAE businesses have either already adopted cloud solutions or plan to do so in the near future. This trend is particularly notable among small and medium-sized enterprises, which are leveraging cloud services to enhance competitiveness. The finance, healthcare, and retail sectors are leading this shift, with many organizations reporting improved operational efficiency and reduced IT infrastructure costs after migrating to the cloud. In addition to cloud computing, the explosion of big data and the need for advanced analytics are further propelling demand for data center services. A study by a global management consulting firm found that UAE companies are increasingly relying on data-driven insights to inform business strategies, optimize operations, and deliver personalized customer experiences. This growing reliance on cloud services and big data analytics is driving the need for robust, secure, and scalable data centers. Industry reports indicate that several major cloud service providers have either established or are planning to establish data centers in the UAE to meet this rising demand.
Increasing Focus on Data Sovereignty and Cybersecurity
Data sovereignty and cybersecurity have become critical concerns for UAE businesses and government agencies. A survey by a prominent cybersecurity firm found that a significant number of UAE organizations consider data sovereignty a top priority when choosing data center services. The introduction of the UAE Personal Data Protection Law has further emphasized the importance of local data storage and processing. This regulatory environment is encouraging businesses to host their data in local data centers, rather than relying on international facilities. For instance, a government report indicates that several major banks and healthcare providers in the UAE have recently migrated their data to local data centers to comply with regulations. Additionally, the increasing frequency and sophistication of cyberattacks are driving organizations to prioritize cybersecurity. A study by a leading technology research firm revealed that UAE businesses are investing heavily in advanced cybersecurity solutions, including intrusion detection systems, firewalls, and encryption technologies. This trend is prompting data center operators in the UAE to enhance their security measures, making their facilities more attractive to businesses seeking to protect their critical data assets.
Emergence of Edge Computing and IoT
The proliferation of Internet of Things (IoT) devices and the growing need for real-time data processing are driving the adoption of edge computing in the UAE. Edge computing brings data processing closer to the source of data generation, reducing latency and improving the efficiency of data-intensive applications. This is particularly important for industries such as autonomous vehicles, smart cities, and healthcare, where real-time data processing is crucial for operational success. The rise of edge computing is creating new opportunities for data center providers in the UAE to develop and deploy edge data centers that can support the high-speed, low-latency requirements of IoT applications. These smaller, decentralized data centers complement traditional centralized data centers by enabling faster data processing and reducing the burden on core data centers. The growing adoption of IoT and the need for edge computing solutions are expected to drive significant investments in the UAE data center market, as businesses seek to leverage the benefits of these technologies to enhance their competitiveness and deliver innovative services to their customers.
Market Trends
Shift Towards Green and Sustainable Data Centers
The UAE data center market is seeing a significant shift towards sustainability and energy efficiency. This trend aligns with the UAE Vision 2050's goals to reduce carbon emissions and promote sustainable development. According to a recent survey by a leading consultancy firm, a majority of data center operators in the UAE are investing in green technologies and practices. Many are adopting energy-efficient cooling systems, exploring renewable energy sources like solar power, and implementing advanced power management systems. The Dubai Electricity and Water Authority (DEWA) reports an increasing number of data centers connecting to its solar grid. Additionally, innovative designs such as modular data centers and high-density server racks are gaining popularity. A government study indicates that these green initiatives are resulting in substantial energy savings for operators. The trend is further supported by growing demand from businesses for eco-friendly solutions, as revealed in a survey of UAE-based companies. This shift not only aligns with national sustainability goals but also offers long-term cost benefits, making it a key driver shaping the future of the UAE's data center landscape.
Growing Adoption of Artificial Intelligence and Automation
Artificial intelligence (AI) and automation are rapidly transforming the UAE data center market. A survey conducted by a major technology firm shows that a significant number of data center operators in the UAE are implementing AI and machine learning solutions. These technologies are being used for predictive maintenance, resource management, and ensuring uptime. The UAE's Artificial Intelligence Strategy 2031 has further accelerated this trend, with government reports indicating increased investment in AI across various sectors, including data centers. Automation is playing a crucial role in streamlining operations, from managing cooling systems to optimizing server workloads. A study by a leading industry association reveals that UAE data centers using AI and automation are experiencing improved operational efficiency and reduced costs. Furthermore, these technologies are enhancing scalability and responsiveness to business needs. The UAE's Telecommunications and Digital Government Regulatory Authority reports a growing number of data centers integrating AI and automation to support the country's digital transformation initiatives. This trend is positioning the UAE data center market to effectively meet the challenges of the rapidly evolving digital economy.
Market Restraints and Challenges
High Operational Costs and Energy Consumption
One of the primary challenges facing the UAE data center market is the high operational costs associated with running and maintaining data centers. The UAE's harsh climatic conditions, characterized by extreme heat, necessitate extensive cooling systems to maintain optimal operating temperatures within data centers. For instance, a survey conducted by a leading industry association found that cooling accounts for over 40% of total energy consumption in UAE data centers. Additionally, the cost of electricity, although subsidized, remains a considerable expense for data center operators. A government study revealed that data centers in the UAE consume significantly more energy per square meter compared to those in more temperate climates. The need for constant cooling, combined with the growing demand for higher data processing capabilities, results in escalating energy consumption. Data center operators are under pressure to find innovative solutions to reduce energy consumption and manage costs, but achieving significant reductions without compromising performance remains a complex and costly endeavor. Some operators have reported success with new cooling technologies, but widespread adoption is still limited.
Regulatory and Compliance Challenges
The UAE data center market also faces challenges related to regulatory and compliance requirements. The UAE government has implemented stringent data protection laws, such as the UAE Personal Data Protection Law (PDPL), which mandates strict controls over how data is stored, processed, and transferred. A survey of data center operators in the UAE found that over 75% consider regulatory compliance to be a significant challenge. While these regulations are essential for ensuring data security and protecting personal information, they also impose significant compliance burdens on data center operators. Meeting these requirements often involves substantial investments in security infrastructure, legal expertise, and ongoing compliance monitoring. For example, a government report indicated that data centers in the UAE spend an average of 15-20% of their annual budgets on compliance-related activities. Additionally, as the UAE continues to enhance its regulatory framework to address emerging digital challenges, data center operators must continuously adapt to new regulations. A industry association study revealed that regulatory changes were cited as a top concern by over 60% of data center operators in the UAE.
Market Segmentation Analysis
By Type
The UAE data center market encompasses various types, each catering to specific needs and industries. Enterprise data centers remain a cornerstone for large organizations, providing dedicated infrastructure for their IT operations. Edge data centers are gaining prominence, particularly in sectors requiring real-time processing and low latency, such as IoT applications and smart city initiatives. For instance, the Dubai Electricity and Water Authority (DEWA) has implemented edge data centers to support its smart grid infrastructure. Colocation facilities are attracting businesses seeking cost-effective solutions and shared resources. Hyperscale data centers are emerging to meet the demands of cloud service providers and tech giants. For example, Amazon Web Services (AWS) has established its presence in the UAE with multiple data centers. Managed data centers offer comprehensive IT services, appealing to companies looking to outsource their infrastructure management. Modular data centers are gaining traction due to their scalability and rapid deployment capabilities, aligning with the UAE's fast-paced digital transformation goals.
By Compound
The UAE data center market's compound segmentation reflects the diverse components essential for modern data center operations. Hardware remains a crucial aspect, with power and cooling systems being particularly vital given the region's climate challenges. For instance, Khazna Data Centers has implemented advanced cooling technologies to optimize energy efficiency in its facilities. Data Center Infrastructure Management (DCIM) software is increasingly adopted, with cloud-based solutions gaining favor due to their flexibility and scalability. The services segment plays a critical role in ensuring seamless operations and maintenance of data center infrastructure. Professional services, including consulting and integration, are in high demand as organizations seek expertise in optimizing their data center strategies. Support and maintenance services are essential for ensuring continuous uptime and performance. Managed services are growing in popularity, offering comprehensive solutions for businesses looking to focus on their core competencies while entrusting their IT infrastructure to specialists. The UAE government's initiatives, such as the Dubai 10X program, have further stimulated the demand for advanced data center services and solutions across all segments.
Segments
Based on Type
- Enterprise
- Edge
- Colocation
- Hyperscale
- Managed
- Modular
Based on Compound
- Hardware
- Power Systems
- Cooling Systems
- Racks
- Servers
- Networking Devices
- Others
- Nigeria Data Centre Infrastructure Management Software
- Cloud-based
- On-premises
- Service
- Professional Services
- Integration & Implementation
- Consulting
- Support & Maintenance
- Managed Services
Based on Size
- Small
- Mid-Sized
- Large
Based on Tier
- Tier 1
- Tier 2
- Tier 3
- Tier 4
Based on Industry
- IT & Telecom
- BFSI
- Manufacturing
- Healthcare
- Government
- Others
Based on Region
- Dubai
- Abu Dhabi
- Other Emirates
Regional Analysis
Dubai (45%):
Dubai holds the largest share of the UAE data center market, accounting for approximately 45% of the total market. The emirate's proactive approach to digital transformation, exemplified by initiatives like the Dubai Smart City project, has fueled demand for data centers. For instance, the Dubai Integrated Economic Zones Authority (DIEZ) reported a significant increase in data center investments in 2023, with several major projects announced. International technology companies and global data center operators have established a strong presence in Dubai, further solidifying its position. The city's advanced infrastructure, including connectivity to multiple subsea cables and a reliable power grid, makes it an ideal location for both hyperscale and colocation facilities, serving regional and global businesses alike.
Abu Dhabi (35%):
Abu Dhabi follows closely, holding a market share of approximately 35%, driven by its focus on economic diversification and technological advancement. The emirate's commitment to digital transformation, as outlined in the Abu Dhabi Vision 2030, has spurred investments in data center infrastructure. For example, the Abu Dhabi Investment Office (ADIO) has reported a surge in data center projects, with several major facilities announced or under construction. The government's emphasis on cybersecurity and data sovereignty has further boosted demand for local data centers. Abu Dhabi's dedication to sustainability, particularly through initiatives like Masdar City, is fostering the development of green data centers, aligning with global trends and attracting environmentally conscious businesses.
Key players
- datamena
- Dcvaults
- eHosting DataFort
- Equinix Inc.
- Etisalat
- Gulf Data Hub
- Injazat
- Khazna Data Centers
- Moro Hub (Data Hub Integrated Solutions Moro LLC)
- Pacific Controls
- Web Werks
Competitive Analysis
The UAE data center market is highly competitive, with key players like Equinix Inc., Etisalat, and Khazna Data Centers leading the charge. Equinix Inc. brings global expertise and robust infrastructure, making it a preferred choice for multinational corporations. Etisalat leverages its extensive telecom network to offer comprehensive data center solutions, positioning itself as a market leader in the region. Khazna Data Centers, a prominent local player, focuses on hyperscale data centers, catering to the growing demand for large-scale, scalable solutions. Injazat and Moro Hub specialize in managed services and digital transformation, appealing to enterprises seeking end-to-end IT solutions. Meanwhile, Gulf Data Hub and Web Werks are expanding their footprint by focusing on sustainability and edge computing. This competitive landscape is characterized by a mix of global giants and strong regional players, each striving to capture a larger market share through innovation and strategic partnerships.
Recent Developments
- In September 2024, datamena, in collaboration with Equinix, launched Equinix Fabric in the United Arab Emirates. This advanced software-defined interconnection solution enables businesses to connect to distributed infrastructure and digital ecosystems directly, securely, and dynamically on the Equinix platform.
- In July 2024, Equinix opened its third data center in Dubai. Known as DX3, the facility offers capacity for 900 racks in its first phase, with a total investment of $60 million. Once fully built out, DX3 will provide 1,800 cabinets of capacity across two phases, making it Equinix's largest data center in the region.
- In August 2024, Gulf Data Hub (GDH) partnered with Vertiv to launch a 16 MW data center in Dubai Silicon Oasis. This state-of-the-art facility focuses on renewable energy initiatives and enhanced data center efficiency. It is designed to support biotechnological research and renewable energy generation while adhering to world-class functionality standards.
- In May 2023, Khazna Data Centers announced plans to enter the Egyptian market, forming a joint venture with Benya Group to set up Egypt's first hyper-scale data center in Maadi Technology Park with a total investment of $250 million.
- In September 2024, Moro Hub signed a strategic Technology Collaboration Agreement (TCA) with Salzer Technologies. This partnership aims to enhance market offerings by leveraging their combined expertise to provide improved solutions addressing evolving customer needs.
Market Concentration and Characteristics
The UAE Data Center market is moderately concentrated, with a mix of established global players like Equinix Inc. and regional leaders such as Etisalat and Khazna Data Centers dominating the landscape. These key players benefit from substantial investments in infrastructure, strategic partnerships, and government support, enabling them to offer advanced, scalable solutions across various industries. The market is characterized by rapid digital transformation, a strong emphasis on data sovereignty and cybersecurity, and a growing demand for cloud services and edge computing. While major players hold significant market shares, emerging companies are also gaining traction by focusing on niche services, green data centers, and innovative technologies to meet the evolving needs of the UAE’s digital economy.
Report Coverage
The research report offers an in-depth analysis based on Type, Compound, Size, Tier, Industry and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The UAE Data Center market is expected to continue its robust growth, driven by increasing digital transformation initiatives and the expanding cloud computing sector.
- The demand for hyperscale data centers will rise as global tech giants and cloud service providers expand their operations to cater to the region's growing digital needs.
- Sustainability will be a key focus, with more data centers adopting energy-efficient technologies and renewable energy sources to align with the UAE’s environmental goals.
- The proliferation of IoT devices and the need for low-latency services will drive the growth of edge computing, leading to the deployment of more edge data centers across the UAE.
- As data privacy regulations tighten, data center operators will invest more in advanced cybersecurity measures to protect against increasing cyber threats.
- There will be a growing demand for managed data center services, as businesses seek to outsource IT infrastructure management to focus on core operations.
- The use of AI and automation in data centers will increase, optimizing operations, improving energy efficiency, and enabling predictive maintenance.
- Continued government support through initiatives like Smart Dubai and Abu Dhabi Vision 2030 will bolster the development of digital infrastructure, including data centers.
- Colocation services will expand as more enterprises look to reduce costs and enhance flexibility by sharing data center space with other organizations.
- While Dubai and Abu Dhabi will remain the primary hubs, data center growth will extend to other emirates, driven by regional development initiatives and the broader demand for digital services across the country.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rapid Digital Transformation and Government Initiatives
The UAE government’s Vision 2030 and Smart Dubai initiatives are accelerating digital adoption across sectors, driving demand for advanced data center infrastructure to support smart cities, e-governance, and digital services.
Growing Demand for Cloud Services and Big Data Analytics
Widespread adoption of cloud computing and big data analytics by UAE enterprises, especially in finance, healthcare, and retail, is fueling the need for scalable, secure, and high-performance data centers.
Increasing Focus on Data Sovereignty and Cybersecurity
Stringent data protection laws and heightened concerns over data sovereignty are prompting organizations to store and process data locally, boosting investments in UAE-based data centers with advanced security features.
Emergence of Edge Computing and IoT
The proliferation of IoT devices and real-time applications in sectors like smart cities and autonomous vehicles is driving the deployment of edge data centers, reducing latency and supporting next-generation digital services.
Shift Towards Green and Sustainable Data Centers
Alignment with UAE Vision 2050 and rising energy costs are pushing operators to adopt energy-efficient technologies, renewable energy sources, and sustainable practices, making green data centers a key market growth area.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is driving the growth of the UAE Data Center market?
How significant is the UAE Data Center market expected to become by 2032?
Which emirates are leading in the UAE Data Center market?
What are the key trends shaping the UAE Data Center market?
Who are the major players in the UAE Data Center market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Size
- 1.2.1 Small
- 1.2.2 Mid-Sized
- 1.2.3 Large
- 1.3 By Tier
- 1.3.1 Tier 1
- 1.3.2 Tier 2
- 1.3.3 Tier 3
- 1.3.4 Tier 4
- 1.4 By Type
- 1.4.1 Enterprise
- 1.4.2 Edge
- 1.4.3 Colocation
- 1.4.4 Hyperscale
- 1.4.5 Managed
- 1.4.6 Modular
- 1.5 By Compound
- 1.5.1 Hardware
- 1.5.2 Power Systems
- 1.5.3 Cooling Systems
- 1.5.4 Racks
- 1.5.5 Servers
- 1.5.6 Networking Devices
- 1.5.7 DCIM Software
- 1.5.8 Cloud-based
- 1.5.9 On-premises
- 1.5.10 Professional Services
- 1.5.11 Integration & Implementation
- 1.5.12 Consulting
- 1.5.13 Support & Maintenance
- 1.5.14 Managed Services
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2023: USD 1,134.69 million → 2032: USD 1,975.45 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2023
- 2.6.2 Forecast Period: 2023-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2023
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 UAE Data Center Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 UAE Data Center Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2023-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2023-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 UAE Data Center Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2023-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 UAE Data Center Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 UAE Data Center Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 UAE Data Center Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 UAE Data Center Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 UAE Data Center Market Outlook, 2023-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2023: USD 1,134.69 million → 2032: USD 1,975.45 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2023
- 11.2 Market Forecast, 2023-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 UAE Data Center Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2023
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Size - Market Size and Forecast, 2023-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2023-2032
- 12.3.4 Volume Forecast, 2023-2032
- 12.3.5 Base-Year Market Share, 2023
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Small
- 12.3.7.2 Mid-Sized
- 12.3.7.3 Large
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Tier - Market Size and Forecast, 2023-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2023-2032
- 12.4.4 Volume Forecast, 2023-2032
- 12.4.5 Base-Year Market Share, 2023
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Tier 1
- 12.4.7.2 Tier 2
- 12.4.7.3 Tier 3
- 12.4.7.4 Tier 4
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Type - Market Size and Forecast, 2023-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2023-2032
- 12.5.4 Volume Forecast, 2023-2032
- 12.5.5 Base-Year Market Share, 2023
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Enterprise
- 12.5.7.2 Edge
- 12.5.7.3 Colocation
- 12.5.7.4 Hyperscale
- 12.5.7.5 Managed
- 12.5.7.6 Modular
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Compound - Market Size and Forecast, 2023-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2023-2032
- 12.6.4 Volume Forecast, 2023-2032
- 12.6.5 Base-Year Market Share, 2023
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Hardware
- 12.6.7.2 Power Systems
- 12.6.7.3 Cooling Systems
- 12.6.7.4 Racks
- 12.6.7.5 Servers
- 12.6.7.6 Networking Devices
- 12.6.7.7 DCIM Software
- 12.6.7.8 Cloud-based
- 12.6.7.9 On-premises
- 12.6.7.10 Professional Services
- 12.6.7.11 Integration & Implementation
- 12.6.7.12 Consulting
- 12.6.7.13 Support & Maintenance
- 12.6.7.14 Managed Services
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 UAE Data Center Geographic Market Outlook, 2023-2032
- 13.1 Domestic Market Distribution and Demand Clusters
- 13.2 State- or Province-Wise Market Size and Forecast, 2023-2032
- 13.3 City and Metropolitan Market Outlook
- 13.4 Industrial, Manufacturing and Commercial Clusters
- 13.5 Geographic Concentration of Key End Users
- 13.6 Local Pricing and Purchasing Differences
- 13.7 Domestic Production Facilities and Capacity Map
- 13.8 Local Infrastructure and Project Pipeline
- 13.9 State-Level Policy and Incentive Differences
- 13.10 Subnational Investment Hotspots and Opportunities
- 13.11 Distribution and Logistics Networks
- 13.12 Domestic Competitive Footprint
Chapter 14 UAE Data Center Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2023-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 UAE Data Center Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2023
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2023-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Equinix Inc.
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Etisalat
- 17.4 Khazna Data Centers
- 17.5 Gulf Data Hub
- 17.6 Injazat
- 17.7 Moro Hub (Data Hub Integrated Solutions Moro LLC)
- 17.8 datamena
- 17.9 Web Werks
- 17.10 eHosting DataFort
- 17.11 Dcvaults
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

