
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| UK Automotive Lead Acid Battery Market Size 2023 | USD 876.05 million |
| UK Automotive Lead Acid Battery Market CAGR | 8.1% |
| UK Automotive Lead Acid Battery Market Size 2032 | USD 1,768.25 million |
Market Overview
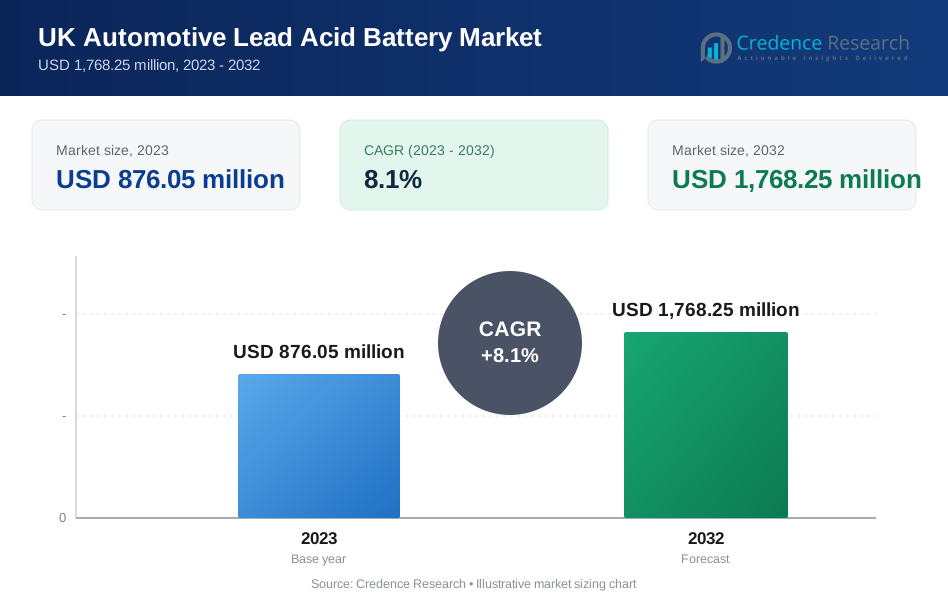
UK Automotive Lead Acid Battery market size was valued at USD 876.05 million in 2023 and is anticipated to reach USD 1,768.25 million by 2032, at a CAGR of 8.1% during the forecast period (2023-2032).
The UK Automotive Lead Acid Battery market is driven by the growing demand for vehicles, particularly electric and hybrid models, which rely heavily on advanced battery technologies. The shift towards cleaner energy solutions and the rise of hybrid and electric vehicles are boosting the need for reliable and cost-effective lead-acid batteries. Additionally, the automotive sector's focus on reducing emissions and improving fuel efficiency further supports this market. Technological advancements in battery design and manufacturing, along with the growing adoption of renewable energy storage solutions, are also fueling market growth. Increasing vehicle production and the expansion of the automotive industry, particularly in the electric vehicle segment, contribute to the rising demand for these batteries. Moreover, the market is witnessing a trend towards the development of more efficient and longer-lasting lead-acid batteries, enhancing their appeal for use in various automotive applications.
The UK Automotive Lead Acid Battery market is characterized by a strong presence of key players across various regions. Prominent companies such as C&D Technologies, Clarios, ACDelco, EnerSys, Exide Industries, and Johnson Controls dominate the market, offering a wide range of battery solutions for both commercial and passenger vehicles. These players leverage advanced manufacturing capabilities and extensive distribution networks to cater to the growing demand for reliable energy storage in automotive applications. Additionally, Halfords, Leoch International Technology, and GS Yuasa contribute to the market with their specialized products for hybrid and electric vehicles, as well as commercial fleets. The market’s geographical spread is influenced by regional automotive manufacturing hubs, particularly in areas like London, Manchester, Birmingham, and Scotland, where demand for lead-acid batteries is driven by a mix of passenger vehicles, hybrid models, and commercial transport solutions. These key players continue to innovate and strengthen their market positions through product diversification and strategic partnerships.
Market Insights
- The UK Automotive Lead Acid Battery market was valued at USD 876.05 million in 2023 and is projected to reach USD 1,768.25 million by 2032, growing at a CAGR of 8.1% during the forecast period.
- The Global Automotive Lead Acid Battery market was valued at USD 21,181.34 million in 2023 and is expected to reach USD 43,052.54 million by 2032, growing at a CAGR of 8.2% from 2023 to 2032.
- Increasing demand for hybrid vehicles is driving market growth, as lead-acid batteries are crucial for supporting start-stop systems and auxiliary power in these vehicles.
- Technological advancements, including improved battery efficiency and durability, are enhancing the performance of lead-acid batteries in automotive applications.
- Growing environmental concerns and recycling limitations present challenges to the market, urging innovations in battery disposal and recycling processes.
- Regional demand for lead-acid batteries is strongest in London, Manchester, Birmingham, and Scotland, driven by high vehicle ownership and commercial transport needs.
- Key players such as C&D Technologies, Exide Industries, and Johnson Controls are strengthening their market position through innovation and strategic partnerships.
- The increasing adoption of energy-efficient technologies in commercial and passenger vehicles is a major trend supporting market expansion.
Report Scope
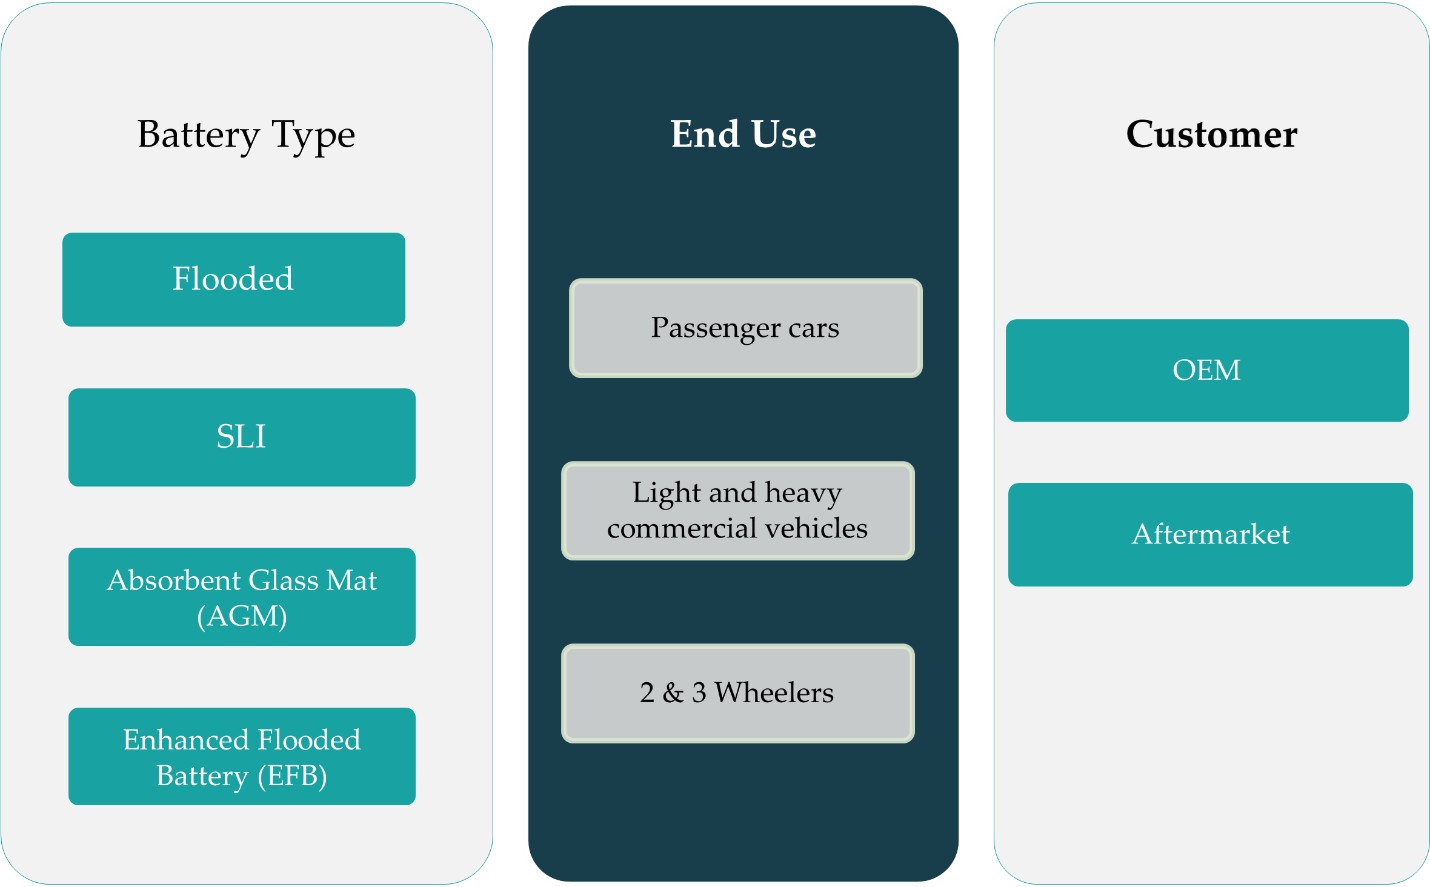
This report segments the UK Automotive Lead Acid Battery Market as follows:
Market Drivers
Increasing Demand for Electric and Hybrid Vehicles
The growing adoption of electric and hybrid vehicles in the UK is a significant driver of the Automotive Lead Acid Battery market. These vehicles require high-performance batteries to power both traditional internal combustion engine systems and electric propulsion units. For instance, the UK government has committed over £2 billion in new capital and R&D funding for the automotive sector, supporting the development of zero-emission vehicles and their batteries. While lithium-ion batteries dominate the electric vehicle (EV) market, lead-acid batteries are still widely used in hybrid vehicles due to their cost-effectiveness, availability, and reliable performance. The push towards more sustainable transportation solutions, driven by government policies aimed at reducing carbon emissions, is stimulating the need for lead-acid batteries in various automotive applications. As the UK government continues to support the shift to electric mobility, the demand for automotive batteries, including lead-acid, is expected to rise significantly in the coming years.
Technological Advancements in Battery Design
Technological innovations in battery design and manufacturing are boosting the growth of the UK Automotive Lead Acid Battery market. Advances in battery construction, such as improvements in electrolyte composition and the use of high-efficiency plates, have enhanced the performance, lifespan, and charge retention of lead-acid batteries. These improvements make lead-acid batteries more viable for use in modern vehicles, offering reliable power and cost-effective energy storage solutions. Furthermore, the development of deep-cycle lead-acid batteries with increased durability and enhanced charging capabilities is supporting the broader adoption of these batteries in the automotive sector. As automakers continue to integrate advanced technologies into their vehicle designs, lead-acid batteries are becoming more attractive for both conventional and hybrid vehicles.
Cost-Effectiveness and Accessibility
One of the key advantages of lead-acid batteries is their cost-effectiveness compared to other battery technologies, such as lithium-ion. In the context of the UK automotive industry, where cost control is crucial for both vehicle manufacturers and consumers, lead-acid batteries offer a more affordable option for powering vehicles. For instance, the UK’s battery strategy highlights the importance of scaling up the battery supply chain to improve accessibility and affordability. Despite advancements in other battery technologies, lead-acid remains an attractive choice due to its lower upfront cost, widespread availability, and well-established supply chain. The cost benefits make these batteries particularly appealing for the automotive market, especially in the production of budget-friendly vehicles and hybrid models. The established infrastructure for manufacturing and recycling lead-acid batteries also contributes to their accessibility and affordability, making them a preferred choice in a highly competitive market.
Government Regulations and Environmental Concerns
Government regulations and growing environmental concerns are driving the demand for lead-acid batteries in the UK automotive sector. The UK government has set ambitious targets for reducing carbon emissions and increasing the adoption of green technologies, including electric vehicles. Lead-acid batteries, while not as advanced as lithium-ion in terms of energy density, still play an important role in the transition to greener automotive technologies. Their ability to store energy efficiently and their recyclability contribute to their appeal in light of stringent environmental regulations. The rising demand for sustainable solutions, coupled with recycling incentives and government support for battery disposal and reuse programs, is reinforcing the role of lead-acid batteries in the automotive market. Additionally, government initiatives that promote low-cost energy storage solutions further contribute to the market's growth.
Market Trends
Shift Towards Hybrid and Electric Vehicle Integration
One of the most notable trends in the UK Automotive Lead Acid Battery market is the increasing integration of lead-acid batteries in hybrid vehicles. Although lithium-ion batteries dominate fully electric vehicles (EVs), lead-acid batteries continue to serve as an efficient power source for hybrid models. The trend towards hybridization is supported by consumer demand for fuel-efficient vehicles that offer a balance of traditional combustion engine power and electric drive capabilities. For instance, the UK’s battery strategy aims to scale up the emerging supply chain and secure investment in battery technologies. As UK automakers develop more hybrid options to meet environmental goals and government regulations, the role of lead-acid batteries in providing auxiliary power and supporting start-stop systems remains crucial. This integration trend is expected to drive steady demand for lead-acid batteries in the automotive sector for the foreseeable future.
Advancements in Battery Efficiency and Durability
Another key trend influencing the UK Automotive Lead Acid Battery market is the continuous improvement in battery efficiency and longevity. Manufacturers are focusing on enhancing the performance of lead-acid batteries through innovations such as optimized charging cycles, advanced plate designs, and better electrolyte compositions. These advancements aim to increase the lifespan, energy density, and charge retention of lead-acid batteries, making them more reliable and effective in automotive applications. As consumers demand higher-performing, longer-lasting vehicles, automotive companies are increasingly turning to these enhanced lead-acid batteries for use in vehicles. The trend toward greater battery durability is a direct response to the evolving needs of the automotive market, where performance and longevity are paramount.
Focus on Sustainable Battery Recycling
The sustainability of lead-acid batteries is a growing trend in the UK automotive industry, driven by environmental concerns and regulatory pressure. Lead-acid batteries are highly recyclable, and the automotive sector is increasingly focusing on the efficient recycling of these batteries to minimize environmental impact. Many UK-based companies are investing in technologies that allow for the recovery of lead and sulfuric acid from used batteries, which can be reused in new battery production. For instance, the UK government has introduced strict regulations on battery disposal and recycling to minimize environmental impact. This trend toward closed-loop recycling helps reduce waste, lower production costs, and decrease the environmental footprint of battery disposal. As the UK government intensifies its efforts to encourage the recycling of automotive components, lead-acid batteries’ recyclability strengthens their position as a preferred option for the industry.
Rising Demand for Energy Storage Solutions
The increasing need for energy storage solutions, driven by the growing interest in renewable energy sources, is another trend impacting the UK Automotive Lead Acid Battery market. Lead-acid batteries are widely used in energy storage systems, providing reliable backup power for households, businesses, and electric vehicles. With the UK’s commitment to expanding its renewable energy infrastructure, there is a growing demand for efficient and cost-effective storage solutions to balance energy production and consumption. Lead-acid batteries offer a proven and affordable technology to store electricity generated from renewable sources like wind and solar. This trend not only supports the automotive industry but also positions lead-acid batteries as a versatile energy storage solution across various sectors, further expanding their market presence.
Market Challenges Analysis
Competition from Advanced Battery Technologies
A significant challenge facing the UK Automotive Lead Acid Battery market is the increasing competition from advanced battery technologies, particularly lithium-ion batteries. While lead-acid batteries remain a cost-effective solution for certain applications, lithium-ion batteries offer higher energy density, longer lifespan, and faster charging capabilities, making them the preferred choice for fully electric vehicles. The growing popularity of electric vehicles (EVs) and advancements in battery technologies have led to a shift away from lead-acid batteries in favor of more efficient, lightweight alternatives. This presents a challenge for the lead-acid battery market, as automakers and consumers seek more technologically advanced solutions to meet performance and sustainability demands. As EV adoption continues to rise, the pressure on lead-acid batteries to remain relevant and competitive in the automotive sector intensifies.
Environmental Concerns and Recycling Limitations
Another challenge facing the UK Automotive Lead Acid Battery market is the growing environmental concerns regarding the production, disposal, and recycling of lead-acid batteries. Although lead-acid batteries are recyclable, the process still poses environmental risks, particularly with the handling of lead, a toxic material. For instance, the UK government has introduced regulations to manage waste lead-acid batteries containing persistent organic pollutants (POPs), ensuring proper disposal and recycling. Public and regulatory pressure to reduce environmental impact and improve battery recycling processes is mounting. While the UK automotive sector has made significant strides in battery recycling, the existing infrastructure still faces limitations in terms of capacity and efficiency. Additionally, the environmental impact of mining and processing lead for battery production remains a concern, as the demand for these materials could intensify. These environmental challenges may drive a push toward greener alternatives and innovation in recycling technology, but they also pose an ongoing challenge to the long-term sustainability of the lead-acid battery market.
Market Opportunities
The UK Automotive Lead Acid Battery market presents significant opportunities due to the growing demand for energy storage solutions in both the automotive and renewable energy sectors. As the UK transitions towards cleaner and more sustainable energy sources, lead-acid batteries remain a cost-effective option for energy storage, particularly in hybrid vehicles and backup power systems. With the increasing integration of renewable energy, such as solar and wind power, lead-acid batteries offer an affordable and reliable way to store excess energy, enabling a more stable and efficient grid. The automotive industry's shift toward hybridization further drives the need for these batteries, as they provide essential power for engine start-stop systems and auxiliary functions in electric and hybrid vehicles.
Additionally, the growing emphasis on vehicle electrification and advancements in battery technology open new avenues for lead-acid battery innovation. Although lithium-ion batteries are taking the lead in fully electric vehicles, lead-acid batteries continue to serve as a viable option for low-cost, high-volume automotive applications. The development of advanced lead-acid batteries with enhanced performance characteristics, such as longer lifespan and higher efficiency, provides manufacturers with the opportunity to meet the evolving needs of the automotive market. Furthermore, government initiatives and regulations aimed at reducing emissions and supporting green technologies create favorable conditions for the continued use of lead-acid batteries in hybrid vehicles and other energy-efficient applications. As automakers look for ways to balance performance and affordability, lead-acid batteries represent an attractive solution, creating significant growth potential for the market.
Market Segmentation Analysis:
By Battery Type:
The UK Automotive Lead Acid Battery market can be segmented by battery type into four categories: Flooded, SLI (Starting, Lighting, and Ignition), Absorbent Glass Mat (AGM), and Enhanced Flooded Batteries (EFB). Flooded batteries remain the most widely used due to their cost-effectiveness and reliability. These batteries are typically used in conventional vehicles with internal combustion engines, offering efficient performance for general automotive applications. SLI batteries, which are primarily designed for starting, lighting, and ignition systems, are common in vehicles requiring a consistent power source for engine starts and electrical systems. Absorbent Glass Mat (AGM) batteries provide enhanced power and longer lifespan, making them ideal for start-stop systems commonly found in hybrid and premium vehicles. Enhanced Flooded Batteries (EFB) are gaining traction, particularly in vehicles with start-stop technology, as they offer better charge acceptance and durability compared to traditional flooded batteries. This diverse range of battery types allows manufacturers to cater to various automotive applications, from basic vehicles to advanced hybrids and electric vehicles.
By End Use:
In terms of end-use, the UK Automotive Lead Acid Battery market is segmented into passenger cars, light and heavy commercial vehicles, and 2 & 3 wheelers. Passenger cars represent the largest share of the market, driven by the high volume of conventional and hybrid vehicles in the UK. Lead-acid batteries are integral to these vehicles, providing reliable power for starting and auxiliary functions. The light and heavy commercial vehicle segment is also a significant contributor, as these vehicles require high-performance batteries to support heavy-duty applications, including transportation and logistics. Lead-acid batteries are commonly used in these vehicles due to their affordability and long-standing reliability. The 2 & 3 wheeler segment, which includes motorcycles and scooters, is witnessing increased demand for lead-acid batteries due to their cost-effectiveness and suitability for smaller vehicles. With the rise of electric scooters and motorcycles, the market for lead-acid batteries in this segment is expected to continue growing, driven by the need for affordable energy storage solutions for two-wheeled electric vehicles.
Segments:
Based on Battery Type:
- Flooded
- SLI
- Absorbent Glass Mat
- Enhanced Flooded Battery
Based on End Use:
- Passenger cars
- Light and heavy commercial vehicles
- 2 & 3 Wheelers
Based on Customer:
- OEM
- Aftermarket
Based on the Geography:
- London
- Manchester
- Birmingham
- Scotland
Regional Analysis
London
London accounted for approximately 35% of the overall market share, driven by its high population density, substantial vehicle ownership, and rapid adoption of electric and hybrid vehicles. The capital city's automotive market benefits from its strategic location, high volume of commercial and passenger vehicles, and a growing demand for energy-efficient solutions. Government incentives aimed at reducing emissions have also encouraged the shift toward hybrid vehicles, further increasing the demand for lead-acid batteries.
Manchester
Manchester, located in the North West, holds a considerable market share, contributing roughly 25% to the overall UK market. The city's automotive market is fueled by a robust manufacturing sector and a growing number of electric and hybrid vehicles. With an expanding number of both commercial and personal vehicles, Manchester has seen a steady rise in the adoption of lead-acid batteries, particularly in commercial vehicles like light trucks and delivery vans. Additionally, the region’s proximity to key automotive manufacturing hubs and infrastructure developments boosts the demand for affordable and reliable energy storage solutions, making lead-acid batteries a preferred choice for many applications.
Birmingham
Birmingham, a central hub for automotive manufacturing and industry, captures around 20% of the market share. The region's strong industrial base, including several automotive giants and manufacturing plants, drives the demand for lead-acid batteries, particularly for commercial vehicles. The presence of numerous manufacturing facilities has led to increased demand for heavy-duty and start-stop systems, where lead-acid batteries offer a cost-effective solution. As the city continues to develop as a key automotive production center, Birmingham’s automotive market remains an important contributor to the overall UK lead-acid battery demand.
Scotland
Scotland, though a smaller market compared to the aforementioned regions, holds about 15% of the UK Automotive Lead Acid Battery market share. The automotive sector in Scotland is largely driven by its transportation needs, including both passenger cars and commercial vehicles. The demand for lead-acid batteries in Scotland is closely tied to the region’s robust logistics and transportation networks, particularly in remote and rural areas. The growing interest in hybrid vehicles, along with government support for reducing carbon emissions, is expected to boost the demand for lead-acid batteries in the coming years, especially in commercial fleets and smaller vehicles like motorcycles and scooters.
Key Player Analysis
- C&D Technologies, Inc.
- Clarios
- ACDelco
- EnerSys
- Exide Industries Ltd.
- Johnson Controls
- Halfords
- Leoch International Technology Limited
- Motive Power Batteries
- Robert Bosch LLC
- Advanced Battery Concepts
- GS Yuasa
Competitive Analysis
The UK Automotive Lead Acid Battery market features a competitive landscape dominated by several established players, including C&D Technologies, Clarios, ACDelco, EnerSys, Exide Industries Ltd., Johnson Controls, Halfords, Leoch International Technology Limited, Motive Power Batteries, Robert Bosch LLC, Advanced Battery Concepts, and GS Yuasa. These companies compete on various fronts such as product quality, technological advancements, distribution networks, and aftersales services. Most of these players focus on enhancing battery performance, lifecycle, and reliability to meet the evolving demands of modern automotive applications, particularly in hybrid and commercial vehicles. Strategic partnerships, mergers, and acquisitions are common tactics adopted by these companies to strengthen their market presence and expand their product portfolios. Innovation also plays a vital role, with firms investing in R&D to improve battery chemistry and manufacturing efficiency. Additionally, their extensive supply chains and brand recognition provide a competitive edge in capturing contracts with automotive OEMs and aftermarket suppliers, ensuring sustained growth and market penetration.
Recent Developments
- In November 2024, EnerSys showcased the iQ Mini™ battery monitoring device and maintenance-free NexSys® Thin Plate Pure Lead (TPPL) batteries, which offer longer service life and faster recharge rates.
- In July 2024, Exide Industries Ltd. introduced an advanced Absorbent Glass Mat (AGM) battery for Starting, Lighting, and Ignition (SLI) applications in the automotive market. This new battery is designed to deliver enhanced performance, including improved starting power, and potentially longer lifespan compared to traditional lead-acid batteries.
- In August 2023, Clarios, a global leader in advanced low-voltage battery manufacturing and recycling, is acquiring Paragon GmbH & Co. KGaA’s power business, which specializes in batteries and battery management systems for the automotive industry. This acquisition enhances Clarios' engineering capabilities and supports its low-voltage and lithium-ion projects, significantly expanding the team dedicated to developing new low-voltage architectures.
- In May 2023, C&D Technologies, Inc. introduced the Pure Lead Max (PLM) VRLA battery, designed for long lifespan and improved performance in UPS and data center applications.
- In April 2023, the acquisition of IBCS by EnerSys is a strategic move to expand its motive power services and strengthen its presence in the UK market. This addition will enhance EnerSys's range of battery-related services, including installation, maintenance, repair, and replacement
Market Concentration & Characteristics
The UK Automotive Lead Acid Battery market exhibits a moderate to high level of market concentration, characterized by the dominance of a few well-established players with strong brand recognition and expansive distribution networks. Companies such as Clarios, Exide Industries, EnerSys, and Johnson Controls command a significant share of the market due to their long-standing industry presence, technological expertise, and extensive product portfolios. The market is also defined by stable demand across both OEM and aftermarket segments, driven by the consistent need for reliable and cost-effective power solutions in passenger cars, commercial vehicles, and hybrid models. Lead-acid batteries continue to be favored for their affordability, recyclability, and proven performance, particularly in start-stop systems. While entry barriers for new players are moderately high due to capital requirements and regulatory standards, ongoing innovation in battery technology and sustainability initiatives offer potential opportunities. The market’s structure reflects a blend of mature operations and evolving product innovations.
Report Coverage
The research report offers an in-depth analysis based on Battery Type, End Use, Customer and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The UK automotive lead acid battery market is expected to see steady demand due to the widespread use of conventional vehicles.
- Increasing vehicle parc in the country will continue to drive replacement battery sales.
- The shift toward electric vehicles may reduce demand for SLI batteries but not eliminate it entirely.
- Lead acid batteries will remain crucial in supporting auxiliary functions in hybrid and electric vehicles.
- Advancements in battery recycling processes will strengthen the sustainability of lead acid technology.
- The aftermarket segment is likely to maintain dominance due to ongoing maintenance needs of older vehicles.
- Demand from commercial and heavy-duty vehicles will provide stability to market growth.
- Regulatory support for recycling and responsible battery disposal will encourage domestic production.
- Technological enhancements in battery life and charge retention will improve competitiveness.
- Collaboration between manufacturers and recycling firms is expected to enhance supply chain efficiency.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the UK Automotive Lead Acid Battery?
What factors are driving the growth of the UK Automotive Lead Acid Battery?
What are some challenges faced by the UK Automotive Lead Acid Battery?
Who are the major players in the UK Automotive Lead Acid Battery?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 UK Automotive Lead Acid Battery Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2023; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global UK Automotive Lead Acid Battery Market Snapshot
- 2.1.1 Market Size – Historical (2023) & Forecast (2023-2032) (2023: USD 876.05 million → 2032: USD 1,768.25 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 UK Automotive Lead Acid Battery Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2023 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2023
- 2.3.2 Top 10 Players by Volume Share – 2023
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. UK Automotive Lead Acid Battery Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 UK Automotive Lead Acid Battery Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 UK Automotive Lead Acid Battery Market Drivers
- 3.3 UK Automotive Lead Acid Battery Market Restraints & Challenges
- 3.4 UK Automotive Lead Acid Battery Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 UK Automotive Lead Acid Battery Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 UK Automotive Lead Acid Battery Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, UK Automotive Lead Acid Battery category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 UK Automotive Lead Acid Battery Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. UK Automotive Lead Acid Battery Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2023)
- 5.1.2 Global Export Volume by Country (2023)
- 5.1.3 Global Import Value by Country (2023)
- 5.1.4 Global Import Volume by Country (2023)
- 5.1.5 Net Trade Balance by Country (2023)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2023)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the UK Automotive Lead Acid Battery market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 UK Automotive Lead Acid Battery Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2023
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 UK Automotive Lead Acid Battery Market Share Analysis – 2023
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2023)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 UK Automotive Lead Acid Battery Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in UK Automotive Lead Acid Battery (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New UK Automotive Lead Acid Battery Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global UK Automotive Lead Acid Battery Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2023 & 2032)
- 7.1.2 Channel Mix Evolution (2023-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America UK Automotive Lead Acid Battery Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe UK Automotive Lead Acid Battery Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific UK Automotive Lead Acid Battery Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America UK Automotive Lead Acid Battery Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East UK Automotive Lead Acid Battery Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa UK Automotive Lead Acid Battery Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. UK Automotive Lead Acid Battery Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
