
Market Overview:
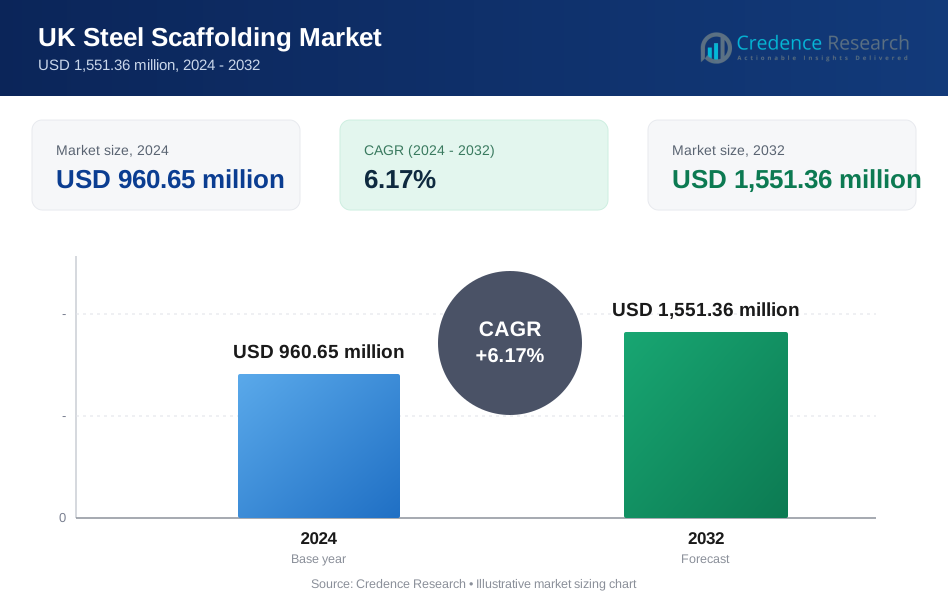
UK steel scaffolding market size was valued at USD 909.79 million in 2018 and grew to USD 960.65 million in 2024. It is anticipated to reach USD 1,551.36 million by 2032, expanding at a CAGR of 6.17% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| UK Steel Scaffolding Market Size 2024 | USD 960.65 million |
| UK Steel Scaffolding Market, CAGR | 6.17% |
| UK Steel Scaffolding Market Size 2032 | USD 1,551.36 million |
The UK steel scaffolding market is led by major players such as Altrad UK, Kaefer Ltd, Lyndon SGB, TRAD Group, Enigma Industrial, Layher Ltd (UK), and RMD Kwikform, which collectively dominate supply, rental, and turnkey project services. These companies focus on modular scaffolding solutions, digital design integration, and strict compliance with safety regulations to support construction, infrastructure, and industrial projects. England accounts for over 65% of the market share, driven by high construction and refurbishment activity, followed by Scotland with around 15%, and Wales and Northern Ireland contributing approximately 10% each. This concentration makes England the key revenue hub.

Market Insights
- The UK steel scaffolding market was valued at USD 960.65 million in 2024 and is projected to reach USD 1,551.36 million by 2032, expanding at a CAGR of 6.17% during the forecast period.
- Rising construction and infrastructure projects, including HS2 rail and major housing developments, are driving demand for supported and modular scaffolding systems across the country.
- Trends include rapid adoption of modular scaffolding, BIM-integrated planning tools, and a focus on reusable, sustainable components to meet regulatory and environmental targets.
- Key players such as Altrad UK, Kaefer Ltd, Lyndon SGB, TRAD Group, and Layher Ltd (UK) dominate the market through rental services, safety-focused product innovations, and long-term contractor agreements.
- England leads with over 65% market share, followed by Scotland at 15%, while Wales and Northern Ireland contribute 10% each; supported scaffolding remains the dominant type, holding the largest share among system categories.
Market Segmentation Analysis:
By Type
Supported scaffolding dominated the UK steel scaffolding market in 2024, holding over 40% share due to its widespread use in residential and commercial construction projects. Its stability, ease of assembly, and ability to handle heavy loads make it the preferred choice for high-rise buildings and infrastructure works. System/modular scaffolding is rapidly growing as contractors adopt standardized, reusable components to reduce setup time and improve safety compliance. Rolling scaffolding sees strong demand for quick maintenance tasks, while cantilever and suspended systems serve specialized projects such as bridge repairs and façade restoration.
- For instance, BrandSafway supplied over 70,000 m² of supported scaffolding for the Battersea Power Station redevelopment, allowing safe multi-level access during structural restoration.
By Location
External access scaffolding accounted for the largest share, exceeding 45% in 2024, driven by large-scale building renovations and infrastructure maintenance across the UK. Heavy-duty load-bearing systems are witnessing growth as transport and energy projects demand robust platforms for heavy equipment support. Internal access scaffolding remains essential for fit-out works in commercial spaces and industrial plants. Formwork and falsework support solutions are increasingly integrated with digital design tools, enhancing precision in concrete construction projects. Facade scaffolding remains a key choice for heritage building refurbishment where safety and minimal disruption are critical.
- For instance, PHD Access erected 25,000 m² of external scaffolding for the £80 million Savoy Hotel restoration, ensuring safe façade works with minimal public disruption.
By End-use Industry
Construction led the UK market with more than 50% share in 2024, supported by government housing initiatives and commercial real estate expansion. Infrastructure projects such as HS2 rail, bridge upgrades, and airport expansions further boost demand for large scaffolding setups. The industrial segment, including oil & gas and manufacturing plants, uses scaffolding extensively for turnaround maintenance and shutdown operations. Energy and power sectors rely on scaffolding for turbine, boiler, and solar farm maintenance, while shipbuilding and marine applications require corrosion-resistant systems for dockside repairs and vessel overhauls, sustaining steady demand in coastal regions.
Market Overview
Rising Construction and Infrastructure Projects
Government-led housing programs and infrastructure investments are major demand drivers for steel scaffolding in the UK. Projects like HS2 rail development, bridge upgrades, and airport expansion require large, stable scaffolding systems for extended timelines. Residential construction growth and refurbishment activities in London and regional cities add further volume, supporting consistent procurement of modular and supported scaffolding systems. The focus on improving urban infrastructure and meeting housing targets strengthens demand across both private and public sector projects, ensuring long-term market momentum.
- For instance, Layher's modular scaffolding was used by subcontractors on High Speed 2 (HS2) rail works to facilitate safe operations across multiple sites. The modular system's design enabled faster and more efficient erection compared to traditional scaffolding methods.
Adoption of Modular and Digital Scaffolding Solutions
UK contractors are increasingly shifting toward modular scaffolding systems, which offer faster assembly and compliance with strict health and safety regulations. Digital tools such as BIM integration and 3D scaffold design software improve project planning and reduce errors, lowering overall project costs. The demand for reusable, standardized components supports sustainability targets and cuts waste generation. This trend is accelerating adoption among major construction companies, enabling shorter project cycles and driving steady market expansion for advanced system scaffolding.
- For instance, in 2016, a project team at Sellafield, working with scaffolding provider Kaefer (which was later acquired by Altrad), introduced an "innovative rolling scaffolding" system to speed up decommissioning and save money.
Growth in Maintenance and Industrial Shutdown Activities
Regular maintenance of power plants, petrochemical sites, and manufacturing units is fueling demand for scaffolding solutions. Scheduled shutdowns in oil & gas and cement plants require quick-install platforms to minimize downtime. Marine and shipyard operations also contribute to demand, with scaffolding used for dockside maintenance and vessel repair. These recurring service requirements create a steady revenue stream for scaffolding rental companies and suppliers, balancing demand even during periods of slower new construction activity across the UK market.

Key Trends & Opportunities
Focus on Safety and Regulatory Compliance
Stringent safety regulations, including Work at Height Regulations 2005, are pushing scaffolding providers to enhance system safety. This includes the use of guardrails, fall arrest systems, and advanced locking mechanisms in modular scaffolding. Continuous training and certification requirements for scaffolders are raising industry standards and increasing demand for compliant, tested systems. This focus presents an opportunity for manufacturers to introduce safer, high-strength scaffolding solutions that exceed compliance norms and win preference in large-scale projects.
- For instance, Layher introduced its Allround Lightweight system with AutoLock function, which locks ledgers automatically and meets BS EN 12811 standards, reducing assembly errors on-site.
Sustainability and Lightweight Materials
UK construction stakeholders are prioritizing environmentally friendly scaffolding solutions to align with carbon reduction targets. Lightweight, reusable steel and hybrid scaffolding systems are gaining traction as they cut transport costs and reduce project emissions. Circular economy initiatives encourage refurbishment and reuse of scaffolding components, lowering lifecycle costs. This shift toward sustainable practices is creating opportunities for suppliers offering eco-certified systems and digital asset tracking for efficient inventory and reuse management.
Key Challenges
Skilled Labor Shortages
A shortage of trained scaffolders and certified inspectors is a major challenge for the UK market. With complex infrastructure projects underway, demand for qualified workers often exceeds supply, causing project delays and higher labor costs. Training programs are being scaled up, but the time required to build competency can slow adoption of advanced modular systems. Labor constraints may force contractors to rely on rental partners with skilled crews, impacting overall market margins and timelines.
Fluctuating Steel Prices and Supply Chain Volatility
Volatility in steel prices directly affects scaffolding manufacturing costs, impacting profitability for suppliers. Global supply chain disruptions, including shipping delays and raw material shortages, can create cost spikes and extend lead times. These uncertainties pose challenges for contractors working on fixed-price contracts, as budgeting for scaffolding procurement becomes difficult. Companies are increasingly exploring long-term supply agreements and local sourcing strategies to mitigate risk, but exposure to market price swings remains a key restraint.
Regional Analysis
England
England held the dominant share of over 65% of the UK steel scaffolding market in 2024, driven by large-scale residential and commercial construction projects. Major infrastructure programs such as HS2 rail, Crossrail expansions, and urban regeneration initiatives across London, Birmingham, and Manchester continue to boost demand. High refurbishment activity in heritage buildings and commercial real estate further fuels supported and modular scaffolding adoption. The concentration of top construction contractors and rental companies in England ensures consistent consumption, making it the key revenue generator for scaffolding manufacturers and service providers.
Scotland
Scotland accounted for around 15% of the UK market share in 2024, supported by infrastructure upgrades, renewable energy projects, and housing developments. Significant demand comes from wind farm construction in the Highlands and offshore energy projects along the North Sea coast. Major cities like Glasgow and Edinburgh are witnessing strong demand for scaffolding in commercial property renovations and transport projects. The government’s focus on net-zero targets and sustainable building practices is also encouraging the use of modular and reusable scaffolding systems, positioning Scotland as a fast-growing regional market.
Wales
Wales represented approximately 10% of the UK scaffolding market share in 2024, with steady demand from housing development programs and infrastructure upgrades. Key projects include road expansion schemes and maintenance work in power plants and industrial sites in South Wales. The focus on public housing refurbishment and school renovation projects is boosting the use of lightweight and easy-to-install scaffolding systems. Wales benefits from its manufacturing base and proximity to suppliers in England, supporting cost-effective procurement and ensuring timely availability for ongoing and upcoming projects.
Northern Ireland
Northern Ireland contributed nearly 10% of the UK steel scaffolding market share in 2024, with demand driven by commercial real estate projects, road network development, and harbor upgrades. Belfast and Derry lead construction activity, requiring supported scaffolding and modular systems for high-rise and mixed-use developments. Infrastructure maintenance and public-sector renovation contracts provide recurring opportunities for scaffolding rental companies. Increased investment in logistics and industrial parks is also supporting market growth, while suppliers focus on quick delivery and compliance with UK and EU safety standards to meet project timelines efficiently.

Market Segmentations:
By Type
- Supported Scaffolding
- Suspended Scaffolding
- Rolling/Mobile Scaffolding
- Cantilever Scaffolding
- System/Modular Scaffolding
By Location
- External Access Scaffolding
- Internal Access Scaffolding
- Formwork / Falsework Support
- Facade / Maintenance Scaffolding
- Heavy-Duty Load-Bearing Systems
By End-use Industry
- Construction
- Industrial (Oil & Gas, Petrochemical, Manufacturing, Cement)
- Infrastructure (Railways, Bridges, Roads, Airports)
- Energy & Power (Thermal, Hydro, Renewable Plant Maintenance)
- Shipbuilding and Marine
By Deployment
- New Installation
- Maintenance / Repair / Overhaul (MRO)
- Retrofit / Expansion Projects
By Business Model
- Rental-Based Scaffolding
- Purchase / Owned Scaffolding
By Geography
- England
- Scotland
- Wales
- Northern Ireland
Competitive Landscape
The UK steel scaffolding market is moderately consolidated, with key players such as Altrad UK, Kaefer Ltd, Lyndon SGB, TRAD Group, Enigma Industrial, and Layher Ltd (UK) leading the competitive landscape. These companies dominate supply, rental, and project management services across construction, infrastructure, and industrial sectors. Their strategies focus on expanding modular scaffolding offerings, improving safety compliance, and adopting digital design solutions like BIM to optimize project planning. Strategic partnerships, acquisitions, and long-term framework agreements with major contractors enhance their market share. Competition is driven by service reliability, safety standards, and the ability to handle large-scale projects. Continuous investment in reusable systems, training programs, and sustainability initiatives is expected to remain a key differentiator, ensuring players stay competitive in a market with rising safety and compliance requirements.
Key Player Analysis
- Altrad UK
- Kaefer Ltd
- Lyndon SGB
- TRAD Group
- Enigma Industrial
- Alltask
- Brogan Group
- GKR Scaffolding
- Palmers Scaffolding
- Layher Ltd (UK)
- RMD Kwikform
- Scafom-rux
- Steeledge UK
- United Scaffolding
Recent Developments
- In April 2025, Layher unveiled its new corporate identity and cutting-edge scaffolding innovations at Bauma 2025 in Munich. Highlights included advanced digital planning tools (Layher SIM2Field®), lightweight bridging systems, and new modular components for versatile applications. The company emphasized digitalization, safety, and sustainability as part of their redesign, and introduced products like the Xtra-Slim steel plank for tight spaces and the O-version FlexBeam compatible with weather protection roofs.
- In April 2025, PERI showcased digital, sustainable scaffolding solutions and smart construction tools at Bauma 2025. The innovations included modular, safety-focused systems and new digital management tools, emphasizing eco-friendly materials and productivity gains for residential and infrastructure projects.
- In February 2025, the Altrad Group finalized the acquisition of Stork's UK business and Heras' UK mobile fencing operations, significantly expanding its services in temporary fencing, hoarding, and scaffolding in the United Kingdom and Europe.
Report Coverage
The research report offers an in-depth analysis based on Type, Location, End-use Industry, Deployment, Business Model and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The UK steel scaffolding market will grow steadily driven by ongoing infrastructure projects and urban redevelopment.
- Adoption of modular and system scaffolding will accelerate due to faster installation and improved safety compliance.
- Digital technologies like BIM and 3D modeling will streamline planning and reduce project errors.
- Demand from industrial shutdowns and maintenance activities will ensure a recurring revenue stream for rental providers.
- Sustainability initiatives will push for reusable and eco-friendly scaffolding components.
- Skilled labor development will remain a focus to meet rising demand for certified scaffolders.
- Market competition will intensify with companies investing in training and advanced equipment.
- Public sector investments in railways, bridges, and housing will continue to support high demand.
- Safety regulations will tighten, encouraging innovation in guardrail systems and fall protection features.
- Regional demand will stay concentrated in England, supported by major urban construction and refurbishment projects.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for UK Steel Scaffolding market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the UK Steel Scaffolding market projected to grow between 2025 and 2032?
Which UK Steel Scaffolding market segment held the largest share in 2024?
What are the primary factors fueling the growth of the UK Steel Scaffolding market?
Who are the leading companies in the UK Steel Scaffolding market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 UK Steel Scaffolding Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global UK Steel Scaffolding Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 960.65 million → 2032: USD 1,551.36 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 UK Steel Scaffolding Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. UK Steel Scaffolding Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 UK Steel Scaffolding Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 UK Steel Scaffolding Market Drivers
- 3.3 UK Steel Scaffolding Market Restraints & Challenges
- 3.4 UK Steel Scaffolding Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 UK Steel Scaffolding Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 UK Steel Scaffolding Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, UK Steel Scaffolding category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 UK Steel Scaffolding Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. UK Steel Scaffolding Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the UK Steel Scaffolding market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 UK Steel Scaffolding Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 UK Steel Scaffolding Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 UK Steel Scaffolding Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in UK Steel Scaffolding (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New UK Steel Scaffolding Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global UK Steel Scaffolding Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America UK Steel Scaffolding Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe UK Steel Scaffolding Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific UK Steel Scaffolding Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America UK Steel Scaffolding Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East UK Steel Scaffolding Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa UK Steel Scaffolding Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. UK Steel Scaffolding Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
