
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| UK Underground Mining Equipment Market Size 2023 | USD 1,005.46 million |
| UK Underground Mining Equipment Market, CAGR | 4.37% |
| UK Underground Mining Equipment Market Size 2032 | USD 1,478.46 million |
Market Overview
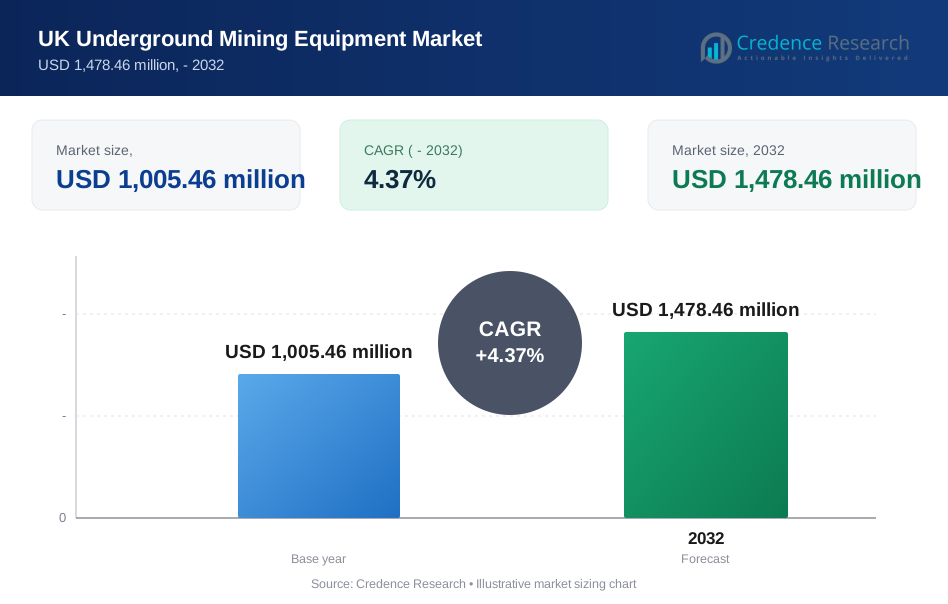
The UK Underground Mining Equipment Market is projected to grow from USD 1,005.46 million in 2023 to USD 1,478.46 million by 2032, reflecting a compound annual growth rate (CAGR) of 4.37% from 2024 to 2032. This growth is driven by the increasing demand for mineral resources and the expansion of underground mining activities, especially in metals and coal mining. Technological advancements in equipment design and automation further bolster the market, offering enhanced safety, efficiency, and productivity for mining operations.
The market is primarily fueled by the growing emphasis on resource extraction to meet industrial demands and support economic development. Trends such as automation, the adoption of electric and battery-operated mining equipment, and enhanced environmental regulations are transforming the industry. Additionally, investments in advanced technologies like remote monitoring systems and AI-driven solutions are reshaping operational strategies and ensuring compliance with stricter safety and sustainability standards.
Geographically, mining activities in regions such as Yorkshire, the Midlands, and South Wales play a significant role in driving demand for underground mining equipment. The market features key players such as Caterpillar Inc., Komatsu Ltd., Sandvik AB, and Epiroc AB, which lead through innovation and strategic partnerships. These companies are increasingly focused on offering customized solutions tailored to the UK's unique mining landscape, ensuring robust competition and sustained market growth.
Market Drivers
Rising Demand for Mineral Resources
The growing need for mineral resources, including coal, iron, and rare earth elements, significantly drives the UK underground mining equipment market. For instance, industrial sectors such as construction and energy transition increasingly rely on materials like coal, iron, and rare earth elements. This trend has prompted mining companies to enhance their operations, particularly in underground mining, which allows access to deeper mineral deposits while minimizing surface disruption. The increasing interest in renewable energy technologies, such as wind turbines and electric vehicles (EVs), has further elevated the demand for materials like copper, cobalt, and lithium, which often require underground extraction methods. As a result, mining companies are intensifying their operations to meet this rising demand, leading to heightened interest in advanced equipment that ensures operational efficiency, safety, and cost-effectiveness.
Technological Advancements in Mining Equipment
Innovations in mining technology have played a pivotal role in boosting market growth. Companies are increasingly adopting automation, artificial intelligence (AI), and Internet of Things (IoT) technologies to optimize underground operations. For instance, the integration of automation and AI is transforming the industry by enhancing productivity and improving worker safety in hazardous environments. Innovations such as automated drills, remote-controlled machinery, and predictive maintenance systems are reducing operational downtime and costs. Additionally, the development of battery-powered and electric mining equipment is driving market demand further, as these technologies align with the UK's stringent emission regulations and sustainability goals.
Government Regulations and Sustainability Initiatives
Stringent government regulations regarding environmental sustainability and worker safety are shaping the market. Policies aimed at reducing greenhouse gas emissions have encouraged the adoption of cleaner, energy-efficient mining equipment. The UK's commitment to achieving net-zero carbon emissions by 2050 is motivating mining operators to invest in eco-friendly technologies, including electric and hybrid mining vehicles. For example, regulatory frameworks emphasize worker safety by mandating advanced equipment that reduces exposure to hazardous conditions. These policies have incentivized manufacturers to develop machinery with enhanced safety features, such as collision-avoidance systems and ventilation monitoring. Such compliance-driven innovation not only ensures adherence to regulations but also fosters market growth by promoting safer and more sustainable mining practices.
Increased Focus on Operational Efficiency and Cost Optimization
Mining companies in the UK are prioritizing operational efficiency and cost management in response to fluctuating commodity prices and growing competition. Advanced underground mining equipment offers solutions to reduce labor-intensive processes, streamline operations, and maximize resource recovery. Technologies such as real-time data analytics and automated drilling systems enable operators to make informed decisions, minimize wastage, and lower overall costs. Furthermore, manufacturers are providing tailored equipment solutions to address specific mining challenges in the UK, such as narrow vein mining and deep underground operations. This customization enhances productivity, making it an attractive investment for mining firms seeking to improve profitability.
Market Trends
Adoption of Automation and Digital Technologies
Automation and digitalization are transforming the UK underground mining equipment market. Mining companies are increasingly integrating advanced technologies such as Artificial Intelligence (AI), Internet of Things (IoT), and data analytics to enhance efficiency and safety. For instance, automated equipment, including remote-controlled loaders and drilling systems, allows for more precise and less labor-intensive operations, particularly in challenging underground environments. Moreover, digital monitoring systems provide real-time insights into equipment performance, enabling predictive maintenance that significantly reduces operational downtime. The implementation of IoT-enabled sensors is also becoming common, allowing for the tracking of critical parameters such as ventilation, temperature, and structural stability. This ensures compliance with safety standards and reduces risks to workers. This shift toward intelligent, connected systems reflects the industry’s commitment to improving operational efficiency while meeting stringent safety and environmental regulations.
Growing Shift Toward Electrification and Sustainability
The trend toward electrification and sustainable practices is a significant driver in the UK underground mining equipment market. For instance, as part of their commitment to achieving net-zero carbon emissions, mining companies in the UK are transitioning from traditional diesel-powered equipment to battery-operated and electric machinery. This shift reduces greenhouse gas emissions and enhances air quality in underground mining sites, creating safer working environments. The demand for electric vehicles (EVs) and hybrid mining equipment is on the rise due to their lower operational costs and alignment with environmental policies. Furthermore, manufacturers are focusing on designing energy-efficient equipment that optimizes resource use while minimizing waste. Innovations such as regenerative braking systems and modular battery solutions are enabling more sustainable operations while maintaining high performance. These advancements underscore the market’s movement toward environmentally responsible mining practices, positioning the UK as a leader in sustainable underground mining technologies.
Market Restraints and Challenges
High Initial Investment and Operating Costs
One of the primary restraints in the UK underground mining equipment market is the significant capital investment required for procuring advanced machinery. Cutting-edge technologies such as automated drills, electric mining vehicles, and IoT-enabled equipment come at a high cost, which can be a barrier for small and medium-sized mining companies. Additionally, operating costs, including maintenance, spare parts, and energy consumption, can strain budgets, particularly during periods of fluctuating commodity prices. These financial challenges are further exacerbated by the specialized training required for operators to handle modern equipment, which adds to operational expenses. While advanced machinery offers long-term benefits in terms of efficiency and safety, the substantial upfront costs can delay adoption and hinder market growth, particularly for companies operating on tight margins.
Regulatory Compliance and Environmental Constraints
The UK's stringent environmental and safety regulations present another challenge for the underground mining equipment market. Compliance with policies aimed at reducing greenhouse gas emissions and minimizing environmental impact often requires significant modifications to existing equipment or the adoption of new, eco-friendly technologies. These transitions can be costly and time-consuming, particularly for companies with limited resources. Furthermore, environmental activism and public opposition to mining activities in certain regions have created additional hurdles for market expansion. The need to balance profitability with sustainability and community engagement often slows down project approvals and the deployment of new technologies. Navigating these regulatory and social challenges requires substantial investment in research and development, which can strain resources for smaller players in the market.
Market Segmentation Analysis
By Product Type
The UK Underground Equipment Market is segmented by product type, with key categories including mining loaders, mining trucks, mining drills, mining bolters, and mining shearers. Mining loaders, essential for material transport in underground operations, are in high demand due to their enhanced maneuverability and productivity, with advanced automated models gaining traction. Mining trucks, designed for harsh underground conditions, are critical for material transport through narrow pathways, with growing demand for electric and hybrid models driven by stricter environmental regulations. Mining drills play a vital role in both mining and tunneling, offering precise and efficient drilling solutions, with automation and monitoring capabilities further boosting demand. Mining bolters, used for supporting mine roofs and enhancing safety, are increasingly sought after due to stricter safety standards and a focus on worker protection. Additionally, mining shearers, primarily used in soft rock mining for continuous cutting, are seeing a rise in demand, fueled by automation and advanced cutting technologies that improve productivity in high-output mining operations.
By Mining Technique
The UK Underground Equipment Market is divided into two primary mining techniques: soft rock mining and hard rock mining. Soft rock mining, which focuses on the extraction of materials like coal, salt, and other softer minerals, drives demand for specialized equipment designed for efficient material handling in mining and energy production. In contrast, hard rock mining, involving the extraction of more durable minerals such as gold, copper, and other metals, requires high-precision, durable machinery capable of withstanding harsh conditions while maximizing productivity. Both segments remain integral to the market, with strong demand for advanced, reliable equipment in response to ongoing mining projects and resource extraction needs.
Segments
Based on Product Type
- Mining Loaders
- Mining Trucks
- Mining Drills
- Mining Bolters
- Mining Shearer
Based on Mining Technique
- Soft Rock Mining
- Hard Rock Mining
Based on End User
- Mining Operators
- Rental Service Providers
Based on Region
- London and Metropolitan Areas
- Northern England
- Scotland
- Other Regions
Regional Analysis
Yorkshire and the Humber (35%):
Yorkshire and the Humber hold the largest share of the UK underground mining equipment market, accounting for approximately 35% of the total market. This dominance is attributed to the region's rich reserves of coal and other mineral resources, coupled with established mining infrastructure. The area's historical reliance on mining as a key economic activity has driven the adoption of advanced underground mining technologies. Additionally, ongoing investments in automation and energy-efficient machinery ensure that the region remains a major contributor to market growth.
Wales (25%):
Wales represents about 25% of the market, owing to its significant coal mining history and the presence of deep underground mines. The Welsh mining sector is focused on modernizing operations to comply with stringent environmental regulations and improve safety standards. This has led to a growing demand for electric and battery-powered mining equipment in the region, aligning with the UK’s sustainability goals. The market in Wales is also supported by government initiatives aimed at revitalizing mining communities and ensuring environmental stewardship.
Key players
- Caterpillar Inc.
- Terex Corporation
- SANY Group
- CNH Industrial
- AB Volvo
- Hitachi Co. Ltd.
- Atlas Copco AB
- Komatsu Ltd.
- Hyundai Heavy Industries Company Limited
- Joy Global Inc.
- Metso Corporation
- Sandvik AB
- Thyssenkrupp AG
Competitive Analysis
The UK underground mining equipment market is characterized by intense competition among global and regional players, with key companies leveraging innovation, product diversification, and strategic partnerships to maintain their market positions. Caterpillar Inc. and Komatsu Ltd. lead the market with their robust portfolios of automated and electric mining solutions, catering to the growing demand for sustainability and efficiency. Sandvik AB and Atlas Copco AB excel in offering advanced drilling and cutting-edge automation technologies, enabling operators to enhance productivity and safety. SANY Group and Hyundai Heavy Industries Company Limited focus on cost-effective equipment tailored for smaller mining operations. AB Volvo and CNH Industrial emphasize eco-friendly solutions, aligning with the UK's stringent environmental regulations. Meanwhile, Thyssenkrupp AG, Metso Corporation, and Hitachi Co. Ltd. are recognized for their material handling and processing equipment. Companies like Terex Corporation and Joy Global Inc. maintain competitiveness through innovative mining machinery and aftersales services. These players collectively drive market innovation and growth.
Recent Developments
- In December 2023, Caterpillar Inc., made a historic underground equipment delivery to Anglo Asian Mining, including three 15-t-payload R1700 underground loaders and two 980UMA wheel loaders,.
- In July 2024, Komatsu Ltd., completed acquisition of GHH Group GmbH, a manufacturer of underground mining and tunneling equipment, expanding their underground mining offerings.
- In October 2023, Metso Corporation acquired Tedd Engineering in UK, specializing in automation and control systems for mobile equipment, for approximately GBP 15 million.
Market Concentration and Characteristics
The UK underground mining equipment market exhibits a moderate-to-high market concentration, with a few global players dominating the industry alongside several regional and niche competitors. Key players like Caterpillar Inc., Komatsu Ltd., Sandvik AB, and Atlas Copco AB hold significant market shares due to their extensive product portfolios, technological advancements, and strong distribution networks. The market is characterized by a focus on innovation, with companies investing heavily in automation, electrification, and sustainability to address environmental regulations and operational efficiency. Despite the dominance of major players, smaller manufacturers and regional firms compete by offering customized solutions tailored to the unique demands of UK mining operations. Collaboration with mining companies for tailored machinery and a shift toward eco-friendly and cost-efficient equipment are defining characteristics of the market. Additionally, long-term service agreements and aftersales support are crucial factors influencing customer loyalty and market dynamics.
Report Coverage
The research report offers an in-depth analysis based on Product Type, Mining Technique, End User, and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The UK underground mining equipment market is expected to continue growing, driven by increasing demand for mineral resources and the adoption of advanced mining technologies.
- The transition from diesel-powered machinery to electric and battery-operated equipment will accelerate, aligning with the UK's sustainability goals and carbon neutrality targets.
- Automation will become a cornerstone of underground mining operations, with technologies like AI and IoT enabling enhanced safety, productivity, and cost management.
- Mining companies will increasingly use real-time data analytics and digital monitoring systems to optimize operations, reduce downtime, and improve decision-making processes.
- The focus on sustainable practices will lead to the development of eco-friendly equipment and the implementation of recycling and waste management technologies.
- Equipment manufacturers will offer more tailored solutions to address specific challenges such as narrow vein mining and deep underground operations.
- Stringent safety and environmental regulations will push companies to adopt advanced equipment that meets or exceeds compliance standards.
- Mining firms will prioritize cost-effective solutions, driving demand for machinery that offers higher efficiency and longer lifespans with lower maintenance costs.
- Strategic alliances between equipment manufacturers, mining companies, and technology providers will strengthen to accelerate innovation and market competitiveness.
- Smaller, regional players will gain traction by offering niche solutions and leveraging local expertise, adding diversity to the competitive landscape.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the market size of the UK Underground Mining Equipment Market in 2023 and 2032, and what is its CAGR?
What factors are driving the growth of the UK Underground Mining Equipment Market?
Which regions in the UK contribute most to the underground mining equipment market?
How are environmental regulations impacting the market?
Who are the major players in the UK Underground Mining Equipment Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 UK Underground Mining Equipment Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (the historical period; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global UK Underground Mining Equipment Market Snapshot
- 2.1.1 Market Size – Historical (the historical period) & Forecast (2032) (base year: USD 1,005.46 million → 2032: USD 1,478.46 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 UK Underground Mining Equipment Market Segmentation Snapshot
- 2.2.1 Market Split by Region – vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share –
- 2.3.2 Top 10 Players by Volume Share –
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. UK Underground Mining Equipment Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 UK Underground Mining Equipment Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 UK Underground Mining Equipment Market Drivers
- 3.3 UK Underground Mining Equipment Market Restraints & Challenges
- 3.4 UK Underground Mining Equipment Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 UK Underground Mining Equipment Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 UK Underground Mining Equipment Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, UK Underground Mining Equipment category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 UK Underground Mining Equipment Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. UK Underground Mining Equipment Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (the historical period)
- 5.1.2 Global Export Volume by Country (the historical period)
- 5.1.3 Global Import Value by Country (the historical period)
- 5.1.4 Global Import Volume by Country (the historical period)
- 5.1.5 Net Trade Balance by Country (the historical period)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (the historical period)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the UK Underground Mining Equipment market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 UK Underground Mining Equipment Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs.
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 UK Underground Mining Equipment Market Share Analysis –
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. )
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 UK Underground Mining Equipment Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in UK Underground Mining Equipment (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New UK Underground Mining Equipment Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global UK Underground Mining Equipment Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel ( & 2032)
- 7.1.2 Channel Mix Evolution (2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America UK Underground Mining Equipment Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe UK Underground Mining Equipment Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific UK Underground Mining Equipment Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America UK Underground Mining Equipment Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East UK Underground Mining Equipment Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa UK Underground Mining Equipment Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. UK Underground Mining Equipment Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
