
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
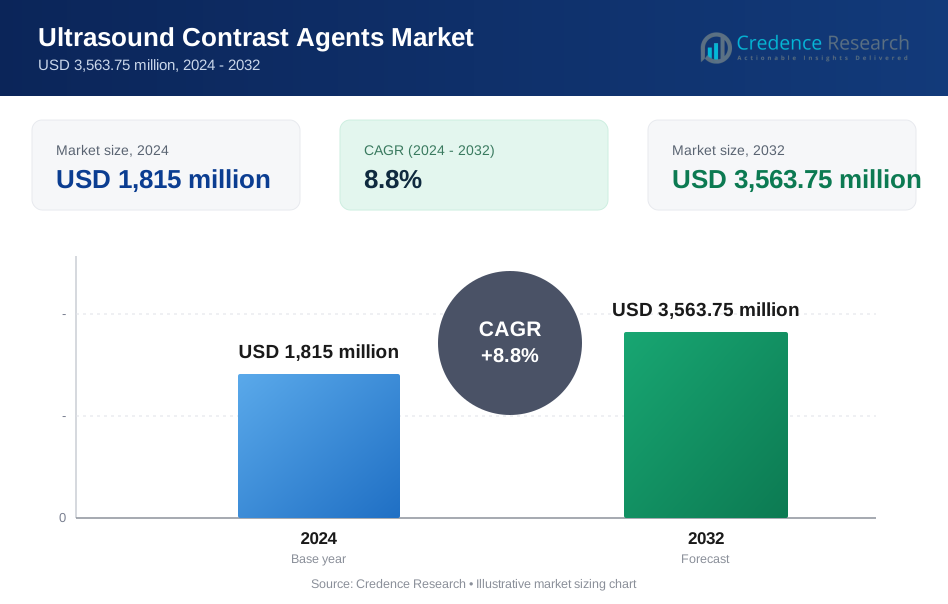
| Ultrasound Contrast Agents Market Size 2024 | USD 1815 Million |
| Ultrasound Contrast Agents Market, CAGR | 8.8% |
| Ultrasound Contrast Agents Market Size 2032 | USD 3563.75 Million |
Market Overview:
The Ultrasound Contrast Agents Market is projected to grow from USD 1815 million in 2024 to an estimated USD 3563.75 million by 2032, with a compound annual growth rate (CAGR) of 8.8% from 2024 to 2032. The growth of the ultrasound contrast agents market is driven by several key factors. Firstly, the growing prevalence of chronic diseases, such as cardiovascular disorders and cancer, has created a demand for advanced diagnostic methods to ensure timely treatment. Ultrasound contrast agents enable higher-resolution imaging, allowing for improved detection and monitoring of such conditions. Secondly, the trend toward minimally invasive procedures is boosting the adoption of ultrasound contrast agents, as these agents enhance visualization without requiring more invasive techniques, such as traditional radiographic methods. Additionally, technological advancements, including the development of microbubble-based contrast agents, have improved image clarity and expanded applications in various medical fields. Increased focus on patient safety also bolsters the market, as ultrasound contrast agents have a favorable safety profile compared to alternative contrast agents used in CT or MRI scans, reducing the risk of adverse reactions. Lastly, supportive government initiatives aimed at enhancing healthcare services, particularly in emerging economies, are driving the demand for innovative diagnostic technologies, contributing significantly to market growth. North America currently holds the largest market share in the ultrasound contrast agents market, driven by a high prevalence of chronic diseases, a strong healthcare infrastructure, and significant R&D investment in the field. The U.S. market, in particular, is leading due to high diagnostic rates and patient awareness. Europe follows closely, with growing adoption of ultrasound contrast agents spurred by supportive healthcare policies and advancements in imaging technology. Meanwhile, the Asia-Pacific region is expected to experience the highest growth rate during the forecast period, owing to increasing healthcare investments, expanding access to diagnostic imaging, and rising awareness of advanced diagnostic options in countries like China, Japan, and India. Latin America and the Middle East & Africa are also poised for gradual growth, largely due to improvements in healthcare access and government initiatives promoting advanced diagnostic practices.Market Drivers:
Increasing Prevalence of Chronic Diseases:
The rising incidence of chronic diseases such as cardiovascular disorders, cancer, and liver and kidney diseases is a primary driver for the ultrasound contrast agents’ market. These conditions often require early and precise diagnosis to ensure effective treatment, and ultrasound contrast agents provide enhanced visualization for more accurate diagnoses. Cardiovascular diseases, being the leading cause of death globally, demand advanced diagnostic tools to assess and monitor conditions like heart failure, myocardial infarctions, and vascular anomalies. Similarly, the growing burden of cancer cases globally emphasizes the need for imaging tools that enable detailed tissue differentiation and localization of tumors, where contrast agents play a vital role. As the prevalence of these chronic conditions continues to grow, so does the demand for ultrasound contrast agents.Preference for Non-Invasive Diagnostic Procedures:
Patients and healthcare providers are increasingly favoring non-invasive and minimally invasive diagnostic methods over traditional, more invasive alternatives. Ultrasound contrast agents offer a non-invasive solution with high efficacy, providing detailed images that are essential for detecting and monitoring diseases without requiring surgical or invasive diagnostic procedures. In addition, ultrasound-based imaging has fewer side effects compared to some traditional imaging modalities that use ionizing radiation, making it safer for patients, particularly those requiring repeat imaging. This preference for safer and less invasive diagnostic tools has significantly contributed to the growth of ultrasound contrast agents, as they allow clinicians to obtain clearer images with minimal patient risk and discomfort.Advancements in Microbubble Technology:
Technological advancements, particularly in microbubble-based contrast agents, are propelling the ultrasound contrast agents’ market forward. Microbubbles improve the echogenicity of ultrasound images, allowing for better contrast between blood vessels and surrounding tissues, which enhances diagnostic precision. Innovations in microbubble formulations have expanded the applications of ultrasound contrast agents beyond cardiology to include oncology, nephrology, and hepatology. For example, Advanced Microbubbles, Inc., a California-based company, is developing custom, size-isolated microbubbles for ultrasound-targeted drug delivery and gene therapy. Their technology allows for precise control of treatment by adjusting microbubble size, with smaller bubbles (2 microns) optimized for tumor ablation and larger ones (4 microns) for targeted drug delivery. Additionally, research into novel, targeted contrast agents that bind to specific cellular markers is underway, promising even greater specificity in disease detection and assessment. As manufacturers continue to improve the stability and functionality of these agents, their utility across a broader range of clinical applications is expected to rise, contributing to market growth.Government Initiatives and Increasing Healthcare Expenditures:
Supportive government initiatives, especially in emerging economies, are accelerating the adoption of advanced diagnostic technologies, including ultrasound contrast agents. Governments and health agencies worldwide are prioritizing early disease detection and preventive healthcare, which drives investments in diagnostic imaging tools. Emerging markets, such as those in Asia-Pacific and Latin America, are witnessing increased healthcare spending, bolstered by growing awareness of the benefits of modern diagnostic techniques. For instance, GE Healthcare received a $44 million grant from the Bill & Melinda Gates Foundation to develop AI-assisted ultrasound technology. Additionally, regulatory agencies are providing favorable guidelines for the approval and use of contrast agents, particularly those with improved safety profiles. With healthcare budgets expanding and regulatory support for safe and efficient diagnostic solutions in place, the market for ultrasound contrast agents is positioned for sustained growth across diverse healthcare environments.Market Trends:
Rising Adoption of Contrast-Enhanced Ultrasound (CEUS):
The increasing adoption of contrast-enhanced ultrasound (CEUS) is a prominent trend in the ultrasound contrast agents’ market. CEUS has gained popularity due to its ability to provide high-resolution images without exposing patients to ionizing radiation, as seen in CT scans or X-rays. This imaging technique is particularly valuable for liver, kidney, and vascular diagnostics, where detailed visualization is essential. For instance, Philips' CEUS technology has demonstrated a significant improvement in resolution for microvascular imaging. The expanding use of CEUS in both routine clinical practice and emergency settings reflects a shift toward safer, more accurate, and cost-effective imaging solutions. As healthcare providers seek alternatives to more invasive imaging techniques, the use of CEUS and related contrast agents is expected to continue growing, supported by ongoing education and training initiatives among radiologists and clinicians.Expansion of Application Areas:
While traditionally focused on cardiology, the application of ultrasound contrast agents has expanded to include a variety of medical fields such as oncology, nephrology, and gastroenterology. In oncology, contrast agents improve the accuracy of tumor visualization, enabling precise detection and staging of cancers. Similarly, in nephrology, they aid in identifying renal anomalies, while in hepatology, they provide clearer imaging for liver lesions. For example, Bracco's SonoVue is widely used for liver imaging, enhancing the detection of focal liver lesions. As research in molecular imaging progresses, contrast agents are increasingly tailored for specific types of tissues and pathologies, enhancing their diagnostic value across multiple specialties. The expansion of application areas has broadened the potential user base, from general hospitals to specialized diagnostic centers, driving growth within the ultrasound contrast agents market.Advancements in Targeted Microbubble Technology:
One of the most significant trends influencing the ultrasound contrast agents’ market is the advancement in targeted microbubble technology. Targeted microbubbles are designed to bind to specific cellular markers, enabling highly specific imaging and even therapeutic applications in some cases. These agents show promise in fields like oncology, where they can help locate and characterize tumors with high specificity, and cardiology, where they can provide detailed imaging of vascular structures. The development of these targeted agents aligns with the broader healthcare trend toward precision medicine, enhancing diagnostic accuracy and personalizing patient care. As research and development efforts in microbubble technology intensify, the availability of targeted ultrasound contrast agents is expected to expand, further driving market growth.Increasing Focus on Safety and Regulatory Approvals:
As the demand for ultrasound contrast agents grows, so does the emphasis on their safety and regulatory compliance. Regulatory bodies, such as the U.S. Food and Drug Administration (FDA) and the European Medicines Agency (EMA), are setting stringent standards for the approval of new agents, prioritizing patient safety and efficacy. This regulatory focus is fostering innovations in contrast agent formulations that reduce the risk of adverse reactions, making them safer for widespread use. Furthermore, approvals for specific clinical applications are encouraging healthcare providers to adopt ultrasound contrast agents with confidence, knowing they meet safety requirements. The focus on safety, coupled with streamlined regulatory pathways, is expected to encourage the development and commercialization of next-generation ultrasound contrast agents that cater to evolving healthcare needs.Market Restraints and Challenges:
High Costs and Limited Accessibility:
One of the primary restraints in the ultrasound contrast agents’ market is the high cost of these agents, which can limit their accessibility, especially in low- and middle-income regions. While contrast-enhanced ultrasound is gaining popularity, the associated costs make it less accessible for healthcare providers and patients in cost-sensitive markets. This cost barrier can restrict the adoption of ultrasound contrast agents in under-resourced healthcare settings and limits widespread utilization, particularly in emerging economies where healthcare budgets are more constrained. As a result, the cost factor poses a challenge to market expansion, even as demand for advanced imaging grows globally.Regulatory Hurdles and Lengthy Approval Processes:
The ultrasound contrast agents market faces significant regulatory hurdles, which can slow down the approval and commercialization of new agents. Regulatory bodies like the FDA and EMA have stringent requirements for the safety, efficacy, and clinical validation of contrast agents, given the risks associated with their use in imaging procedures. This can lead to lengthy and costly approval processes that delay the market entry of innovative products. Additionally, varying regulatory standards across regions create further challenges for companies attempting to operate on a global scale. These regulatory complexities can deter smaller manufacturers from investing in R&D for new agents, limiting market innovation.Limited Awareness and Adoption Among Clinicians:
Despite the proven benefits of ultrasound contrast agents, there is still limited awareness and adoption among some healthcare providers, particularly in regions where traditional imaging modalities dominate. In many cases, clinicians are more familiar with other forms of contrast media used in CT and MRI scans and may lack the training or experience needed to utilize ultrasound contrast agents effectively. This limited familiarity can lead to underutilization and restrict the growth potential of the ultrasound contrast agents market. Overcoming this challenge requires targeted educational initiatives and training programs to build awareness and drive adoption across a broader range of clinical applications.Market Segmentation Analysis:
By Product, the market is categorized into Instruments and Consumables & Reagents. Instruments include ultrasound equipment and imaging devices essential for contrast-enhanced ultrasound procedures. Consumables & Reagents encompass the microbubble contrast agents and other necessary materials used during imaging. Consumables & Reagents are projected to witness robust growth due to frequent use and demand across diagnostic procedures, while advancements in instruments continuously enhance imaging precision and efficiency. By Application, the market includes Molecular Imaging, Gene Therapy, Drug Delivery, and Stem Cell Delivery. Molecular imaging represents a substantial share due to its growing use in visualizing cellular and molecular processes for accurate diagnosis. The application in gene therapy and drug delivery is expanding as ultrasound contrast agents offer promising capabilities in targeted and controlled therapeutic interventions. Stem cell delivery applications are also gaining momentum, with contrast agents aiding in the precise localization and monitoring of stem cell therapies. By End-user, the market serves Hospitals, Diagnostic Centers, Ambulatory Surgical Centers, and Others. Hospitals account for the largest market share, driven by high patient volumes and diverse imaging needs. Diagnostic Centers follow, as they increasingly incorporate contrast-enhanced ultrasound to improve diagnostic accuracy. Ambulatory Surgical Centers represent a smaller but growing segment, driven by the rising demand for outpatient imaging and minimally invasive procedures.Segmentation:
By Product- Instruments
- Consumables & Reagents
- Molecular Imaging
- Gene Therapy
- Drug Delivery
- Stem Cell Delivery
- Hospital
- Diagnostic Centers
- Ambulatory Surgical Centers
- Others
- North America
- US
- Canada
- Mexico
- Europe
- Germany
- France
- UK
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
Regional Analysis:
The Ultrasound Contrast Agents Market is experiencing substantial growth worldwide, with key regional differences in market share, adoption rates, and technological advancements. The primary regions analyzed include North America, Europe, Asia-Pacific, Latin America, and the Middle East & Africa.North America
North America holds the largest market share in the ultrasound contrast agents market, accounting for approximately 35% of the global market. The high prevalence of chronic diseases, such as cardiovascular and liver disorders, coupled with a well-established healthcare infrastructure, drives demand for advanced imaging technologies in the United States and Canada. Furthermore, substantial investments in R&D and strong regulatory support for contrast-enhanced ultrasound technology have accelerated adoption in this region. Increasing awareness and high diagnostic rates contribute to the widespread use of ultrasound contrast agents across hospitals and diagnostic centers. North America’s leadership in medical technology and innovation supports the continued expansion of the ultrasound contrast agents market.Europe
Europe is the second-largest market, with a market share of around 30%. The region benefits from a supportive regulatory environment, high healthcare standards, and a growing focus on non-invasive diagnostic methods. The demand for ultrasound contrast agents is particularly high in countries like Germany, France, and the United Kingdom, where healthcare providers increasingly recognize the value of CEUS in early disease detection and management. Government-backed healthcare policies and reimbursement support further contribute to the adoption of ultrasound contrast agents across Europe. Additionally, advancements in microbubble technology and an increasing focus on molecular imaging are further propelling market growth within this region.Asia-Pacific
The Asia-Pacific region is expected to experience the highest growth rate in the ultrasound contrast agents market, with a current market share of approximately 20%. Rising healthcare expenditures, expanding access to diagnostic imaging, and a large population with increasing incidences of chronic diseases are significant growth drivers in this region. Countries like China, Japan, and India are seeing rapid adoption of contrast-enhanced ultrasound as healthcare awareness and infrastructure improve. Asia-Pacific also benefits from growing government initiatives to enhance diagnostic capabilities and a shift toward preventive healthcare. As a result, this region is projected to play a significant role in the global market expansion in the coming years.Latin America and the Middle East & Africa
Latin America and the Middle East & Africa account for a smaller portion of the global ultrasound contrast agents’ market, with a combined market share of about 15%. In Latin America, the adoption of advanced diagnostic imaging is increasing as healthcare access and infrastructure improve, particularly in countries like Brazil and Mexico. The Middle East & Africa region, while currently limited in adoption due to healthcare access and economic constraints, is seeing gradual growth fueled by increasing investments in healthcare and government initiatives promoting advanced diagnostics. Though these regions currently have lower market shares, they hold growth potential as awareness and adoption of ultrasound contrast agents rise in response to improving healthcare services.Key Player Analysis:
- Acusphere, Inc.
- Bayer AG
- B.K. Medical Holding Company, Inc.
- Bracco Diagnostic Inc.
- Bristol-Myers Squibb Company
- Daiichi Sankyo Company, Limited
- GE Healthcare
- Koninklijke Philips N.V.
- Lantheus Medical Imaging, Inc.
- Siemens Healthcare GmbH
- Trivitron Healthcare
Competitive Analysis:
The Ultrasound Contrast Agents Market is highly competitive, with several major players actively engaged in R&D to enhance imaging efficacy and expand applications. Key companies, including GE Healthcare, Bracco Imaging S.p.A., Lantheus Medical Imaging, Inc., and Bayer AG, dominate the market through extensive product portfolios and global distribution networks. These companies focus on innovation in microbubble technology and targeted contrast agents to improve diagnostic precision, especially in cardiovascular and oncology imaging. Smaller players and new entrants are increasingly adopting strategic partnerships and collaborations to gain market traction, particularly in emerging regions. Regulatory approvals and compliance are crucial competitive factors, with companies investing heavily to meet regional standards and streamline product approvals. As competition intensifies, market leaders are leveraging advancements in contrast agent formulations and targeting capabilities to strengthen their market positions and expand their presence in fast-growing markets like Asia-Pacific and Latin America.Recent Developments:
- In September 2023, GE HealthCare received a USD 44 million grant from the Bill & Melinda Gates Foundation to advance AI-assisted ultrasound technology. This funding is directed towards the development of auto-assessment applications that leverage AI to enhance ultrasound imaging, primarily focused on maternal and fetal health and respiratory disease diagnostics. The project, led by Caption Health—recently acquired by GE HealthCare—aims to create technology compatible with various ultrasound devices, including affordable handheld options, widening access to cutting-edge imaging solutions.
- In July 2023, Siemens Healthcare Diagnostics focused on innovation with 15 products under development within the In Vitro Diagnostics, Cardiovascular Devices, and Diagnostic Imaging markets. Meanwhile, Trivitron Healthcare is similarly active, developing 12 products in areas like In Vitro Diagnostics, Cardiovascular Devices, and Diabetes Care Devices, reflecting the sector’s growing emphasis on diagnostic advancements and diversified healthcare solutions.
- In March 2023, Bracco Imaging took steps to expand its portfolio in ultrasound and MRI contrast agents, foreseeing growth in this segment. The company is collaborating with scanner manufacturers to promote ultrasound contrast agent adoption, particularly in China, Japan, and Korea, positioning itself strongly in these high-potential markets.
Market Concentration & Characteristics:
The Ultrasound Contrast Agents Market is moderately concentrated, with a few major players holding significant market shares, including GE Healthcare, Bracco Imaging, Lantheus Medical Imaging, and Bayer AG. These key players leverage extensive R&D capabilities, robust product pipelines, and strategic partnerships to maintain competitive advantages. However, smaller companies and regional manufacturers are increasingly entering the market, particularly in Asia-Pacific, attracted by the growing demand and expanding application areas of ultrasound contrast agents. Market characteristics include a strong emphasis on innovation, particularly in microbubble technology and targeted imaging solutions. Regulatory compliance plays a crucial role, as companies need to navigate stringent approval processes, especially for safety in diagnostic applications. The market is also highly responsive to advancements in AI and imaging technology, which enhance contrast agent efficacy. Overall, market growth is shaped by technological advancements, strategic collaborations, and an increasing focus on non-invasive diagnostic procedures.Report Coverage:
The research report offers an in-depth analysis based on By Product, By Application and By End-user It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.Future Outlook:
- Advancements in AI integration with ultrasound contrast agents will drive precision in diagnostics, especially for cardiovascular and oncology applications.
- Increasing global focus on non-invasive and radiation-free imaging will propel demand for ultrasound contrast solutions.
- Growth in chronic diseases, particularly cardiovascular and liver conditions, will expand application areas for contrast-enhanced ultrasound.
- Emerging markets in Asia-Pacific will experience high adoption due to rising healthcare investments and expanding diagnostic infrastructure.
- Technological innovations in microbubble formulations will enhance specificity, opening new diagnostic and therapeutic uses.
- Regulatory support and streamlined approval processes in key regions will facilitate faster market penetration for new agents.
- Collaborations between ultrasound device manufacturers and contrast agent producers will foster integrated solutions, especially in developed economies.
- Portable and handheld ultrasound device compatibility with contrast agents will expand point-of-care diagnostics, increasing accessibility.
- Rising healthcare awareness and infrastructure improvements in Latin America and the Middle East & Africa will create growth opportunities.
- Companies focusing on R&D for targeted imaging solutions will capture market share, aligning with trends in personalized medicine.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth of the ultrasound contrast agents’ market?
What drives the growth of the ultrasound contrast agents market?
Which region is expected to grow the fastest?
What are the key challenges in this market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Ultrasound Contrast Agents Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Ultrasound Contrast Agents Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 1,815 million → 2032: USD 3,563.75 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Ultrasound Contrast Agents Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Ultrasound Contrast Agents Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Ultrasound Contrast Agents Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Ultrasound Contrast Agents Market Drivers
- 3.3 Ultrasound Contrast Agents Market Restraints & Challenges
- 3.4 Ultrasound Contrast Agents Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Ultrasound Contrast Agents Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Ultrasound Contrast Agents Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Ultrasound Contrast Agents category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Ultrasound Contrast Agents Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Ultrasound Contrast Agents Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Ultrasound Contrast Agents market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Ultrasound Contrast Agents Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Ultrasound Contrast Agents Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Ultrasound Contrast Agents Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Ultrasound Contrast Agents (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Ultrasound Contrast Agents Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Ultrasound Contrast Agents Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Ultrasound Contrast Agents Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Ultrasound Contrast Agents Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Ultrasound Contrast Agents Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Ultrasound Contrast Agents Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Ultrasound Contrast Agents Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Ultrasound Contrast Agents Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Ultrasound Contrast Agents Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
