
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| UK Biomaterials Market Size 2024 | USD 8,603.57 million |
| UK Biomaterials Market, CAGR | 14.67% |
| UK Biomaterials Market Size 2032 | USD 25,725.61 million |
Market Overview
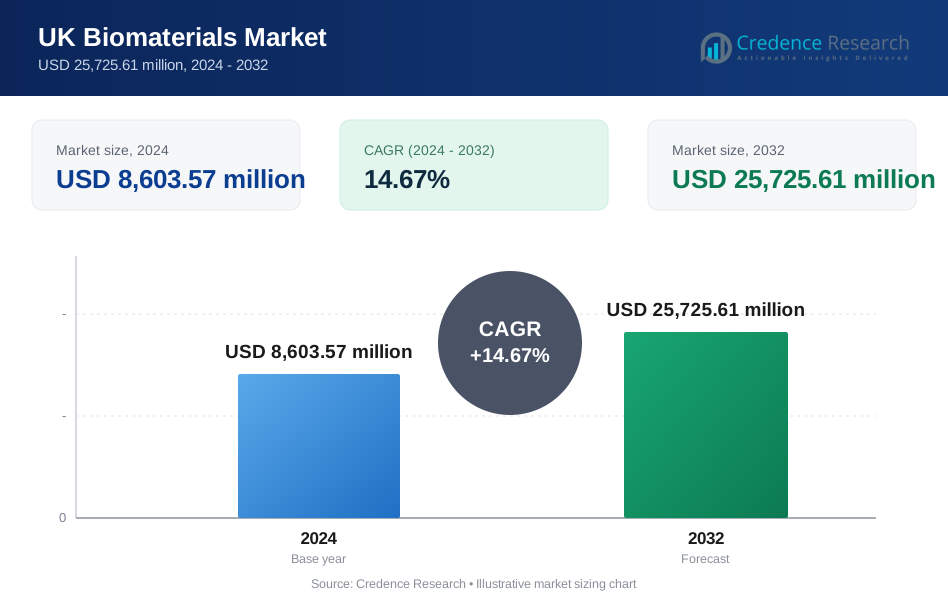
UK Biomaterials market size was valued at USD 8,603.57 million in 2024 and is anticipated to reach USD 25,725.61 million by 2032, at a CAGR of 14.67% during the forecast period (2024-2032).
The UK biomaterials market is driven by the increasing demand for advanced medical treatments, particularly in orthopedics, dentistry, and wound care. Growing healthcare spending, along with innovations in biotechnology and material science, is fostering the development of biocompatible materials for medical implants and prosthetics. Additionally, the aging population in the UK is creating a greater need for medical devices and regenerative therapies, further propelling market growth. The rise in chronic diseases, combined with a focus on improving patient outcomes, is also driving the adoption of biomaterials in healthcare settings. Moreover, advancements in 3D printing and nanotechnology are contributing to the evolution of more effective and customizable biomaterials. Sustainability trends are pushing the industry toward eco-friendly and biodegradable options, aligning with broader environmental goals. As a result, the UK biomaterials market is positioned for continued expansion and innovation, driven by both technological advances and evolving healthcare needs.
The geographical landscape of the UK biomaterials market is shaped by strong regional hubs such as London, Manchester, Birmingham, and Scotland, each playing a vital role in advancing research, development, and application of biomaterials across healthcare sectors. These regions benefit from the presence of renowned academic institutions, established healthcare infrastructure, and supportive innovation ecosystems, fostering growth in medical technologies and biomaterials adoption. Key players operating in the UK biomaterials market include industry leaders and research-focused companies such as BASF, UK Biobank, Medipharm Ltd, Biocompatibles UK Ltd, and Carmichael, all of whom contribute to the development and supply of high-quality biomaterials for diverse applications including orthopedics, cardiovascular care, and regenerative medicine. These companies actively collaborate with academic and clinical partners to drive innovation, ensure regulatory compliance, and meet the evolving needs of the medical sector. Their strategic presence and technological capabilities position the UK as a dynamic and competitive hub in the global biomaterials landscape.
Market Insights
- The UK biomaterials market was valued at USD 8,603.57 million in 2024 and is projected to reach USD 25,725.61 million by 2032, growing at a CAGR of 14.67%.
- The global biomaterials market was valued at USD 2,03,827.80 million in 2024 and is projected to reach USD 6,19,828.57 million by 2032, growing at a CAGR of 14.91% during the forecast period.
- Increasing demand for advanced medical devices and implants is driving market expansion, especially in orthopedics, cardiovascular, and dental sectors.
- Trends such as the adoption of biodegradable and eco-friendly biomaterials are gaining traction due to sustainability goals.
- Technological advancements, particularly in 3D printing and regenerative medicine, are enabling highly customized and efficient biomaterial applications.
- The market faces challenges due to high R&D costs and strict regulatory requirements for product approval and compliance.
- Major players such as BASF, UK Biobank, Medipharm Ltd, Biocompatibles UK Ltd, and Carmichael are driving innovation and competition.
- Key growth regions include London, Manchester, Birmingham, and Scotland, each benefiting from strong healthcare infrastructure and research institutions.
Report Scope
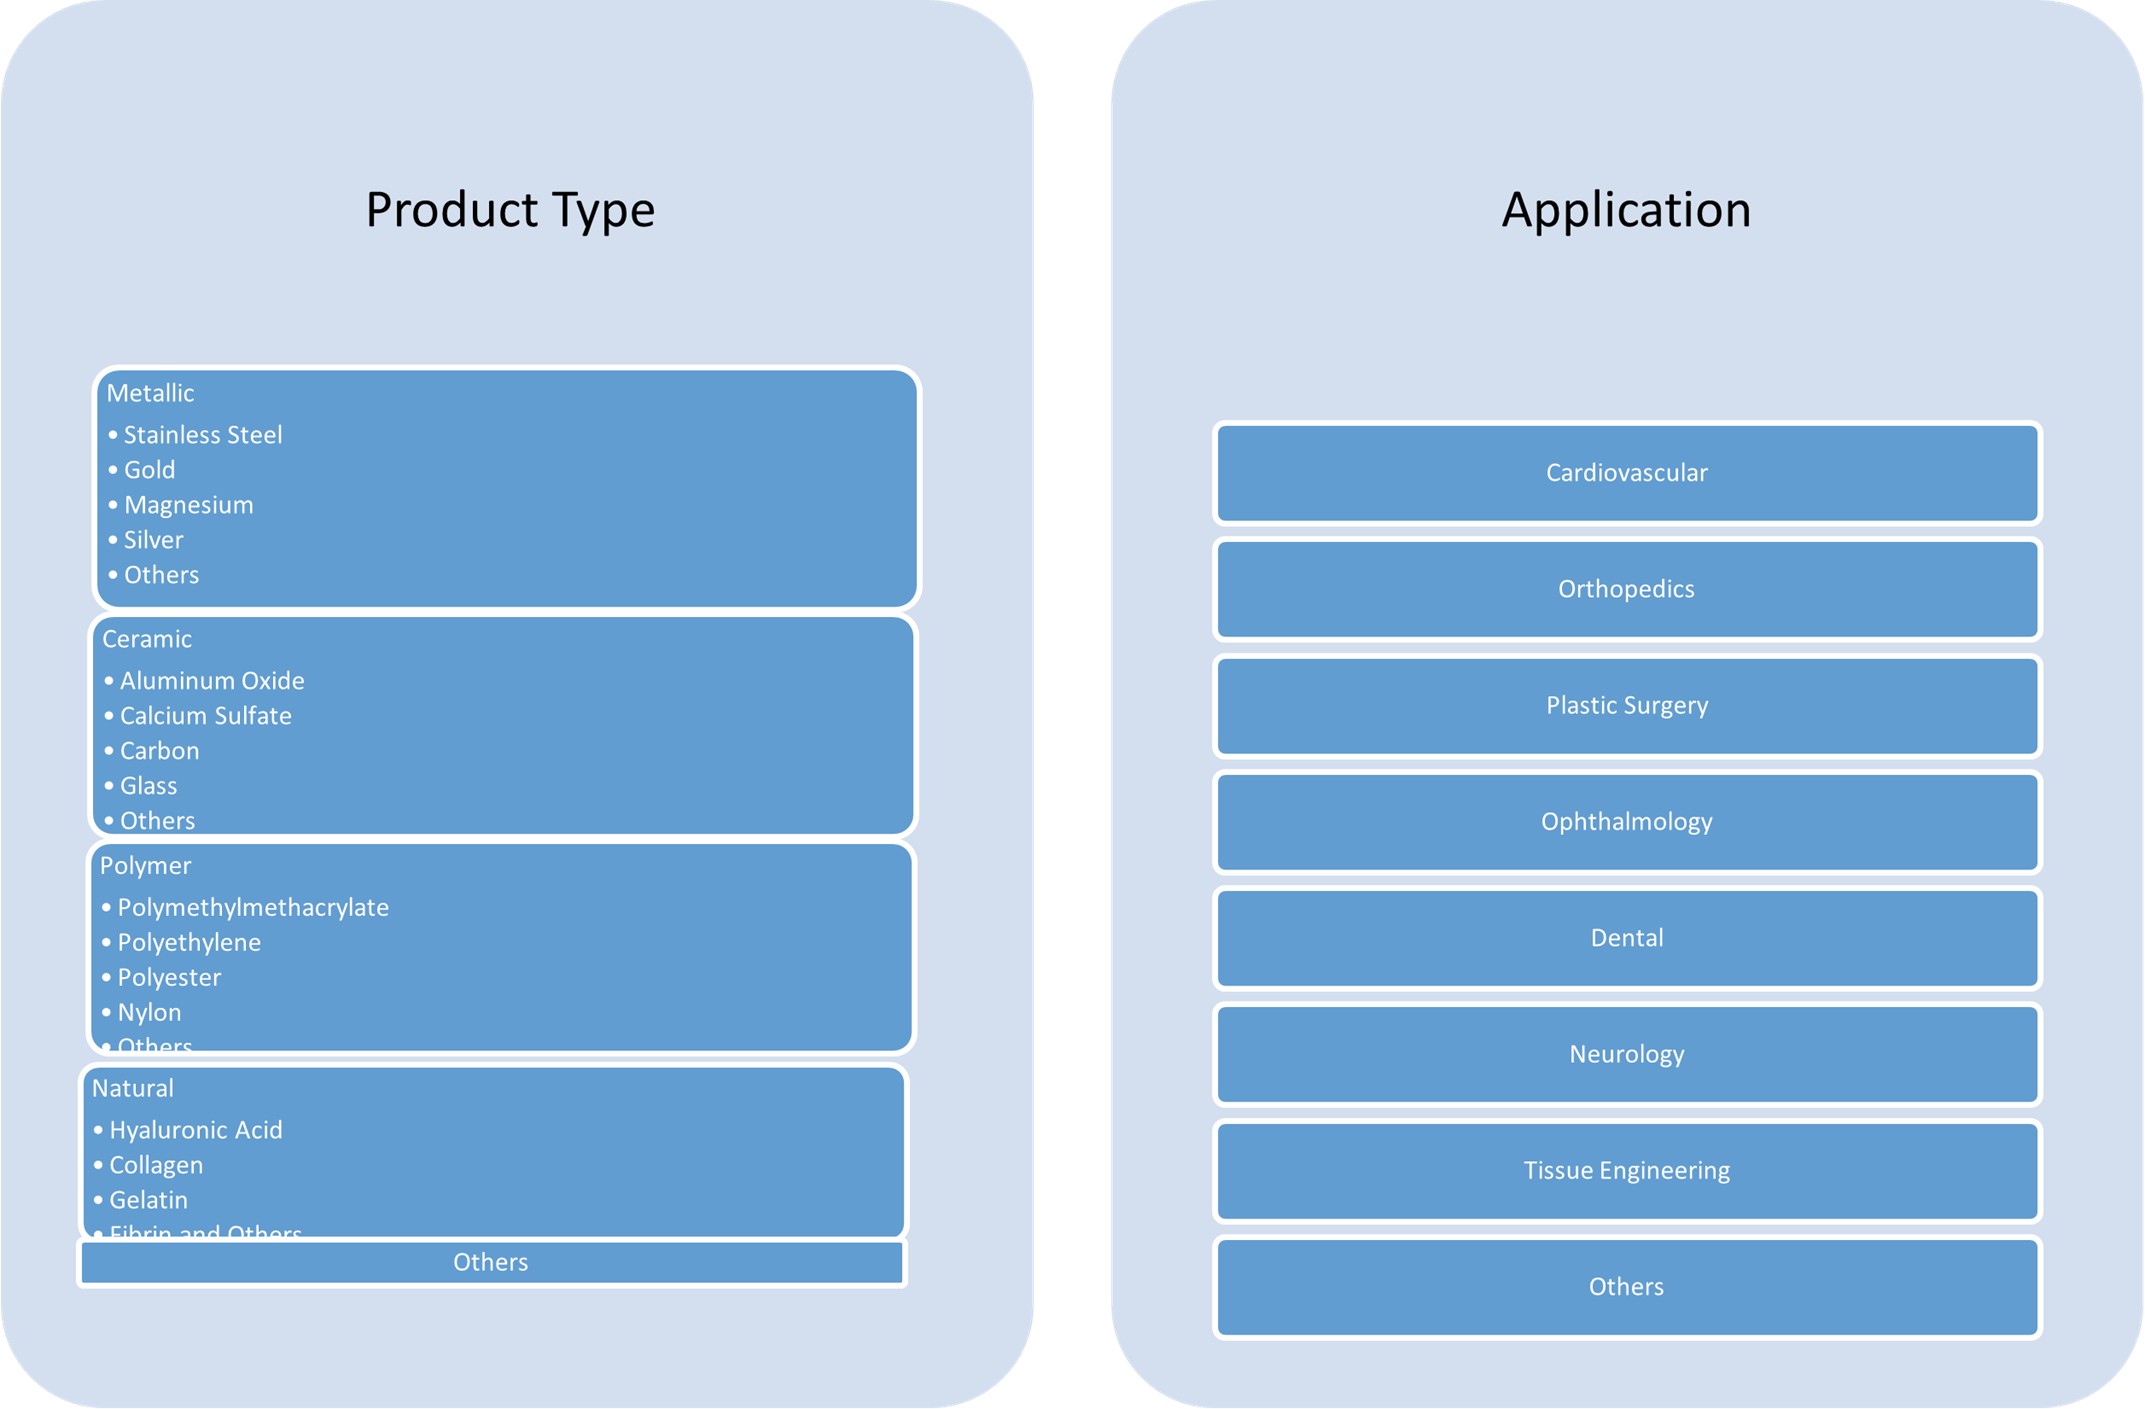
This report segments the UK Biomaterials Market as follows:
Market Drivers
Technological Advancements in Biomaterials
The continuous evolution of material science and biotechnology is a significant driver of the UK biomaterials market. Innovations in material development have led to the creation of advanced biomaterials that are more durable, biocompatible, and customizable. For instance, the UK biomaterials sector is benefiting from innovations in 3D printing and nanotechnology, enabling the production of advanced implants and prosthetics. This has allowed for improved patient outcomes, faster recovery times, and better long-term functionality. As research in these fields progresses, the ability to develop new, specialized biomaterials continues to expand, further driving the market’s growth.
Increasing Healthcare Demand and Aging Population
The growing demand for healthcare services in the UK, primarily driven by an aging population, is a key factor propelling the biomaterials market. For instance, the UK’s aging population is driving demand for biomaterials used in joint replacements, dental implants, and cardiovascular treatments. According to demographic studies, the elderly population is projected to increase significantly over the next decade, leading to higher incidences of age-related diseases like osteoarthritis, cardiovascular conditions, and osteoporosis. This will directly fuel the need for advanced biomaterials in treatments and surgeries, thereby expanding the market. Additionally, the rising prevalence of chronic diseases among younger populations further accelerates demand for biomaterial-based medical solutions.
Rising Focus on Sustainability and Eco-friendly Solutions
As environmental concerns grow, there is an increasing emphasis on the sustainability of biomaterials. In response to these concerns, the UK biomaterials market is seeing a shift towards biodegradable, eco-friendly, and sustainable materials. Research is focused on developing biodegradable polymers, natural biomaterials, and bioresorbable materials that reduce waste and environmental impact, aligning with broader environmental goals. Moreover, governments and healthcare institutions are pushing for the use of sustainable medical products to reduce the carbon footprint of the healthcare sector. The trend towards sustainability not only supports environmental protection but also opens new opportunities for companies in the biomaterials market to develop innovative, eco-conscious solutions, meeting both regulatory and consumer expectations.
Increased Healthcare Expenditure and Innovation in Medical Devices
Government and private sector investment in healthcare innovation is another key driver of the UK biomaterials market. The UK's healthcare system is undergoing continuous improvement, with significant investments in the development of medical devices and technologies that require biomaterials. Biomaterials play a crucial role in the creation of medical devices such as pacemakers, stents, and prosthetic limbs, all of which are integral to modern healthcare. Increased healthcare spending has fueled the development and adoption of cutting-edge medical devices, which in turn drives the demand for high-performance biomaterials. With a growing focus on improving patient outcomes and enhancing the quality of life, the demand for superior biomaterials in the medical device industry will continue to rise, contributing to the overall growth of the market. Furthermore, private sector collaborations and partnerships with research institutions are accelerating innovation, enabling the UK to remain at the forefront of medical technology development.
Market Trends
Shift Towards Biodegradable and Eco-friendly Materials
One of the most prominent trends in the UK biomaterials market is the growing emphasis on sustainability and the adoption of biodegradable materials. For instance, the UK biomaterials market is seeing a shift toward biodegradable and eco-friendly materials due to environmental concerns and regulatory pressures. Researchers are increasingly focused on developing materials that not only meet the biocompatibility standards for medical applications but also degrade naturally within the body or the environment. This trend is particularly relevant for applications such as wound care, drug delivery systems, and implants, where biocompatible and eco-friendly materials offer both medical benefits and reduced environmental impact. The move toward biodegradable biomaterials aligns with broader global trends in sustainability and is expected to gain momentum in the coming years.
Increased Use of 3D Printing and Customization
The integration of 3D printing technologies into the biomaterials sector is another key trend that is shaping the future of the UK market. 3D printing allows for the customization of biomaterials to meet the specific needs of individual patients, a significant advancement in personalized medicine. This capability is particularly important in orthopedics, dentistry, and prosthetics, where personalized implants and devices can improve patient outcomes by ensuring a perfect fit and better functionality. With the ongoing evolution of 3D printing technology, the market is seeing an increasing number of customized biomaterials being developed for various applications, further driving demand for innovative solutions in the medical device sector.
Expansion of Regenerative Medicine Applications
Regenerative medicine is becoming an increasingly important field within the UK biomaterials market. For instance, biomaterials are playing a crucial role in regenerative medicine, including tissue engineering and stem cell therapy. Researchers are focused on developing biomaterials that can mimic the natural extracellular matrix, providing support for cell growth and tissue formation. This trend is especially relevant for the treatment of conditions that require tissue repair or replacement, such as burn injuries, spinal cord injuries, and degenerative diseases. The integration of biomaterials into regenerative medicine is expected to not only enhance treatment outcomes but also open new opportunities for the market, particularly as advancements in stem cell technology continue to progress.
Growth of the Implant and Prosthetics Sector
The UK biomaterials market is also experiencing a significant trend toward the development of advanced implants and prosthetics. As the demand for medical implants, such as joint replacements, dental implants, and cardiovascular devices, continues to grow, there is a corresponding need for more sophisticated biomaterials. These materials must possess superior mechanical properties, biocompatibility, and durability to withstand long-term use within the human body. Advances in polymeric, metallic, and ceramic biomaterials are enabling the creation of more efficient and reliable medical implants. Additionally, as the number of individuals requiring prosthetics rises, particularly with the aging population and increasing incidences of chronic conditions, the demand for high-performance, long-lasting biomaterials in the implant and prosthetic sector is expected to continue its upward trajectory.
Market Challenges Analysis
High Research and Development Costs
One of the primary challenges facing the UK biomaterials market is the high cost of research and development (R&D). For instance, the UK biomaterials sector requires significant investment in scientific research, material testing, and clinical trials. The process is time-consuming and expensive, often leading to high production costs for new materials. While these innovations have the potential to improve patient outcomes, the financial burden of R&D can limit the ability of smaller companies to compete with larger firms in the market. Furthermore, lengthy regulatory approval processes and stringent quality standards further exacerbate costs, making it challenging for companies to bring new biomaterials to market quickly and efficiently.
Regulatory Hurdles and Compliance Issues
The UK biomaterials market also faces challenges related to regulatory hurdles and compliance with stringent medical device regulations. The biomaterials used in medical applications must undergo rigorous testing to ensure safety, efficacy, and biocompatibility, which can be a time-consuming and costly process. Regulatory bodies, such as the Medicines and Healthcare products Regulatory Agency (MHRA), require extensive documentation and evidence before approving new biomaterials for use in medical devices. Additionally, companies must stay up to date with evolving regulations, which can vary between regions and change over time. Navigating these complex regulatory requirements can delay the introduction of new biomaterials to the market and increase costs for manufacturers, ultimately impacting the overall growth of the market.
Market Opportunities
The UK biomaterials market presents significant opportunities driven by several factors, including the growing demand for advanced healthcare solutions and the increasing focus on personalized medicine. As the aging population expands, the need for medical implants, prosthetics, and regenerative therapies rises, offering a broad spectrum of opportunities for biomaterial innovation. Advanced biomaterials, including biodegradable and bioresorbable materials, are gaining traction in applications like wound healing, drug delivery systems, and tissue engineering. The demand for custom-designed medical devices, supported by advancements in 3D printing technology, also opens up avenues for growth. These technologies enable the development of personalized implants and prosthetics tailored to individual patient needs, improving treatment outcomes and enhancing the overall patient experience. Additionally, as the UK continues to invest in healthcare infrastructure, there are ample opportunities for manufacturers to introduce cutting-edge biomaterials that support emerging medical technologies.
Another key opportunity for the UK biomaterials market lies in the expansion of regenerative medicine and tissue engineering. With ongoing advancements in stem cell research and tissue regeneration, the demand for biomaterials that can support cellular growth and tissue repair is increasing. This presents opportunities for innovation in areas such as organ regeneration, spinal cord injuries, and the treatment of degenerative diseases. The convergence of biomaterials and regenerative medicine not only offers the potential for groundbreaking therapies but also aligns with the growing emphasis on sustainable healthcare solutions. As the market shifts towards environmentally friendly materials, companies that focus on developing sustainable biomaterials with minimal environmental impact will be well-positioned to meet both consumer and regulatory demands. The opportunities in these emerging fields are expected to drive market expansion and technological innovation in the coming years.
Market Segmentation Analysis:
By Product Type:
The UK biomaterials market is primarily segmented by product type, with key categories including metallic, ceramic, polymer, and natural biomaterials. Metallic biomaterials dominate the market, with materials like stainless steel, gold, magnesium, and silver widely used in medical implants and prosthetics due to their strength, durability, and biocompatibility. Stainless steel is commonly used in orthopedic devices, while gold and silver are favored for dental and cardiac implants due to their resistance to corrosion. Ceramic biomaterials, including aluminum oxide, calcium sulfate, carbon, and glass, offer excellent wear resistance and are often utilized in joint replacements and dental applications. Polymer biomaterials, such as polymethylmethacrylate, polyethylene, polyester, and nylon, are highly versatile and used in applications ranging from bone cements to soft tissue implants. Natural biomaterials, including hyaluronic acid, collagen, gelatin, and fibrin, are increasingly utilized in tissue engineering and regenerative medicine due to their compatibility with human tissue and ability to promote cell growth and healing.
By Application:
The UK biomaterials market is also segmented based on applications, with significant demand across a range of medical fields including cardiovascular, orthopedics, plastic surgery, ophthalmology, dental, neurology, and tissue engineering. Orthopedics remains the largest application segment, driven by the growing demand for joint replacements and spinal implants. Cardiovascular applications are expanding with the use of biomaterials in stents, heart valves, and pacemakers, spurred by the increasing prevalence of cardiovascular diseases. Dental applications are another key growth area, as biomaterials like ceramics and polymers are used for implants, crowns, and bridges. Plastic surgery and ophthalmology also represent significant markets, where biomaterials are used in reconstructive surgeries and in treatments for eye disorders. Furthermore, neurology and tissue engineering are emerging segments, driven by advancements in regenerative medicine and the need for materials that support nerve regeneration and organ replacement. These diverse applications offer substantial growth opportunities for the biomaterials market in the UK.
Segments:
Based on Product Type:
- Metallic
- Stainless Steel
- Gold
- Magnesium
- Silver
- Others
- Ceramic
- Aluminum Oxide
- Calcium Sulfate
- Carbon
- Glass
- Others
- Polymer
- Polymethylmethacrylate
- Polyethylene
- Polyester
- Nylon
- Others
- Natural
- Hyaluronic Acid
- Collagen
- Gelatin
- Fibrin and others
- Others
Based on Application:
- Cardiovascular
- Orthopedics
- Plastic Surgery
- Ophthalmology
- Dental
- Neurology
- Tissue Engineering
- Others
Based on the Geography:
- London
- Manchester
- Birmingham
- Scotland
Regional Analysis
London
London holds the largest market share, accounting for approximately 30% of the total UK biomaterials market. This can be attributed to the region’s strong healthcare infrastructure, proximity to top medical research institutions, and high demand for advanced medical devices in its large urban population. London’s medical sector is a key driver of innovation in biomaterials, with leading universities, hospitals, and medical centers involved in cutting-edge research and development. The city’s central role in the global medical and healthcare industry also positions it as a hub for biomaterials adoption, particularly in fields such as orthopedics, plastic surgery, and regenerative medicine.
Manchester
Manchester follows closely, contributing around 20% to the market. The city has become a focal point for biomaterials innovation, thanks to its increasing investment in medical research and the growth of the life sciences sector. The presence of institutions like the University of Manchester and the Manchester Institute of Biotechnology has strengthened the region’s position as a leader in biomaterials R&D. Moreover, Manchester’s growing number of healthcare businesses and medical device manufacturers, coupled with its strong industrial base, makes it a significant contributor to the biomaterials market. The region also benefits from a large patient population requiring treatments such as joint replacements and dental implants, boosting demand for relevant biomaterials.
Birmingham
The Birmingham region accounts for approximately 18% of the UK biomaterials market. With its strong industrial background and emphasis on medical device manufacturing, Birmingham is an essential player in the production and distribution of biomaterials. The city’s healthcare sector, supported by institutions like the University of Birmingham and the Queen Elizabeth Hospital, has seen significant advancements in medical research and technology. Additionally, Birmingham is a major center for orthopedics and cardiovascular treatment, where the demand for durable and biocompatible materials is substantial. This has led to a steady rise in the adoption of advanced biomaterials across various medical applications.
Scotland
Scotland holds a smaller yet significant share of the market, accounting for approximately 12%. The country has a well-established healthcare system and a growing focus on medical research, particularly in the fields of tissue engineering and regenerative medicine. Key academic institutions such as the University of Edinburgh and the University of Glasgow are fostering the development of new biomaterials, with applications in both medical devices and drug delivery systems. Scotland’s healthcare sector also benefits from a large population that requires long-term care, particularly for conditions related to aging, thus driving demand for materials used in implants and prosthetics. Although Scotland’s market share is smaller than that of London or Manchester, its contributions to biomaterial innovation and adoption are noteworthy.
Key Player Analysis
- BASF
- UK Biobank
- Medipharm Ltd
- Biocompatibles UK Ltd
- Carmichael
Competitive Analysis
The UK biomaterials market is moderately consolidated, with several key players driving innovation, product development, and strategic collaborations. Leading companies such as BASF, UK Biobank, Medipharm Ltd, Biocompatibles UK Ltd, and Carmichael play a pivotal role in shaping the competitive landscape. These players focus on extensive research and development to deliver advanced biomaterials tailored for diverse medical applications, including orthopedics, cardiovascular devices, and regenerative medicine. Firms in this sector focus heavily on research and development to introduce high-performance biomaterials that cater to evolving medical needs such as orthopedics, dental care, cardiovascular applications, and regenerative medicine. The competition is further intensified by rapid technological advancements, particularly in areas like 3D printing, tissue engineering, and biodegradable material development. Companies in the market are actively engaging in partnerships with academic institutions, healthcare providers, and research organizations to accelerate innovation and bring cutting-edge solutions to market. Investment in sustainable and eco-friendly biomaterials is also emerging as a competitive differentiator. Additionally, players are expanding their geographic footprint and product portfolios to address diverse clinical demands across regions. This competitive landscape encourages continuous innovation, quality improvement, and regulatory compliance, ensuring that companies remain agile and responsive to changing healthcare trends.
Recent Developments
- In April 2025, BASF expanded its EcoBalanced portfolio for Care Chemicals in North America, introducing the first EcoBalanced personal care products in the region. These include Dehyton® PK 45 and Dehyton® KE UP, both certified as EcoBalanced grades using a biomass balance (BMB) approach to reduce carbon footprint. Additionally, six U.S. Care Chemicals production sites are now powered entirely by renewable electricity, saving approximately 33,000 tons of CO₂ annually.
- In November 2024, Covestro began production of Desmophen® CQ NH, a partially bio-based polyaspartic resin (at least 25% bio-based content), at its Foshan, China site. The facility is powered entirely by renewable energy, and the product is used in wind turbine and flooring coatings, supporting both local supply and sustainability goals.
- In January 2025, BASF’s Performance Materials division transitioned all European sites to 100% renewable electricity, covering engineering plastics, polyurethanes, thermoplastic polyurethanes, and specialty polymers.
- In June 2023, Invibio announced a collaboration with Paragon Medical to scale up manufacturing of PEEK-OPTIMA Ultra-Reinforced composite trauma devices in China, responding to growing global demand for high-performance biomaterials in trauma fixation.
- In February 2023, Celanese introduced ECO-B, more sustainable versions of Acetyl Chain materials, incorporating mass balance bio-content to provide chemically identical, bio-based alternatives for engineered materials.
Market Concentration & Characteristics
The UK biomaterials market exhibits a moderate to high level of market concentration, with a mix of established players and emerging innovators contributing to its dynamic nature. The market is characterized by a strong emphasis on research and development, driven by advancements in medical technology and a growing demand for high-performance, biocompatible materials. Companies in this sector focus on specialized product offerings tailored to specific medical applications such as orthopedics, dental implants, cardiovascular devices, and tissue engineering. The market also reflects characteristics of rapid innovation cycles, strict regulatory oversight, and high entry barriers due to the need for clinical validation and compliance with health and safety standards. Collaboration between industry, academia, and healthcare institutions is common, fostering continuous innovation and ensuring alignment with evolving clinical needs. Additionally, sustainability is becoming an integral characteristic, with increasing interest in biodegradable and eco-friendly biomaterials. These factors collectively shape a competitive yet innovation-oriented market landscape in the UK.
Report Coverage
The research report offers an in-depth analysis based on Product Type, Application and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The UK will continue to invest in biomaterials research to drive innovation in healthcare and regenerative medicine.
- Universities and research institutions will expand collaborations with industry to accelerate the commercialisation of new biomaterial technologies.
- Demand for sustainable and biodegradable biomaterials will grow across sectors including packaging, textiles, and medical devices.
- Regulatory frameworks in the UK will evolve to support faster approvals and safer implementation of biomaterial innovations.
- The government will increase funding and policy support to position the UK as a global leader in biomaterials development.
- Startups and SMEs in the biomaterials space will attract more venture capital and strategic partnerships.
- Advances in nanotechnology and bioengineering will lead to the creation of more functional and adaptable biomaterials.
- The UK’s aging population will drive demand for biomaterials in orthopaedics, dental care, and wound healing applications.
- Integration of AI and data science will optimise biomaterial design, testing, and personalised medical applications.
- Workforce development initiatives will enhance skills in biomaterials science to meet growing industry needs.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the UK Biomaterials?
What factors are driving the growth of the UK Biomaterials?
What are some challenges faced by the UK Biomaterials?
Who are the major players in the UK Biomaterials?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 UK Biomaterials Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global UK Biomaterials Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 8,603.57 million → 2032: USD 25,725.61 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 UK Biomaterials Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. UK Biomaterials Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 UK Biomaterials Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 UK Biomaterials Market Drivers
- 3.3 UK Biomaterials Market Restraints & Challenges
- 3.4 UK Biomaterials Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 UK Biomaterials Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 UK Biomaterials Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, UK Biomaterials category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 UK Biomaterials Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. UK Biomaterials Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the UK Biomaterials market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 UK Biomaterials Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 UK Biomaterials Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 UK Biomaterials Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in UK Biomaterials (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New UK Biomaterials Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global UK Biomaterials Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America UK Biomaterials Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe UK Biomaterials Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific UK Biomaterials Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America UK Biomaterials Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East UK Biomaterials Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa UK Biomaterials Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. UK Biomaterials Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
