
Market Overview:
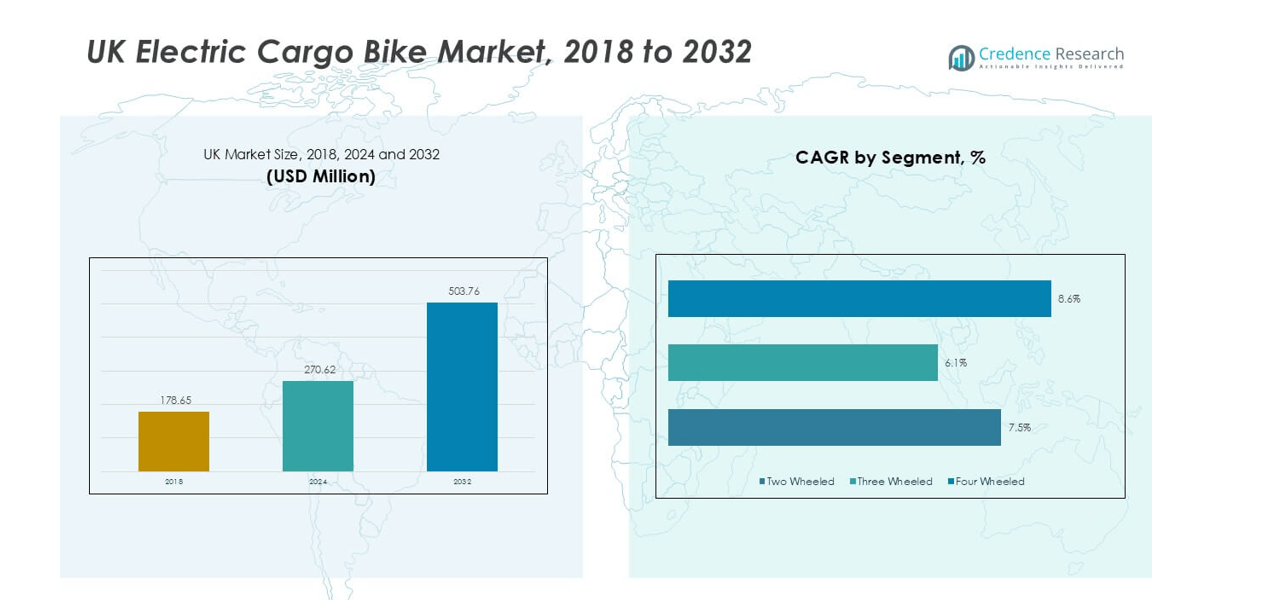
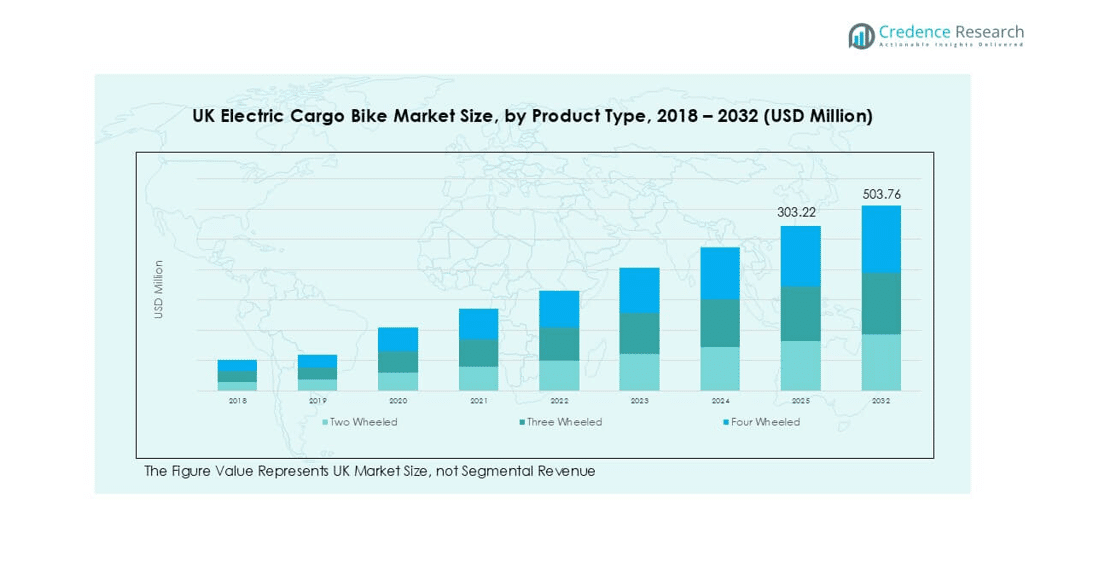
The UK electric cargo bike market size was valued at USD 178.65 million in 2018, increasing to USD 270.62 million in 2024, and is anticipated to reach USD 503.76 million by 2032, growing at a CAGR of 7.52% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| UK Electric Cargo Bike Market Size 2024 | USD 270.62 million |
| UK Electric Cargo Bike Market, CAGR | 7.52% |
| UK Electric Cargo Bike Market Size 2032 | USD 503.76 million |
In the UK electric cargo bike market, key players such as DOUZE Factory SAS, Butchers & Bicycles ApS, NIHOLA, Babboe, Riese & Müller GmbH, and Urban Arrow are intensifying competition by leveraging regional and urban-logistics expertise. Their combined market share in the UK is estimated at around 20% of the cargo-bike segment, reflecting a fragmented landscape with many niche specialists. Regionally, London stands out as the leading zone, accounting for approximately 38% of the UK market, driven by dense urban logistics demand and supportive mobility policies.
Market Insights
- The UK electric cargo bike market was valued at USD 270.62 million in 2024 and is projected to reach USD 503.76 million by 2032, expanding at a CAGR of 7.52% during the forecast period.
- Growth stems from rising demand for sustainable urban mobility and the surge in e-commerce and last-mile deliveries in UK cities.
- Key trends include dominance of the two-wheeled segment (~60% share), lithium-ion battery adoption (>70% battery type share), and increasing fleet electrification by service-delivery operators.
- Competitive pressure is intense with many niche manufacturers and logistics firms competing; however, high upfront costs and limited charging infrastructure restrain market growth.
- Regionally, England leads with roughly 70% market share, followed by Scotland (~12%), Wales (~8%), and Northern Ireland (~5%), reflecting concentration of urban delivery networks and infrastructure support.
Market Segmentation Analysis:
By Product Type
The two-wheeled segment dominated the UK electric cargo bike market with over 61% share in 2024. Its leadership is driven by high maneuverability, cost-efficiency, and suitability for urban logistics. These bikes are widely used for last-mile deliveries and personal transport due to their compact design and ease of parking in congested areas. Major logistics firms prefer two-wheeled models for quick movement through narrow city routes. Increasing investments in sustainable delivery fleets and urban mobility programs further enhance the adoption of this segment across major UK cities.
- For instance, Amazon deployed over 330 electric cargo bikes at its London micro-mobility hubs, supporting around five million parcel deliveries annually across central districts, reducing an estimated 700 tons of CO₂ emissions per year.
By Battery Type
Lithium-ion batteries accounted for nearly 73% of the UK electric cargo bike market in 2024. Their dominance stems from superior energy density, faster charging times, and longer lifespan compared to lead-based or nickel-based options. Manufacturers are integrating advanced lithium cells to extend range and reduce overall bike weight. The segment benefits from declining battery costs and government support for energy-efficient mobility. Continuous R&D in solid-state and recyclable battery technologies also strengthens the lithium-ion segment’s position as the preferred power source for electric cargo bikes in the UK market.
- For instance, Urban Arrow uses Bosch’s lithium-ion PowerPack 500, offering a 13.4 Ah capacity and an effective range of about 90 kilometers per charge. Bosch’s latest celchemistry allows over 1,500 full charge cycles before capacity drops below 80%, enhancing operational lifespan for logistics fleets.
By End Use
The service delivery segment held about 52% share of the UK electric cargo bike market in 2024. This dominance is fueled by rising e-commerce and food delivery operations seeking low-emission, cost-effective transportation solutions. Companies like Deliveroo and DHL are expanding electric cargo bike fleets to improve last-mile efficiency and meet sustainability goals. Urban congestion reduction programs by local councils also promote the use of such vehicles for short-distance logistics. Increased demand for faster and eco-friendly deliveries continues to drive strong growth in the service delivery end-use segment.
Key Growth Drivers
Growing demand for sustainable urban mobility
Urban centres across the UK face rising congestion and stricter air-quality targets. The shift toward zero-emission transport has led businesses and city authorities to favour electric cargo bikes. In particular, fleets of two- and three-wheeled models are replacing vans for short-haul deliveries. This driver boosts adoption because these bikes offer agility in tight spaces, lower operating costs and environmental benefits.
- For instance, DPD UK operates a large electric vehicle (EV) fleet, which includes cargo bikes alongside thousands of electric vans and some heavier electric vehicles. The fleet operates in dozens of urban centers across the country, where DPD aims to achieve all-electric deliveries. These efforts have already saved significant amounts of CO₂, with the company achieving a total reduction of over 167,000 tonnes since 2020 through a range of initiatives, including electric vehicles and biofuel-powered HGVs.
Expansion of e-commerce and last-mile delivery
The UK’s booming online-shopping economy has created urgent need for efficient last-mile logistics. Electric cargo bikes provide urban logistics firms with a faster, greener way to deliver goods in congested city zones. With van access sometimes restricted and parking difficult, cargo bikes reduce delivery times and cut emissions. This structural shift in delivery models fuels growth in the market for electric cargo bikes.
- For instance, UPS tested its eQuad four-wheeled cargo bike in Cambridge, achieving an average delivery capacity of 200 kilograms per trip and operating within zero-emission zones where conventional vans were banned, improving last-mile efficiency by 20% compared to small vans.
Supportive government policies and incentives
UK policy initiatives emphasise green transport and clean-logistics. Grants, subsidies and local-authority schemes help reduce the upfront cost of electric cargo bikes for businesses. These policy frameworks create a more supportive investment climate, encouraging companies and councils to adopt cargo-bike fleets. In turn, this policy drive accelerates market penetration and acceptance of electric cargo bikes.
Key Trends & Opportunities
Fleet electrification for commercial delivery services
Logistics and retail firms increasingly integrate electric cargo bikes into their operations to replace vans and reduce emissions. This trend opens opportunity for manufacturers and rental platforms to supply tailored fleets for service-delivery, retail and rental businesses. Urban locales are particularly ripe for deployment, creating room for growth in commercial end-use and ancillary services (maintenance, charging infrastructure).
- For instance, Sainsbury's introduced a trial of a fleet of five electric cargo bikes for its delivery network in South London, delivering up to 100 online grocery orders a day from its Streatham Common store. The initiative aimed to test a more flexible, zero-emission delivery method for dense urban areas.
Technological advances and battery innovations
Battery life, load capacity and motor efficiency continue to improve in electric cargo bikes. Longer ranges and faster charging make the bikes more viable for commercial and personal use alike. The opportunity lies in smart-features (telematics, fleet-management software), battery swapping systems and lighter materials. Companies that capitalise on these innovations can differentiate and seize advantage in the growing UK market.
Key Challenges
High initial cost and total ownership expense
Despite lower operating costs, electric cargo bikes still carry higher upfront purchase prices compared to conventional bicycles or small vans. This cost barrier limits uptake among smaller businesses and individual users. Additionally, ancillary costs - such as dedicated charging infrastructure, battery replacement and specialised maintenance - may deter investment and slow the pace of adoption.
Limited charging infrastructure and range constraints
Urban deployment of electric cargo bikes is constrained by charging-point availability and battery range. For heavier loads or frequent stops, battery depletion becomes a real concern. In cities without well-developed infrastructure, operators may face downtime or route limitations. This challenge affects reliability and reduces the appeal of electric cargo bikes where long-distance or high-frequency use is needed.
Regional Analysis
England
England commands the largest portion of the market, estimated around 70% of the UK total. Major urban centres such as London, Manchester and Birmingham drive demand through dense delivery networks and supportive low-emission policies. Logistics and retail firms invest heavily in electric cargo bikes to meet sustainability targets and navigate urban traffic. Infrastructure improvements, such as dedicated lanes and city grants, further strengthen England’s dominance. The high concentration of e-commerce operations and last-mile fleets in England makes this region pivotal for market growth.
Scotland
Scotland holds about 12% of the UK electric cargo bike market. The region shows growing interest from local authorities in green mobility initiatives, especially in cities like Edinburgh and Glasgow. Unique terrain and weather conditions push manufacturers to tailor models for Scottish use, including rugged frames and all-weather functionality. However, more dispersed population and fewer large urban delivery hubs slightly limit acceleration. Support from devolved government funding and expansion of cycling infrastructure provide a positive tailwind for Scotland’s segment.
Wales
Wales represents approximately 8% of the market. Its smaller urban centres and rural-urban mix shape demand for cargo bikes that serve local businesses and community-based logistics rather than large-scale delivery fleets. Welsh authorities’ ambition to cut carbon emissions and promote cycling creates opportunity for cargo bike adoption. Nonetheless, slower pace of e-commerce deployment and less dense urban freight clusters mean growth trails England. Focus on modular and multi-purpose models, plus grant support, help Wales progress steadily.
Northern Ireland
Northern Ireland accounts for roughly 5% of the UK market. The region’s compact geography and concentrated population around Belfast favour deployment of electric cargo bikes for last-mile and micro-logistics services. Incentives from regional government support smaller fleets, and community-oriented delivery models gain traction. However, relatively limited scale of major retail/industrial hubs and less developed cargo-bike infrastructure slightly constrain rapid expansion. Over time, Northern Ireland’s market may accelerate as infrastructure and fleet financing improve.
Market Segmentations:
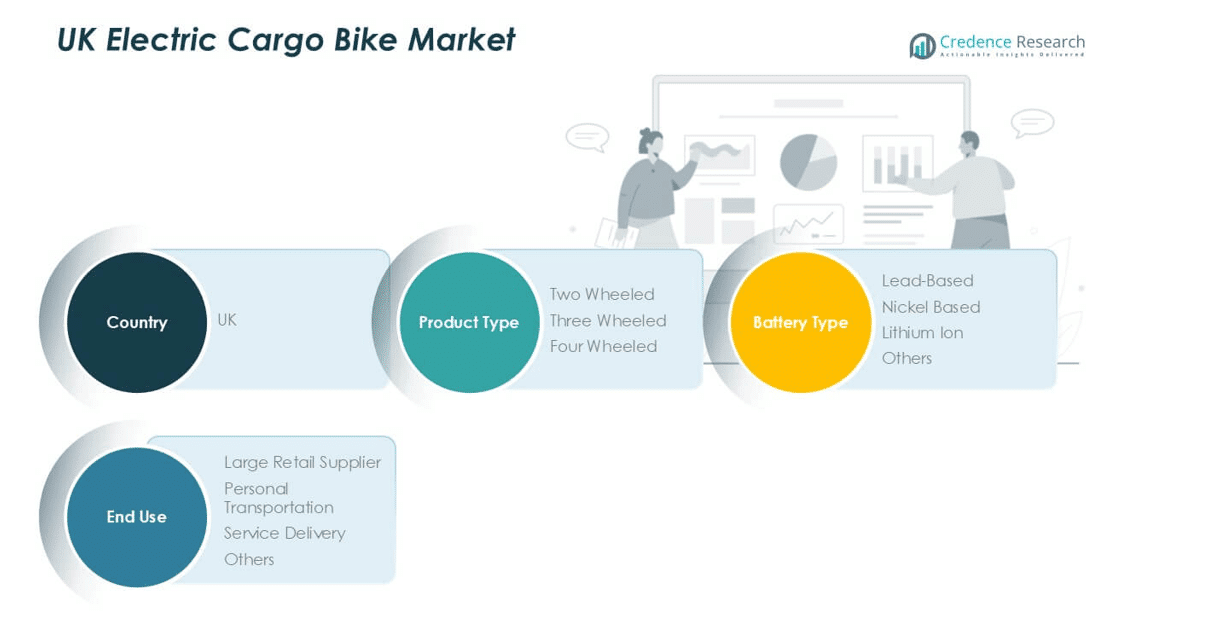
By Product Type
- Two Wheeled
- Three Wheeled
- Four Wheeled
By Battery Type
- Lead-Based
- Nickel Based
- Lithium Ion
- Others
By End Use
- Large Retail Supplier
- Personal Transportation
- Service Delivery
- Others
By Geography
- England
- Scotland
- Wales
- Northern Ireland
Competitive Landscape
The competitive landscape of the UK electric cargo bike market features a wide array of established bicycle manufacturers, specialist cargo-bike firms, and new mobility startups all vying for dominance. Global brands and European niche players alike are enhancing their UK presence, which intensifies competition across product specs, service models, and geographic coverage. Many companies highlight innovations such as heavier payloads, longer battery range and smart fleet-management features to differentiate from more basic models. At the same time, logistics firms and retail fleets are entering the supply chain directly or partnering with manufacturing firms, pushing rivals to scale costs and expand service offerings. With government grants and green-mobility mandates fueling demand, suppliers must combine strong design, after-sales support and integrated charging infrastructure to secure market position and ride the shift toward sustainable last-mile delivery in the UK.
Key Player Analysis
- DOUZE Factory SAS
- XYZ CARGO
- Butchers & Bicycles ApS
- NIHOLA
- Babboe
- Riese & Müller GmbH
- Urban Arrow
Recent Developments
- In February 2024, Riese & Müller has introduced a new entry-level platform for its premium brand. While the starting price of £5,469 is still a significant investment, this bike offers several unique features. Most notably, it boasts a frame made in Portugal from 81% recycled aluminium.
- In February 2024, Gocycle, a renowned supplier of electric bikes, announced the launch of its new electric cargo bike. The product came in two variants namely the CXi and the CX+.
- In September 2023, Amazon, a global leader in the e-commerce space started a micromobility hub in Glasgow, Scotland to start delivering using electric cargo bikes. This move is part of the company’s efforts to decarbonize and electrify its delivery services in the European region.
Report Coverage
The research report offers an in-depth analysis based on Product Type, Battery Type, End Use and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Adoption of electric cargo bikes will grow rapidly across UK urban logistics as companies replace vans with bikes for last-mile delivery.
- Fleet operators will increasingly choose high-capacity, two-wheeled models supported by lithium-ion batteries to maximise efficiency and reduce emissions.
- Government incentives and city-level low-emission zones will drive greater deployment of electric cargo bikes in metropolitan areas.
- Technology improvements in battery life, modular design, and telematics will enhance bike range and reduce total cost of ownership.
- Integration of charging infrastructure in urban zones and business parks will support broader uptake by overcoming range anxiety.
- Shared-fleet and rental schemes for cargo bikes will emerge, letting small businesses access electric cargo bikes without full ownership.
- Expansion into smaller towns and rural delivery zones will open additional market segments beyond major cities.
- Partnerships between manufacturers, logistics firms and local authorities will accelerate market scale and service innovation.
- Supply chain pressures, such as battery raw-material costs and import logistics, may temporarily constrain growth.
- Standardisation of safety and regulatory frameworks for electric cargo bikes will increase market trust and simplify deployment across the UK.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Sustainable Urban Mobility Initiatives
UK cities are increasingly prioritizing zero-emission transport to address congestion and air quality, leading businesses and local authorities to adopt electric cargo bikes for urban logistics and last-mile delivery.
E-commerce and Last-Mile Delivery Growth
The rapid expansion of online shopping in the UK has intensified demand for efficient, low-emission last-mile delivery solutions, with electric cargo bikes offering a practical alternative to vans in congested urban areas.
Government Incentives and Policy Support
National and local government grants, subsidies, and low-emission zone policies are reducing the upfront cost and operational barriers for businesses to invest in electric cargo bike fleets, accelerating market adoption.
Technological Advancements in Batteries and Fleet Management
Improvements in lithium-ion battery technology, telematics, and modular bike design are increasing range, payload, and operational efficiency, making electric cargo bikes more attractive for commercial and personal use.
Corporate Sustainability Commitments
Major logistics and retail firms are expanding electric cargo bike fleets to meet ambitious sustainability targets, reduce carbon emissions, and enhance brand reputation in response to consumer and regulatory pressures.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the market size of the UK Electric Cargo Bike Market in 2023 and 2032?
At what Compound Annual Growth Rate is the UK Electric Cargo Bike market projected to grow between 2025 and 2032?
What are the key drivers of the UK Electric Cargo Bike Market growth?
How is the UK government supporting the electric cargo bike market?
What is the impact of e-commerce on the UK Electric Cargo Bike Market?
Who are the leading players in the UK Electric Cargo Bike Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End Use
- 1.2.1 Large Retail Supplier
- 1.2.2 Personal Transportation
- 1.2.3 Service Delivery
- 1.2.4 Others
- 1.3 By Battery Type
- 1.3.1 Lead-Based
- 1.3.2 Nickel Based
- 1.3.3 Lithium Ion
- 1.3.4 Others
- 1.4 By Product Type
- 1.4.1 Two Wheeled
- 1.4.2 Three Wheeled
- 1.4.3 Four Wheeled
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 270.62 million → 2032: USD 503.76 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 UK Electric Cargo Bike Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 UK Electric Cargo Bike Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 UK Electric Cargo Bike Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 UK Electric Cargo Bike Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 UK Electric Cargo Bike Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 UK Electric Cargo Bike Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 UK Electric Cargo Bike Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 UK Electric Cargo Bike Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 270.62 million → 2032: USD 503.76 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 UK Electric Cargo Bike Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End Use - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Large Retail Supplier
- 12.3.7.2 Personal Transportation
- 12.3.7.3 Service Delivery
- 12.3.7.4 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Battery Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Lead-Based
- 12.4.7.2 Nickel Based
- 12.4.7.3 Lithium Ion
- 12.4.7.4 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Product Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Two Wheeled
- 12.5.7.2 Three Wheeled
- 12.5.7.3 Four Wheeled
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 UK Electric Cargo Bike End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 UK Electric Cargo Bike Geographic Market Outlook, 2024-2032
- 14.1 Domestic Market Distribution and Demand Clusters
- 14.2 State- or Province-Wise Market Size and Forecast, 2024-2032
- 14.3 City and Metropolitan Market Outlook
- 14.4 Industrial, Manufacturing and Commercial Clusters
- 14.5 Geographic Concentration of Key End Users
- 14.6 Local Pricing and Purchasing Differences
- 14.7 Domestic Production Facilities and Capacity Map
- 14.8 Local Infrastructure and Project Pipeline
- 14.9 State-Level Policy and Incentive Differences
- 14.10 Subnational Investment Hotspots and Opportunities
- 14.11 Distribution and Logistics Networks
- 14.12 Domestic Competitive Footprint
Chapter 15 UK Electric Cargo Bike Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 UK Electric Cargo Bike Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 DOUZE Factory SAS
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Butchers & Bicycles ApS
- 18.4 NIHOLA
- 18.5 Babboe
- 18.6 Riese & Müller GmbH
- 18.7 Urban Arrow
- 18.8 Gocycle
- 18.9 XYZ CARGO
- 18.10 Tern Bicycles
- 18.11 Yuba Bicycles
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

