
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| U.S. Interior Design Software Market Size 2023 | USD 1,901.07 million |
| U.S. Interior Design Software Market, CAGR | 11.91% |
| U.S. Interior Design Software Market Size 2032 | USD 5,232.63 million |
Market Overview:
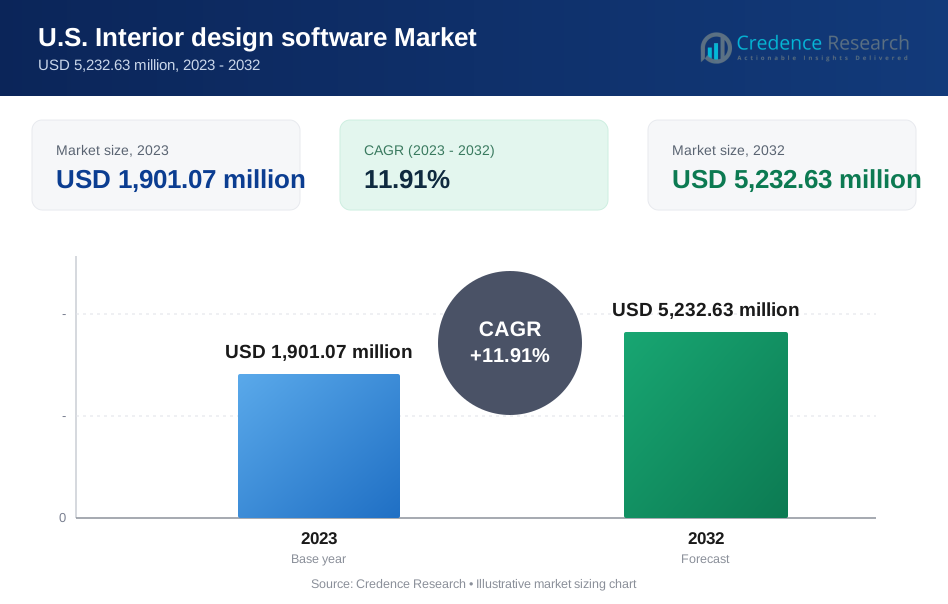
U.S. Interior design software market size was valued at USD 1,901.07 million in 2023 and is anticipated to reach USD 5,232.63 million by 2032, at a CAGR of 11.91% during the forecast period (2023-2032).
One of the key drivers of market growth is the increasing focus on digitization and automation in interior design. AI-powered tools and 3D rendering technologies are enabling designers to create detailed, photorealistic models, reducing project timelines and costs. The rising trend of smart homes and sustainable design is also influencing software adoption, as professionals seek solutions that incorporate energy-efficient layouts, eco-friendly materials, and space optimization techniques. Additionally, the surge in remote working and hybrid office environments has led to a higher demand for interior design software to create flexible, adaptable workspaces. The accessibility of cloud-based platforms has further enhanced market penetration, allowing designers and firms to collaborate in real time, streamline workflow management, and access design tools from anywhere.
The U.S. market is regionally diverse, with major metropolitan areas such as New York, California, Texas, and Florida serving as key hubs for interior design activity. New York and California lead in software adoption due to the high concentration of architecture and design firms, coupled with strong demand for commercial and residential space planning. Texas and Florida are witnessing rapid growth, driven by increasing urbanization, expanding real estate markets, and rising investments in home improvement projects. The Midwest and Southern states are also gaining traction, supported by the growing trend of smart city initiatives and rising interest in digital interior design solutions. Overall, the increasing preference for cloud-based, AI-integrated design software across various regions is shaping the growth trajectory of the U.S. interior design software market.
Market Insights:
- The S. interior design software market was valued at USD 1,901.07 million in 2023 and is projected to reach USD 5,232.63 million by 2032, growing at a CAGR of 11.91%, driven by rising adoption of AI, 3D rendering, and cloud-based solutions.
- The increasing focus on digitization and automation is transforming interior design processes, enabling AI-powered tools and 3D visualization to streamline workflows, reduce costs, and enhance project efficiency.
- Smart homes and sustainable design trends are accelerating software adoption, as professionals integrate energy-efficient layouts, eco-friendly materials, and space optimization features to meet evolving consumer demands.
- The market is experiencing a shift towards cloud-based and subscription models, allowing designers and firms to collaborate remotely, improve workflow efficiency, and access real-time design updates.
- The expanding real estate sector, rising home renovations, and commercial infrastructure development are key factors fueling market growth, with increasing investments in hotels, offices, and retail spaces.
- High software costs and integration challenges remain significant barriers, as advanced solutions require substantial investment, training, and seamless compatibility with existing AEC software.
- Regional demand varies, with New York and California leading due to high architectural firm concentration, while Texas, Florida, and the Midwest witness rapid growth driven by urbanization, smart city initiatives, and home improvement projects.
Market Drivers:
Adoption of AI, AR/VR, and 3D Rendering Technologies
The increasing integration of artificial intelligence (AI), augmented reality (AR), virtual reality (VR), and 3D rendering technologies is significantly driving the growth of the U.S. interior design software market. AI-powered design tools allow designers to automate repetitive tasks, optimize space layouts, and generate smart recommendations based on user preferences. Advanced 3D rendering and AR/VR solutions enable clients to visualize designs in a realistic and immersive manner, reducing the risk of errors and last-minute modifications. For instance, SketchUp Viewer provides immersive experiences by enabling users to view and interact with 3D models in virtual reality. Compatible with devices like Meta Quest 2, Pro, and 3, it allows stakeholders to inhabit a design virtually, facilitating clear communication and reducing misunderstandings. These technologies also improve collaboration between designers, architects, and clients, streamlining project workflows and enhancing customer satisfaction. As more firms adopt AI-driven generative design tools and real-time visualization platforms, the demand for sophisticated interior design software solutions continues to grow.
Rising Demand for Cloud-Based and Subscription-Based Solutions
The shift toward cloud-based interior design software is reshaping the industry, allowing designers and firms to access projects remotely, collaborate in real time, and improve workflow efficiency. Cloud-based solutions offer cost-effective and scalable alternatives to traditional on-premise software, enabling smaller design studios and independent professionals to leverage high-end design tools without heavy upfront investments. For instance, platforms like Foyr Neo and Cedreo offer cloud-based solutions that provide cost-effective and scalable alternatives to traditional on-premise software, enabling smaller design studios and independent professionals to leverage high-end design tools without heavy upfront investments. Subscription-based models have further facilitated software adoption by providing flexible pricing plans and continuous software updates, ensuring access to the latest design features and improvements. This transition to cloud computing is also enhancing data security, enabling seamless integration with other enterprise solutions, and improving overall project management efficiency.
Growth in Real Estate, Home Renovation, and Commercial Infrastructure
The expanding U.S. real estate sector, rising home renovation activities, and increasing commercial infrastructure development are key factors propelling the demand for interior design software. The surge in home improvement projects, driven by rising disposable incomes and the increasing preference for personalized home interiors, has accelerated software adoption among homeowners, architects, and interior designers. For instance, the U.S. home improvement sector has seen significant growth, with homeowners spending approximately $827 billion on home improvement projects over the two-year period ending in 2023. The growing trend of sustainable and energy-efficient building designs has further amplified the need for advanced design software that supports eco-friendly material selection, energy-efficient layouts, and space optimization. In the commercial sector, the rising construction of hotels, offices, retail spaces, and healthcare facilities is driving the demand for customized, technology-driven interior design solutions.
Increasing Demand for Smart Homes and Sustainable Interior Design
The growing penetration of smart home technology and the increasing emphasis on sustainable design practices are driving the evolution of the interior design software market in the U.S. Homeowners and businesses are seeking solutions that enable seamless integration of smart lighting, HVAC systems, IoT-enabled furniture, and automated home management systems. Interior design software is playing a critical role in facilitating this transformation by offering AI-driven recommendations for smart space utilization and energy-efficient designs. For instance, Interior design software, such as HomeByMe and Live Home 3D, is playing a critical role in facilitating this transformation by offering AI-driven recommendations for smart space utilization and energy-efficient designs. Additionally, sustainability-driven consumer preferences are pushing designers to incorporate eco-friendly materials, optimize space usage, and enhance indoor environmental quality using design software. The rising influence of LEED-certified projects and green building standards is further encouraging the adoption of interior design tools that align with energy conservation and sustainability goals.
Market Trends:
Expansion of AI-Powered Automation in Design Processes
The growing integration of artificial intelligence (AI) and machine learning in interior design software is transforming the way professionals create and optimize spaces. AI-driven tools now assist in generating automated design layouts, recommending furniture placements, and predicting the best color schemes based on user preferences. For instance, platforms like Planner 5D utilize machine learning algorithms to generate design ideas and layouts tailored to specific inputs such as room dimensions, style preferences, and budget constraints. These advancements are reducing the time spent on manual adjustments and enhancing precision in design planning. AI algorithms are also being used to analyze past design patterns and consumer behavior, enabling designers to create more personalized and functionally optimized spaces. As automation continues to gain traction, software providers are focusing on improving AI-driven design assistants that streamline workflows and offer real-time modifications based on project constraints.
Growing Adoption of Augmented and Virtual Reality Technologies
The demand for immersive visualization experiences is driving the adoption of augmented reality (AR) and virtual reality (VR) in the interior design software market. Clients and designers are increasingly relying on AR-enabled mobile applications and VR headsets to experience spaces before finalizing design decisions. These technologies allow users to navigate virtual interiors, interact with furniture placements, and make real-time modifications, improving decision-making and reducing costly post-installation changes. The use of AR for virtual staging in real estate is also gaining momentum, helping potential buyers visualize furnished spaces. For instance, Enscape offers real-time walkthroughs, allowing users to navigate fully rendered 3D environments and explore designs from every angle. This immediate visualization facilitates instant feedback and informed decision-making, enhancing collaboration between designers and clients. As hardware and software integrations improve, interior design firms are expected to invest more in AR/VR-powered platforms to enhance customer engagement and satisfaction.
Rising Preference for Cloud-Based and Cross-Platform Solutions
With an increasing emphasis on remote collaboration, interior design firms are shifting toward cloud-based and cross-platform design software solutions. For instance, Applications like Figma AI integrate artificial intelligence to streamline the design process with smart automation and AI-powered suggestions, enhancing layout and style recommendations. Cloud-based platforms offer real-time synchronization, enabling teams to work on projects simultaneously from different locations. This trend has gained further momentum with the rise of hybrid work models, allowing designers to manage projects seamlessly across multiple devices, including tablets, laptops, and smartphones. Cross-platform compatibility is also expanding, allowing software solutions to integrate with external tools such as BIM (Building Information Modeling) software, ERP systems, and smart home automation platforms. The enhanced accessibility and interoperability of cloud-based design solutions are making them a preferred choice for professionals looking for flexibility and efficiency in project management.
Increasing Emphasis on Sustainable and Eco-Friendly Design Features
Sustainability is becoming a focal point in interior design, with a growing emphasis on eco-friendly materials and energy-efficient layouts. AI-powered tools are being developed to assist designers in creating personalized and functional spaces that align with environmental considerations. For example, research into AI applications in interior design explores the use of generative models to streamline the creation of room interiors, offering efficient and customizable design solutions that can incorporate sustainable practices. These advancements enable designers to assess the environmental impact of their choices and optimize natural lighting and energy consumption, supporting the industry's shift towards environmentally responsible practices.
Market Challenges Analysis:
High Software Costs and Learning Curve
The high cost of premium interior design software remains a significant barrier to widespread adoption, particularly for small and independent design firms. Advanced software with AI-powered automation, 3D rendering, and virtual reality integration often requires substantial investment, making it less accessible to budget-conscious professionals. Additionally, many of these solutions have complex user interfaces, requiring extensive training and expertise to maximize their functionality. The steep learning curve associated with high-end design software limits its usability for non-technical users, increasing dependency on skilled professionals and reducing the rate of adoption among freelance designers and small businesses.
Limited Compatibility and Integration Challenges
Despite technological advancements, integration challenges persist within the U.S. interior design software market. Many software solutions struggle to achieve seamless compatibility with existing architecture, engineering, and construction (AEC) software, leading to inefficiencies in design workflows. The lack of standardized file formats and cross-platform compatibility hinders collaboration between designers, architects, and construction teams, causing delays in project execution. Additionally, cloud-based solutions, while offering remote accessibility, sometimes face data security concerns and performance limitations, especially when handling large-scale projects requiring high computational power. These challenges create bottlenecks in operational efficiency and slow down the adoption of digital design solutions across the industry.
Market Opportunities:
The U.S. interior design software market presents significant growth opportunities, driven by the increasing adoption of digital design solutions across residential, commercial, and industrial sectors. The rising demand for AI-powered automation, 3D visualization, and cloud-based collaboration tools is transforming the way interior design projects are conceptualized and executed. As businesses and homeowners seek more personalized and data-driven design solutions, software providers have the opportunity to expand their offerings with advanced functionalities such as real-time rendering, smart space planning, and AR/VR-based interactive experiences. The growing trend of remote work and hybrid office models is also creating a demand for innovative design software that facilitates virtual space planning and workplace optimization. Additionally, the increasing preference for subscription-based models is making high-end design tools more accessible to independent designers and small firms, further expanding the market’s potential.
The shift toward sustainable and eco-friendly interior design solutions is another key area of opportunity. As regulatory policies and consumer preferences push for greener construction and renovation practices, there is a growing need for software that can integrate energy-efficient layouts, sustainable material selection, and LEED-compliant design principles. The market is also witnessing rising interest from real estate developers and furniture manufacturers who seek to integrate interior design software with smart home automation and IoT-based solutions. With advancements in AI, big data analytics, and cloud computing, the U.S. interior design software market is well-positioned for expansion, offering lucrative opportunities for technology providers to innovate and capture a larger share of the growing demand for intelligent, efficient, and sustainable design solutions.
Market Segmentation Analysis:
The U.S. interior design software market is segmented based on features, application, end-user, pricing model, and deployment model, reflecting diverse user needs and industry trends.
By Features, the market includes 3D view, collaboration tools, and virtual tour functionalities, enhancing design accuracy and client engagement. 3D view enables realistic visualization, while collaboration tools support remote teamwork and project coordination. Virtual tour capabilities allow designers and clients to experience immersive walkthroughs, improving decision-making and reducing design revisions.
By Application, the software is widely used for floor plan creation, furniture and fixture designing, real-time 3D modeling, space planning, and visualization. Floor plan creation and space planning are essential for architects and interior designers to develop efficient layouts, while real-time 3D modeling and visualization enhance design presentation and customization.
By End-User, the market serves both residential and non-residential sectors. The residential sector benefits from increased home renovation projects and smart home integrations, while the non-residential sector, including commercial offices, hotels, and retail spaces, drives demand for large-scale, high-efficiency design solutions.
By Pricing Model, the industry is divided into perpetual licensing and subscription-based models. Subscription-based solutions are gaining popularity due to lower upfront costs, frequent updates, and cloud accessibility, whereas perpetual licensing remains preferred by firms seeking long-term investments without recurring fees.
By Deployment Model, the market is split between cloud-based and on-premises solutions. Cloud-based software dominates, offering remote accessibility and real-time collaboration, while on-premises solutions cater to firms requiring higher data security and offline functionality.
Segmentation:
By Features
- 3D View
- Collaboration Tools
- Virtual Tour
By Application
- Floor Plan Creation
- Furniture And Fixture Designing
- Real-Time 3D Modeling
- Space Planning
- Visualization
By End-user
- Residential Sector
- Non-Residential Sector
By Pricing Model
- Perpetual Licensing
- Subscription-Based
By Deployment Model
- Cloud-Based
- On-Premises
Regional Analysis:
The U.S. interior design software market exhibits diverse growth dynamics across different regions, with major metropolitan areas and states leading the adoption of advanced design technologies. The market is primarily segmented into the Northeast, West, Midwest, and South, each contributing to the industry’s overall expansion based on unique economic and real estate trends.
Northeast: High Concentration of Architectural and Design Firms
The Northeast region accounts for approximately 30% of the U.S. interior design software market, driven by the high concentration of architectural firms, real estate developers, and commercial interior design projects. States such as New York, Massachusetts, and Pennsylvania play a significant role in market expansion due to the demand for high-end interior design solutions in luxury residential apartments, office spaces, and hospitality projects. The presence of leading design schools and institutions in the region has also contributed to the early adoption of AI-powered and 3D rendering technologies, making this market highly competitive and innovation-driven.
West: Leading in Smart Homes and Sustainable Design
The Western region, particularly states such as California, Washington, and Oregon, holds around 28% of the market share, benefiting from the growing demand for smart home integrations, sustainable design practices, and technology-driven interiors. The increasing number of tech-driven startups and real estate projects focusing on eco-friendly and energy-efficient designs has fueled software adoption. California, in particular, leads in the implementation of AR/VR-enabled design solutions and cloud-based collaboration tools, as firms seek more flexible and innovative ways to plan and execute interior projects. The region’s booming commercial sector, including tech campuses and corporate offices, further strengthens the demand for real-time design visualization and AI-powered automation.
Midwest: Rising Adoption in Commercial and Residential Sectors
The Midwest region contributes 20% to the U.S. interior design software market, with Illinois, Ohio, and Michigan emerging as key states driving adoption. The region is experiencing rapid urbanization and commercial development, particularly in cities like Chicago, Detroit, and Columbus, where modern office spaces and residential renovations are on the rise. The growing presence of small and mid-sized design firms adopting cloud-based and subscription-driven software models has further propelled market growth. Additionally, the affordable housing market in the Midwest is driving demand for software solutions that cater to cost-effective, functional, and aesthetic interior designs, making the region a growing hub for emerging design technologies.
South: Strong Growth in Residential and Hospitality Sectors
The Southern region holds approximately 22% of the market share, with states like Texas, Florida, and Georgia driving expansion. The region is witnessing a boom in residential construction, luxury housing, and hospitality projects, contributing to the rising adoption of 3D modeling and real-time visualization tools. The hospitality industry in Florida and Texas, fueled by tourism and commercial expansion, has increased the demand for software solutions catering to hotel interiors, resort designs, and luxury real estate. Additionally, the cost-effectiveness of cloud-based interior design software is encouraging smaller firms in the South to leverage advanced design tools, further expanding market opportunities.
Key Player Analysis:
- Ashampoo 3D CAD
- Autodesk
- Cedreo
- Chief Architect
- Coohom
- DecoSoftware
- Floorplanner
- Home Designer Suite
- HomeByMe ‘
- Company 11
- Company 12
- Company 13
- Company 14
Competitive Analysis:
The U.S. interior design software market is highly competitive, with a mix of established software providers, emerging tech firms, and niche players offering specialized solutions. Industry leaders such as Autodesk Inc., Dassault Systèmes, Trimble Inc., and Chief Architect Inc. dominate the market with comprehensive design tools, AI-driven automation, and cloud-based collaboration features. These companies continuously invest in innovation, AR/VR integration, and AI-powered design recommendations to enhance user experience and maintain their competitive edge. Emerging players and startups are focusing on subscription-based, cost-effective solutions to attract small and mid-sized design firms. For instance, Autodesk Inc. provides a diverse portfolio of software solutions, including AutoCAD, Revit, Maya, 3ds Max, Fusion 360, and BIM 360, catering to various sectors such as architecture, engineering, construction, and media and entertainment. The market is witnessing an increasing shift toward cloud-based platforms, enabling remote project management and real-time collaboration. Additionally, strategic partnerships between software developers and real estate firms are expanding market reach. As competition intensifies, companies are differentiating through customization, sustainability-focused features, and seamless integration with smart home technologies to capture a larger market share.
Recent Developments:
- In November 2024, Siemens made a significant move by acquiring Altair Engineering Inc. for $10.6 billion. This strategic acquisition aims to strengthen Siemens' digital twin portfolio while advancing their sustainability tools and AI capabilities. The deal brings together Altair's extensive portfolio in simulation, data science, and HPC with Siemens' strong position in mechanical and EDA design.
- In March 2024, Autodesk launched their AEC 2025 product line, introducing significant improvements to AutoCAD, Revit, and Civil 3D. The release features deeper integration with Autodesk Construction Cloud, new markup import functionality, and integration of ArcGIS Basemaps for enhanced geographical information
- In MAy 2024, Floorplanner acquired ARspar technologies, an AI photo editing platform. This strategic acquisition aims to enhance Floorplanner's visual capabilities by integrating ARspar's AI-driven photo editing technology into their space planning tools.
Market Concentration & Characteristics:
The U.S. interior design software market is moderately concentrated, with a few dominant players accounting for a significant market share, while smaller firms and startups continue to expand their presence. Leading companies such as Autodesk Inc., Dassault Systèmes, and Trimble Inc. leverage advanced AI-driven automation, cloud-based collaboration, and 3D visualization tools to maintain their competitive edge. Mid-sized firms and emerging players are increasingly focusing on subscription-based pricing models and user-friendly interfaces to attract independent designers and small businesses. Key market characteristics include a strong emphasis on innovation, integration with AR/VR technologies, and the rising adoption of AI-powered design recommendations. The shift toward cloud-based solutions and mobile-friendly platforms is reshaping industry dynamics, allowing greater flexibility and real-time collaboration. Additionally, the growing preference for sustainability-focused design tools and smart home integrations is influencing software development trends, making the market highly dynamic and technology-driven.
Report Coverage:
The research report offers an in-depth analysis based on By Features, By Application, By End-user, By Pricing Model and By Deployment Model. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- AI-driven automation will enhance design accuracy, reducing manual efforts and optimizing space planning through predictive analytics.
- AR/VR adoption will continue expanding, allowing immersive virtual walkthroughs and real-time client collaboration.
- Cloud-based platforms will dominate, enabling seamless remote project management and multi-device accessibility.
- Sustainability-focused tools will gain traction, integrating eco-friendly material recommendations and energy-efficient design solutions.
- Subscription-based pricing models will increase accessibility for small firms and independent designers, driving market penetration.
- Integration with smart home technology will grow, enabling seamless connectivity with IoT-based lighting, security, and automation systems.
- Customization and modular design solutions will be in high demand, catering to personalized residential and commercial projects.
- Data security and compliance will become a priority, with cloud-based software enhancing encryption and regulatory adherence.
- Cross-platform compatibility will improve, ensuring smooth interoperability with BIM, ERP, and construction management tools.
- Expansion of AI-powered design assistants will streamline workflows, reducing project timelines and improving efficiency.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the U.S. Interior Design Software Market?
What factors are driving the growth of the U.S. Interior Design Software Market?
What are the key segments within the U.S. Interior Design Software Market?
Who are the major players in the U.S. Interior Design Software Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 U.S. Interior design software Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2023; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global U.S. Interior design software Market Snapshot
- 2.1.1 Market Size – Historical (2023) & Forecast (2023-2032) (2023: USD 1,901.07 million → 2032: USD 5,232.63 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 U.S. Interior design software Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2023 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2023
- 2.3.2 Top 10 Players by Volume Share – 2023
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. U.S. Interior design software Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 U.S. Interior design software Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 U.S. Interior design software Market Drivers
- 3.3 U.S. Interior design software Market Restraints & Challenges
- 3.4 U.S. Interior design software Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 U.S. Interior design software Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 U.S. Interior design software Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, U.S. Interior design software category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 U.S. Interior design software Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. U.S. Interior design software Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2023)
- 5.1.2 Global Export Volume by Country (2023)
- 5.1.3 Global Import Value by Country (2023)
- 5.1.4 Global Import Volume by Country (2023)
- 5.1.5 Net Trade Balance by Country (2023)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2023)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the U.S. Interior design software market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 U.S. Interior design software Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2023
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 U.S. Interior design software Market Share Analysis – 2023
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2023)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 U.S. Interior design software Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in U.S. Interior design software (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New U.S. Interior design software Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global U.S. Interior design software Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2023 & 2032)
- 7.1.2 Channel Mix Evolution (2023-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America U.S. Interior design software Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe U.S. Interior design software Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific U.S. Interior design software Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America U.S. Interior design software Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East U.S. Interior design software Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa U.S. Interior design software Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. U.S. Interior design software Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
