
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
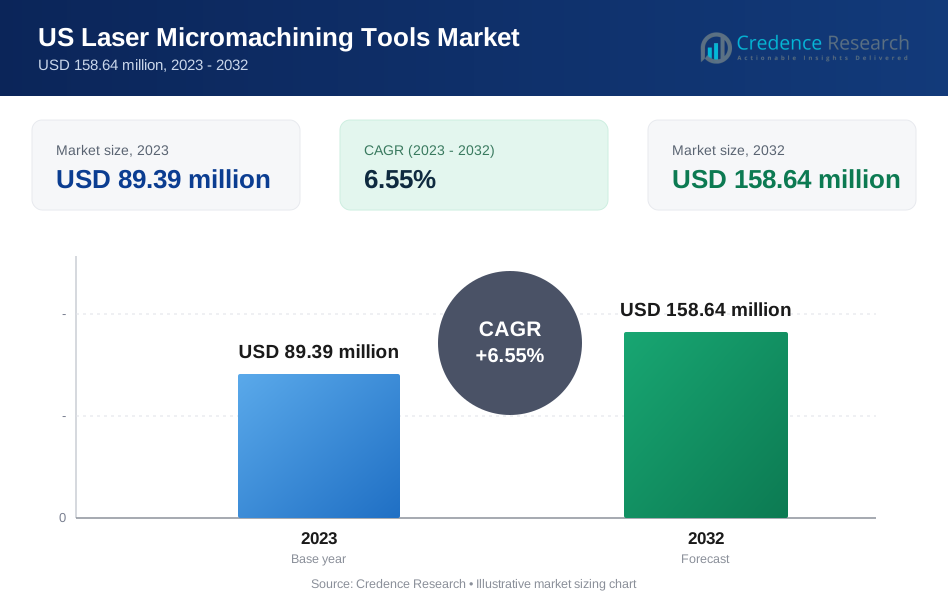
| US Laser Micromachining Tools Market Size 2023 | USD 89.39 Million |
| US Laser Micromachining Tools Market, CAGR | 6.55% |
| US Laser Micromachining Tools Market Size 2032 | USD 158.64 Million |
Market Overview
The US Laser Micromachining Tools Market is projected to grow from USD 89.39 million in 2023 to an estimated USD 158.64 million by 2032, with a compound annual growth rate (CAGR) of 6.55% from 2024 to 2032. This growth is driven by increasing demand for precision manufacturing in sectors such as electronics, medical devices, and automotive, where laser micromachining tools are essential for high-precision cutting, drilling, and engraving.
Key drivers of the market include the rising adoption of miniaturized components, the need for high-precision manufacturing, and the increasing use of laser technology in microfabrication. Trends such as the development of ultrafast lasers and the integration of laser micromachining with other manufacturing processes are enhancing the capabilities and efficiency of these tools, making them indispensable in high-tech industries.
Geographically, the market is concentrated in regions with a strong presence of high-tech manufacturing industries, such as the Midwest and West Coast. Key players in the US market include Meera Lasers (India), LAP Laser, SIL Lasers (India), Makino (Japan), Nippon Laser & Electronics Laboratory Inc., Lasertech Co., Ltd., Epilog Laser, Optron Inc., AccuLaser Technology Co., Ltd., GSI Group, and United Laser. These companies are focusing on technological innovations and strategic partnerships to maintain their competitive edge in the market.
Market Drivers
Growing Demand for Precision Manufacturing
The US laser micromachining tools market is experiencing significant growth due to the rising demand for precision manufacturing across various industries. Sectors such as electronics, medical devices, and automotive increasingly require high-precision components, which laser micromachining tools can produce with unparalleled accuracy. For instance, the US Census Bureau reported that manufacturers' new orders for ferrous metal foundries grew by 4.1% year-over-year (YOY) in October, leading new orders growth in the Primary Metals category. These tools allow manufacturers to achieve intricate designs and fine tolerances that are essential for modern electronic devices, including smartphones, tablets, and wearable technology. Additionally, the medical device industry relies on laser micromachining for the production of components like stents, catheters, and microfluidic devices, where precision and reliability are paramount. As the trend toward miniaturization and complex design continues, the demand for laser micromachining tools is expected to grow, fueling the market's expansion.
Technological Advancements in Laser Micromachining
Technological advancements are a critical driver of the US laser micromachining tools market. Innovations in laser technology, such as the development of ultrafast lasers and fiber lasers, have significantly enhanced the capabilities of micromachining tools. For instance, ultrafast lasers offer extremely short pulse durations, allowing for precise material removal with minimal thermal damage. This is particularly important in applications where the integrity of the surrounding material is critical. According to a review by Nature, ultrafast lasers have become a ubiquitous micromachining tool for various materials, including metals, semiconductors, ceramics, glass, and polymers. Additionally, advancements in software and control systems have improved the accuracy and efficiency of laser micromachining processes, enabling manufacturers to achieve higher throughput and better product quality. As these technologies continue to evolve, they are expected to open new applications and drive further adoption of laser micromachining tools.
Increasing Use of Laser Micromachining in Diverse Applications
The versatility of laser micromachining tools is another key driver of market growth. These tools are capable of working with a wide range of materials, including metals, ceramics, polymers, and semiconductors, making them suitable for diverse applications. For instance, in the automotive industry, laser micromachining is used for the precise cutting and drilling of engine components and sensors. In the aerospace sector, it is employed for creating lightweight structures and high-performance components. The growing adoption of laser micromachining in industries such as jewelry and fashion for engraving and cutting also contributes to market expansion. Furthermore, the rise of additive manufacturing technologies, where laser micromachining is used for post-processing and finishing, is expected to create additional opportunities for market growth. According to the International Federation of Robotics, the demand for service sector robots grew by 37% in 2021 worldwide, highlighting the increasing need for precision components produced by laser micromachining tools.
Increasing Investments in Manufacturing Automation
Investments in manufacturing automation are significantly driving the growth of the US laser micromachining tools market. As industries seek to improve productivity, reduce costs, and maintain high quality, there is a growing trend toward automating manufacturing processes. Laser micromachining tools are well-suited for automation due to their precision, repeatability, and ability to be integrated into automated production lines. Automation not only enhances the efficiency of micromachining processes but also reduces human error and ensures consistent product quality. Additionally, the integration of Industry 4.0 technologies, such as IoT and AI, with laser micromachining systems enables real-time monitoring and optimization of production processes. This trend toward increased automation is expected to drive the adoption of laser micromachining tools, particularly in high-tech industries where precision and efficiency are critical.
Market Trends
Adoption of Ultrafast Laser Technology
One of the most significant trends in the US laser micromachining tools market is the growing adoption of ultrafast laser technology. Ultrafast lasers, including femtosecond and picosecond lasers, are gaining traction due to their ability to deliver extremely short pulses of light. For instance, according to a report by BIS Research, the ultrafast laser technology market in North America is projected to grow significantly, driven by the increasing demand for high-precision manufacturing techniques used in biomedical applications and high-speed data transmission. This technology enables high-precision material processing with minimal thermal damage, which is crucial in applications requiring intricate and delicate features, such as in the semiconductor, electronics, and medical device industries. The use of ultrafast lasers allows for cleaner cuts and improved surface finishes, enhancing the overall quality of the micromachined components. As manufacturers increasingly prioritize precision and quality, the demand for ultrafast laser technology is expected to continue rising, driving market growth. Additionally, the National Institute of Standards and Technology (NIST) highlights that federal investments in new technologies have been crucial to the birth and growth of major new industries, reinforcing the demand for advanced laser micromachining tools.
Integration with Automation and Industry 4.0 Technologies
Another key trend in the US laser micromachining tools market is the integration of these tools with automation systems and Industry 4.0 technologies. Manufacturers are increasingly adopting automation to enhance productivity, reduce operational costs, and maintain consistent quality. For instance, the International Federation of Robotics reported a 37% growth in the demand for service sector robots in 2021, with projections for continued strong market growth. Laser micromachining tools are well-suited for automated environments due to their precision, reliability, and ease of integration. Moreover, the incorporation of Industry 4.0 technologies, such as the Internet of Things (IoT) and artificial intelligence (AI), enables real-time monitoring, predictive maintenance, and process optimization. These advancements facilitate more efficient production processes and reduce downtime, which is critical in high-volume manufacturing sectors. The trend towards smart manufacturing and digitalization is expected to further boost the adoption of laser micromachining tools, positioning them as essential components in modern production systems. According to a report by Baison Laser, IoT and AI are transforming the laser cutting industry by enabling real-time data acquisition, predictive maintenance, and optimization of cutting parameters, thereby enhancing the efficiency and productivity of manufacturing processes.
Market Restraints and Challenges
High Initial Costs and Technological Complexity
One of the primary restraints in the US laser micromachining tools market is the high initial cost associated with purchasing and implementing these advanced systems. The technology used in laser micromachining tools, especially those incorporating ultrafast lasers, requires significant investment in high-quality laser sources, precision optics, and control systems. For instance, according to a report by the National Institute of Standards and Technology (NIST), federal investments in new technologies and shared infrastructure have been crucial in supporting the growth of high-tech manufacturing sectors, but the substantial initial investment remains a barrier for many small and medium-sized enterprises (SMEs). Additionally, the complexity of the technology necessitates skilled operators and maintenance personnel, which can further increase operational costs. The need for specialized training and the potential for increased downtime due to maintenance or technical issues can also pose challenges, particularly for companies with limited technical expertise. These factors collectively act as restraints, potentially slowing the widespread adoption of laser micromachining tools.
Competition from Alternative Micromachining Technologies
Another challenge facing the US laser micromachining tools market is competition from alternative micromachining technologies. While laser micromachining offers distinct advantages in terms of precision and material versatility, other technologies such as electrical discharge machining (EDM), chemical etching, and mechanical micromachining also provide high-precision capabilities. For instance, EDM is particularly effective for hard metals and can produce complex geometries that may be challenging for laser micromachining. According to a survey by the Association for Manufacturing Technology (AMT), many manufacturers continue to rely on EDM due to its cost-effectiveness and suitability for specific applications. Furthermore, as these alternative technologies continue to advance and improve in terms of precision and efficiency, they may pose an increasing competitive threat to the laser micromachining market. Companies must therefore continually innovate and demonstrate the unique value proposition of laser micromachining to differentiate themselves and maintain a competitive edge in the market.
Market Segmentation Analysis
By Process
The US laser micromachining tools market is segmented by process into additive and subtractive techniques. Subtractive micromachining, which involves removing material to create intricate patterns and features, dominates the market. This process is widely used in industries requiring precision components, such as electronics and medical devices. For instance, according to a survey by the National Institute of Standards and Technology (NIST), subtractive manufacturing processes are preferred for their ability to provide fine surface finishes and high-speed material processing, enhancing overall manufacturing efficiency. Additive processes, while currently less prevalent, are gaining traction as they offer unique advantages in rapid prototyping and complex geometries, especially in the aerospace and defense sectors. The increasing interest in additive manufacturing techniques is expected to drive growth in this segment. A report by the U.S. Department of Defense highlights the growing adoption of additive manufacturing for producing lightweight and complex components in defense applications, which further supports this trend.
By Application
The application segment of the US laser micromachining tools market includes drilling, cutting & milling, marking & engraving, texturing & patterning, and other specialized applications. Drilling and cutting & milling represent the largest share due to their critical role in manufacturing components with precise dimensions and shapes. These applications are particularly important in the electronics and automotive industries, where exact specifications are crucial. For instance, a study by the Consumer Technology Association (CTA) indicates that the demand for precision drilling and cutting tools is driven by the miniaturization of electronic components and the need for high-precision manufacturing in the automotive sector. Marking & engraving is also a significant segment, widely used for labeling and branding in various industries. The texturing & patterning segment is growing, driven by the demand for aesthetic enhancements and functional surface modifications in consumer electronics and medical devices. According to a survey by the Medical Device Manufacturers Association (MDMA), the use of laser texturing and patterning in medical devices has increased by 20% over the past three years, highlighting the growing importance of these applications in the medical field.
Segments
Based on Process
- Additive Micromachining
- Subtractive Micromachining
Based on Application
- Drilling
- Cutting & Milling
- Marking & Engraving
- Texturing & Patterning
- Others
Based on End User
- Automotive
- Aerospace and Defense
- Medical and Pharmaceuticals
- Electronic Products
- Others
Based on Region
- West Coast
- Midwest
- Northeast
- South
Regional Analysis
West Coast (35%)
The West Coast, particularly California, dominates the US laser micromachining tools market, holding an estimated 35% market share. This region is a global hub for technology and innovation, home to Silicon Valley and numerous high-tech companies specializing in electronics, semiconductors, and biotechnology. For instance, California's strong aerospace and defense industry also contributes significantly, utilizing these tools for precision manufacturing and microfabrication. According to the National Science Foundation (NSF), California received substantial funding for advanced manufacturing research, which has driven innovation and the adoption of cutting-edge technologies in the region. The presence of major technology firms, coupled with a robust infrastructure for research and development, drives the demand for advanced laser micromachining tools. The region's focus on innovation and cutting-edge technologies continues to bolster its leadership position in the market.
Northeast (20%)
The Northeast region accounts for about 20% of the US laser micromachining tools market. This area is characterized by a strong presence of medical device manufacturers, academic institutions, and research laboratories, particularly in states like Massachusetts and New York. For instance, the medical and pharmaceutical industries in the Northeast extensively use laser micromachining tools for developing and manufacturing intricate medical devices. According to the National Institutes of Health (NIH), significant investments in biomedical research have been made in this region, fostering advancements in medical technology and the adoption of precision tools. Additionally, the region's proximity to financial and corporate headquarters fosters investments in high-tech equipment and advanced manufacturing technologies, supporting market growth. The Northeast's focus on research and development, along with a supportive regulatory environment, encourages the adoption of cutting-edge technologies like laser micromachining.
Key players
- IPG Photonics (U.S.)
- MKS Instruments, Inc. (U.S.)
- Coherent Inc. (U.S.)
- Trumpf Inc.
- Spectra-Physics (a division of MKS Instruments)
- Laserline Inc.
- Epilog Laser
Competitive Analysis
The US laser micromachining tools market is characterized by the presence of key players like IPG Photonics, MKS Instruments (including its division Spectra-Physics), Coherent Inc., Trumpf Inc., Laserline Inc., and Epilog Laser. These companies dominate the market through their advanced laser technologies and comprehensive product portfolios. IPG Photonics and Coherent Inc. lead with their cutting-edge fiber laser solutions, offering high precision and efficiency. MKS Instruments and its Spectra-Physics division provide a wide range of photonics solutions, while Trumpf Inc. is renowned for its innovative machine tools and laser technology. Laserline Inc. specializes in diode lasers, and Epilog Laser is known for its robust and versatile laser engraving and cutting systems. These companies compete on technological innovation, product quality, and customer service, striving to enhance their market share and meet the evolving demands of precision manufacturing industries.
Recent Developments
- In May 2024, IPG Photonics (U.S.) launched the LightWELD® 2000 XR, an improved version of their handheld laser welder and cleaner, offering higher power and greater productivity. In May 2024, introduced a new Cobot Laser Welding System aimed at automating repetitive steps to improve productivity and reduce operating costs. In June 2024, Developed a new laser technology designed to improve the silicon wafer heating process for semiconductor manufacturer.
- In March 2024, Coherent, along with Juniper Networks and Marvell, delivered a public demonstration of an industry-first comprehensive 800ZR system at OFC24, showcasing advancements in optical connections.
- In June 2024, Trumpf Inc. announced the U.S. debut of their new Flex Cell bending automation solution at FABTECH 2024. While not directly related to tablet counting, this showcases Trumpf's ongoing innovations in automation and manufacturing technologies.
- In June 2024, Laserline will be presenting on "Innovative Automotive Applications with Visible and Infrared High Power Diode Lasers" at the Advanced Laser Applications Workshop (ALAW) 2024.
- In April 2023, Epilog Laser expanded its Fusion Maker Laser Series by introducing the Fusion Maker 24 and 36 models, featuring larger work areas and higher wattages of lasers. In January 2023, Launched the Fusion Galvo G100 Laser System, enabling users to produce various marks on metal quickly and efficiently.
Market Concentration and Characteristics
The US laser micromachining tools market exhibits a moderate to high level of market concentration, with a few key players dominating the industry. Companies such as IPG Photonics, Coherent Inc., MKS Instruments, and Trumpf Inc. hold significant market shares due to their advanced technological capabilities, extensive product portfolios, and strong customer bases. These leading firms are characterized by their continuous innovation in laser technology, focusing on enhancing precision, efficiency, and versatility in micromachining applications. The market is also marked by high barriers to entry, including substantial initial investment costs and the need for specialized technical expertise. This concentration allows major players to leverage economies of scale and invest in research and development, further solidifying their positions in the market and shaping the competitive landscape.
Report Coverage
The research report offers an in-depth analysis based on Process, Application, End User and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will see ongoing innovations in ultrafast lasers and fiber lasers, enhancing precision and efficiency in micromachining applications.
- Increasing demand for miniaturized components in electronics and medical devices will drive the adoption of advanced laser micromachining tools.
- The medical and pharmaceutical sectors will continue to leverage laser micromachining for producing intricate and precise medical devices and instruments.
- Enhanced integration of laser micromachining tools with automation and Industry 4.0 technologies will improve productivity and process optimization.
- Key players will invest more in research and development to innovate and maintain their competitive edge in the market.
- Emerging industries such as wearable technology and electric vehicles will create new opportunities for laser micromachining applications.
- Growing emphasis on environmentally friendly manufacturing processes will boost the demand for laser micromachining tools that minimize waste and energy consumption.
- Advances in software and control systems will improve the accuracy, speed, and user-friendliness of laser micromachining tools.
- Increasing demand for customized solutions will drive the development of more versatile and flexible laser micromachining tools.
- While the West Coast will remain a leading hub, other regions like the South and Midwest will see significant growth due to rising industrial activities and investments in technology.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth of the US Laser Micromachining Tools Market?
What are the key drivers of market growth?
Which industries primarily use laser micromachining tools?
What technological trends are influencing the market?
Who are the major players in the US Laser Micromachining Tools Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 US Laser Micromachining Tools Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2023; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global US Laser Micromachining Tools Market Snapshot
- 2.1.1 Market Size – Historical (2023) & Forecast (2023-2032) (2023: USD 89.39 million → 2032: USD 158.64 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 US Laser Micromachining Tools Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2023 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2023
- 2.3.2 Top 10 Players by Volume Share – 2023
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. US Laser Micromachining Tools Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 US Laser Micromachining Tools Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 US Laser Micromachining Tools Market Drivers
- 3.3 US Laser Micromachining Tools Market Restraints & Challenges
- 3.4 US Laser Micromachining Tools Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 US Laser Micromachining Tools Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 US Laser Micromachining Tools Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, US Laser Micromachining Tools category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 US Laser Micromachining Tools Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. US Laser Micromachining Tools Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2023)
- 5.1.2 Global Export Volume by Country (2023)
- 5.1.3 Global Import Value by Country (2023)
- 5.1.4 Global Import Volume by Country (2023)
- 5.1.5 Net Trade Balance by Country (2023)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2023)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the US Laser Micromachining Tools market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 US Laser Micromachining Tools Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2023
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 US Laser Micromachining Tools Market Share Analysis – 2023
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2023)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 US Laser Micromachining Tools Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in US Laser Micromachining Tools (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New US Laser Micromachining Tools Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global US Laser Micromachining Tools Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2023 & 2032)
- 7.1.2 Channel Mix Evolution (2023-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America US Laser Micromachining Tools Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe US Laser Micromachining Tools Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific US Laser Micromachining Tools Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America US Laser Micromachining Tools Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East US Laser Micromachining Tools Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa US Laser Micromachining Tools Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. US Laser Micromachining Tools Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
