
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| U.S. Military Aircraft Modernization Market Size 2023 | USD 14,810.83 Million |
| U.S. Military Aircraft Modernization Market, CAGR | 7.60% |
| U.S. Military Aircraft Modernization Market Size 2032 | USD 26,602.75 Million |
Market Overview
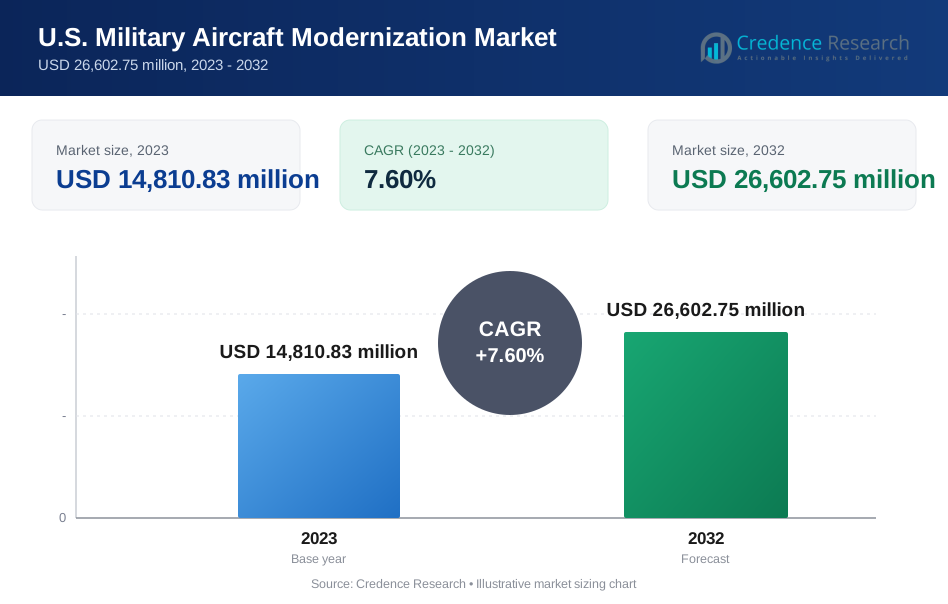
The U.S. Military Aircraft Modernization Market is projected to grow from USD 14,810.83 million in 2023 to USD 26,602.75 million by 2032, at a compound annual growth rate (CAGR) of 7.60%.
The U.S. military aircraft modernization market is driven by the increasing need to enhance the performance and capabilities of existing aircraft amid rising defense budgets. Technological advancements in avionics, materials, and propulsion systems are boosting the modernization efforts to improve efficiency, combat readiness, and operational flexibility. Additionally, the growing focus on maintaining technological superiority and countering evolving threats is pushing the U.S. military to invest in upgrading its fleet. The demand for upgraded aircraft with advanced stealth capabilities, enhanced sensors, and improved weapon systems is also a significant factor contributing to the market growth. Furthermore, government initiatives aimed at extending the lifecycle of military aircraft through retrofitting and modernization are expected to drive further market expansion. With a focus on sustainability and cost-effectiveness, the U.S. military's modernization strategies are shaping the future of the defense industry and supporting market growth.
The U.S. military aircraft modernization market is influenced by key players located across various regions of the country. Major defense contractors such as Lockheed Martin, Boeing, Northrop Grumman, and Raytheon Technologies play a central role in driving modernization efforts through technological advancements and system upgrades. These companies are concentrated in regions like the Western and Midwestern United States, where significant defense manufacturing and R&D activities take place. Other notable players include General Dynamics, L3Harris Technologies, and Honeywell International, which contribute through specialized components like avionics, propulsion systems, and weaponry. The Southern U.S., with military bases like Eglin Air Force Base and Naval Air Station Pensacola, supports modernization with a focus on training, testing, and specialized mission aircraft. The Northeast also plays a key role, particularly in cybersecurity and electronic warfare innovations. This diverse geographical presence ensures that modernization efforts remain robust and efficient across various defense sectors.
Market Insights
- The U.S. military aircraft modernization market is expected to grow from USD 14,810.83 million in 2023 to USD 26,602.75 million by 2032, with a CAGR of 7.60%.
- Increasing defense budgets and rising national security concerns are key drivers, fueling demand for advanced military aircraft modernization.
- Technological advancements in avionics, AI, and stealth capabilities are leading modernization trends in military aircraft.
- The market faces challenges such as high costs and integration issues with older aircraft platforms.
- Key players like Lockheed Martin, Boeing, Northrop Grumman, and Raytheon Technologies dominate the market, focusing on innovation and system upgrades.
- Regional strengths include the Western U.S. (technology and R&D), the Midwestern U.S. (military bases), and the Southern U.S. (specialized mission aircraft modernization).
- Economic factors and government regulations could impact modernization efforts and defense spending in the coming years.
Market Drivers
Technological Advancements in Aircraft Systems
The continuous evolution of aircraft technologies plays a pivotal role in driving the U.S. military aircraft modernization market. Advancements in avionics, propulsion systems, materials, and weaponry are essential for ensuring that military aircraft can meet current and future operational demands. Modernization efforts focus on integrating state-of-the-art systems such as advanced radar, communication networks, and enhanced sensor capabilities, enabling aircraft to operate more efficiently and effectively in diverse combat environments. For instance, the U.S. Air Force has integrated advanced radar systems like the AN/APG-81 AESA radar in the F-35 Lightning II, enhancing its target detection and tracking capabilities. These technological upgrades help the U.S. military maintain a competitive edge in air superiority.
Rising Defense Budgets and National Security Concerns
Increased defense budgets in the U.S. are directly fueling the demand for aircraft modernization. With a growing focus on national security and preparedness against emerging threats, the U.S. government is committed to strengthening its military capabilities. For instance, the National Defense Authorization Act (NDAA) for 2025 includes provisions for the procurement of 75 new aircraft for the U.S. Navy and Marines, highlighting the government's commitment to maintaining a modern and capable fleet. Modernizing existing aircraft is a cost-effective strategy compared to acquiring entirely new fleets, providing a balanced approach to defense spending while enhancing the operational readiness of the military. As global security challenges evolve, there is a heightened need to upgrade aircraft to counter potential adversaries' technological advancements.
Long Lifecycle and Sustainment of Military Aircraft
The long operational lifespan of military aircraft drives the demand for regular modernization. Many U.S. military aircraft were designed decades ago but remain crucial to military operations. Modernization programs extend the lifespan of these aircraft by retrofitting them with new systems and technologies, which reduces the need for costly replacements. This lifecycle sustainment strategy is not only cost-effective but also ensures that the U.S. military maintains a reliable and capable fleet, even as individual aircraft age.
Geopolitical Tensions and Evolving Threats
Ongoing geopolitical tensions and the rise of new security threats are key drivers for the modernization of U.S. military aircraft. The military needs to stay ahead of evolving adversaries with the latest capabilities, including stealth technology, advanced weaponry, and enhanced countermeasures. As the global security landscape becomes more complex, the U.S. military must ensure that its aircraft are capable of addressing a wide range of threats, from near-peer adversaries to asymmetric warfare challenges. Modernization efforts allow the U.S. to adapt its fleet to these changing strategic requirements.
Market Trends
Integration of Advanced Avionics and AI Systems
A key trend in U.S. military aircraft modernization is the integration of advanced avionics and artificial intelligence (AI) systems. The incorporation of AI enables aircraft to process data more efficiently, making real-time decision-making and autonomous operations a reality. Advanced avionics systems improve navigation, communication, and mission effectiveness by providing pilots with enhanced situational awareness. For instance, the U.S. Air Force has integrated AI algorithms to assist in navigation and radar operations, as demonstrated by the ARTUµ AI algorithm used in the Lockheed Martin U-2 reconnaissance aircraft. This trend reflects a broader push for smarter, more capable aircraft that can respond dynamically to evolving combat environments, further enhancing the U.S. military’s operational capabilities.
Stealth and Countermeasure Enhancements
As global military threats evolve, enhancing stealth capabilities remains a prominent trend in U.S. military aircraft modernization. Stealth technology enables aircraft to evade detection, providing a strategic advantage in high-risk combat zones. In addition to stealth, the integration of advanced countermeasures such as electronic warfare systems is becoming increasingly vital. These countermeasures help aircraft avoid enemy radar and missile systems, ensuring the survival of military assets in hostile environments. The combination of stealth enhancements and countermeasure technologies is essential for maintaining the U.S. military’s air dominance.
Sustainability and Environmental Considerations
Another growing trend in U.S. military aircraft modernization is the focus on sustainability and environmental impact. The U.S. military is working to reduce the carbon footprint of its aircraft by adopting more fuel-efficient technologies and eco-friendly materials. Modernizing older aircraft with energy-efficient engines and lighter composite materials reduces fuel consumption and operational costs while aligning with environmental goals. These sustainability efforts contribute to the broader military strategy of maintaining readiness while being mindful of long-term environmental impacts.
Lifecycle Management and Retrofitting Strategies
The trend toward extending the lifespan of military aircraft through lifecycle management and retrofitting is gaining momentum. Retrofitting older aircraft with new systems and technologies is more cost-effective than purchasing new fleets, making it a preferred approach for the U.S. military. Modernization programs focus on upgrading key components such as propulsion systems, avionics, and weaponry, ensuring that aging aircraft remain relevant and effective. This trend not only helps optimize the existing fleet but also enables the military to respond swiftly to emerging threats without the delay associated with procuring new aircraft.
Market Challenges Analysis
High Costs of Modernization Programs
One of the primary challenges in U.S. military aircraft modernization is the significant financial investment required. Modernizing existing aircraft with advanced technologies, such as new avionics, propulsion systems, and weaponry, entails substantial upfront costs. Additionally, ongoing maintenance and upgrades can further strain defense budgets, especially as the number of aircraft in need of modernization increases. For instance, the modernization of the B-52 bomber has incurred costs of over $8.6 billion, highlighting the substantial financial commitment required for such programs. While these upgrades are more cost-effective than purchasing entirely new fleets, the financial burden remains a challenge for military planners who must balance modernization with other defense priorities. Budget constraints and the pressure to optimize spending in a complex global security environment make it challenging to fund modernization programs without compromising other areas of defense.
Integration and Compatibility Issues
Another challenge faced in U.S. military aircraft modernization is the integration and compatibility of new systems with older platforms. Aircraft designed decades ago may not easily accommodate cutting-edge technologies, leading to potential compatibility issues. Retrofitting these systems often requires significant engineering and modification efforts, which can extend the time and cost of modernization programs. Additionally, maintaining interoperability between modernized aircraft and newer systems across the military’s fleet is crucial for joint operations, and any technological gaps can hinder mission effectiveness. Overcoming these integration challenges requires advanced technical expertise and precise planning to ensure that all systems work seamlessly, maintaining operational efficiency while modernizing the fleet.
Market Opportunities
Expanding Role of Artificial Intelligence and Automation
The growing incorporation of artificial intelligence (AI) and automation presents significant opportunities for the U.S. military aircraft modernization market. AI technologies can enhance operational efficiency by enabling smarter decision-making, improving data analysis, and enhancing autonomous flight capabilities. AI-driven systems are particularly valuable for mission-critical tasks, such as real-time threat detection and tactical response, making them indispensable in modern warfare. Additionally, automation can streamline maintenance procedures, predict system failures, and reduce human error, leading to improved aircraft availability and mission success. As AI and automation technologies continue to advance, their integration into existing and future aircraft fleets offers substantial growth potential in the modernization sector.
Growth in Sustainability and Green Technologies
Another key opportunity lies in the growing emphasis on sustainability and environmental consciousness in the U.S. military. As the military seeks to reduce its carbon footprint and adopt greener practices, there is a rising demand for fuel-efficient engines, eco-friendly materials, and more sustainable operational solutions. The modernization of military aircraft with such technologies not only supports environmental goals but also reduces long-term operating costs. Moreover, the U.S. Department of Defense is increasingly focused on enhancing the energy efficiency of its fleets, creating a fertile ground for the development of next-generation aircraft technologies. Companies involved in the creation of fuel-efficient, low-emission aircraft components and systems are poised to benefit from these trends, presenting significant opportunities for market growth.
Market Segmentation Analysis:
By Type:
The U.S. military aircraft modernization market is segmented by aircraft type, which includes fighter aircraft, transport aircraft, helicopters, and special mission aircraft. Fighter aircraft dominate the segment due to their critical role in air superiority and combat operations. Modernization efforts focus on enhancing their stealth capabilities, avionics, and weapon systems to counter emerging threats. Transport aircraft modernization aims to improve efficiency and capacity, with upgrades focusing on avionics and structural modifications for greater operational versatility. Helicopters, essential for tactical operations and reconnaissance, are also undergoing modernization, with a focus on improving survivability and mission capabilities. Special mission aircraft, often tasked with intelligence, surveillance, and reconnaissance (ISR), benefit from advanced avionics and mission-specific upgrades, such as enhanced sensor systems, to improve effectiveness in specialized operations. Each segment requires tailored modernization strategies to meet the unique operational needs of the U.S. military.
By Modernization:
The U.S. military aircraft modernization market is further segmented by the type of modernization efforts, including avionics upgrades, engine enhancements, structural modifications, and weapon system improvements. Avionics upgrades are crucial for enhancing the aircraft's navigation, communication, and operational capabilities, ensuring effective mission execution. Engine upgrades focus on improving fuel efficiency, power output, and overall performance, contributing to cost savings and extended aircraft lifespan. Structural modifications are essential for maintaining airframe integrity and meeting updated military standards, extending the service life of older aircraft. Weapon system upgrades, which include the integration of advanced missile systems and targeting technologies, enhance the aircraft's combat readiness and ability to engage modern threats. These modernization areas are critical for ensuring that U.S. military aircraft remain effective and reliable, maintaining air superiority and operational dominance across diverse mission environments.
Segments:
Based on Type:
- Fighter Aircraft
- Transport Aircraft
- Helicopters
- Special Mission Aircraft
Based on Modernization:
- Avionics
- Engine Upgrades
- Structural Modifications
- Weapon System Upgrades
Based on Component:
- Software
- Hardware
Based on the Geography:
- Western United States
- Midwestern United States
- Southern United States
- Northeastern United States
Regional Analysis
Western United States
The Western United States holds a significant share of the U.S. military aircraft modernization market, accounting for approximately 35% of the total market. This region's dominance is driven by the presence of key military bases and defense contractors, including major aerospace companies like Boeing and Lockheed Martin. These companies are heavily involved in military aircraft design, development, and modernization, making the Western U.S. a hub for technological advancements and system upgrades. Additionally, states such as California, Nevada, and Arizona house several military installations, where modernization programs are essential to maintaining operational readiness. The region’s proximity to cutting-edge research and development in aviation technologies also positions it as a critical player in aircraft modernization, with a focus on advancing avionics, engine upgrades, and weapon systems to maintain air superiority.
Midwestern United States
The Midwestern United States holds approximately 25% of the U.S. military aircraft modernization market. This region is home to significant military facilities, such as Wright-Patterson Air Force Base in Ohio, which serves as a key hub for aircraft maintenance, modernization, and innovation. The region is also home to important aerospace suppliers and manufacturers that provide critical components for military aircraft. Modernization efforts in the Midwest are focused on structural modifications, engine upgrades, and avionics enhancements. The presence of numerous defense contractors in the area, coupled with the U.S. military’s strategic investment in these facilities, supports continuous growth in the region’s aircraft modernization efforts. Additionally, the Midwest benefits from strong collaboration between the public and private sectors, ensuring that aircraft modernization programs are carried out efficiently and effectively.
Southern United States
The Southern United States is estimated to account for 20% of the market share in U.S. military aircraft modernization. States like Texas, Florida, and Alabama are home to prominent military bases, including the Naval Air Station Pensacola and the Eglin Air Force Base, both of which contribute to modernization programs through maintenance and upgrades. The Southern U.S. is a significant player due to the vast infrastructure and testing facilities that support modernization initiatives. Additionally, the region’s focus on special mission aircraft modernization, particularly in areas of intelligence, surveillance, and reconnaissance (ISR), provides a unique growth opportunity. The Southern region is also investing in training programs and the integration of advanced technologies like AI and automation, ensuring the continued readiness of military aircraft and extending their operational lifespan.
Northeastern United States
The Northeastern United States holds a smaller market share of approximately 15% in the U.S. military aircraft modernization sector. Despite being home to fewer large military bases compared to other regions, the Northeast plays a critical role due to its concentration of defense research facilities, such as those in Massachusetts and New York. These areas are heavily involved in the development of cutting-edge technologies that drive modernization efforts, including advanced avionics and weapon system integration. Additionally, the Northeast has a growing focus on cybersecurity and electronic warfare technologies, which are becoming increasingly important in modern military operations. The region’s contributions, while smaller in terms of market share, are significant in terms of technological innovation, making it an essential player in the overall modernization strategy.
Key Player Analysis
- Lockheed Martin Corporation
- Boeing Company
- Northrop Grumman Corporation
- Raytheon Technologies Corporation
- General Dynamics Corporation
- L3Harris Technologies
- Textron Aviation
- Sierra Nevada Corporation
- Honeywell International Inc.
- Collins Aerospace
Competitive Analysis
The U.S. military aircraft modernization market is highly competitive, with key players like Lockheed Martin, Boeing, Northrop Grumman, Raytheon Technologies, General Dynamics, L3Harris Technologies, Textron Aviation, Sierra Nevada Corporation, Honeywell International Inc., and Collins Aerospace leading the sector. Companies are leveraging their expertise in various areas such as avionics, propulsion systems, and weapon systems to enhance the capabilities of military aircraft. The competition is driven by the constant need to improve operational efficiency, extend the lifespan of aging aircraft, and maintain air superiority. For instance, Lockheed Martin's F-35 program has delivered over 800 aircraft to the U.S. military services, international partners, and foreign military sales customers. Players in the market are investing heavily in research and development to stay ahead in areas such as AI integration, advanced materials, and stealth technology. Furthermore, partnerships with the U.S. government and military agencies play a crucial role in securing modernization contracts and ensuring the timely deployment of upgraded aircraft. Competitive differentiation is also seen in the development of specialized mission systems, which cater to specific operational needs like intelligence, surveillance, and reconnaissance (ISR). Companies are increasingly focusing on offering cost-effective solutions to manage the high expenses associated with modernization programs while maintaining high performance and reliability. This intense competition ensures continuous innovation and modernization, making the U.S. military fleet technologically superior and combat-ready.
Recent Developments
- In January 2025, Lockheed Martin delivered 110 F-35 fighter jets to the U.S. and its allies in 2024, achieving a target set by CEO Jim Taiclet. This delivery is part of the ongoing modernization under the Technology Refresh 3 (TR-3) program, enhancing the jets' displays and processing power.
- In January 2025, Northrop Grumman was awarded a $3.5 billion contract by the U.S. Navy to develop the E-130J aircraft, which will replace the E-6B Mercury for nuclear command, control, and communications missions. This project is crucial for maintaining the U.S. nuclear deterrent capabilities.
- In December 2024, Lockheed Martin demonstrated an uncrewed capability with a surrogate HIMARS launcher, marking significant progress in developing autonomous systems that can operate alongside manned vehicles. This technology aims to enhance artillery capabilities for the U.S. Army.
- In December 2024, Saab received an order valued at SEK 466 million from the Swedish Defence Materiel Administration for enhancements to the Gripen C/D, focusing on integrating advanced missile systems to improve operational capabilities.
- In August 2024, Boeing delivered the first MH-139A Grey Wolf production aircraft to the U.S. Air Force as part of a modernization initiative aimed at supporting national security and enhancing capabilities within the U.S. nuclear triad. The aircraft features improved speed, range, and operational flexibility.
Market Concentration & Characteristics
The U.S. military aircraft modernization market is characterized by moderate to high market concentration, with a few key players dominating the sector. These companies have established strong relationships with the U.S. government and defense agencies, allowing them to secure large-scale modernization contracts. The market’s characteristics include a high level of technological complexity, with companies investing heavily in research and development to drive innovation in avionics, propulsion systems, and weapon systems. The focus is on improving the operational efficiency and mission effectiveness of aging military aircraft, while extending their service life through upgrades. Due to the specialized nature of the market, there are significant barriers to entry, as new players must possess advanced technical expertise and substantial financial resources to compete effectively. The U.S. military aircraft modernization market also features long procurement cycles, with contracts often spanning several years, ensuring stable demand for leading companies. Furthermore, the market is heavily influenced by government defense budgets and regulations, making it responsive to changes in national security priorities. Companies that succeed in this market typically focus on offering cost-effective, mission-specific solutions and maintaining a high level of reliability and performance in their products and services. This competitive landscape fosters continuous innovation and ensures the U.S. military’s technological superiority in the global defense arena.
Report Coverage
The research report offers an in-depth analysis based on Type, Modernization, Component and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The U.S. military aircraft modernization market is expected to experience steady growth driven by increasing defense budgets and national security concerns.
- Advancements in artificial intelligence, autonomous systems, and next-generation avionics will continue to shape the future of military aircraft upgrades.
- Increasing demand for stealth and low observability technologies will lead to further development of advanced materials and coatings for aircraft.
- The integration of more efficient propulsion systems and fuel-efficient engines will be a key focus for reducing operational costs.
- Upgrades in weapon systems and targeting technologies will enhance precision strike capabilities and improve overall combat effectiveness.
- Aging aircraft fleets will require extensive modernization efforts, creating a sustained demand for avionics, engine, and structural upgrades.
- The market will see increased adoption of cyber capabilities and electronic warfare systems to counter emerging threats in the digital domain.
- Growing emphasis on sustainability and energy efficiency will drive the development of environmentally friendly aircraft technologies.
- Collaborative partnerships between defense contractors and government agencies will continue to be pivotal for successful modernization programs.
- Regional investments in military modernization will support specialized upgrades for various mission types, ensuring readiness across different combat scenarios.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the U.S. Military Aircraft Modernization Market?
What factors are driving the growth of the U.S. Military Aircraft Modernization Market?
What are the key segments within the U.S. Military Aircraft Modernization Market?
What are some challenges faced by the U.S. Military Aircraft Modernization Market?
Who are the major players in the U.S. Military Aircraft Modernization Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 U.S. Military Aircraft Modernization Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2023; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global U.S. Military Aircraft Modernization Market Snapshot
- 2.1.1 Market Size – Historical (2023) & Forecast (2023-2032) (2023: USD 14,810.83 million → 2032: USD 26,602.75 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 U.S. Military Aircraft Modernization Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2023 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2023
- 2.3.2 Top 10 Players by Volume Share – 2023
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. U.S. Military Aircraft Modernization Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 U.S. Military Aircraft Modernization Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 U.S. Military Aircraft Modernization Market Drivers
- 3.3 U.S. Military Aircraft Modernization Market Restraints & Challenges
- 3.4 U.S. Military Aircraft Modernization Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 U.S. Military Aircraft Modernization Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 U.S. Military Aircraft Modernization Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, U.S. Military Aircraft Modernization category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 U.S. Military Aircraft Modernization Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. U.S. Military Aircraft Modernization Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2023)
- 5.1.2 Global Export Volume by Country (2023)
- 5.1.3 Global Import Value by Country (2023)
- 5.1.4 Global Import Volume by Country (2023)
- 5.1.5 Net Trade Balance by Country (2023)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2023)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the U.S. Military Aircraft Modernization market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 U.S. Military Aircraft Modernization Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2023
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 U.S. Military Aircraft Modernization Market Share Analysis – 2023
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2023)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 U.S. Military Aircraft Modernization Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in U.S. Military Aircraft Modernization (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New U.S. Military Aircraft Modernization Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global U.S. Military Aircraft Modernization Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2023 & 2032)
- 7.1.2 Channel Mix Evolution (2023-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America U.S. Military Aircraft Modernization Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe U.S. Military Aircraft Modernization Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific U.S. Military Aircraft Modernization Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America U.S. Military Aircraft Modernization Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East U.S. Military Aircraft Modernization Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa U.S. Military Aircraft Modernization Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. U.S. Military Aircraft Modernization Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
