
Urothelial Cancer Treatment Market Overview:
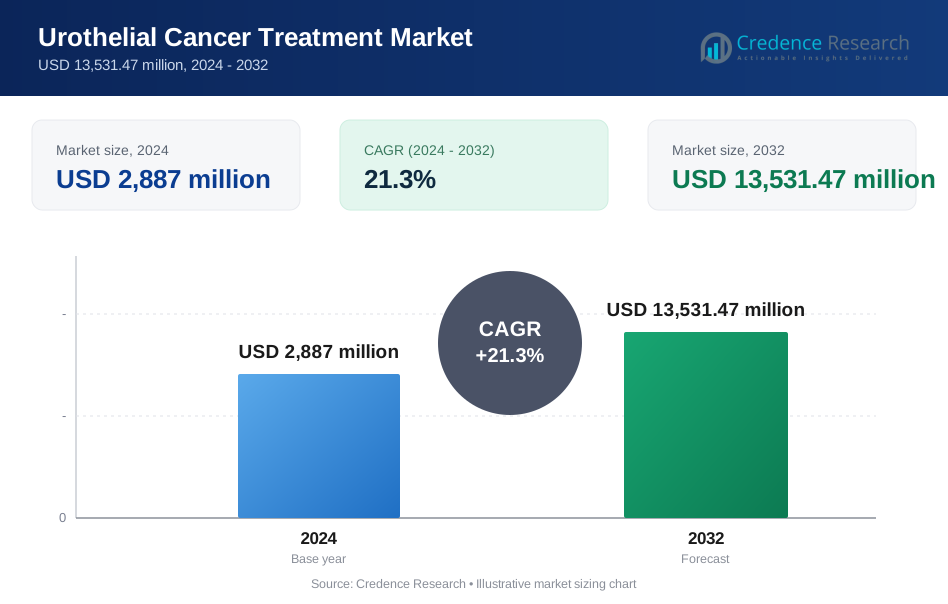
The Urothelial Cancer Treatment Market size was valued at USD 2,887 million in 2024 and is anticipated to reach USD 13,531.47 million by 2032, at a CAGR of 21.3% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Urothelial Cancer Treatment Market Size 2024 | USD 2,887 million |
| Urothelial Cancer Treatment Market, CAGR | 21.3% |
| Urothelial Cancer Treatment Market Size 2032 | USD 13,531.47 million |
Urothelial Cancer Treatment Market Insights
- Market growth is driven by rising urothelial cancer prevalence, increasing adoption of immunotherapy, and expanding oncology infrastructure, with immunotherapy holding 41.6% segment share in 2024 due to superior survival outcomes.
- Key market trends include rapid uptake of immune checkpoint inhibitors and targeted therapies, with immune checkpoint inhibitors accounting for 38.4% share in 2024, supported by precision medicine and biomarker-based treatment approaches.
- Market participation is shaped by strong innovation pipelines, extensive clinical trials, and strategic collaborations among leading pharmaceutical companies focused on combination regimens and lifecycle expansion.
- Regionally, North America dominated with 38.6% share in 2024, followed by Europe at 27.4% and Asia Pacific at 21.9%, supported by advanced healthcare systems, early approvals, and increasing treatment access.

Urothelial Cancer Treatment Market Segmentation Analysis:
By Treatment Type:
The Urothelial Cancer Treatment Market, by treatment type, is led by immunotherapy, which accounted for 41.6% market share in 2024, driven by its superior survival outcomes and durable responses in advanced and metastatic cases. Immune checkpoint inhibitors such as PD-1 and PD-L1 therapies have significantly reshaped first- and second-line treatment protocols. Chemotherapy continues to hold a notable share due to its established use in early-stage disease, while targeted therapy is gaining traction with biomarker-driven approaches. Increasing regulatory approvals and guideline inclusion strongly support immunotherapy dominance.
- For instance, cisplatin/gemcitabine achieved a 64.6% overall response rate in patients with muscle-invasive urothelial cancer. Carboplatin/gemcitabine showed a 43.3% overall response rate in similar real-world cohorts.
By End-Use:
Based on end-use, hospitals dominated the Urothelial Cancer Treatment Market with a 46.9% share in 2024, supported by high patient inflow, advanced oncology infrastructure, and access to multidisciplinary care. Hospitals remain the primary centers for complex procedures, systemic therapies, and combination regimens requiring close monitoring. Cancer treatment centers are expanding steadily due to specialized oncology services, while specialty clinics are witnessing growth from outpatient immunotherapy administration. The dominance of hospitals is further reinforced by reimbursement coverage, availability of clinical trials, and rising hospitalization rates for advanced urothelial cancer cases.
- For instance, Merck's AMBASSADOR trial (KEYNOTE-123) tested adjuvant pembrolizumab in 702 hospital-enrolled patients with muscle-invasive urothelial carcinoma after surgery, significantly improving disease-free survival over observation alone.
By Drug Type:
In terms of drug type, immune checkpoint inhibitors emerged as the leading sub-segment, holding a 38.4% market share in 2024, owing to strong clinical efficacy and broad adoption across treatment lines. Drugs targeting PD-1 and PD-L1 pathways have become standard of care for cisplatin-ineligible and relapsed patients. Platinum-based chemotherapy drugs maintain a substantial presence due to historical usage, while FGFR inhibitors are expanding rapidly with increased genetic testing. Rising precision oncology adoption and favorable survival data continue to drive immune checkpoint inhibitor leadership.
Key Growth Drivers
Rising Prevalence of Urothelial Cancer and Aging Population
The Urothelial Cancer Treatment Market is driven by the increasing prevalence of urothelial cancer, particularly among the aging population. Longer life expectancy has increased exposure to risk factors such as smoking, occupational chemicals, and chronic inflammation. Improved diagnostic capabilities and greater disease awareness are also contributing to higher detection rates. As patient volumes rise, demand for effective treatment options continues to grow, supporting increased utilization of chemotherapy, immunotherapy, and targeted drugs across both early-stage and advanced disease settings.
- For instance, Janssen Biotech's erdafitinib (Balversa), approved for locally advanced or metastatic urothelial carcinoma with FGFR3 alterations, showed a confirmed ORR of 35.3% and median overall survival of 12.1 months in a key trial versus chemotherapy.
Expanding Adoption of Immunotherapy and Targeted Therapies
The rapid shift toward immunotherapy and targeted therapies is a major growth catalyst in the Urothelial Cancer Treatment Market. Immune checkpoint inhibitors and biomarker-driven treatments have demonstrated superior clinical outcomes compared to traditional chemotherapy. Their expanding use across first-line, second-line, and combination regimens has strengthened physician adoption. Continuous regulatory approvals and expanding clinical pipelines are further accelerating treatment uptake, improving survival outcomes and driving long-term market expansion.
- For instance, Bristol-Myers Squibb's nivolumab monotherapy in platinum-resistant metastatic urothelial carcinoma achieved an ORR of 20.4% and median OS of 8.6 months in the phase II CheckMate 275 trial, with durable responses observed over 24.5 months of follow-up.
Increasing Healthcare Investment and Oncology Infrastructure
Growing healthcare expenditure and expansion of oncology infrastructure are strongly supporting the Urothelial Cancer Treatment Market. Governments and private healthcare providers are investing in advanced cancer hospitals, diagnostic facilities, and specialty oncology centers. Improved access to innovative therapies and favorable reimbursement policies in developed regions are enhancing treatment penetration. Simultaneously, infrastructure development in emerging markets is improving patient access to modern urothelial cancer treatments, sustaining overall market growth.
Key Trends & Opportunities
Advancement of Precision Medicine and Biomarker-Based Treatment
Precision medicine is emerging as a key trend and opportunity in the Urothelial Cancer Treatment Market. Increasing use of genetic profiling and biomarker testing enables more accurate patient stratification and personalized treatment selection. Targeted therapies such as FGFR inhibitors and PD-L1 inhibitors benefit significantly from this approach. Pharmaceutical companies are investing in companion diagnostics and combination therapies, enhancing treatment effectiveness while opening new growth avenues for innovative and differentiated drug offerings.
- For instance, Merck's Keytruda (pembrolizumab) uses PD-L1 IHC 22C3 pharmDx by Agilent for urothelial carcinoma patients ineligible for cisplatin. The assay identifies those likely to benefit, supporting biomarker-driven treatment in advanced cases.
Expanding Market Presence in Emerging Economies
Emerging markets present substantial growth opportunities for the Urothelial Cancer Treatment Market. Rising cancer awareness, improving healthcare infrastructure, and expanding insurance coverage are increasing access to advanced oncology therapies. Countries in Asia Pacific, Latin America, and the Middle East are witnessing growing urothelial cancer incidence due to lifestyle changes and aging demographics. Strategic partnerships, localized manufacturing, and favorable regulatory reforms are enabling global players to strengthen their presence and expand patient reach.
- For instance, epidemiological analyses by Novotech and other groups show that Asia accounts for more than 215,000 bladder cancer cases annually and has the second-highest incidence globally, underscoring the need for localized clinical development and manufacturing of urothelial cancer drugs.
Key Challenges
High Cost of Advanced Therapies and Reimbursement Limitations
High treatment costs remain a major challenge for the Urothelial Cancer Treatment Market. Immunotherapies and targeted drugs are often expensive and require long-term administration, increasing the financial burden on healthcare systems and patients. Limited reimbursement coverage in developing regions further restricts access to innovative treatments. These economic barriers continue to impact adoption rates, particularly in price-sensitive markets, despite strong clinical demand.
Treatment Resistance and Therapy-Related Adverse Effects
Treatment resistance and adverse effects pose significant challenges in the Urothelial Cancer Treatment Market. A notable proportion of patients experience reduced responsiveness to immunotherapy or targeted treatments over time, limiting long-term efficacy. Additionally, immune-related toxicities and chemotherapy-associated side effects can lead to treatment discontinuation. Addressing these challenges requires continued clinical research, development of combination regimens, and improved patient management strategies, increasing overall treatment complexity.
Regional Analysis
North America
The Urothelial Cancer Treatment Market in North America accounted for 38.6% market share in 2024, driven by high disease prevalence, strong adoption of immunotherapy, and advanced oncology infrastructure. The United States leads the region due to early regulatory approvals, wide reimbursement coverage, and strong presence of major pharmaceutical companies. High awareness levels and access to precision diagnostics support increased use of targeted and immune-based therapies. Ongoing clinical trials and rapid integration of novel combination regimens continue to strengthen treatment penetration, reinforcing North America’s leadership position in the global market.
Europe
Europe held a 27.4% market share in 2024 in the Urothelial Cancer Treatment Market, supported by well-established healthcare systems and rising adoption of innovative oncology therapies. Countries such as Germany, France, and the United Kingdom contribute significantly due to strong public healthcare funding and early inclusion of immunotherapies in treatment guidelines. Increasing cancer screening programs and growing focus on personalized medicine are improving treatment outcomes. Regulatory support from the European Medicines Agency and expanding access to advanced biologics continue to drive steady market growth across the region.
Asia Pacific
Asia Pacific represented 21.9% market share in 2024 in the Urothelial Cancer Treatment Market, reflecting rapid growth driven by rising cancer incidence and expanding healthcare access. Countries including China, Japan, and India are witnessing increasing diagnosis rates due to improved screening and awareness. Government investments in oncology infrastructure and growing availability of immunotherapy drugs are supporting market expansion. Additionally, rising healthcare expenditure and entry of multinational pharmaceutical companies through partnerships are accelerating adoption of advanced urothelial cancer treatments across the region.
Latin America
Latin America accounted for 7.2% market share in 2024 in the Urothelial Cancer Treatment Market, supported by gradual improvements in cancer care infrastructure. Brazil and Mexico are key contributors due to increasing healthcare spending and expanding access to oncology drugs. Growing awareness of urothelial cancer and improving diagnostic capabilities are enhancing early detection rates. However, access to advanced therapies remains uneven across countries. Ongoing healthcare reforms and expanding public-private partnerships are expected to improve treatment availability and support long-term market development.
Middle East & Africa
The Middle East & Africa region held a 4.9% market share in 2024 in the Urothelial Cancer Treatment Market, driven by rising cancer burden and improving healthcare systems. Gulf Cooperation Council countries are leading the region due to investments in advanced hospitals and oncology centers. Increasing adoption of immunotherapy in urban healthcare facilities is improving treatment outcomes. However, limited access to innovative therapies in parts of Africa continues to restrain growth. Government-led healthcare modernization initiatives are expected to gradually enhance regional market penetration.
Urothelial Cancer Treatment Market Segmentations:
By Treatment Type:
- Chemotherapy
- Immunotherapy
- Targeted Therapy
- Surgery
- Radiation Therapy
By End-Use:
- Hospitals
- Cancer Treatment Centers
- Ambulatory Surgical Centers
- Specialty Clinics
- Others
By Drug Type:
- Platinum-based Chemotherapy Drugs
- Immune Checkpoint Inhibitors
- FGFR Inhibitors
- PD-L1 Inhibitors
- Others
By Cancer Stage:
- Non-Muscle Invasive Bladder Cancer (NMIBC)
- Muscle Invasive Bladder Cancer (MIBC)
- Metastatic Urothelial Carcinoma
- Others
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
Competitive landscape analysis of the Urothelial Cancer Treatment Market highlights the strong presence of Merck & Co., Inc., Bristol Myers Squibb, Roche (Genentech), Pfizer Inc., AstraZeneca, Novartis International AG, Sanofi S.A., Johnson & Johnson (Janssen Pharmaceuticals), Eli Lilly and Company, and Seattle Genetics. The market is characterized by robust innovation pipelines focused on immunotherapy, targeted therapies, and combination regimens aimed at improving survival outcomes. Leading players continue to strengthen their positions through expanded clinical trials, strategic collaborations, and regulatory approvals for new indications. Heavy investment in R&D enables rapid development of immune checkpoint inhibitors and biomarker-driven treatments. Companies are also pursuing geographic expansion and partnerships in emerging markets to broaden patient access. Portfolio diversification, lifecycle management strategies, and integration of companion diagnostics remain central to sustaining long-term growth and differentiation in this evolving oncology market.
Key Player Analysis
- AstraZeneca
- Novartis International AG
- Seattle Genetics
- Johnson & Johnson (Janssen Pharmaceuticals)
- Eli Lilly and Company
- Sanofi S.A.
- Bristol Myers Squibb
- Pfizer Inc.
- Genentech, Inc. (Roche)
- Merck & Co., Inc.
Recent Developments
- In September 2025, Johnson & Johnson received FDA approval for INLEXZO™ (gemcitabine intravesical system) for treating BCG-unresponsive non-muscle invasive bladder cancer, marking a novel drug-device launch in urothelial cancer care.
- In August 2024, Astellas Pharma secured approval from China’s National Medical Products Administration (NMPA) for PADCEV (enfortumab vedotin) to treat adult patients with locally advanced or metastatic urothelial cancer previously treated with platinum chemotherapy and PD‑1/PD‑L1 inhibitors.
- In March 2024, Bristol Myers Squibb received FDA approval for nivolumab (Opdivo) in combination with cisplatin and gemcitabine as a first-line treatment for adult patients with unresectable or metastatic urothelial carcinoma.
Report Coverage
The research report offers an in-depth analysis based on Treatment Type, Drug Type, End Use, Cancer Stage and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Urothelial Cancer Treatment Market will continue to expand due to increasing global disease prevalence and earlier diagnosis rates.
- Immunotherapy will remain the backbone of treatment, with broader use across first-line and combination regimens.
- Targeted therapies will gain stronger adoption as biomarker testing becomes standard clinical practice.
- Combination treatment approaches will improve response durability and reduce resistance rates.
- Precision medicine will drive more personalized and effective treatment pathways for patients.
- Emerging markets will witness faster treatment adoption supported by improving oncology infrastructure.
- Pharmaceutical companies will increase investment in late-stage clinical trials and novel drug platforms.
- Regulatory agencies will accelerate approvals for breakthrough and orphan oncology therapies.
- Digital health and real-world evidence will play a growing role in treatment optimization and monitoring.
- Long-term market growth will depend on improving affordability, access, and reimbursement coverage.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Prevalence of Urothelial Cancer and Aging Population
The increasing incidence of urothelial cancer, particularly among older adults, is driving demand for advanced treatment options. Improved diagnostics and greater disease awareness are leading to higher detection rates and more patients seeking therapy.
Expanding Adoption of Immunotherapy and Targeted Therapies
Immunotherapies and targeted drugs are rapidly being integrated into treatment protocols due to their superior survival outcomes and durable responses, especially in advanced and metastatic cases. Regulatory approvals and guideline updates are accelerating their uptake.
Increasing Healthcare Investment and Oncology Infrastructure
Governments and private providers are investing in advanced cancer hospitals and diagnostic facilities, improving patient access to innovative urothelial cancer treatments. This is particularly impactful in emerging markets where oncology infrastructure is expanding.
Advancement of Precision Medicine and Biomarker-Based Treatment
The growing use of genetic profiling and biomarker testing enables more personalized and effective treatment selection, supporting the adoption of targeted therapies and companion diagnostics. This trend is opening new growth avenues for innovative drug offerings.
Broader Access and Reimbursement in Developed Regions
Favorable reimbursement policies and early regulatory approvals in North America and Europe are enhancing patient access to advanced therapies, supporting higher market penetration and faster adoption of new treatment modalities.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Urothelial Cancer Treatment Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Urothelial Cancer Treatment Market projected to grow between 2024 and 2032?
Which Urothelial Cancer Treatment Market segment held the largest share in 2024?
Which Urothelial Cancer Treatment Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Urothelial Cancer Treatment Market?
Who are the leading companies in the Urothelial Cancer Treatment Market?
Which region commanded the largest share of the Urothelial Cancer Treatment Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End-Use
- 1.2.1 Hospitals
- 1.2.2 Cancer Treatment Centers
- 1.2.3 Ambulatory Surgical Centers
- 1.2.4 Specialty Clinics
- 1.2.5 Others
- 1.3 By Drug Type
- 1.3.1 Platinum-based Chemotherapy Drugs
- 1.3.2 Immune Checkpoint Inhibitors
- 1.3.3 FGFR Inhibitors
- 1.3.4 PD-L1 Inhibitors
- 1.3.5 Others
- 1.4 By Cancer Stage
- 1.4.1 Non-Muscle Invasive Bladder Cancer (NMIBC)
- 1.4.2 Muscle Invasive Bladder Cancer (MIBC)
- 1.4.3 Metastatic Urothelial Carcinoma
- 1.4.4 Others
- 1.5 By Treatment Type
- 1.5.1 Chemotherapy
- 1.5.2 Immunotherapy
- 1.5.3 Targeted Therapy
- 1.5.4 Surgery
- 1.5.5 Radiation Therapy
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 2,887 million → 2032: USD 13,531.47 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Urothelial Cancer Treatment Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Urothelial Cancer Treatment Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Urothelial Cancer Treatment Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Urothelial Cancer Treatment Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Urothelial Cancer Treatment Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Urothelial Cancer Treatment Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Urothelial Cancer Treatment Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Urothelial Cancer Treatment Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 2,887 million → 2032: USD 13,531.47 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Urothelial Cancer Treatment Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End-Use - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Hospitals
- 12.3.7.2 Cancer Treatment Centers
- 12.3.7.3 Ambulatory Surgical Centers
- 12.3.7.4 Specialty Clinics
- 12.3.7.5 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Drug Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Platinum-based Chemotherapy Drugs
- 12.4.7.2 Immune Checkpoint Inhibitors
- 12.4.7.3 FGFR Inhibitors
- 12.4.7.4 PD-L1 Inhibitors
- 12.4.7.5 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Cancer Stage - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Non-Muscle Invasive Bladder Cancer (NMIBC)
- 12.5.7.2 Muscle Invasive Bladder Cancer (MIBC)
- 12.5.7.3 Metastatic Urothelial Carcinoma
- 12.5.7.4 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Treatment Type - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Chemotherapy
- 12.6.7.2 Immunotherapy
- 12.6.7.3 Targeted Therapy
- 12.6.7.4 Surgery
- 12.6.7.5 Radiation Therapy
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Urothelial Cancer Treatment End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Urothelial Cancer Treatment Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Urothelial Cancer Treatment Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Urothelial Cancer Treatment Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Merck & Co., Inc.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Bristol Myers Squibb
- 18.4 Roche (Genentech)
- 18.5 Pfizer Inc.
- 18.6 AstraZeneca
- 18.7 Novartis International AG
- 18.8 Sanofi S.A.
- 18.9 Johnson & Johnson (Janssen Pharmaceuticals)
- 18.10 Eli Lilly and Company
- 18.11 Seattle Genetics
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

