
Market Overview
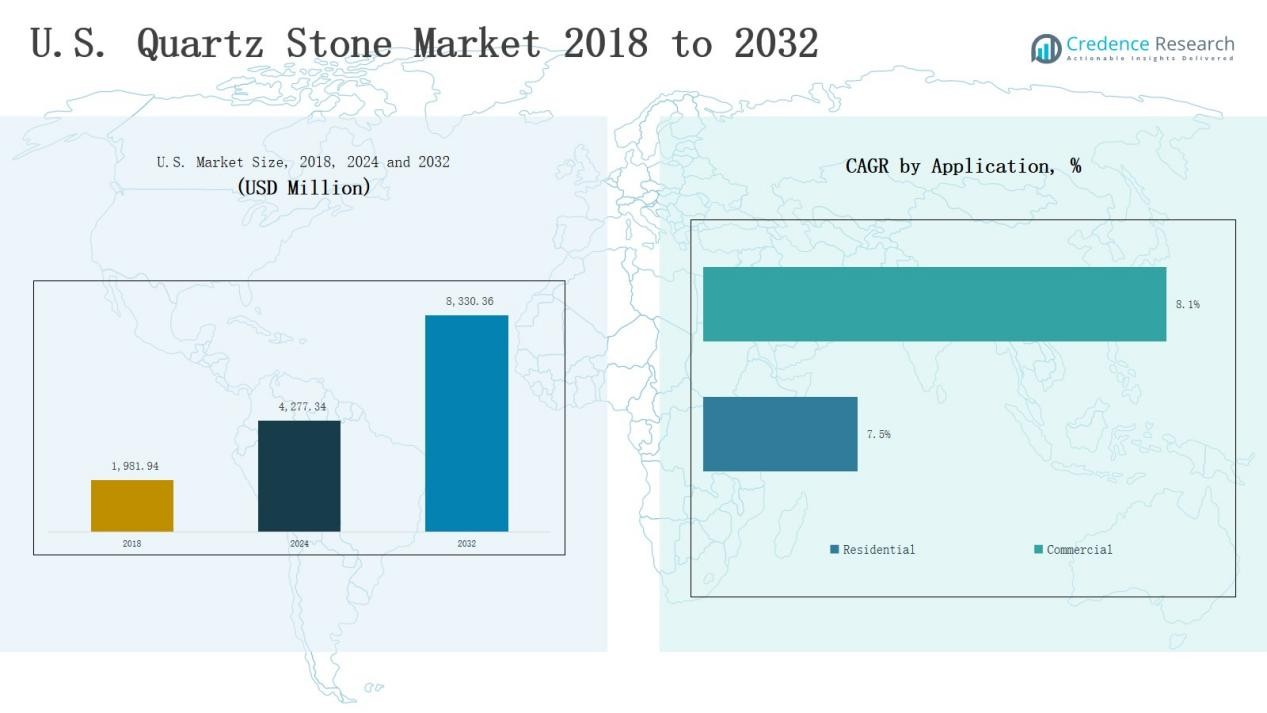
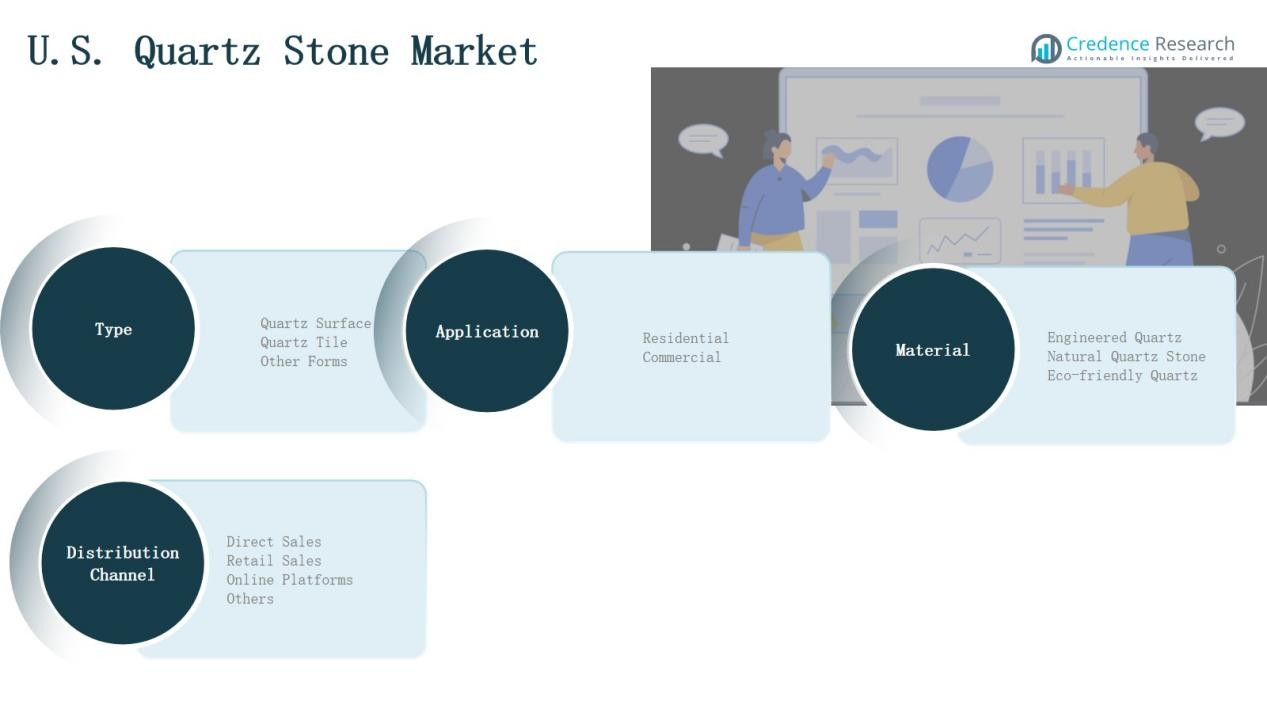
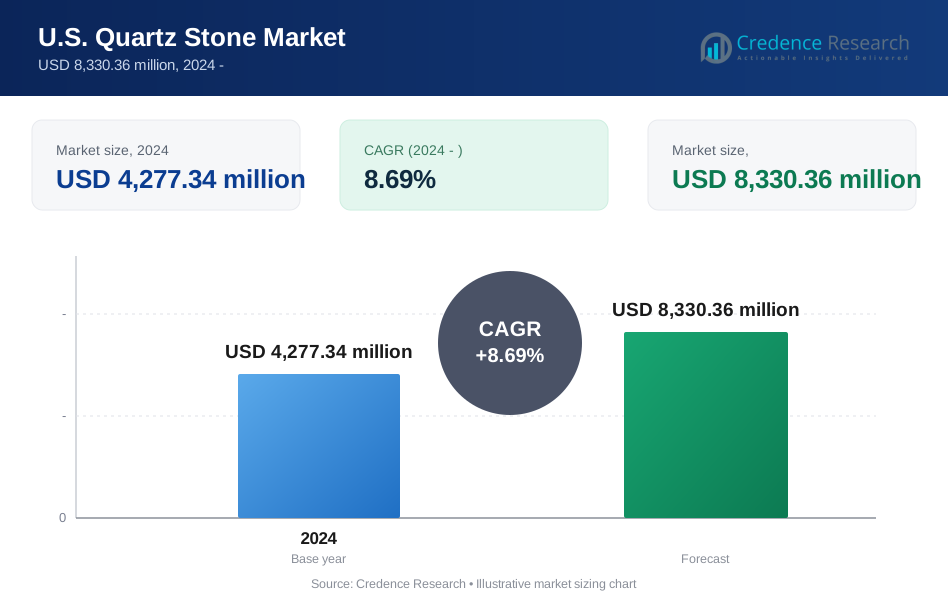
The U.S. Quartz Stone Market size was valued at USD 1,981.94 million in 2018, increased to USD 4,277.34 million in 2024, and is projected to reach USD 8,330.36 million by 2032, growing at a CAGR of 8.69% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| U.S. Quartz Stone Market Size 2024 | USD 4,277.34 Million |
| U.S. Quartz Stone Market, CAGR | 8.69% |
| U.S. Quartz Stone Market Size 2032 | USD 8,330.36 Million |
The U.S. Quartz Stone Market is led by major companies including Caesarstone Ltd., Cambria Company LLC, Hanwha L&C (HanStone Quartz), LG Hausys Ltd., DuPont de Nemours, Inc., Wilsonart LLC, Vicostone JSC, Compac Surfaces, Santa Margherita S.p.A., and Quarella S.p.A. These firms dominate through advanced engineering, design innovation, and strong brand portfolios. They focus on surface durability, aesthetic customization, and sustainable production to meet rising consumer expectations. The South region emerged as the market leader in 2024, holding a 33% share, driven by rapid urbanization, housing expansion, and growing hospitality investments.
Market Insights
- The U.S. Quartz Stone Market grew from USD 1,981.94 million in 2018 to USD 4,277.34 million in 2024, and is projected to reach USD 8,330.36 million by 2032, growing at 69% CAGR.
- Quartz Surface led with 63% share in 2024 due to its durability and use in countertops, while Quartz Tile held 25% and Other Forms captured 12%.
- The Residential segment dominated with 68% share, driven by rising home renovations and modern kitchen remodeling trends across the United States.
- Engineered Quartz held 72% share in 2024, supported by consistent quality, variety, and growing demand for sustainable and customized designs.
- The South region remained the leader with 33% share, followed by the Northeast and West each at 24%, driven by rapid urbanization and strong construction growth.
Market Segment Insights
By Type:
The Quartz Surface segment dominated the U.S. Quartz Stone Market in 2024, accounting for 63% of the total share. Its popularity stems from superior durability, aesthetic appeal, and wide use in countertops and wall claddings. The Quartz Tile segment captured 25%, driven by cost-effective flooring demand in residential and commercial interiors. Other Forms held the remaining 12%, mainly used in decorative and architectural applications where design flexibility and customized finishing are required.
- For instance, Cambria offers its Inverness Everleigh quartz surface, featuring debossed, intricate veining in both a high-gloss and a Cambria Matte® finish for premium kitchen installations.
By Application:
The Residential segment led the U.S. Quartz Stone Market in 2024 with a 68% share, supported by increasing home renovation and luxury kitchen remodeling activities. Rising consumer preference for durable, stain-resistant surfaces also boosts demand. The Commercial segment held 32%, driven by the growing adoption of premium quartz in hotels, offices, and retail interiors for enhanced durability, visual consistency, and low maintenance requirements.
- For instance, Silestone by Cosentino collaborated with U.S. hotel chains in 2024 to supply its Sunlit Days collection for eco-certified interiors, while HanStone Quartz products were increasingly specified in office fit-outs and retail counters due to their visual uniformity and ease of maintenance.
By Material Composition:
The Engineered Quartz segment dominated the U.S. Quartz Stone Market in 2024, holding 72% of the share. Its strong performance is linked to controlled manufacturing, consistent quality, and wide design variety. Natural Quartz Stone accounted for 18%, favored in traditional applications valuing authentic texture and color depth. Eco-friendly Quartz captured 10%, supported by rising sustainability trends, recycled material use, and increasing consumer preference for environmentally responsible interior products.
Key Growth Driver
Rising Demand for Premium Residential Interiors
The U.S. Quartz Stone Market is driven by growing adoption of premium materials in residential renovations and new housing projects. Homeowners prefer quartz surfaces for their durability, stain resistance, and visual appeal. Expanding home improvement spending and the popularity of modern kitchen and bathroom designs further enhance market growth. The increasing availability of customizable colors and textures supports consumer appeal, positioning quartz stone as a long-term replacement for granite and marble surfaces.
- For instance, Caesarstone Darcrest quartz countertop features unique organic hues and a honed finish that appeals to consumers seeking both aesthetic and practical benefits in bathroom surfaces.
Expanding Commercial Construction Sector
Rising commercial construction across offices, hotels, and retail spaces drives quartz stone demand. Developers favor quartz for its consistency, ease of maintenance, and design flexibility. Growing investment in hospitality and corporate infrastructure supports large-scale adoption. Quartz’s hygienic properties and non-porous surface make it ideal for high-traffic commercial environments, boosting its usage in lobbies, reception areas, and food service facilities throughout the United States.
- For instance, Silestone by Cosentino is a durable, hygienic quartz surface with a wide color range that is often used in hospitality design projects.
Technological Advancements in Manufacturing
Continuous advancements in surface engineering, digital printing, and resin formulation enhance product quality and design realism. U.S. manufacturers invest in automated production lines and sustainable processing technologies to increase efficiency and reduce waste. These innovations enable precise color matching, improved surface hardness, and expanded design options. Technological integration strengthens domestic production capacity and allows local players to compete with international brands offering advanced engineered quartz solutions.
Key Trend & Opportunity
Sustainability and Eco-Friendly Quartz Products
Growing environmental awareness encourages the use of eco-friendly quartz made from recycled materials and low-emission resins. Consumers increasingly prefer sustainable interiors with certified green products. Manufacturers adopt renewable energy, closed-loop water systems, and recycled aggregates to meet U.S. sustainability standards. This shift creates opportunities for brands emphasizing environmental performance, supporting premium positioning within both residential and commercial segments.
- For instance, Cosentino’s HybriQ+ line is produced using 100% renewable electricity and 99% recycled water.
Rise of Digital Customization and Smart Fabrication
Digital design tools and precision fabrication technologies are transforming the quartz industry. Consumers and designers benefit from 3D visualization, computer-aided cutting, and CNC shaping systems for bespoke installations. This trend allows faster project turnaround, reduced material waste, and greater customization flexibility. Integration with digital retail platforms also strengthens direct-to-consumer engagement, expanding brand reach and enabling personalized product experiences.
- For instance, Caesarstone launched its “Caesarstone Visualizer 3.0,” offering real-time 3D kitchen and bathroom layout previews with AI-assisted color matching.
Key Challenge
High Production and Installation Costs
Quartz stone manufacturing requires energy-intensive processes, advanced resins, and imported raw materials, driving up costs. Installation also demands specialized equipment and skilled labor, raising project expenses. Price sensitivity among mid-range consumers limits market expansion. Balancing affordability with premium quality remains a key challenge for manufacturers seeking wider adoption in both residential and commercial segments.
Competition from Alternative Surface Materials
Quartz stone faces strong competition from granite, porcelain, and solid-surface composites. These alternatives offer similar aesthetic and functional benefits at lower price points. Rapid product innovation in ceramics and hybrid surfaces further intensifies competition. To maintain growth, quartz manufacturers must differentiate through sustainability, advanced design, and stronger brand positioning across both online and offline distribution channels.
Supply Chain Volatility and Raw Material Dependence
The U.S. Quartz Stone Market remains vulnerable to fluctuations in resin, silica, and pigment prices. Dependence on imported materials and logistics disruptions can affect production timelines and profit margins. Global trade tensions and rising transportation costs add uncertainty. Companies are adopting localized sourcing and strategic partnerships to secure stable supply chains and ensure consistent market delivery.
Regional Analysis
Northeast
The Northeast region held 24% of the U.S. Quartz Stone Market in 2024. Strong urban infrastructure and high disposable income support residential and commercial remodeling projects. States such as New York, Massachusetts, and Pennsylvania show consistent demand for quartz countertops and flooring in luxury apartments and hospitality spaces. The region’s preference for durable, low-maintenance materials boosts adoption among premium interior designers. Renovation activity in older housing stock and urban redevelopment programs continue to drive steady market growth in this region.
Midwest
The Midwest accounted for 19% of the total market share in 2024. Rising home improvement projects and new housing developments fuel demand for engineered quartz surfaces. Consumers prefer quartz over natural stone due to its cost efficiency and low upkeep. Industrial expansion in Illinois, Ohio, and Michigan also promotes commercial usage in office and retail infrastructure. The region benefits from improved supply chain access and domestic manufacturing facilities, supporting steady distribution across urban and semi-urban centers.
South
The South region led the market with a 33% share in 2024. Rapid urbanization, population growth, and strong housing starts in Texas, Florida, and Georgia drive high consumption of quartz stone. Developers favor quartz for its resistance to humidity and heat, suitable for southern climates. The region’s expanding hospitality sector further strengthens product penetration in hotels and restaurants. Continuous real estate investment and remodeling activities maintain the South’s dominance in overall market revenue.
West
The West region captured 24% of the U.S. Quartz Stone Market in 2024. States like California, Washington, and Arizona lead demand due to their strong design culture and sustainability focus. The popularity of eco-friendly quartz surfaces supports growth among environmentally conscious consumers. Local fabricators benefit from proximity to ports, enabling steady material imports and faster delivery cycles. Expanding high-end residential projects and commercial developments in metropolitan areas sustain long-term regional demand.
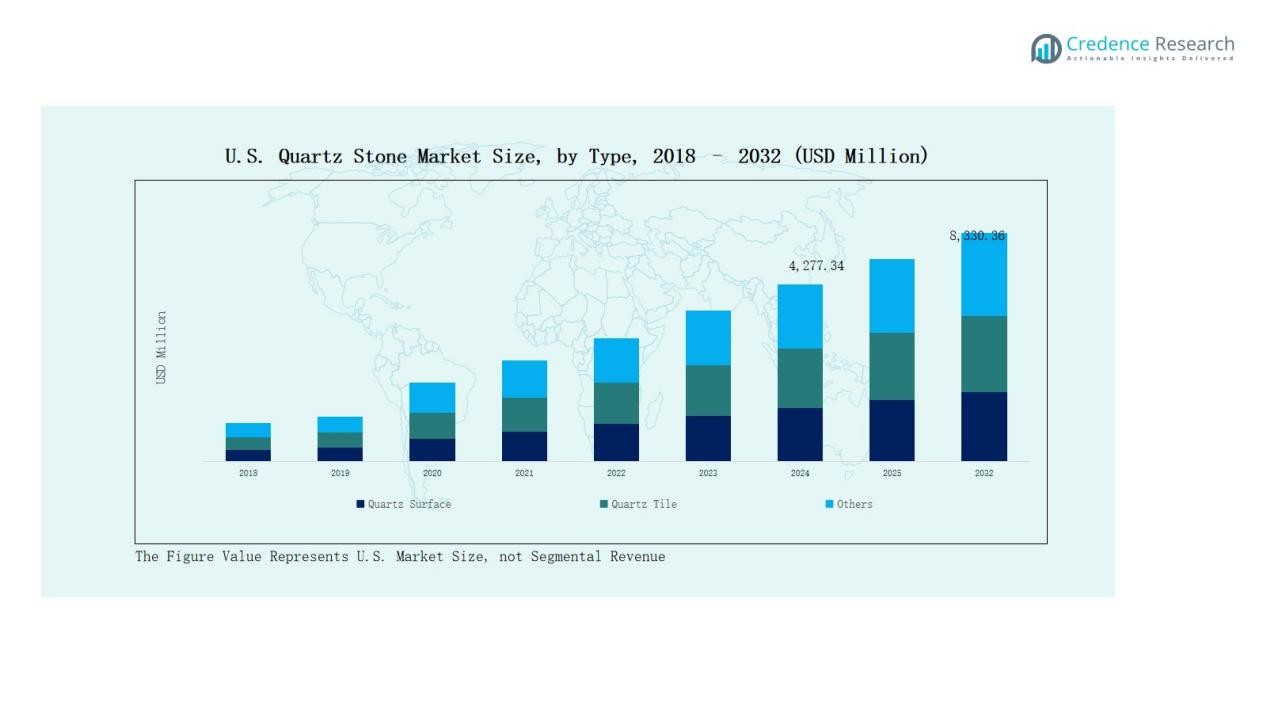
Market Segmentations:
By Type
- Quartz Surface
- Quartz Tile
- Other Forms
By Application
- Residential
- Commercial
By Material Composition
- Engineered Quartz
- Natural Quartz Stone
- Eco-friendly Quartz
By Distribution Channel
- Direct Sales
- Retail Sales
- Online Platforms
- Others
By Region
- Northeast
- Midwest
- South
- West
Competitive Landscape
The U.S. Quartz Stone Market is moderately consolidated, featuring strong competition among global and domestic players. Leading companies such as Caesarstone Ltd., Cambria Company LLC, Hanwha L&C (HanStone Quartz), LG Hausys Ltd., DuPont de Nemours, Inc., and Wilsonart LLC dominate through extensive product portfolios and advanced manufacturing technologies. These firms emphasize innovation, surface durability, and design variety to strengthen market presence. Regional players, including Santa Margherita S.p.A., Vicostone JSC, and Compac Surfaces, expand through partnerships and distribution networks to enhance coverage. The market shows rising investment in automation, digital fabrication, and sustainable quartz production to meet evolving consumer preferences. Product differentiation through texture, finish, and eco-certified materials remains a key strategy for maintaining competitiveness. Companies also focus on capacity expansion, technological integration, and branding efforts to capture growing residential and commercial demand across the United States.
Key Players
- Caesarstone Ltd.
- Hanwha L&C (HanStone Quartz)
- Compac Surfaces
- Vicostone JSC
- Wilsonart LLC
- DuPont de Nemours, Inc.
- LG Hausys Ltd.
- Cambria Company LLC
- Santa Margherita S.p.A.
- Quarella S.p.A.
- Samsung Radianz (Samsung Surface Brand)
- Bitto (Dongguan)
Recent Developments
- In August 2025, Wilsonart introduced ten new quartz designs featuring bold green and blue tones, along with enhanced solid surface patterns to expand its premium design portfolio.
- In April 2025, Vadara Quartz formed a distribution partnership with CRS Marble & Granite to strengthen its U.S. market reach and improve regional supply capabilities.
- In May 2025, LX Hausys launched new quartz colors, including “Taj Duna” in its Viatera Quartzite Collection and an upgraded “Cloud Ridge” in the Suprema line to enhance aesthetic diversity.
Report Coverage
The research report offers an in-depth analysis based on Type, Application, Material Composition, Distribution Channel and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for engineered quartz surfaces will continue to grow across residential and commercial projects.
- Manufacturers will expand production capacity to meet rising domestic construction and renovation needs.
- Sustainable and recycled quartz products will gain strong consumer preference.
- Digital fabrication and automation will improve design precision and reduce production waste.
- Local sourcing of raw materials will increase to reduce supply chain risks.
- Partnerships between manufacturers and interior design firms will strengthen product visibility.
- Retail and online sales channels will expand, offering wider product access to consumers.
- Product innovation will focus on heat resistance, texture variation, and surface strength.
- Rising awareness of eco-friendly building materials will shape future market strategies.
- The competitive landscape will intensify with new entrants introducing advanced design technologies.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for U.S. Quartz Stone Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the U.S. Quartz Stone Market projected to grow between 2025 and 2032?
Which U.S. Quartz Stone Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the U.S. Quartz Stone Market?
Who are the leading companies in the U.S. Quartz Stone Market?
Which region commanded the largest share of the U.S. Quartz Stone Market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 U.S. Quartz Stone Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to the forecast period)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global U.S. Quartz Stone Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (the forecast period) (2024: USD 4,277.34 million → forecast year: USD 8,330.36 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 U.S. Quartz Stone Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs.
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. U.S. Quartz Stone Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 U.S. Quartz Stone Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 U.S. Quartz Stone Market Drivers
- 3.3 U.S. Quartz Stone Market Restraints & Challenges
- 3.4 U.S. Quartz Stone Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 U.S. Quartz Stone Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 U.S. Quartz Stone Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, U.S. Quartz Stone category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 U.S. Quartz Stone Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through the forecast period
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through the forecast period
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. U.S. Quartz Stone Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the U.S. Quartz Stone market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 U.S. Quartz Stone Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 U.S. Quartz Stone Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 U.S. Quartz Stone Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in U.S. Quartz Stone (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New U.S. Quartz Stone Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global U.S. Quartz Stone Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & )
- 7.1.2 Channel Mix Evolution (the forecast period)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through the forecast period
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America U.S. Quartz Stone Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe U.S. Quartz Stone Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific U.S. Quartz Stone Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America U.S. Quartz Stone Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East U.S. Quartz Stone Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa U.S. Quartz Stone Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. U.S. Quartz Stone Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
