
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
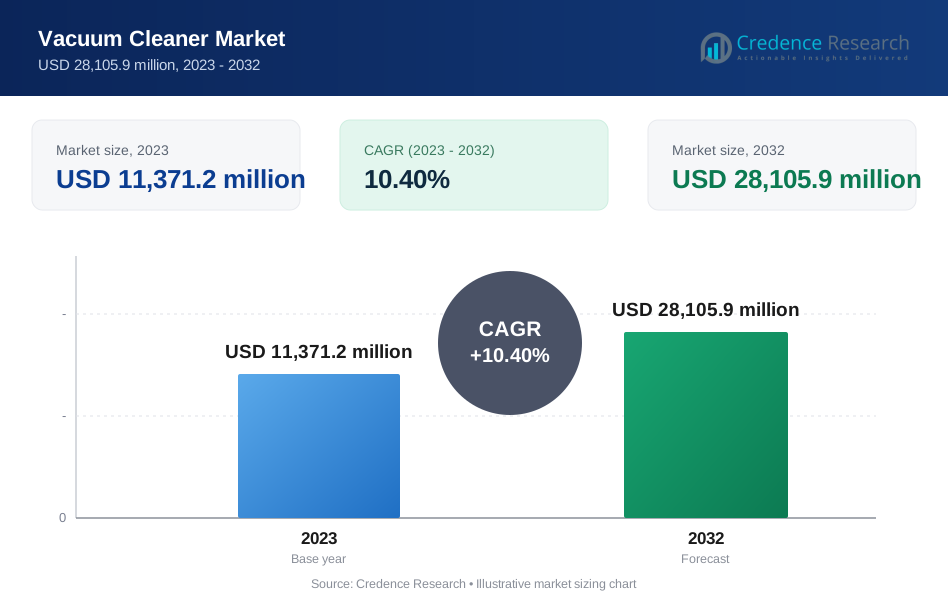
| Vacuum Cleaner Market Size 2023 | USD 11,371.2 Million |
| Vacuum Cleaner Market, CAGR | 10.40% |
| Vacuum Cleaner Market Size 2032 | USD 28,105.9 Million |
Market Overview
The vacuum cleaner market is projected to grow from USD 11,371.2 million in 2023 to USD 28,105.9 million by 2032, expanding at a compound annual growth rate (CAGR) of 10.40%.
The vacuum cleaner market is driven by increasing consumer emphasis on cleanliness and hygiene, coupled with rising disposable incomes that facilitate the adoption of advanced household appliances. Technological innovations, such as automated and robotic vacuum cleaners, are significantly enhancing consumer convenience and efficiency, further propelling market growth. Additionally, trends towards smart homes equipped with IoT-enabled devices are boosting demand for smart vacuum cleaners that integrate seamlessly with other home automation systems. The growing awareness of indoor air quality and the rise in allergies also contribute to the expanding use of vacuum cleaners in residential spaces.
The vacuum cleaner market showcases significant activity across diverse regions, with North America and Europe maintaining strong positions due to advanced technology adoption and consumer awareness. Asia-Pacific stands out as a rapidly growing sector, propelled by urbanization and increased standards of living, particularly in China and India. Key players in this competitive landscape include Dyson, known for innovative designs, iRobot Corporation, a leader in robotic vacuum technology, and Panasonic Holdings Corporation, which integrates smart home technologies into its products. Other notable companies such as ECOVACS, Neato Robotics, Inc., and Snow Joe LLC also contribute to the dynamic evolution of the market with their specialized offerings and geographic reach.
Market Drivers
Economic Growth and Urban Development Drive Demand
Rising disposable income, especially in developing regions, is empowering consumers to enhance their quality of life by investing in practical home appliances such as vacuum cleaners. As discretionary spending increases, the appeal of vacuum cleaners grows, particularly in urban areas where living spaces tend to be smaller due to the trend towards apartment living. Vacuum cleaners provide an effective solution for maintaining cleanliness in these compact environments, aligning with the urban shift and making them an essential tool for modern living.
Health Awareness Boosting Vacuum Cleaner Adoption
There is a growing consumer awareness of the health implications associated with allergens, asthma, and dust. This heightened sensitivity is propelling the demand for vacuum cleaners equipped with advanced filtration systems, such as HEPA filters, which are capable of trapping fine particles and improving indoor air quality. Additionally, the increasing ownership of pets and busy lifestyles contribute to the accumulation of dust and pet dander, further underscoring the need for efficient cleaning solutions that vacuum cleaners offer to maintain a healthy home environment. For instance, the COVID-19 pandemic positively influenced the growth of the vacuum cleaner market due to growing consumer awareness regarding the use of technologically advanced residential and commercial cleaning equipment.
Innovations and Technological Enhancements in Vacuum Cleaners
The vacuum cleaner market is witnessing significant technological advancements that are introducing more powerful and efficient cleaning solutions. Innovations such as robotic functionality, self-emptying bases, and smartphone app integrations are enhancing the convenience and effectiveness of vacuum cleaners. Furthermore, the development of specialty vacuums designed to address specific needs, such as removing pet hair, cleaning upholstery, or maintaining hard floors, caters to the varied preferences of consumers, providing them with customized cleaning options. For instance, companies like Dyson and Samsung have contributed to the development of more sophisticated models equipped with Artificial Intelligence (AI), LIDAR technology, and complex sensor arrays.
Impact of Marketing and Regulatory Trends Effective marketing strategies that emphasize the importance of a clean living environment and the convenience offered by modern vacuum cleaners are crucial in shaping consumer perceptions and driving sales. Additionally, regulatory focus on energy efficiency and sustainable manufacturing practices across various regions encourages the adoption of environmentally friendly vacuum cleaners. This regulatory landscape, coupled with a growing consumer inclination towards sustainability, fosters a market environment where eco-friendly and energy-saving vacuum designs are increasingly favored. For instance, the vacuum cleaner market is witnessing a significant impact of government regulations and policies as governments across the globe are setting regulatory frameworks for vacuum cleaner manufacturers to lower their energy consumption and develop eco-friendly solutions.
Market Trends
Integration of Advanced Technologies:
The vacuum cleaner market is undergoing a significant transformation driven by the adoption of smart technologies. Robotic vacuum cleaners equipped with features such as app controls, voice assistant integration, and self-emptying bases are revolutionizing cleaning practices. These smart vacuums cater to the increasing consumer demand for convenience and automation, allowing for effortless scheduling and monitoring of cleaning sessions through smartphones and voice commands like Amazon Alexa and Google Assistant. Additionally, advancements in sensor technology are enhancing the mapping and navigation capabilities of robot vacuums, enabling them to operate more efficiently by creating precise virtual maps of homes and systematically avoiding obstacles.
Specialized Features and Sustainable Practices
As consumers become more specific about their cleaning needs, there is a rising demand for specialty vacuums. These include models designed specifically for pet hair, lightweight and cordless options for ease of use across multi-level homes, and vacuums with specialized attachments for different surfaces such as upholstery and hard floors. Moreover, air quality concerns are influencing the market with a push towards vacuums that incorporate advanced filtration systems, such as HEPA filters, to capture allergens and improve indoor air quality. The market is also responding to a growing environmental consciousness among consumers with vacuum cleaners that feature sustainable designs, utilizing recycled materials and energy-efficient configurations. Furthermore, the emergence of subscription-based models offering regular maintenance and replacement parts is creating additional convenience, aligning with the modern consumer’s preference for services that provide value and reduce hassle.
Market Challenges Analysis
Balancing Cost and Innovation in a Competitive Market
In the vacuum cleaner market, particularly in developing regions, affordability remains a pivotal factor influencing consumer decisions. While advanced features such as smart functionalities and self-emptying bases enhance the appeal and functionality of vacuum cleaners, they also escalate costs, potentially limiting market penetration. Manufacturers face the challenge of integrating these innovative features while maintaining price competitiveness to ensure broader accessibility. The key to success in such markets lies in striking an optimal balance between incorporating advanced technology and keeping products economically viable for price-sensitive consumers. Consumers increasingly prefer durable vacuum cleaners that promise longevity, yet the incorporation of complex modern features can complicate repairs and elevate maintenance costs. The challenge extends to basic models where innovation may be stagnant, limiting options for consumers who seek straightforward, budget-friendly cleaning tools. This gap underscores the need for manufacturers to innovate across all product lines, ensuring that even basic models benefit from new technologies that do not compromise durability or inflate costs.
Environmental and Educational Challenges Impact Market Dynamics
The rise of cordless and robotic vacuum cleaners brings to light concerns over electronic waste and the sustainability of manufacturing practices. Planned obsolescence strategies by some manufacturers exacerbate these issues, leading to shorter product lifespans and increased e-waste. The industry must address these environmental challenges by designing products with longer lifespans and promoting recycling programs, which not only comply with regulatory standards but also appeal to the growing consumer base concerned with environmental impact. Despite the availability of vacuums equipped with advanced features like HEPA filters, consumer awareness regarding the benefits of such technologies remains limited. Effective marketing strategies are essential to educate consumers about the advantages of different vacuum types and features, helping them make informed purchasing decisions. Furthermore, providing reliable after-sales service is crucial for building brand trust and ensuring customer satisfaction, especially in a market where competition is intense and consumer loyalty is hard to secure. Establishing robust after-sales support systems and engaging in transparent marketing practices can significantly enhance consumer trust and brand reputation in the vacuum cleaner market.
Market Segmentation Analysis:
By Products:
The vacuum cleaner market is diversified into several product segments including canister, central, drum, robotic, upright, wet and dry, and others. Each type caters to specific consumer needs and applications. Canister vacuums are prized for their versatility and ease of handling, making them suitable for cleaning hard-to-reach areas. Central vacuum systems offer a more permanent solution for larger homes by providing powerful suction and quieter operation. Drum vacuums are typically used in industrial settings for their capacity to handle large amounts of debris and liquid. Robotic vacuums have gained popularity in residential settings for their convenience and advanced features like automated cleaning and navigation systems. Upright vacuums are favored for their effectiveness in cleaning large areas of carpeting, while wet and dry vacuums offer the flexibility to clean both spills and dry dirt. The segment labeled "others" includes handheld and stick vacuums, which are ideal for quick and light cleaning tasks.
By Application:
The application of vacuum cleaners spans industrial, commercial, and residential sectors, each with distinct demands and usage patterns. Industrial applications often require robust vacuum systems with high capacity and power to manage heavy-duty cleaning and debris removal. Commercial settings, including offices, schools, and hotels, typically use upright and canister vacuums that balance power with maneuverability for daily maintenance. Residential use is the largest segment, driven by the increasing demand for convenient and efficient home cleaning solutions. Within this segment, robotic vacuums are becoming increasingly popular due to their automation and time-saving features, whereas upright and canister models remain staples for comprehensive home cleaning. Each application segment pushes development in terms of innovation, with manufacturers continually improving product features like filtration systems, noise reduction, and energy efficiency to meet the specific needs of each market segment.
Segments:
Based on Products:
- Canister
- Central
- Drum
- Robotic
- Upright
- Wet and Dry
- Others
Based on Applications:
- Industrial
- Commercial
- Residential
Based on Distribution Channel:
- Offline
- Online
Based on the Geography:
- North America
- The U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- The U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
The North American region, comprising the United States and Canada, holds a significant market share of approximately 30% in the global vacuum cleaner market. This region's dominance can be attributed to several factors, including the high disposable incomes, the presence of major vacuum cleaner manufacturers, and the growing demand for technologically advanced and energy-efficient cleaning appliances. The United States, in particular, is a major contributor to the regional market's growth due to the widespread adoption of robotic vacuum cleaners and the increasing focus on smart home technologies.
Asia-Pacific
The Asia-Pacific region is the largest and fastest-growing market for vacuum cleaners, capturing a substantial market share of around 35%. Countries such as China, Japan, India, and South Korea are significant contributors to the regional market's expansion. The Asia-Pacific region's rapid urbanization, rising disposable incomes, and changing lifestyle preferences have driven the demand for vacuum cleaners, particularly in the residential sector. Additionally, the region's focus on developing smart cities and the increasing adoption of automated cleaning solutions have further fueled the market's growth.
Key Player Analysis
- Snow Joe LLC
- Panasonic Holdings Corporation
- Nilfisk Group
- Neato Robotics, Inc.
- iRobot Corporation
- Haier Group
- Emerson Electric Co.
- ECOVACS
- Dyson
- DEWALT
Competitive Analysis
In the competitive vacuum cleaner market, leading players such as Dyson, iRobot Corporation, and ECOVACS are at the forefront, primarily due to their strong focus on technological innovation and smart product features like robotic and cordless vacuum cleaners. Dyson continues to lead with its powerful, high-end models known for superior suction and innovative designs. iRobot excels in the robotic vacuum segment, offering advanced navigation and connectivity features. ECOVACS competes closely with iRobot, emphasizing user-friendly robotics and automation. Panasonic and Haier Group leverage their broad electronics expertise to integrate smart home compatibility and energy efficiency. Nilfisk focuses on the commercial and industrial sectors with robust models designed for durability and large-scale cleaning efficiency. Emerson Electric Co., Snow Joe LLC, and DEWALT distinguish themselves with specialized products tailored for specific consumer needs, including outdoor and workshop environments. Together, these companies drive market competition through continuous innovation, quality improvements, and strategic market segmentation.
Recent Developments
In April 2023, The new cord-free Dyson V15 Detect Extra vacuum cleaner has been introduced in India by the multinational electronics company Dyson. It is designed with 230AW and a laser to detect little dust, and it also has whole-machine HEPA filtration to catch ultra-fine particles like pet dander and other contaminants.
In January 2024, Dreame International, Ltd. Introduced its complete range of smart home products at the CES 2024 event. The company unveiled various new smart cleaning appliances, such as DreameBot X30 Ultra, DreameBot L10s Pro Ultra, DreameBot L20 Ultra, Dreame H13 Pro Wet and Dry Vacuum, Dreame Z10 Station Cordless Vacuum Cleaner.
In January 2024, Samsung Electronics Co., Ltd. announced to launch a new vacuum cleaner rangeBespoke Jet Bot Combo, equipped with advanced artificial intelligence features at CES 2024. This new range is a vacuum and mop robot cleaner that offers steam cleaning and improved AI features to help gain an easier cleaning experience for the customers.
In June 2023, Dyson launched the new generation of cord free vacuums with the Dyson Gen5outsize and Gen5detect. The latter is a powerful cordless vacuum that features a fifth-generation Hyperdymium motor, delivering 280 air watts of powerful suction. These machines provide a fully sealed HEPA filtration system designed to collect 99.9% of viruses and 99.99% of particles down to 0.1 microns.
In March 2023, Alfred Kärcher SE & Co. KG launched B 50W new range of scrubber dryers, which is suitable for applications such as showrooms, hospitals, and industrial warehouses.
In February 2023, BISSELL Inc. company launched BISSELL CrossWave HydroSteam, a multi-surface cleaner with in-built 3-in-1 technology of part vacuum, part mop, and part steam cleaner working in unison.
Market Concentration & Characteristics
The vacuum cleaner market exhibits a moderate to high level of market concentration, with a few dominant players such as Dyson, iRobot, and Panasonic leading the industry due to their innovative capabilities, brand recognition, and extensive distribution networks. These key players are instrumental in setting market trends through continuous advancements in technology and product features, such as automation, enhanced filtration systems, and energy efficiency. The market is characterized by fierce competition, particularly in the segments of robotic and cordless vacuum cleaners, where technological enhancements directly influence consumer preference. Additionally, the integration of smart home technology and sustainability considerations are becoming increasingly crucial characteristics, shaping consumer demands and competitive strategies. Smaller companies and new entrants often focus on niche markets or introduce disruptive innovations to gain a foothold. Overall, the market dynamics are driven by technology advancements, brand power, and strategic marketing initiatives.
Report Coverage
The research report offers an in-depth analysis based on Products, Applications, Distribution Channel, and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Continued growth in demand for robotic vacuum cleaners will drive market innovations and consumer adoption.
- Advancements in battery technology will enhance the performance and convenience of cordless vacuum models.
- Integration of AI and machine learning will improve navigation and efficiency in robotic vacuums.
- Consumer demand for eco-friendly and sustainable products will increase, influencing the design and materials used in vacuum cleaners.
- Expansion of smart home ecosystems will lead to more vacuum cleaners being compatible with IoT and voice assistant technologies.
- The development of multi-functional vacuum cleaners that can handle various surfaces and materials will cater to diverse consumer needs.
- Manufacturers will focus on improving filtration systems to address health concerns related to air quality.
- Market competition will intensify as new entrants introduce innovative products at competitive prices.
- Online sales channels will grow, providing greater accessibility and convenience for consumers.
- The trend towards personalized cleaning solutions will lead to customizable features and settings in vacuum cleaners.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Vacuum Cleaner Market?
What factors are driving the growth of the Vacuum Cleaner Market?
What are the key segments within the Vacuum Cleaner Market?
What are some challenges faced by the Vacuum Cleaner Market?
Who are the major players in the Vacuum Cleaner Market?
Which segment is leading the market share?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue) (Volume Where Applicable)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Vacuum Cleaner Scope – Segments & Subsegments Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2023; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 Industry Classification & Applicable Codes
- 1.5 Currency, Measurement Units & Valuation Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Vacuum Cleaner Market Snapshot
- 2.1.1 Market Size – Historical (2023) & Forecast (2023-2032) (2023: USD 11,371.2 million → 2032: USD 28,105.9 million)
- 2.1.2 Volume & Revenue – Global Totals (Volume Where Applicable)
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Vacuum Cleaner Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2023 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2023
- 2.3.2 Top 10 Players by Volume Share – 2023 (Volume Where Applicable)
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Vacuum Cleaner Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Vacuum Cleaner Market Position in the Broader Industry Value Chain
- 3.1.2 Demand Structure & Purchasing Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Vacuum Cleaner Market Drivers
- 3.3 Vacuum Cleaner Market Restraints & Challenges
- 3.4 Vacuum Cleaner Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Vacuum Cleaner Value Chain Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.6.1.1 Key Input/Resource 1
- 3.6.1.2 Key Input/Resource 2
- 3.6.1.3 Key Input/Resource 3
- 3.6.2 Midstream – Core Operations & Value Creation
- 3.6.2.1 Operating Model & Process Overview
- 3.6.2.2 Key Operating Locations & Capabilities by Company
- 3.6.3 Downstream – Market Channels & End Users
- 3.6.3.1 Direct Sales & Customer Engagement Channels
- 3.6.3.2 Indirect Sales, Intermediaries & Partner Channels
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Vacuum Cleaner Supply Chain Analysis
- 3.8.1 Critical Input & Resource Availability Risk Assessment
- 3.8.2 Supplier & Operational Concentration Risk (Geographic Exposure)
- 3.8.3 Supply & Service Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Vacuum Cleaner category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Vacuum Cleaner Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Market Size × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute Revenue Growth Through 2032
- 4.3 Incremental Demand Opportunity
- 4.3.1 By Region – Incremental Demand Through 2032
- 4.3.2 Segment – Incremental Demand
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Priority Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Priority market opportunity scorecards reflect the geographic scope and strategic relevance of the study. Listed markets are indicative and may be adapted to the industry.
Chapter 5. Vacuum Cleaner Cross-Border Trade & Market Access Analysis
- 5.1 International Trade & Cross-Border Activity Overview
- 5.1.1 Global Export Value by Country (2023)
- 5.1.2 Global Export Volume by Country (2023) (Volume Where Applicable)
- 5.1.3 Global Import Value by Country (2023)
- 5.1.4 Global Import Volume by Country (2023) (Volume Where Applicable)
- 5.1.5 Net Trade Balance by Country (2023)
- 5.2 Export Analysis – Segment
- 5.2.1 Category 1 (Applicable Classification Code)
- 5.2.2 Category 2 (Applicable Classification Code)
- 5.2.3 Category 3 (Applicable Classification Code)
- 5.2.4 Category 4 (Applicable Classification Code)
- 5.2.5 Category 5 (Applicable Classification Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Category 1 (Applicable Classification Code)
- 5.3.2 Category 2 (Applicable Classification Code)
- 5.3.3 Category 3 (Applicable Classification Code)
- 5.3.4 Category 4 (Applicable Classification Code)
- 5.3.5 Category 5 (Applicable Classification Code)
- 5.4 Cross-Border Pricing & Transaction Benchmarks
- 5.4.1 Export Pricing – Segment & Country
- 5.4.2 Import Pricing – Segment & Source Country
- 5.4.3 Price Trends (2023)
- 5.5 Key Cross-Border Trade & Delivery Routes
- 5.5.1 Cross-Border Trade/Delivery Route 1
- 5.5.2 Cross-Border Trade/Delivery Route 2
- 5.5.3 Cross-Border Trade/Delivery Route 3
- 5.5.4 Cross-Border Trade/Delivery Route 4
- 5.5.5 Cross-Border Trade/Delivery Route 5
- 5.6 Trade Policy & Market Access Impact Assessment
- 5.6.1 Tariff & Non-Tariff Barriers
- 5.6.2 Regional Trade & Economic Integration Frameworks
- 5.6.3 Bilateral & Multilateral Trade Agreements
- 5.6.4 Cross-Border Operating, Licensing & Localization Requirements
Note: This chapter applies where cross-border trade or delivery is relevant to Vacuum Cleaner. Goods, services, and digital offerings are assessed using applicable classifications and transaction measures. Import-export volumes, trade balances, and route analyses are included only where meaningful to the market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Vacuum Cleaner Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2023
- 6.1.2 Leading, Mid-Sized & Emerging Player Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Vacuum Cleaner Market Share Analysis – 2023
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company (Volume Where Applicable)
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2023)
- 6.2.5 Company Market Share by Key Segment
- 6.2.6 Company Market Share by Customer Group
- 6.3 Operating Scale, Capacity & Infrastructure Analysis
- 6.3.1 Global Operating Scale & Supply Capacity
- 6.3.2 Resource Utilization & Operating Efficiency
- 6.3.3 Output, Service Delivery & Activity Metrics
- 6.3.4 Operating Footprint & Infrastructure Map
- 6.3.5 Planned Operational & Capacity Expansion
- 6.4 Vacuum Cleaner Competitive Benchmarking Matrix
- 6.4.1 Revenue, Growth, Profitability & Operating Metric Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Vacuum Cleaner (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Products, Services & Solutions in Vacuum Cleaner
- 6.5.3 Operational & Infrastructure Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Vacuum Cleaner Market – By Sales & Delivery Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2023 & 2032) (Volume Where Applicable)
- 7.1.2 Channel Mix Evolution (2023-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share (Volume Where Applicable)
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region (Volume Where Applicable)
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Sales & Delivery Channel
- 8.2.2 By Competitive Positioning & Price Tier
Chapter 9. North America Vacuum Cleaner Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Vacuum Cleaner Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Vacuum Cleaner Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Vacuum Cleaner Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Vacuum Cleaner Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Vacuum Cleaner Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Vacuum Cleaner Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Supply, Output & Operating Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Demand, Adoption & Usage Assumptions
- Appendix F – Pricing & Revenue Metric Reference Tables
- Appendix G – Company Operations & Infrastructure Database
- Appendix H – Cross-Border Trade & Activity Data Tables (Where Applicable)
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
