
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Vehicle Cameras Market Size 2024 | USD 8,811.5 million |
| Vehicle Cameras Market , CAGR | 11.4% |
| Vehicle Cameras Market Size 2032 | USD 20,899.28 million |
Market Overview
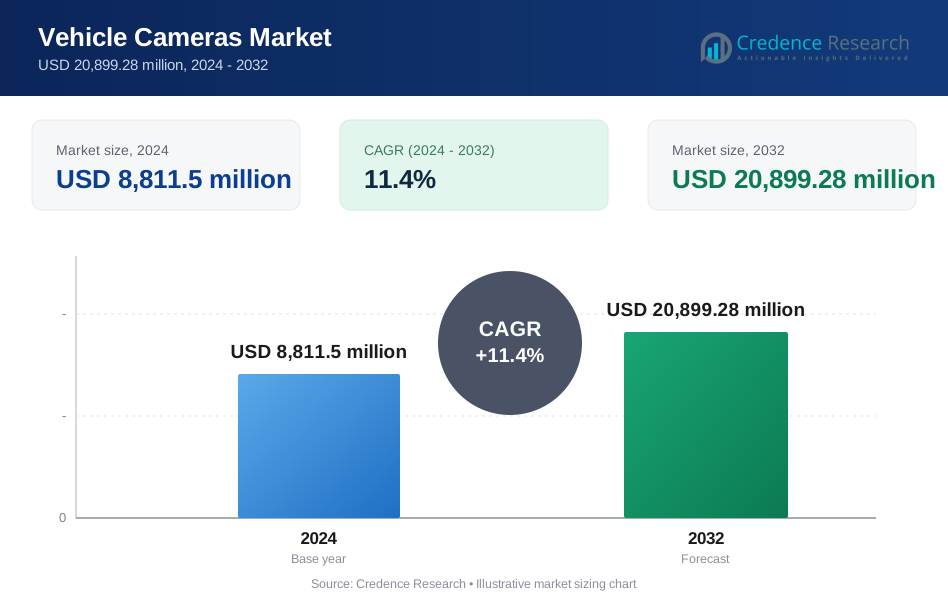
The global vehicle cameras market is projected to grow from USD 8,811.5 million in 2024 to USD 20,899.28 million by 2032, registering a CAGR of 11.4% during the forecast period.
The vehicle cameras market is driven by increasing demand for advanced driver assistance systems (ADAS) and enhanced road safety measures. Rising concerns over vehicular accidents and regulatory mandates for in-vehicle camera installations are boosting adoption across passenger and commercial vehicles. Technological advancements, including high-definition imaging, AI-powered analytics, and night vision capabilities, are enhancing camera functionalities and driving market growth. The growing popularity of electric and autonomous vehicles is further fueling the need for sophisticated camera systems. Additionally, the rising trend of integrating dashcams for insurance claims and fleet management solutions contributes to the market's expanding scope.
The vehicle cameras market is expanding globally, with significant growth in regions such as North America, Europe, and Asia-Pacific. North America, driven by advanced automotive technology and stringent safety regulations, remains a key market. Europe follows closely, with increasing demand for high-resolution cameras in both passenger and commercial vehicles. In the Asia-Pacific region, the market is driven by rising automobile production and the adoption of advanced driver-assistance systems (ADAS). Key players in the market include S. Will Industrial, GoPro, Garmin, Transcend Information, Pittasoft, and Qrontech, among others. These companies are innovating to meet evolving consumer and regulatory demands.
Market Drivers
Growth in Automotive Sales and Production
The global automotive industry is experiencing robust growth, with increasing vehicle production and sales contributing to the expanding demand for vehicle cameras. As manufacturers prioritize equipping vehicles with advanced safety technologies to meet consumer expectations, the market for camera systems continues to grow. For instance, a report by Deloitte highlighted that global vehicle sales are expected to surpass 92 million units in 2024, reflecting a strong recovery and growth in the automotive sector. The surge in automobile production, particularly in emerging markets, further strengthens the demand for vehicle cameras, making them a standard feature in both passenger and commercial vehicles.
Stringent Safety Regulations
Governments worldwide are enforcing stringent regulations to enhance road safety, which has positively influenced the adoption of vehicle cameras. For instance, the National Highway Traffic Safety Administration (NHTSA) in the United States mandates the inclusion of rear-view cameras in new vehicles to minimize accidents. Similar regulations in Europe and Asia-Pacific markets underscore the critical role of vehicle cameras in meeting safety standards, driving market growth on a global scale.
Increasing Demand for Advanced Driver Assistance Systems (ADAS)
The rising emphasis on vehicle safety has significantly boosted the adoption of Advanced Driver Assistance Systems (ADAS), which rely heavily on vehicle cameras. Features like lane departure warning, blind spot detection, and collision avoidance are becoming standard in modern vehicles, meeting consumer demand for enhanced safety. These camera-dependent systems play a critical role in improving driving accuracy, reducing accidents, and ensuring compliance with safety standards, thus driving the integration of vehicle cameras across automotive segments.
Technological Advancements and Rising Disposable Incomes
Technological advancements in camera systems, including higher-resolution sensors, improved image processing, and night vision capabilities, are enhancing their applications in autonomous vehicles and advanced safety features. Simultaneously, rising disposable incomes empower consumers to invest in premium vehicles equipped with sophisticated safety technologies, including advanced camera systems. This combination of technological innovation and growing purchasing power ensures a steady increase in the adoption of vehicle cameras across diverse vehicle segments.
Market Trends
Increasing Demand for Advanced Systems and Autonomous Vehicles
The rising adoption of Advanced Driver Assistance Systems (ADAS) is a key driver for the vehicle camera market. Features such as lane departure warning, blind spot detection, and automatic emergency braking rely heavily on camera technology to enhance driver safety and convenience. As consumers increasingly prioritize vehicle safety, the demand for ADAS-equipped vehicles continues to grow, fueling the integration of advanced camera systems. For instance, a survey by HERE Technologies found that 91% of Indian drivers believe ADAS is crucial for enhancing road safety. Similarly, the rise of autonomous vehicles further amplifies this demand. Self-driving cars depend on a comprehensive suite of sensors, including high-resolution cameras, to accurately perceive their surroundings. These multi-camera systems enable precise navigation, object recognition, and real-time decision-making, making them indispensable for the development of autonomous driving technologies. Together, the demand for ADAS and autonomous vehicle advancements is accelerating the evolution of the vehicle camera industry.
Technological Innovations and Market Expansion
Technological advancements, such as the adoption of 360-degree cameras and the integration of artificial intelligence (AI), are transforming the vehicle camera market. The popularity of 360-degree camera systems, which provide drivers with a complete view around the vehicle, is steadily increasing across both passenger and commercial vehicles. Simultaneously, AI-powered vehicle cameras are revolutionizing safety features with capabilities like object recognition, traffic sign identification, and driver monitoring, making vehicles smarter and safer. The growing demand for high-resolution cameras, which improve the accuracy of ADAS and autonomous systems, further highlights the shift toward enhanced imaging technologies. Additionally, night vision technology is gaining prominence, offering improved visibility in low-light conditions and enhancing safety in regions with extended periods of darkness. Alongside these innovations, the expanding aftermarket presents opportunities for consumers to upgrade their vehicles with advanced camera systems, driving further growth in the industry.
Market Challenges Analysis
Environmental and Lighting Challenges
Vehicle cameras face significant challenges from environmental and lighting conditions, which can impact their reliability and performance. Adverse weather, such as rain, snow, fog, and extreme temperatures, poses difficulties for cameras to maintain consistent functionality. Additionally, dirt, dust, and other debris can obstruct camera lenses, reducing their effectiveness. Lighting conditions further complicate performance, especially in low-light and nighttime scenarios where visibility is limited, and glare from artificial or natural light sources can degrade image quality. High-contrast environments, such as direct sunlight, require advanced image processing to ensure accurate detection and clarity. Overcoming these challenges requires continuous innovation in camera hardware and software to enhance resilience and adaptability in diverse conditions.
Integration, Cybersecurity, and Cost Considerations
Integrating vehicle cameras into modern systems presents its own set of hurdles. Precise calibration and synchronization of multiple cameras are essential for accurate environmental perception, especially in applications like ADAS and autonomous driving. Furthermore, processing and fusing data from various cameras demand robust hardware and efficient algorithms, increasing system complexity. Cybersecurity adds another layer of concern, as connected cameras are vulnerable to cyberattacks that can compromise vehicle safety and user privacy. Ensuring data protection is critical as cameras capture sensitive information. Cost remains a pressing challenge; high development and production expenses for advanced systems can limit affordability for consumers, particularly in emerging markets. Additionally, evolving and region-specific regulatory standards complicate global product development, requiring manufacturers to constantly adapt. Addressing these challenges involves a combination of advanced technology, cost-effective production, and adherence to dynamic regulations.
Market Segmentation Analysis:
By Prices
The vehicle camera market is segmented into affordable, mid-range, and high-end categories, catering to various consumer needs and budgets. The affordable segment is driven by the growing demand for basic safety features, such as rear-view cameras, in entry-level vehicles. As safety regulations become more stringent, even low-cost vehicles are increasingly equipped with essential camera systems. The mid-range segment is experiencing significant growth, fueled by the adoption of advanced driver assistance systems (ADAS) in mainstream vehicles, offering features like lane departure warning and blind-spot monitoring. High-end vehicle cameras cater to luxury vehicles, providing high-resolution imaging, 360-degree camera systems, and sophisticated features such as night vision and autonomous driving capabilities. As technology advances, high-end camera systems are becoming more widely available, pushing down costs and making them more accessible in premium vehicle segments.
By End User
The vehicle camera market is also segmented by end user, including law enforcement and defense vehicles, private vehicles, transportation vehicles, and others. Law enforcement and defense vehicles require robust, high-performance camera systems for surveillance, navigation, and safety. These vehicles often integrate specialized cameras with real-time data analytics for enhanced situational awareness. The private vehicle segment is witnessing widespread adoption of vehicle cameras, driven by increasing safety concerns and consumer preferences for ADAS and parking assistance systems. Transportation vehicles, including buses, trucks, and delivery vehicles, also contribute significantly to the market, as fleet owners seek to improve safety, monitor driver behavior, and enhance operational efficiency. Additionally, the "others" segment includes niche applications such as off-road vehicles and industrial machinery, where cameras are used for monitoring and safety purposes. Each of these end-user categories has unique requirements, pushing demand for customized and advanced vehicle camera solutions.
Segments:
Based on Prices:
- Affordable
- Mid-range
- High-end
Based on End User:
- Law Enforcement and Defense Vehicles
- Private Vehicles
- Transportation Vehicles
- Others
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
North America holds a substantial share of the market, accounting for approximately 38%. This growth is primarily driven by the increasing adoption of advanced driver assistance systems (ADAS) in the region, along with stringent safety regulations mandating the installation of rear-view cameras in all new vehicles. The strong presence of major automakers, coupled with the high demand for luxury and high-end vehicles equipped with advanced camera systems, is propelling the market forward. Additionally, the growing trend of autonomous vehicle development and the rising consumer demand for enhanced safety features contribute to the region’s dominance in the vehicle camera market. The adoption of high-resolution and multi-camera systems for applications like parking assistance, collision avoidance, and 360-degree views is expected to continue driving the market growth in North America.
Europe
In contrast, the European vehicle camera market is also witnessing robust growth, with a market share of approximately 30%. Europe is home to several automotive manufacturing giants, and the demand for advanced vehicle cameras is increasing, especially in countries like Germany, France, and the UK. The stringent regulations set by the European Union regarding vehicle safety and the mandatory installation of cameras in certain vehicle categories are driving the adoption of vehicle cameras across the region. Additionally, the rising popularity of electric vehicles (EVs) and autonomous driving technologies is boosting the demand for high-end camera systems in Europe. The trend towards integrating vehicle cameras with artificial intelligence (AI) for enhanced vehicle safety and driver assistance systems is further fueling market growth. As technological advancements continue to evolve, Europe is expected to maintain a significant share in the global vehicle camera market.
Key Player Analysis
- Will Industrial, Ltd.
- GoPro, Inc.
- Garmin International, Inc.
- Transcend Information, Inc.
- Pittasoft Co., Ltd.
- Hyundai MnSOFT
- AIPTEK International, Inc.
- Qrontech Co., Ltd. (Lukas)
- DCS Systems Ltd. (RoadHawk U.K.)
Competitive Analysis
The vehicle camera market is highly competitive, with several key players vying for dominance through technological innovation and product offerings. Companies like Qrontech Co., Ltd. (Lukas), S. Will Industrial, Inc., AIPTEK International, Inc., Hyundai MnSOFT, GoPro, Inc., Pittasoft Co., Ltd., DCS Systems Ltd. (RoadHawk U.K.), Garmin International, Inc., and Transcend Information, Inc. are all pushing the envelope in terms of camera capabilities, including higher resolutions, advanced image processing, and AI integration. These players focus on offering specialized solutions for various segments, from law enforcement and defense vehicles to private and transportation vehicles. The market's competitive nature is further driven by the demand for cost-effective solutions, with some companies offering budget-friendly options while others cater to the premium market. As regulatory standards around vehicle safety and ADAS grow stricter, these companies are leveraging innovation and strategic partnerships to stay ahead and meet evolving customer needs.
Recent Developments
- In January 2023, Nexar, Inc. is a dash cam manufacturing company, launched a Pro GPS dual dash camera Max with high quality 1080p full of HD image sensors. Regarding the quality of the footage, it’s crisp and clear. Critical details, such as vehicle number plates and faces, are easily identifiable. This kinds of camera will now be preferred in the market over the other low quality cameras
- In January 2023, Amazon.com Inc., Amazons’ Ring division introduced its first car dashboard camera. The device named Ring Car Cam can record both inside and outside of the vehicle. The product has sensors to detect motion within the vehicle and external disturbances such as if the car is hit or broken into.
- In September 2022, ContinentalTechnology Company opened its new, state-of-the-art automotive manufacturing facility in New Braunfels, Texas. The purpose of the new building is to expand its capacity to produce radar sensors in advanced driver assistance systems (ADAS).
Market Concentration & Characteristics
The vehicle camera market is moderately concentrated, with a few key players dominating the landscape. These players are actively driving innovation, particularly in advanced features such as high-resolution imaging, AI integration, and enhanced night vision technology. While large companies like Garmin, GoPro, and Hyundai MnSOFT lead the market with a broad range of offerings, there is still significant space for smaller players to innovate, especially in niche applications like law enforcement or commercial fleets. The market is characterized by increasing demand for camera systems integrated with Advanced Driver Assistance Systems (ADAS) and autonomous vehicles. As consumers become more safety-conscious, the shift towards higher-quality, feature-rich systems is evident. Additionally, there is a growing trend towards the adoption of 360-degree and multi-camera solutions, which provide a more comprehensive view of a vehicle's surroundings. The market is also influenced by regional regulations, pushing manufacturers to adapt their products to meet specific standards.
Report Coverage
The research report offers an in-depth analysis based on Prices, End User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The demand for vehicle cameras will continue to rise with the growing adoption of Advanced Driver Assistance Systems (ADAS).
- Increased integration of artificial intelligence and machine learning will enhance the functionality of vehicle cameras.
- The market will see a shift toward higher resolution cameras to improve safety features and image quality.
- Growth in autonomous vehicle development will drive the need for multi-camera systems to ensure precise environmental perception.
- The expansion of 360-degree camera systems will become more prevalent in both passenger and commercial vehicles.
- The development of night vision and thermal cameras will improve safety during low-light and adverse weather conditions.
- Aftermarket vehicle camera solutions will see significant growth as consumers seek to upgrade vehicle safety features.
- Regulatory pressures across different regions will drive the adoption of standard camera systems in all new vehicles.
- With rising disposable incomes, consumers will increasingly invest in high-end camera systems for enhanced safety.
- The rise of connected vehicle ecosystems will create new opportunities for vehicle cameras to interact with other in-car technologies.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Growth in Automotive Sales and Production
The global increase in vehicle production and sales, especially in emerging markets, is driving the demand for vehicle cameras as manufacturers equip more vehicles with advanced safety technologies.
Stringent Safety Regulations
Government mandates, such as the requirement for rear-view cameras in new vehicles in the US and similar regulations in Europe and Asia-Pacific, are compelling automakers to integrate camera systems, boosting market growth.
Rising Adoption of Advanced Driver Assistance Systems (ADAS)
The proliferation of ADAS features like lane departure warning, blind spot detection, and collision avoidance, all of which rely on vehicle cameras, is accelerating the integration of camera systems across automotive segments.
Technological Advancements in Camera Systems
Innovations such as high-definition imaging, AI-powered analytics, 360-degree views, and night vision capabilities are enhancing camera performance and expanding their applications in both conventional and autonomous vehicles.
Increasing Demand for Fleet Management and Insurance Solutions
The use of dashcams and multi-camera systems for fleet monitoring, driver behavior analysis, and insurance claims is expanding, particularly in commercial and transportation vehicles, further fueling market adoption.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Vehicle Cameras Market?
What factors are driving the growth of the Vehicle Cameras Market?
What are the key segments within the Vehicle Cameras Market?
What are some challenges faced by the Vehicle Cameras Market?
Who are the major players in the Vehicle Cameras Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Prices
- 1.2.1 Affordable
- 1.2.2 Mid-range
- 1.2.3 High-end
- 1.3 By End User
- 1.3.1 Law Enforcement and Defense Vehicles
- 1.3.2 Private Vehicles
- 1.3.3 Transportation Vehicles
- 1.3.4 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 8,811.5 million → 2032: USD 20,899.28 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Vehicle Cameras Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Vehicle Cameras Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Vehicle Cameras Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Vehicle Cameras Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Vehicle Cameras Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Vehicle Cameras Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 Global Vehicle Cameras Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Vehicle Cameras Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 8,811.5 million → 2032: USD 20,899.28 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Vehicle Cameras Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Prices - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Affordable
- 12.3.7.2 Mid-range
- 12.3.7.3 High-end
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By End User - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Law Enforcement and Defense Vehicles
- 12.4.7.2 Private Vehicles
- 12.4.7.3 Transportation Vehicles
- 12.4.7.4 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global Vehicle Cameras End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Vehicle Cameras Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Vehicle Cameras Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Vehicle Cameras Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Will Industrial, Ltd.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 GoPro, Inc.
- 18.4 Garmin International, Inc.
- 18.5 Transcend Information, Inc.
- 18.6 Pittasoft Co., Ltd.
- 18.7 Hyundai MnSOFT
- 18.8 AIPTEK International, Inc.
- 18.9 Qrontech Co., Ltd. (Lukas)
- 18.10 DCS Systems Ltd. (RoadHawk U.K.)
- 18.11 Nexar, Inc.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

