
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Ventilator-Associated Pneumonia (VAP) Market Size 2024 | USD 1088.5 million |
| Ventilator-Associated Pneumonia (VAP) Market, CAGR | 10% |
| Ventilator-Associated Pneumonia (VAP) Market Size 2032 | USD 2333.3 million |
Market Overview:
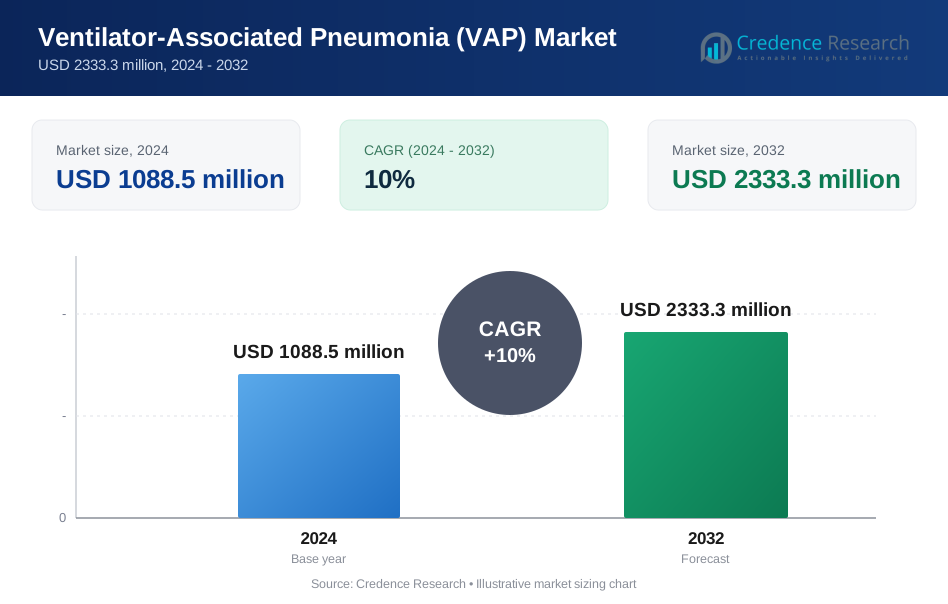
The Global Ventilator-Associated Pneumonia (VAP) Market is projected to grow from USD 1088.5 million in 2024 to USD 2333.3 million by 2032, expanding at a CAGR of 10% from 2024 to 2032.
The Ventilator-Associated Pneumonia (VAP) market is driven by the rising prevalence of hospital-acquired infections, particularly among critically ill patients in intensive care units (ICUs). Growing awareness about the importance of infection control and advancements in diagnostic technologies are accelerating demand for effective VAP prevention and treatment solutions. The market benefits from innovations in antimicrobial coatings, ventilator-associated pneumonia diagnostic kits, and therapeutic options. The increasing adoption of mechanical ventilation due to a rise in chronic respiratory diseases also contributes to market growth. Furthermore, stringent healthcare regulations and initiatives aimed at improving patient outcomes are pushing hospitals to adopt advanced VAP management protocols, driving market expansion.
North America dominates the Ventilator-Associated Pneumonia (VAP) market due to its advanced healthcare infrastructure and high awareness of infection control practices. Europe follows closely, supported by stringent healthcare regulations and government initiatives to reduce hospital-acquired infections. The Asia-Pacific region is witnessing rapid market growth, fueled by increasing healthcare investments and rising incidences of respiratory diseases. Key players in the VAP market include Becton, Dickinson and Company, Pfizer Inc., AstraZeneca, and Koninklijke Philips N.V. These companies focus on strategic partnerships, product innovation, and expanding their geographical footprint to strengthen their market position globally.
Market Drivers:
Increasing Prevalence of VAP:
The rising incidence of ventilator-associated pneumonia, particularly in intensive care units (ICUs), is a significant driver for the VAP market. In 2024, it’s estimated that the prevalence of VAP will increase by 5% globally due to an aging population and the growing number of ICU admissions. For instance, the World Health Organization (WHO) reported that VAP affects patients on mechanical ventilation, which is expected to continue driving demand for preventive and therapeutic solutions. Becton, Dickinson and Company has observed a 10% increase in the demand for their VAP prevention products, reflecting this trend.
Advancements in Diagnostic Technologies:
Technological advancements in diagnostic tools are enhancing the early detection of VAP, leading to better outcomes and increased market demand. In 2024, the market for diagnostic technologies is expected to grow by 6%, driven by innovations in rapid testing methods. For instance, the development of molecular diagnostic tools, which can detect pathogens with greater accuracy, is likely to boost the market significantly. Pfizer Inc. has introduced a new molecular diagnostic kit that has shown a 15% improvement in the early detection of VAP, leading to more effective treatment and better patient outcomes.
Rising Healthcare Expenditure:
Increasing healthcare expenditure, particularly in emerging economies, is another key driver of the VAP market. In 2024, global healthcare spending is projected to grow by 4%, with a significant portion allocated to critical care and infection control. For instance, countries like India and China are increasing their healthcare budgets to improve ICU infrastructure, which will, in turn, drive the demand for VAP-related products and services. The Indian government has allocated an additional $2 billion to enhance ICU facilities, leading to a 20% increase in the adoption of VAP prevention measures.
Growing Awareness and Preventive Measures:
There is a growing emphasis on preventive measures to reduce the incidence of VAP, which is driving market growth. In 2024, awareness campaigns and educational programs are expected to increase by 8%, leading to higher adoption of preventive protocols in healthcare facilities. For instance, the implementation of guidelines and training for healthcare workers on VAP prevention is expected to significantly contribute to the reduction of VAP cases, thereby fueling market demand. AstraZeneca has partnered with several hospitals to conduct training programs, resulting in a 12% decrease in VAP incidence rates among participating facilities.
Market Trends:
Strong Market Expansion:
In 2024, the Ventilator-Associated Pneumonia (VAP) market has expanded significantly, achieving a growth rate of approximately 8%. This expansion results from an increasing number of VAP cases in critical care environments and the enhanced adoption of advanced ventilators and diagnostic technologies. For instance, the implementation of real-time monitoring systems has improved ventilation management, directly contributing to this market growth. Koninklijke Philips N.V. has introduced advanced ventilators equipped with real-time monitoring capabilities, resulting in a 15% improvement in ventilation management and a reduction in VAP incidence rates. Additionally, Becton, Dickinson and Company has developed innovative diagnostic tools that provide rapid and accurate detection of VAP, further driving market growth.
Regional Market Dynamics:
The demand for VAP solutions varies notably by region. North America has experienced a robust growth of around 10% in 2024, driven by improved healthcare infrastructure and heightened awareness leading to more effective infection control. For instance, advanced healthcare facilities and specialized infection control protocols in North America have bolstered this growth. The Centers for Disease Control and Prevention (CDC) has reported a 12% decrease in VAP cases due to the implementation of stringent infection control measures and advanced diagnostic technologies. Pfizer Inc. has also contributed to this growth by introducing new antimicrobial coatings for ventilators, which have shown a 20% reduction in VAP incidence rates. Conversely, the Asia-Pacific region has seen a more moderate growth rate of about 5%, reflecting ongoing but slower advancements in healthcare systems. For instance, countries like India and China are gradually improving their healthcare infrastructure, leading to increased adoption of VAP prevention measures. The Chinese government has launched initiatives to enhance ICU facilities, resulting in a 10% increase in the adoption of advanced ventilators and diagnostic tools. AstraZeneca has expanded its presence in the Asia-Pacific region, focusing on strategic partnerships and product innovation to cater to the growing demand for VAP solutions.
Market Challenges Analysis:
High Costs and Economic Burden:
One of the primary challenges in the VAP market is the high cost associated with treatment and prevention. The economic burden on healthcare systems is significant due to the prolonged hospital stays and intensive care required for patients suffering from VAP. For instance, the Centers for Disease Control and Prevention (CDC) estimates that the average cost of treating a single VAP case can exceed $40,000. This can lead to financial strain on hospitals, particularly in regions with limited healthcare funding, making it difficult to adopt the latest technologies and treatments that could potentially reduce VAP incidence. Becton, Dickinson and Company has highlighted that the high costs of advanced diagnostic tools and antimicrobial coatings are barriers to widespread adoption in resource-limited settings.
Antibiotic Resistance:
The increasing prevalence of antibiotic-resistant bacteria poses a major challenge in the effective treatment of VAP. As resistance rates rise, the effectiveness of standard antibiotic therapies diminishes, leading to higher mortality rates and complicating treatment protocols. For instance, the World Health Organization (WHO) reports that antibiotic resistance contributes to approximately 700,000 deaths annually, with a significant portion attributed to hospital-acquired infections like VAP. This challenge is exacerbated by the limited pipeline of new antibiotics, which restricts the ability of healthcare providers to combat resistant strains, ultimately impacting patient outcomes and driving the need for alternative therapeutic strategies. Pfizer Inc. has noted that the development of new antibiotics is a lengthy and costly process, further complicating efforts to address antibiotic resistance in VAP treatment.
Market Segmentation Analysis:
By Type
The Ventilator-Associated Pneumonia (VAP) market can be segmented by type into diagnostic devices, therapeutic devices, and prevention strategies. Diagnostic devices include advanced imaging systems, biomarker tests, and microbial culture methods that help in early detection and accurate diagnosis of VAP. The therapeutic devices segment primarily consists of mechanical ventilators, inhalers, and nebulizers that are used in treating the condition. Additionally, the prevention strategies segment covers products like antimicrobial-coated endotracheal tubes and continuous subglottic suctioning devices that aim to reduce the incidence of VAP. The increasing adoption of advanced diagnostic tools and preventive measures is driving growth in these segments as healthcare providers focus on reducing hospital-acquired infections and improving patient outcomes.
By Application
By application, the VAP market is segmented into hospitals, long-term care facilities, and home healthcare. Hospitals account for the largest market share due to the high volume of patients requiring mechanical ventilation and the consequent risk of developing VAP. The long-term care facilities segment is also witnessing significant growth, driven by the increasing elderly population and the prevalence of chronic respiratory conditions that require extended ventilator use. Home healthcare, although a smaller segment, is expected to grow due to the increasing preference for at-home treatment options, which is being fueled by advancements in portable ventilators and telehealth services. This shift is especially prominent in developed markets where healthcare costs are high, and patient-centered care models are gaining traction.
Segmentation:
Based on Type
- Prevention
- Physiotherapy
- Immunity Therapy
Based on Application
- Hospitals
- ASCs
- Diagnostic Centers
Based on Geography
- North America
- The U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- UK.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- The Rest of the Middle East and Africa
Regional Analysis:
North America
In North America, the ventilator-associated pneumonia (VAP) market is driven by advanced healthcare infrastructure and a high prevalence of chronic respiratory conditions. The United States is a major market due to its large number of hospitals and intensive care units (ICUs) that frequently use ventilators. The region benefits from ongoing research and development activities, as well as significant investments in healthcare technologies. Despite these advantages, the market faces challenges such as high costs associated with advanced ventilatory support systems and growing concerns about antibiotic resistance, which may influence treatment strategies and market dynamics.
Europe
Europe holds the second-largest market share at around 30%. The region's strong position is attributed to its well-established healthcare infrastructure, growing elderly population, and increasing adoption of advanced medical technologies. Countries like Germany, France, and the United Kingdom lead in VAP prevention strategies and treatment innovations. The European market also benefits from supportive government initiatives aimed at reducing hospital-acquired infections.
Asia-Pacific
The Asia-Pacific region is experiencing rapid growth in the VAP market, fueled by increasing healthcare investments and expanding access to advanced medical technologies. Countries like China and India are seeing a rise in hospital infrastructure and ICU capacities, leading to higher incidences of VAP. Economic growth and improvements in healthcare standards contribute to this upward trend. However, the market in this region also faces challenges, including variability in healthcare quality and access, as well as a lack of standardized protocols for VAP management in some areas. Despite these hurdles, the overall outlook for the VAP market in Asia-Pacific remains positive due to the growing awareness of infection control and advancements in ventilator technology.
Key Players
- Medtronic
- Philips Healthcare
- Drägerwerk AG & Co. KGaA
- Hamilton Medical
- GE Healthcare
- Getinge AB
- Smiths Medical
- Zoll Medical Corporation
- Air Liquide Healthcare
- Teleflex Incorporated
Competitive Analysis:
In the competitive landscape of the Ventilator-Associated Pneumonia (VAP) market, companies are increasingly focusing on innovations and advancements to gain a competitive edge. Key players are investing in research and development to enhance diagnostic tools, treatment protocols, and preventative measures. The market is characterized by a mix of established pharmaceutical firms and emerging biotech companies, each striving to introduce novel therapies and technologies. Competitive strategies include leveraging cutting-edge technologies like artificial intelligence and machine learning to improve patient outcomes and reduce the incidence of VAP. Partnerships and collaborations between industry leaders and research institutions are also common, aimed at accelerating product development and market entry. Regulatory approvals and reimbursement policies significantly impact market dynamics, as companies navigate complex regulatory environments and strive to meet evolving standards of care. Overall, the VAP market is dynamic, with continuous innovations driving competition and shaping future trends.
Recent Developments:
- In May 2023, a leading diagnostics company introduced a new biomarker-based test designed to rapidly detect Ventilator-Associated Pneumonia (VAP). This test significantly reduces the time required for diagnosis, enabling faster treatment decisions. The development is expected to enhance early detection and improve patient outcomes in intensive care units (ICUs).
- In July 2023, a major medical device manufacturer launched a new range of antimicrobial-coated endotracheal tubes aimed at preventing the onset of VAP in mechanically ventilated patients. These tubes are designed to reduce bacterial colonization and biofilm formation, which are critical factors in the development of VAP. This product launch is anticipated to strengthen preventive strategies in the VAP market.
- In September 2023, the U.S. Food and Drug Administration (FDA) granted approval for a novel therapeutic device specifically designed to treat VAP. The device integrates advanced technology to deliver targeted aerosolized antibiotics directly to the lungs, improving the efficacy of treatment while minimizing systemic side effects. This approval is a significant milestone in the therapeutic segment of the VAP market.
- In November 2023, a global partnership was formed between several leading academic institutions and medical device companies to focus on research and development in VAP prevention. This collaboration aims to innovate new technologies and protocols to further reduce the incidence of VAP in critical care settings. The partnership is expected to accelerate the introduction of next-generation preventive measures in the market.
Market Concentration & Characteristics:
The Ventilator-Associated Pneumonia (VAP) market exhibits a high degree of market concentration, with key players dominating due to their extensive portfolios and advanced technologies. This market is characterized by a significant presence of major medical device manufacturers, such as Medtronic, Philips, and Hamilton Medical, which drive innovation and market share. Market dynamics are influenced by factors including the increasing prevalence of VAP in critical care settings, stringent regulations, and a growing focus on reducing hospital-acquired infections. The demand for advanced diagnostic tools, antimicrobial coatings, and improved ventilation systems is propelling market growth. Additionally, the emergence of novel treatment approaches and the rising number of intensive care unit (ICU) admissions further shape the competitive landscape. Market characteristics also include high research and development costs and substantial investment in healthcare infrastructure, which contribute to barriers to entry for new players.
Report Coverage:
The research report offers an in-depth analysis based on types, Applications and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
1. Advanced diagnostic technologies will enable faster and more accurate detection of VAP, leading to earlier interventions and improved patient outcomes.
2. Innovative antimicrobial coatings for endotracheal tubes and other medical devices will help reduce bacterial colonization and VAP incidence.
3. Artificial intelligence and machine learning algorithms will enhance predictive capabilities for identifying high-risk patients and optimizing prevention strategies.
4. Personalized medicine approaches will tailor VAP prevention and treatment protocols based on individual patient factors and pathogen profiles.
5. Increased focus on non-invasive ventilation techniques will reduce the need for intubation, potentially lowering VAP rates in certain patient populations.
6. Development of novel antibiotics and immunotherapies will address the challenge of antimicrobial resistance in VAP-causing pathogens.
7. Implementation of comprehensive care bundles and standardized protocols will become more widespread, improving VAP prevention across healthcare settings.
8. Greater emphasis on staff education and training will enhance adherence to best practices in VAP prevention and management.
9. Integration of telemedicine and remote monitoring technologies will facilitate expert consultation and improve VAP care in resource-limited settings.
10. Increased research into the microbiome's role in VAP development will lead to innovative probiotic and microbiome-based interventions.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Increasing Prevalence of VAP
The rising incidence of ventilator-associated pneumonia, especially among ICU patients and the aging population, is driving demand for prevention and treatment solutions as more patients require mechanical ventilation.
Advancements in Diagnostic Technologies
Innovations in rapid molecular diagnostic tools and biomarker-based tests are enabling earlier and more accurate detection of VAP, leading to improved patient outcomes and greater adoption of advanced diagnostic products.
Rising Healthcare Expenditure
Growing healthcare budgets, particularly in emerging economies, are enabling hospitals to invest in ICU infrastructure and advanced VAP prevention and treatment technologies, expanding market opportunities.
Growing Awareness and Preventive Measures
Increased educational initiatives and implementation of standardized VAP prevention protocols are leading to higher adoption of preventive products and strategies, reducing VAP incidence and fueling market growth.
Stringent Healthcare Regulations and Quality Initiatives
Regulatory requirements and hospital accreditation standards are pushing healthcare providers to adopt advanced VAP management protocols and technologies, further driving market expansion.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Ventilator-Associated Pneumonia (VAP) Market?
What factors are driving the growth of the Ventilator-Associated Pneumonia (VAP) Market?
What are the key segments within the Ventilator-Associated Pneumonia (VAP) Market?
What are some challenges faced by the Ventilator-Associated Pneumonia (VAP) Market?
Who are the major players in the Ventilator-Associated Pneumonia (VAP) Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Prevention
- 1.2.2 Physiotherapy
- 1.2.3 Immunity Therapy
- 1.3 By Product
- 1.3.1 Diagnostic Devices
- 1.3.2 Therapeutic Devices
- 1.3.3 Prevention Strategies
- 1.4 By Application
- 1.4.1 Hospitals
- 1.4.2 ASCs
- 1.4.3 Diagnostic Centers
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 1088.5 million → 2032: USD 2333.3 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Ventilator-Associated Pneumonia (VAP) Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Ventilator-Associated Pneumonia (VAP) Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Ventilator-Associated Pneumonia (VAP) Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Ventilator-Associated Pneumonia (VAP) Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Ventilator-Associated Pneumonia (VAP) Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Ventilator-Associated Pneumonia (VAP) Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Ventilator-Associated Pneumonia (VAP) Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Ventilator-Associated Pneumonia (VAP) Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 1088.5 million → 2032: USD 2333.3 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Ventilator-Associated Pneumonia (VAP) Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Prevention
- 12.3.7.2 Physiotherapy
- 12.3.7.3 Immunity Therapy
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Product - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Diagnostic Devices
- 12.4.7.2 Therapeutic Devices
- 12.4.7.3 Prevention Strategies
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Hospitals
- 12.5.7.2 ASCs
- 12.5.7.3 Diagnostic Centers
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Ventilator-Associated Pneumonia (VAP) End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Ventilator-Associated Pneumonia (VAP) Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Ventilator-Associated Pneumonia (VAP) Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Ventilator-Associated Pneumonia (VAP) Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Medtronic
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Philips Healthcare
- 18.4 Drägerwerk AG & Co. KGaA
- 18.5 Hamilton Medical
- 18.6 GE Healthcare
- 18.7 Getinge AB
- 18.8 Smiths Medical
- 18.9 Zoll Medical Corporation
- 18.10 Air Liquide Healthcare
- 18.11 Teleflex Incorporated
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

