
Market Overview
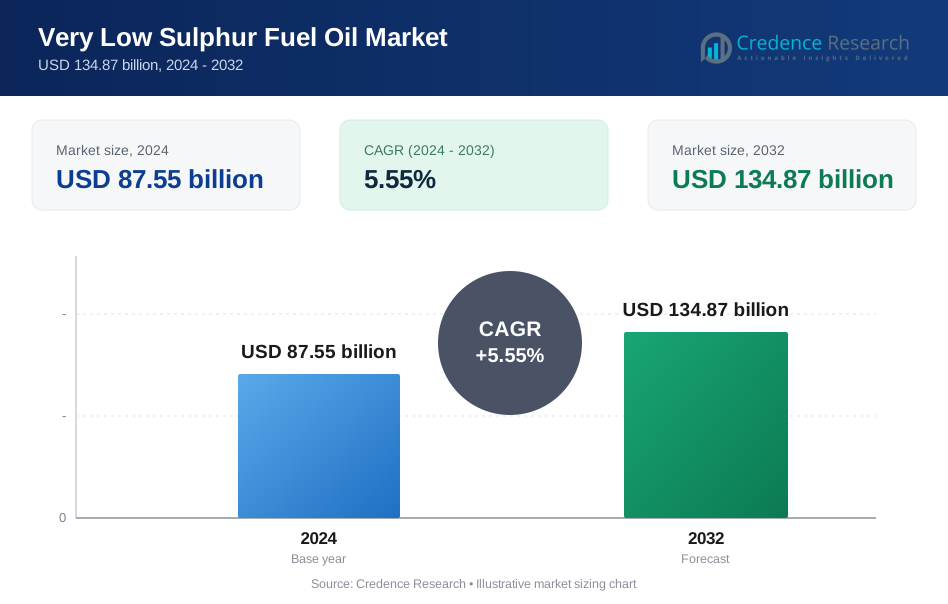
The Very Low Sulphur Fuel Oil (VLSFO) Market was valued at USD 87.55 billion in 2024 and is anticipated to reach USD 134.87 billion by 2032, expanding at a CAGR of 5.55% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Very Low Sulphur Fuel Oil Market Size 2024 | USD 87.55 billion |
| Very Low Sulphur Fuel Oil Market, CAGR | 5.55% |
| Very Low Sulphur Fuel Oil Market Size 2032 | USD 134.87 billion |
The Very Low Sulphur Fuel Oil Market grows with rising maritime trade and strict environmental regulations that limit sulphur emissions. Shipping companies adopt VLSFO to comply with International Maritime Organization rules while ensuring uninterrupted operations.
The Very Low Sulphur Fuel Oil Market demonstrates strong growth across North America, Europe, Asia Pacific, Latin America, and the Middle East & Africa, each shaped by regional regulations and trade flows. North America benefits from advanced refining capacity and a well-established shipping sector, while Europe emphasizes compliance with strict environmental rules and sustainability goals. Asia Pacific emerges as a key demand hub, driven by heavy shipping traffic and expanding port infrastructure in China, India, and Southeast Asia. Latin America and the Middle East & Africa show gradual growth through increasing crude exports and government-backed investments in cleaner fuel adoption. Key players driving the market include BP, Exxon Mobil, Chevron, Saudi Aramco, and Indian Oil, each focusing on refining upgrades, supply chain integration, and strategic collaborations to expand global footprints. Their strong presence ensures reliability of supply and innovation in fuel quality to meet evolving industry demands.

Market Insights
- The Very Low Sulphur Fuel Oil Market was valued at USD 87.55 billion in 2024 and is projected to reach USD 134.87 billion by 2032, growing at a CAGR of 5.55% during the forecast period.
- The market grows with rising demand for cleaner marine fuels, supported by strict IMO 2020 regulations and global sustainability initiatives.
- Key trends include a shift toward hybrid fuel solutions, digital monitoring of fuel efficiency, and increasing refinery investments in desulphurization units to enhance compliance.
- Competitive dynamics remain strong, with leading players such as BP, Exxon Mobil, Chevron, Saudi Aramco, and Indian Oil focusing on supply chain integration, refining capacity expansion, and strategic partnerships to strengthen market presence.
- High refining and operational costs, coupled with limited availability of compliant fuels in certain regions, act as restraints that challenge consistent supply.
- North America and Europe lead adoption due to strict environmental policies and well-established port facilities, while Asia Pacific shows the fastest growth with strong shipping demand in China, India, and Southeast Asia.
- Emerging opportunities arise in Latin America and the Middle East & Africa, where growing crude exports, port infrastructure upgrades, and government-backed clean fuel initiatives support future market expansion.
Market Drivers
Stringent Environmental Regulations and IMO 2020 Implementation
The Very Low Sulphur Fuel Oil Market benefits directly from international maritime regulations enforcing reduced sulphur emissions. The International Maritime Organization’s (IMO) 2020 mandate restricted sulphur content in marine fuels to 0.5%, down from 3.5%. It pushed ship operators to shift from high sulphur fuel oil to VLSFO as a primary compliant alternative. This regulatory change drives consistent demand growth across global shipping fleets. Governments worldwide reinforce such standards with penalties for non-compliance, further securing long-term adoption. The transition has reshaped fuel supply chains, positioning VLSFO as a dominant marine fuel option.
- For instance, BP was a major supplier of IMO 2020-compliant Very Low Sulphur Fuel Oil (VLSFO) and other compliant marine fuels in key ports like Singapore and Rotterdam, and globally, following the rule change on January 1, 2020. The company actively marketed these fuels and stated they had a 'robust commercial offer' to support customer compliance.
Rising Global Shipping and Trade Activities
The Very Low Sulphur Fuel Oil Market grows strongly with expansion in international shipping volumes. Global trade recovery after disruptions increases fuel consumption in container ships, tankers, and bulk carriers. It supports rising VLSFO demand as shipping companies seek reliable fuel that ensures compliance and efficiency. Port expansions and investments in logistics corridors further enhance fuel consumption patterns. Freight operators prioritize stable and compliant fuel supplies, which strengthens adoption. The steady increase in seaborne trade volumes underpins demand for VLSFO across developed and emerging regions.
- For instance, ExxonMobil is a key supplier of VLSFO through its global bunkering network, with an active presence in major hubs like Rotterdam and Singapore. The company has publicly confirmed its successful delivery of compliant marine fuels, including marine biofuel oils, to major shipping customers.
Increasing Preference for Cleaner Marine Fuels
The Very Low Sulphur Fuel Oil Market benefits from a shift in consumer and industry preference toward environmentally friendly fuel options. Shipping companies focus on reducing carbon intensity and air pollutants to align with sustainability goals. It positions VLSFO as a practical solution before full-scale adoption of LNG, methanol, or hydrogen fuels. Demand grows in parallel with the need to balance compliance, performance, and affordability. Maritime operators view VLSFO as a transitional fuel that bridges traditional oil-based products and alternative fuels. The preference for cleaner solutions secures its role in current and near-term energy strategies.
Expanding Refinery Adaptations and Supply Capabilities
The Very Low Sulphur Fuel Oil Market benefits from significant refinery investments to optimize production capacity. Refineries adapt their operations to meet growing demand for low-sulphur blends through desulphurization units and residue upgrading processes. It ensures reliable availability of compliant fuel across major ports worldwide. Supply chain improvements reduce cost pressures and enhance operational reliability for shipping companies. Large refining hubs in Asia, Europe, and the Middle East expand their output capacity to support global VLSFO requirements. The growing adaptability of refineries ensures consistent availability and strengthens market stability.
Market Trends
Shift Toward Blended Fuel Formulations
The Very Low Sulphur Fuel Oil Market reflects a growing trend in blended formulations to optimize performance. Refineries mix low-sulphur feedstocks with residual fuels to meet IMO 2020 compliance standards. It creates fuels with better combustion properties and reduced environmental impact. Shipping operators increasingly prefer these blends for consistent engine efficiency. Blended fuels also help stabilize prices by reducing reliance on costly refining processes. This trend ensures flexibility in meeting diverse operational requirements across vessels of different sizes.
- For instance, In late 2019, the Singapore Refining Company (SRC), a joint venture in which Chevron holds a 50% stake, began supplying very low-sulfur fuel oil (VLSFO) in Singapore in preparation for the IMO 2020 regulations. As a marine fuel provider, Chevron offers VLSFO and other products to shipping companies in Singapore and other major ports.
Integration of Digital Tools in Fuel Management
The Very Low Sulphur Fuel Oil Market shows rising adoption of digital platforms for fuel monitoring and supply chain optimization. Shipowners use IoT and AI-driven solutions to track fuel consumption, emissions, and quality in real time. It enables predictive maintenance and reduces unexpected downtime during voyages. Data-driven insights support better procurement strategies and help companies control operational costs. The use of blockchain systems also enhances transparency in marine fuel transactions. This trend reflects the sector’s focus on improving efficiency through technology integration.
- For instance, In June 2020, BP's shipping unit partnered with Windward, a maritime trade analytics and insights company. This collaboration was intended to accelerate digitalization by leveraging AI and behavioral analytics for its operations.
Growing Investments in Port Infrastructure and Bunkering Facilities
The Very Low Sulphur Fuel Oil Market benefits from increasing expansion of port infrastructure and bunkering hubs. Major ports across Asia, Europe, and the Middle East upgrade facilities to ensure reliable VLSFO supply. It supports smoother operations for international shipping companies that rely on consistent fuel access. Investment in storage and blending units further strengthens the global supply chain. Shipping operators gain confidence in adopting VLSFO when bunkering facilities expand coverage across trade routes. This trend highlights the strategic role of ports in enabling smooth adoption of low-sulphur fuels.
Transitional Role Between Conventional Fuels and Alternative Marine Energy
The Very Low Sulphur Fuel Oil Market trends toward acting as a bridge between traditional fuels and next-generation energy sources. Shipping companies continue to explore LNG, biofuels, and hydrogen for long-term decarbonization. It maintains VLSFO as a preferred option until alternative fuels scale up commercially. Shipowners view VLSFO as a practical solution for compliance while preparing for future energy shifts. Its transitional role ensures steady demand despite growing focus on greener technologies. This trend underscores the importance of VLSFO in balancing immediate compliance and long-term sustainability goals.
Market Challenges Analysis
High Production Costs and Supply Constraints
The Very Low Sulphur Fuel Oil Market faces challenges due to costly refining processes and supply limitations. Refineries must invest in desulphurization units and blending facilities to produce compliant fuels. It increases operating expenses and narrows profit margins for producers. Smaller refiners struggle to maintain competitiveness against integrated players with larger capacities. Limited availability of low-sulphur crude adds pressure on supply chains and creates pricing volatility. Shipping operators often face higher procurement costs when global demand surges. These cost and supply challenges restrict smooth adoption across emerging maritime hubs.
Engine Compatibility and Performance Concerns
The Very Low Sulphur Fuel Oil Market also encounters difficulties linked to vessel engine compatibility. VLSFO has variable viscosity and stability, which can affect engine performance if not managed properly. It forces shipowners to invest in fuel testing and monitoring systems to prevent breakdowns. Poor fuel quality may cause deposit formation, filter blockages, or reduced efficiency during long voyages. Maritime operators report inconsistent availability of standardized VLSFO blends across different regions. This variability complicates global shipping operations and raises operational risks. The industry continues to seek uniform quality standards to ensure reliable vessel performance.
Market Opportunities
Rising Demand from Global Shipping and Maritime Trade
The Very Low Sulphur Fuel Oil Market presents opportunities through expanding maritime trade and stricter environmental mandates. International Maritime Organization regulations continue to enforce low sulphur limits, creating steady demand for compliant fuels. It enables shipping companies to maintain global operations without penalties while supporting sustainability goals. Growing container traffic and bulk carrier activities drive stronger consumption in major ports. Emerging economies increase their seaborne trade, strengthening VLSFO adoption across Asia and Latin America. This shift positions VLSFO as a critical fuel in international shipping’s transition to cleaner operations.
Innovation in Blending and Refinery Investments
The Very Low Sulphur Fuel Oil Market benefits from refinery upgrades and innovation in fuel blending technologies. Producers explore optimized blends with improved viscosity, stability, and compatibility to address engine performance concerns. It creates opportunities for refiners to capture long-term supply contracts with shipping companies. Global refiners expand investments in hydrocrackers and desulphurization units to increase production capacity. Collaborations between refiners and shipping operators help establish uniform quality standards across regions. Advancements in fuel formulation open pathways for VLSFO to remain a reliable choice while alternative fuels develop.
Market Segmentation Analysis:
By Source
The Very Low Sulphur Fuel Oil Market divides into refinery direct output and blended fuel categories. Refinery direct output remains significant due to large-scale desulphurization processes that ensure consistent quality and compliance with IMO regulations. It provides shipping operators with reliable performance in marine engines and reduces risks of incompatibility. Blended fuel gains traction as refiners and suppliers mix low sulphur components to meet demand flexibility. Traders and distributors often use blending to adjust availability in key maritime hubs, improving supply chain efficiency. This dual-source structure strengthens market resilience while meeting diverse operator requirements across regions.
- For instance, ExxonMobil’s Singapore refinery, with a nameplate capacity of about 592,000 barrels per day of distillation, supports large-scale production of cleaner marine fuels to meet IMO requirements.
By Viscosity Grade
Viscosity segmentation in the Very Low Sulphur Fuel Oil Market highlights demand for both high-viscosity and low-viscosity grades. High-viscosity fuels serve large vessels, including container ships and bulk carriers, where heavy-duty engine performance is essential. It ensures steady combustion under high operational loads while maintaining compliance. Low-viscosity grades are preferred for smaller vessels and engines requiring lighter fuels, offering smoother handling and reduced maintenance concerns. Shipping operators increasingly demand flexibility in viscosity grades to adapt to different engine types and operational routes. Market participants expand their portfolios to provide both grades, ensuring wider adoption across global fleets.
- For instance, BP Marine supplied very low sulfur fuel oil (VLSFO) and other marine fuels in 2022, offering both IMO-compliant VLSFO (≤0.5% sulfur) and higher-sulfur fuel options for vessels equipped with scrubbers. While tailored blends to meet specific viscosity requirements, like IFO 180 and IFO 380 grades, were a standard part of its global supply.
By Sulphur Content
The Very Low Sulphur Fuel Oil Market focuses on fuels with sulphur content below 0.5% in line with IMO 2020 mandates. Strict adherence to this benchmark drives compliance among international shipping companies. It ensures reduced emissions of sulphur oxides, improving air quality and lowering environmental risks. Some markets also explore ultra-low sulphur fuel oils with sulphur levels below 0.1% to meet Emission Control Area standards. Shipping operators in North America and Europe demand these stricter grades, creating opportunities for refiners with advanced desulphurization capabilities. This segment reflects how regulatory pressure and environmental goals define product development and supply priorities in the market.
Segments:
Based on Source
- Refinery
- Hydrocracker
Based on Viscosity Grade
- IFO 180
- IFO 380
- MGO
Based on Sulphur Content
- 5% Sulfur
- 1% Sulfur
Based on Application
- Main Engine
- Auxiliary Engine
- Boiler
Based on End-User
- Shipping
- Power Generation
- Industrial Boilers
- Others
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis
North America
North America holds nearly 23% share of the Very Low Sulphur Fuel Oil Market, supported by advanced port infrastructure and strict environmental compliance standards. The United States leads adoption, with major maritime hubs such as Houston and Los Angeles driving strong demand. It benefits from the enforcement of Emission Control Area (ECA) rules along U.S. and Canadian coasts, which require ultra-low sulphur content fuels. Canada contributes with shipping routes through the Atlantic and Pacific coasts, where compliance remains a priority. Mexico also plays a role as an emerging fuel supply hub, supporting both regional trade and transoceanic shipping. Investments in refining upgrades across the U.S. Gulf Coast strengthen availability of compliant fuels. This regional strength reflects a blend of regulatory enforcement, modern refining capacity, and extensive maritime trade routes.
Europe
Europe accounts for around 27% share of the Very Low Sulphur Fuel Oil Market, reflecting its strong focus on environmental sustainability and regulatory alignment. Major ports in Rotterdam, Antwerp, and Hamburg anchor demand by serving as global bunkering hubs. It benefits from strict European Union directives on sulphur emissions and the implementation of ECAs in the North Sea and Baltic Sea. Southern European ports in Spain, Italy, and Greece also contribute significantly due to heavy container traffic and energy trade flows. Ship operators in Europe increasingly adopt ultra-low sulphur fuel oils, with content below 0.1%, to meet stricter ECA regulations. Refiners in the region continue to adapt production lines to balance demand for both high-viscosity and lighter blends. Europe’s strong regulatory environment and strategic shipping corridors ensure its continued importance in the market.
Asia Pacific
Asia Pacific dominates with about 34% share of the Very Low Sulphur Fuel Oil Market, making it the largest regional segment. China, Singapore, and Japan lead consumption, supported by their roles as global shipping and bunkering hubs. Singapore stands out as the world’s largest bunkering port, where VLSFO supply volumes exceed 40 million tonnes annually. China drives regional demand with its extensive industrial base, large shipping fleet, and major export activity. Japan and South Korea also maintain strong demand through technologically advanced fleets and compliance-focused maritime operators. India contributes by expanding refining capacity and supporting trade routes across the Indian Ocean. The region’s scale, combined with rapid industrialization and growing international trade, cements Asia Pacific as the central driver of global VLSFO adoption.
Latin America
Latin America represents roughly 8% share of the Very Low Sulphur Fuel Oil Market, with Brazil, Panama, and Mexico acting as leading contributors. Brazil’s extensive oil trade and container traffic create steady demand at ports like Santos and Rio de Janeiro. It benefits from refining investments that allow local producers to supply compliant fuels. Panama plays a strategic role as the operator of the Panama Canal, where global shipping companies rely on VLSFO for compliance. Mexico contributes further with Gulf of Mexico ports supplying regional and transatlantic shipping routes. Other countries, including Chile and Argentina, also record rising demand from energy and commodity exports. Latin America’s market continues to develop with a focus on expanding refining capacity and bunkering infrastructure.
Middle East and Africa
The Middle East and Africa together account for nearly 8% share of the Very Low Sulphur Fuel Oil Market. The United Arab Emirates and Saudi Arabia dominate regional activity due to strong refining capacity and strategic port locations. Fujairah in the UAE stands as one of the world’s top bunkering hubs, supplying millions of tonnes of VLSFO annually. It benefits from regional investments in refinery upgrades designed to meet IMO 2020 requirements. Saudi Arabia supports demand through major shipping routes in the Red Sea and Arabian Gulf. In Africa, South Africa leads with port activity in Durban and Cape Town, where global shipping companies refuel. Nigeria and Egypt also contribute with growing regional bunkering facilities. This region’s share highlights its importance as a supply hub connecting Asia, Europe, and Africa through global maritime corridors.
Key Player Analysis
- Indian Oil
- Rosneft
- Marathon Petroleum
- Saudi Aramco
- Mediterranean Fuels
- Exxon Mobil
- Hindustan Petroleum
- Phillips 66
- Chevron
- BP
Competitive Analysis
The competitive landscape of the Very Low Sulphur Fuel Oil Market features major players such as BP, Chevron, Exxon Mobil, Hindustan Petroleum, Indian Oil, Marathon Petroleum, Mediterranean Fuels, Phillips 66, Rosneft, and Saudi Aramco. These companies dominate the market through extensive refining capacities, global distribution networks, and investments in advanced desulphurization technologies. They focus on meeting International Maritime Organization (IMO) 2020 sulphur regulations by producing fuels with improved stability, efficiency, and lower emissions. Strategic initiatives such as expanding marine bunkering facilities, securing supply agreements with shipping companies, and upgrading refineries enable them to strengthen their competitive positions. Many players invest in blending operations and hybrid fuel solutions to address varying demand across shipping routes and regional markets. Sustainability also remains a core focus, with firms integrating carbon reduction goals and cleaner production processes into their long-term strategies. Intense competition drives continuous innovation in product quality, supply chain efficiency, and cost management, ensuring reliable supply to global maritime operators while maintaining compliance with evolving environmental standards.
Recent Developments
- In August 2025, Saudi Aramco reported 100% supply reliability in the first half of 2025, underscoring exceptional fuel continuity for maritime customers and consistent energy delivery across its network.
- In May 2025, Mediterranean Fuels expanded its product portfolio, now offering both VLSFO 0.5% and ULSFO 0.1% grades at select Mediterranean ports.
- In May 2025, ExxonMobil completed a successful sea trial of its marine bio fuel oil (a VLSFO blended with second-generation FAME) aboard a Stena Bulk tanker in Rotterdam, which demonstrated a CO₂ emission reduction of up to 40%, and will be launched later this year in select ports.
- In May 2025, Industry-wide (Mediterranean region) VLSFO market share is projected to shrink from 55% to around 21% in response to Emission Control Area regulations, while low-sulphur alternatives like MGO and ULSFO gain prominence
Report Coverage
The research report offers an in-depth analysis based on Source, Viscosity Grade, Sulphur Content, Application, End-User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand will rise steadily as global shipping volumes escalate and sulphur regulations become more stringent.
- Refiners will expand desulphurization capabilities to meet growing needs for compliant marine fuels.
- VLSFO will maintain its role as the primary marine fuel as the sector awaits scalable alternative fuels.
- Blended fuel formulations will gain prominence for improved stability and better engine compatibility.
- Digital fuel monitoring and supply tracking will increase adoption to ensure quality and traceability.
- Port expansions and enhanced bunkering infrastructure will boost global accessibility of VLSFO.
- Refineries in emerging economies will upgrade to serve growing regional demand for low-sulphur fuel.
- Collaboration between shipping operators and fuel providers will support smoother transitions and supply reliability.
- Demand for ultra-low sulphur blends will grow in Emission Control Areas where stricter limits apply.
- VLSFO will serve as a bridge fuel while industry scales up future-ready fuels like LNG, biofuels, and hydrogen.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Stringent Environmental Regulations and IMO 2020 Implementation
The enforcement of the International Maritime Organization’s 2020 mandate, which limits sulphur content in marine fuels to 0.5%, has compelled global shipping fleets to adopt VLSFO, driving consistent demand as operators seek compliance and avoid penalties.
Rising Global Shipping and Trade Activities
The recovery and expansion of international shipping volumes, including container ships, tankers, and bulk carriers, increase fuel consumption and underpin the need for reliable, compliant marine fuels like VLSFO across major trade routes.
Increasing Preference for Cleaner Marine Fuels
Shipping companies are prioritizing fuels that reduce carbon intensity and air pollutants, positioning VLSFO as a practical transitional solution that balances compliance, performance, and affordability while the industry prepares for alternative fuels.
Expanding Refinery Adaptations and Supply Capabilities
Significant investments in refinery upgrades, desulphurization units, and blending facilities are enhancing the global supply of VLSFO, ensuring availability and supporting market stability as demand grows.
Port Infrastructure and Bunkering Expansion
Upgrades and expansions of port infrastructure and bunkering hubs, especially in Asia Pacific and the Middle East, are improving global accessibility and supply reliability of VLSFO, encouraging broader adoption by international shipping operators.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Very Low Sulphur Fuel Oil, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Very Low Sulphur Fuel Oil market projected to grow between 2025 and 2032?
What are the primary factors fueling the growth of the Very Low Sulphur Fuel Oil market?
Who are the leading companies in the Very Low Sulphur Fuel Oil market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Source
- 1.2.1 Refinery
- 1.2.2 Hydrocracker
- 1.2.3 Blended Fuel
- 1.3 By Application
- 1.3.1 Main Engine
- 1.3.2 Auxiliary Engine
- 1.3.3 Boiler
- 1.4 By Sulphur Content
- 1.4.1 0.5% Sulfur
- 1.4.2 0.1% Sulfur
- 1.5 By Viscosity Grade
- 1.5.1 IFO 180
- 1.5.2 IFO 380
- 1.5.3 MGO
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 87.55 billion → 2032: USD 134.87 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Very Low Sulphur Fuel Oil Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Very Low Sulphur Fuel Oil Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Very Low Sulphur Fuel Oil Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Very Low Sulphur Fuel Oil Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Very Low Sulphur Fuel Oil Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Very Low Sulphur Fuel Oil Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Very Low Sulphur Fuel Oil Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Very Low Sulphur Fuel Oil Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 87.55 billion → 2032: USD 134.87 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Very Low Sulphur Fuel Oil Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Source - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Refinery
- 12.3.7.2 Hydrocracker
- 12.3.7.3 Blended Fuel
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Main Engine
- 12.4.7.2 Auxiliary Engine
- 12.4.7.3 Boiler
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Sulphur Content - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 0.5% Sulfur
- 12.5.7.2 0.1% Sulfur
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Viscosity Grade - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 IFO 180
- 12.6.7.2 IFO 380
- 12.6.7.3 MGO
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Very Low Sulphur Fuel Oil End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Very Low Sulphur Fuel Oil Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Very Low Sulphur Fuel Oil Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Very Low Sulphur Fuel Oil Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 BP
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Exxon Mobil
- 18.4 Chevron
- 18.5 Saudi Aramco
- 18.6 Indian Oil
- 18.7 Rosneft
- 18.8 Marathon Petroleum
- 18.9 Hindustan Petroleum
- 18.10 Phillips 66
- 18.11 Mediterranean Fuels
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

