
Market Overview
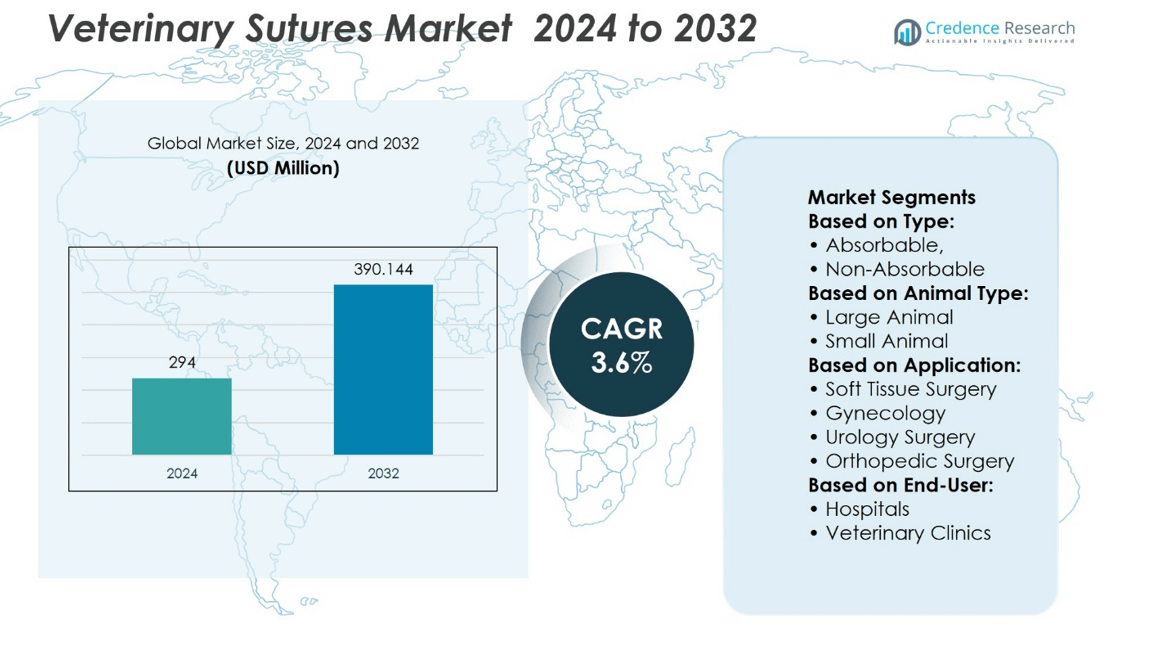
The Global Veterinary Sutures Market size was valued at USD 294 million in 2024 and is anticipated to reach USD 390.144 million by 2032, at a CAGR of 3.6% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Veterinary Sutures Market Size 2024 | USD 294 million |
| Veterinary Sutures Market, CAGR | 3.6% |
| Veterinary Sutures Market Size 2032 | USD 390.144 million |
The Veterinary Sutures Market is driven by the rising number of surgical procedures in companion animals and livestock, fueled by increased pet ownership and advancements in veterinary care. Growing awareness of animal health, expanding veterinary infrastructure, and demand for minimally invasive surgeries further support market growth. Additionally, the development of absorbable and antimicrobial sutures enhances surgical outcomes and reduces complications. Market trends include a shift toward biodegradable and synthetic suture materials, along with technological innovations that improve suture strength and handling. Manufacturers are also focusing on customizable suture solutions tailored to different animal types and surgical needs.
North America dominates the Veterinary Sutures Market due to advanced veterinary infrastructure, high pet ownership, and increased spending on animal healthcare. Europe follows closely, driven by stringent animal welfare regulations and growing demand for surgical interventions. The Asia-Pacific region is witnessing rapid growth owing to rising awareness and expanding veterinary services. Key players in the market include Medtronic PLC, DemeTech, Teleflex Inc., UNIFY Sutures, Vitrex Surgical, and AmerisourceBergen Corporation, all focusing on innovation and strategic collaborations to strengthen market presence.
Market Insights
- The Veterinary Sutures Market was valued at USD 294 million in 2024 and is expected to reach USD 390.144 million by 2032, growing at a CAGR of 3.6% during the forecast period.
- Rising pet adoption and increasing surgical interventions in animals are significantly boosting market demand.
- There is a growing trend toward using absorbable, antimicrobial, and biodegradable sutures for better post-operative outcomes.
- Leading players like Medtronic PLC, Teleflex Inc., and DemeTech are investing in advanced product lines and global distribution strategies.
- High costs associated with veterinary surgeries and lack of skilled professionals in emerging markets may limit growth.
- North America holds the largest market share due to robust veterinary infrastructure, while Asia-Pacific shows the fastest growth.
- Market players are focusing on developing customizable suture materials tailored to specific animal types and surgical procedures.
Market Drivers
Increased Companion Animal Surgeries Drive Demand for Advanced Suture Materials
The growing volume of surgical procedures in pets is a key driver of the Veterinary Sutures Market. Rising pet ownership and improved access to veterinary care have led to a higher number of orthopedic, soft tissue, and spay-neuter surgeries. Clinics increasingly seek sutures that support faster healing and lower infection risks. Absorbable and antimicrobial sutures are gaining preference in clinical settings. Manufacturers are focusing on providing sterile, biocompatible materials tailored for different animal sizes and tissue types. It encourages product innovation that aligns with diverse surgical requirements.
- For instance, Ethicon (a Johnson & Johnson company) manufactures VICRYL RAPIDE™ sutures, which retain approximately 50% of their tensile strength at 5 days and are fully absorbed by hydrolysis within 42 days. In 2022, Ethicon’s animal health division supported over 2.7 million veterinary surgical procedures worldwide, with its suture products accounting for nearly 38 million linear meters sold globally.
Livestock Health Programs and Regulatory Support Promote Suture Usage
Government-funded livestock healthcare initiatives support the adoption of high-quality sutures across rural and commercial veterinary practices. Disease management and surgical interventions under national animal health programs boost demand for reliable wound closure products. The Veterinary Sutures Market benefits from these efforts by expanding its reach in developing regions. Regulatory bodies promote the use of approved suture materials to maintain animal safety during surgeries. Standardized protocols require durable and non-reactive sutures to reduce post-operative complications. It ensures consistent procurement across public and private veterinary facilities.
- For instance, under India’s National Animal Disease Control Programme (NADCP), more than 19,200,000 livestock were treated surgically between 2021 and 2023 across state-run veterinary hospitals.
Veterinary Practice Modernization and Hospital Infrastructure Expansion Accelerate Product Uptake
The modernization of veterinary hospitals and clinics creates a structured demand for surgical consumables, including sutures. New facilities integrate advanced surgical units requiring precision wound closure materials. The Veterinary Sutures Market gains traction as hospitals adopt minimally invasive and laparoscopic techniques. These methods require specialized sutures compatible with sensitive procedures. Clinics prioritize products that reduce operation time and improve wound management efficiency. It strengthens partnerships between suture manufacturers and veterinary networks
Rising Demand for Specialty Animal Care Encourages Use of Tailored Sutures
Specialty practices in oncology, cardiology, and neurology demand suture products that support delicate tissue handling and secure closure. The rise in elective procedures in pets and exotic animals expands the need for custom suture solutions. It drives manufacturers to design materials with controlled absorption rates and tensile strength. The Veterinary Sutures Market adapts to species-specific needs, including cats, dogs, horses, and small mammals. Clinics select sutures that match anatomical and procedural requirements. Surgeons rely on high-performance materials that minimize tissue trauma.
Market Trends
Shift Toward Absorbable and Antimicrobial Sutures Enhances Post-Surgical Outcomes
Veterinarians increasingly prefer absorbable sutures due to their ability to degrade naturally without the need for removal. These sutures reduce stress on animals and minimize follow-up visits, especially in rural or large-animal settings. Antimicrobial coatings are also gaining attention for their role in lowering infection risks during recovery. The Veterinary Sutures Market sees innovation in this area, with products tailored for improved wound healing and reduced inflammatory response. It reflects a broader industry push for safer, more efficient surgical materials. Clinics are adopting these solutions to streamline patient care and support faster healing.
- For instance, Ethicon’s VICRYL RAPIDE™ (polyglactin 910) sutures retain approximately half of initial tensile strength at five days post‑implantation and are fully absorbed by the body within 42 days, as validated in subcutaneous implantation studies on rats.
Product Customization Aligns with Species-Specific Surgical Needs
Manufacturers are developing suture products designed for specific animal categories, including small pets, large livestock, and exotic species. Differences in tissue strength, anatomy, and movement patterns require tailored solutions. The Veterinary Sutures Market incorporates materials with variable tensile strength, needle types, and absorption profiles to match procedure types. It encourages surgeons to adopt sutures that reduce risk of breakage or irritation. Clinics prefer options that align with the anatomical demands of each case. Demand is rising for kits and bundled products that simplify surgical preparation.
- For instance, Ethicon offers VICRYL RAPIDE™ (polyglactin 910) in multiple USP sizes-from USP 8/0 up to USP 0-with needle‑thread configurations optimized for smaller species such as rabbits and felines; one version.
Surge in Minimally Invasive and Laparoscopic Procedures Influences Material Choices
Modern veterinary practices are integrating minimally invasive techniques, driving the need for compatible suture products. These procedures often require finer sutures that allow precise closure in restricted spaces. The Veterinary Sutures Market responds with micro-gauge and monofilament materials designed for reduced tissue drag. It supports enhanced visibility and control during procedures. Manufacturers focus on providing sterile, preloaded needle options for quick application. This trend aligns with growing expectations for low-complication recovery.
Veterinary Education and Skill Development Shape Product Adoption Patterns
Training programs and continuing education initiatives are increasing awareness of advanced suturing techniques. Surgeons are learning to differentiate materials based on factors like knot security, tissue reaction, and handling ease. The Veterinary Sutures Market benefits from this trend by aligning product features with practitioner preferences. It allows for broader uptake across both entry-level and specialist facilities. Clinical workshops promote the use of innovative materials in real-world scenarios. This shift drives knowledge-based procurement across hospitals and independent practices.
Market Challenges Analysis
Limited Standardization and Regulatory Variations Restrict Product Consistency
Variations in veterinary regulations across regions create inconsistencies in product approval and usage standards. Many countries lack unified guidelines for veterinary surgical materials, which affects the adoption of advanced suture technologies. Clinics in rural or under-resourced areas often rely on general surgical sutures rather than those developed specifically for animals. This inconsistency limits the overall effectiveness of surgical outcomes and increases the risk of complications. The Veterinary Sutures Market must navigate fragmented regulatory environments and address the gap in clinical training on proper suture selection. It creates challenges for manufacturers trying to offer globally accepted, compliant products. Delays in approval processes and variations in quality control also hinder product availability in emerging markets.
Cost Sensitivity and Low Awareness Impact Advanced Product Adoption
High-quality veterinary sutures with specialized coatings or absorption properties often carry premium pricing, which limits access in price-sensitive markets. Many veterinary practices, especially smaller clinics, continue to prioritize cost over performance. It creates a barrier to the widespread adoption of innovative sutures that could improve clinical outcomes. Awareness about the long-term benefits of using species-specific and procedure-specific sutures remains low in several regions. The Veterinary Sutures Market must invest in practitioner education and demonstrate measurable clinical benefits to encourage adoption. Limited budgets, especially in livestock care, further restrict demand for advanced materials. It makes balancing affordability and performance a continuing challenge for both manufacturers and end-users.
Market Opportunities
Expansion of Companion Animal Care and Elective Surgeries Creates New Product Demand
The growing focus on pet wellness and preventive healthcare opens significant opportunities for advanced suture products. Rising demand for elective procedures such as sterilization, dental surgeries, and tumor removals increases the need for reliable wound closure materials. Clinics seek sutures that improve healing and reduce the risk of post-operative infections. The Veterinary Sutures Market stands to benefit from this shift by offering products tailored for various surgical specialties. It creates room for innovation in absorbable, antimicrobial, and bio-compatible materials. Increased willingness among pet owners to invest in high-quality veterinary care supports wider adoption of premium sutures in urban and semi-urban areas.
Growth in Veterinary Infrastructure and Training Supports Product Diversification
Veterinary hospitals and clinics continue to expand their surgical capabilities through infrastructure upgrades and advanced procedure offerings. Institutions are investing in specialized units and staff training, which creates an opportunity for product differentiation. The Veterinary Sutures Market can introduce procedure-specific kits and materials aligned with updated clinical protocols. It encourages suppliers to collaborate with teaching hospitals and training centers to build long-term user familiarity. Opportunities exist to supply targeted solutions for niche areas like exotic animal care or laparoscopic surgery. The increasing number of veterinary graduates also strengthens the market’s foundation for knowledge-driven product selection.
Market Segmentation Analysis:
By Type:
The veterinary sutures market is segmented into absorbable and non-absorbable sutures. Absorbable sutures hold a significant share due to their ability to naturally dissolve within the animal's body, reducing the need for follow-up visits. These are preferred in internal surgeries where suture removal is not feasible. Non-absorbable sutures remain essential for external wound closures and orthopedic procedures that demand extended support. Product selection depends on the healing time required and surgical site accessibility. Both types continue to see innovation in materials and coatings to enhance performance and reduce infection risks.
- For instance, Ethicon’s VICRYL™ (polyglactin 910) braided sutures demonstrate a tensile strength of approximately 195 N at time zero, declining to about 157 N by day 14 and as low as 14 N by day 42 under standardized incubation studies, with full absorption occurring between day 56 and day 70.
By Animal Type:
The market is divided into large and small animals. Small animals, including cats and dogs, dominate the segment owing to the rising trend of pet ownership and frequent surgical interventions in veterinary clinics. It supports strong demand for both absorbable and non-absorbable sutures tailored to various species and sizes. Large animals, such as horses and cattle, contribute steadily to the market, primarily through soft tissue and orthopedic procedures. Growth in equine sports medicine and livestock care strengthens product uptake. The Veterinary Sutures Market benefits from increasing awareness around professional post-operative care in both segments.
- For instance, Medtronic partnered with over 900 rural veterinary clinics across India in 2024, supplying specialized absorbable sutures designed for post-operative recovery in both small pet surgeries and large animal interventions.
By Application Type:
Soft tissue surgery accounts for a major share due to its prevalence in both routine and emergency care. It includes procedures involving organs, skin, and subcutaneous tissues where suture choice directly influences recovery outcomes. Gynecology and urology surgeries demand precision sutures that minimize tissue reaction and support rapid healing. Orthopedic surgeries use stronger sutures that ensure long-term stability. The others category includes dental, ophthalmic, and oncological procedures where specific suture features are critical to success.
By End-User:
Hospitals lead due to access to advanced surgical infrastructure and trained professionals. Veterinary clinics follow closely, driven by rising caseloads and convenience for pet owners. Clinics often stock a wide range of suture types to cater to different animal breeds and medical needs. This diversity in demand across end-users promotes continuous product development and customization by manufacturers.
Segments:
Based on Type:
- Absorbable,
- Non-Absorbable
Based on Animal Type:
- Large Animal
- Small Animal
Based on Application:
- Soft Tissue Surgery
- Gynecology
- Urology Surgery
- Orthopedic Surgery
Based on End-User:
- Hospitals
- Veterinary Clinics
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
North America dominates the veterinary sutures market with a market share of approximately 37.2% in 2024. The region’s leadership is supported by the presence of well-established veterinary healthcare infrastructure and high animal healthcare expenditure. The United States, in particular, exhibits strong demand due to the high adoption rate of companion animals and increasing surgical interventions in veterinary practices. Rising pet insurance coverage, growth in equine and livestock populations, and awareness of animal health have elevated the need for specialized suturing solutions. Key players operating in this region also invest heavily in R&D to develop advanced suture materials. Demand for absorbable sutures is increasing due to better post-operative outcomes and fewer follow-ups. The region continues to witness strong growth driven by robust veterinary service networks and stringent regulations emphasizing animal care quality.
Europe
Europe holds the second-largest share of the veterinary sutures market, accounting for around 26.8% in 2024. Countries such as Germany, France, and the UK lead in veterinary surgical procedures and investments in animal healthcare technologies. The rise in livestock monitoring programs and efforts toward animal disease control by EU regulatory bodies push the demand for effective surgical solutions. The growing trend of pet humanization in Western Europe contributes to the demand for soft tissue and orthopedic surgeries, which in turn fuels suture consumption. Veterinarians in this region increasingly prefer biodegradable sutures that reduce the need for re-visits. Local and regional manufacturers support the supply chain with cost-effective and high-quality suture materials. Europe’s market reflects maturity, yet continues to expand with improvements in companion animal healthcare.
Asia Pacific
The Asia Pacific region accounts for a market share of 19.5% in 2024, and it is expected to grow at a strong pace over the forecast period. The increasing livestock population and pet adoption rates in countries like China, India, and Japan drive demand for surgical products. Government initiatives to control zoonotic diseases and improve veterinary service access also support market expansion. The region experiences a rising need for affordable and effective suturing solutions to support growing animal surgeries in both rural and urban setups. Domestic players play a critical role in supplying low-cost sutures to meet the large-scale veterinary needs. Urbanization and rising disposable incomes contribute to pet care spending and support higher surgical intervention rates. Demand for non-absorbable sutures remains steady, particularly for large animals in agricultural settings.
Latin America
Latin America represents a smaller yet emerging share of the veterinary sutures market with a market share of 9.1% in 2024. Brazil and Argentina are major contributors due to their large livestock industries and growing companion animal care services. The market is largely driven by agricultural veterinary needs, including soft tissue and orthopedic procedures in large animals. Improvements in veterinary education and awareness are promoting better surgical practices. Import reliance remains high, although local manufacturing is gradually expanding to meet regional demand. The market shows steady development with growing investments in animal welfare programs and public-private partnerships aimed at rural veterinary outreach.
Middle East and Africa Remain
The Middle East and Africa (MEA) account for 7.4% of the global market in 2024, indicating the lowest market share but with considerable potential. The region’s growth is influenced by increasing focus on livestock health in Gulf countries and growing pet adoption in urban centers of South Africa. Access to advanced veterinary services is limited in rural areas, yet improving infrastructure supports market entry. The demand is primarily focused on cost-effective suture materials for large animals, especially in agricultural economies. International aid and veterinary programs also support basic surgical interventions in underdeveloped regions. MEA is projected to grow steadily as government and NGO efforts strengthen veterinary service coverage.
Key Player Analysis
- UNIFY sutures
- Teleflex Inc.
- DemeTech
- Medtronic PLC
- Vitrex Surgical
- AmerisourceBergen Corporation
- KRUUSE UK Ltd.
- B.Braun
- Q-Close
- Ethicon U.S.
Competitive Analysis
The Veterinary Sutures Market such as Medtronic PLC, DemeTech, B.Braun, Ethicon U.S., Q-Close, KRUUSE UK Ltd., Teleflex Inc., AmerisourceBergen Corporation, UNIFY Sutures, and Vitrex Surgical dominate the market by offering a comprehensive range of suture solutions designed for various veterinary procedures. Market leaders emphasize innovation in both absorbable and non-absorbable sutures, targeting a wide range of applications from routine wound closures to complex surgical interventions. These firms invest heavily in research and development to introduce materials that reduce tissue reaction and improve handling properties for veterinary professionals. Strategic collaborations, regional expansions, and tailored product offerings further strengthen their market positions. Additionally, companies leverage extensive distribution networks and provide educational support to veterinarians to boost product adoption and brand loyalty. Their ability to address the distinct needs of small animals, livestock, and equine practices demonstrates a commitment to comprehensive care. The competitive landscape remains dynamic, driven by ongoing innovation, regulatory compliance, and a growing emphasis on animal welfare.
Recent Developments
- In 2025, AmerisourceBergen expanded its distribution partnerships, increasing accessibility of advanced veterinary sutures in North America, helping meet the rising demand for veterinary surgical care
- In January 2025, Medtronic launched new absorbable monofilament sutures, advancing veterinary surgical options with improved biocompatibility and ease of use, reflecting a significant milestone in enhancing surgical outcomes for pets.
- In April 2023, Corza Medical finalized a deal to acquire Takeda Pharmaceuticals’ TachoSil manufacturing operations in Linz, Austria.
Market Concentration & Characteristics
The Veterinary Sutures Market Market displays a moderately concentrated structure with a mix of global and regional players competing across various product categories. Large multinational companies dominate the upper tier through strong brand portfolios, extensive distribution networks, and ongoing investments in product innovation. These players maintain high entry barriers through regulatory approvals, proprietary materials, and established relationships with veterinary professionals. At the same time, regional manufacturers contribute to market diversity by offering cost-effective alternatives tailored to local clinical needs. It features a wide range of absorbable and non-absorbable sutures designed for small animal, livestock, and equine procedures, reflecting growing demand for precision in wound management. Product differentiation relies heavily on factors such as suture strength, biocompatibility, and ease of handling. Technological advancements, such as antibacterial coatings and synthetic materials, further define competition. Pricing remains competitive, particularly in emerging markets, where affordability drives procurement decisions. Companies leverage training initiatives and clinical support to build trust among veterinary practitioners and expand their user base. Despite the presence of several active participants, a few key firms continue to command significant market share by consistently meeting evolving clinical standards and aligning products with veterinary best practices.
Report Coverage
The research report offers an in-depth analysis based on Type, Animal Type, Application, End-User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will expand steadily due to increased pet ownership and spending on companion animal healthcare.
- Demand for advanced suture materials will grow as surgical precision and recovery outcomes become more critical.
- Manufacturers will focus on biodegradable and antimicrobial sutures to reduce post-operative complications.
- Veterinary hospitals and clinics will continue to drive procurement through bulk purchases and long-term contracts.
- Emerging markets will offer new growth opportunities due to expanding veterinary infrastructure and animal welfare initiatives.
- Innovation in synthetic suture technology will improve handling, tensile strength, and tissue compatibility.
- Online distribution channels will gain traction, supporting broader access to surgical supplies in remote regions.
- Rising awareness of livestock health and veterinary surgical procedures will support consistent demand across rural areas.
- Regulatory compliance will remain essential, prompting companies to invest in certifications and quality control.
- Key players will strengthen their positions through acquisitions, product portfolio expansion, and veterinarian education programs.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Increased Companion Animal Surgeries
Rising pet ownership and improved access to veterinary care are leading to a higher volume of surgical procedures in companion animals, driving demand for advanced suture materials that support faster healing and lower infection risks.
Government and Regulatory Support for Livestock Health
Government-funded livestock healthcare initiatives and regulatory mandates for approved suture materials are expanding the adoption of high-quality sutures in both rural and commercial veterinary practices, ensuring consistent procurement and safety standards.
Modernization of Veterinary Infrastructure
The expansion and upgrading of veterinary hospitals and clinics are increasing the demand for precision surgical consumables, including specialized sutures compatible with minimally invasive and laparoscopic procedures.
Shift Toward Advanced Suture Materials
Growing preference for absorbable, antimicrobial, and biodegradable sutures is enhancing post-operative outcomes, reducing the need for follow-up visits, and minimizing complications, thus accelerating market growth.
Expansion of Specialty and Elective Veterinary Procedures
The rise in specialty practices and elective surgeries in both pets and large animals is driving the need for customizable suture solutions tailored to specific species, tissue types, and surgical requirements.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Veterinary Sutures Market and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Veterinary Sutures Market projected to grow between 2025 and 2032?
What are the primary factors fueling the growth of the Veterinary Sutures Market?
Who are the leading companies in the Veterinary Sutures Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Absorbable
- 1.2.2 Non-Absorbable
- 1.3 By End-User
- 1.3.1 Hospitals
- 1.3.2 Veterinary Clinics
- 1.4 By Animal Type
- 1.4.1 Large Animal
- 1.4.2 Small Animal
- 1.5 By Application
- 1.5.1 Soft Tissue Surgery
- 1.5.2 Gynecology
- 1.5.3 Urology Surgery
- 1.5.4 Orthopedic Surgery
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 294 million → 2032: USD 390.144 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Veterinary Sutures Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Veterinary Sutures Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Veterinary Sutures Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Veterinary Sutures Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Veterinary Sutures Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Veterinary Sutures Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Veterinary Sutures Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Veterinary Sutures Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 294 million → 2032: USD 390.144 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Veterinary Sutures Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Absorbable
- 12.3.7.2 Non-Absorbable
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By End-User - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Hospitals
- 12.4.7.2 Veterinary Clinics
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Animal Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Large Animal
- 12.5.7.2 Small Animal
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Application - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Soft Tissue Surgery
- 12.6.7.2 Gynecology
- 12.6.7.3 Urology Surgery
- 12.6.7.4 Orthopedic Surgery
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Veterinary Sutures End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Veterinary Sutures Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Veterinary Sutures Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Veterinary Sutures Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Medtronic PLC
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 DemeTech
- 18.4 Teleflex Inc.
- 18.5 UNIFY Sutures
- 18.6 Vitrex Surgical
- 18.7 AmerisourceBergen Corporation
- 18.8 KRUUSE UK Ltd.
- 18.9 B.Braun
- 18.10 Q-Close
- 18.11 Ethicon U.S.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

