
Market Overview
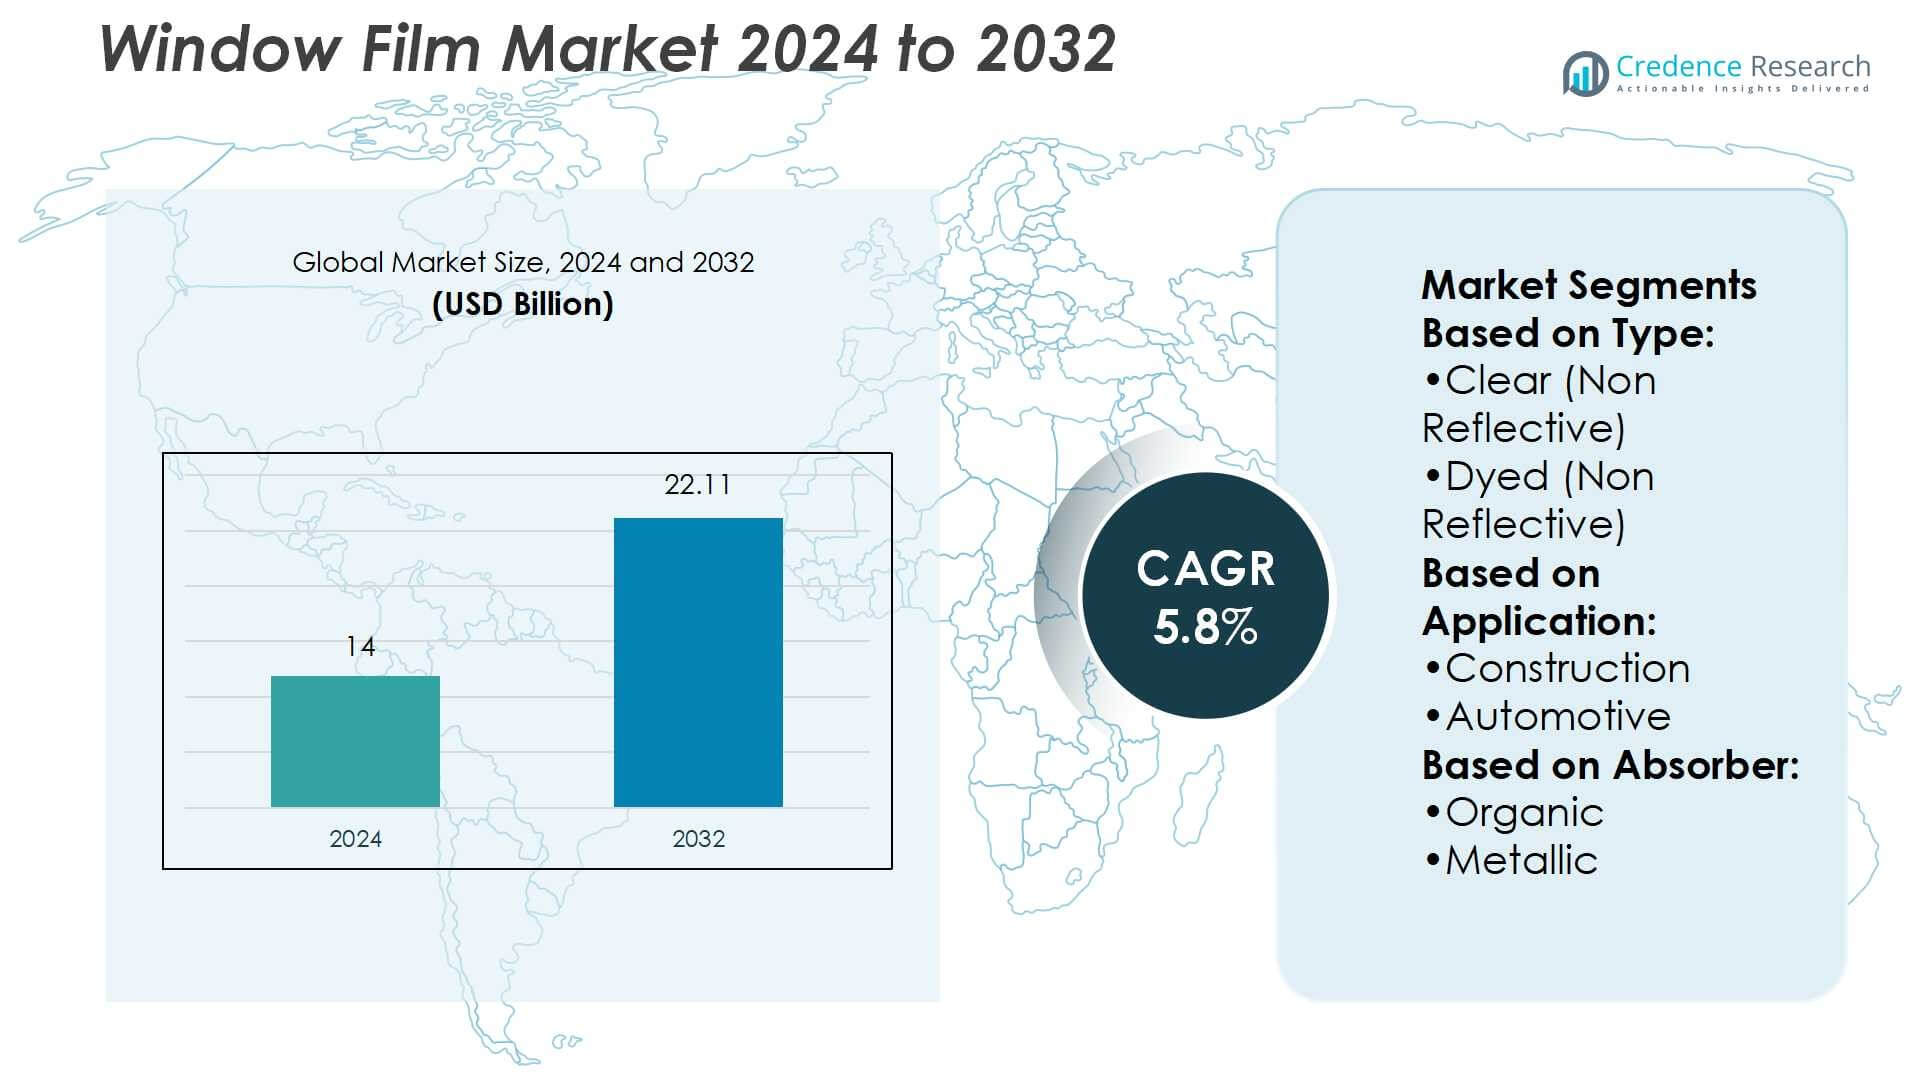
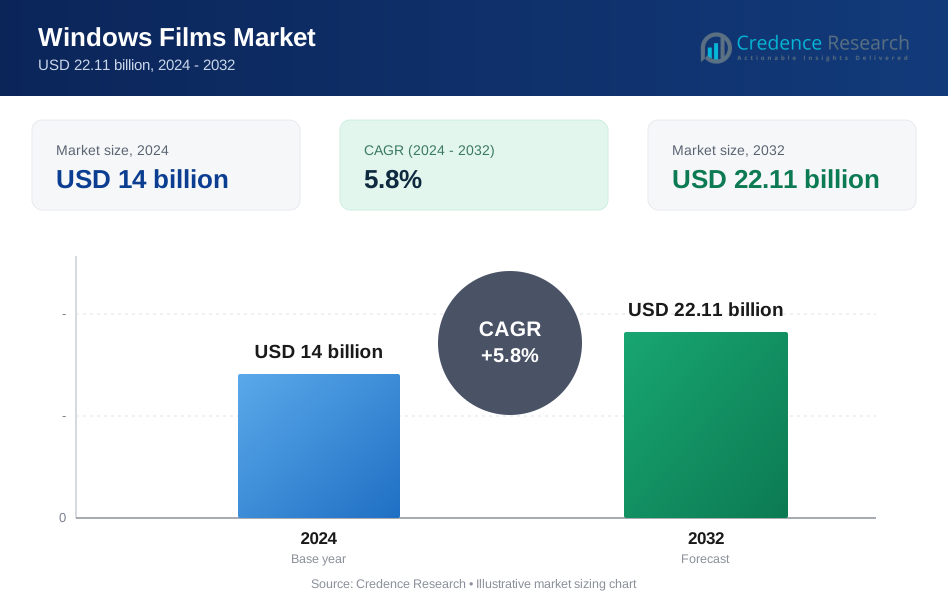
Window Film Market size was valued USD 14 billion in 2024 and is anticipated to reach USD 22.11 billion by 2032, at a CAGR of 5.8% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Window Film Market Size 2024 | USD 14 Billion |
| Window Film Market, CAGR | 5.8% |
| Window Film Market Size 2032 | USD 22.11 Billion |
The window film market is shaped by key players including 3M, Eastman Performance Films, Avery Dennison Corporation, Johnson Window Films, Garware Suncontrol Film, Lintec Corporation, Madico, Decorative Films, Deposition Technology Innovations, and Dexerials Corporation. These companies compete through product innovation, advanced material development, and global distribution strategies to serve diverse applications in automotive, construction, and decorative sectors. Asia-Pacific emerges as the leading region, commanding a 34% share of the global market, driven by rapid urbanization, strong automotive production, and increasing adoption of energy-efficient building solutions. This regional dominance highlights both scale and innovation-led growth.
Market Insights
- The window film market was valued at USD 14 billion in 2024 and is projected to reach USD 22.11 billion by 2032, growing at a CAGR of 5.8%.
- Growing demand for energy efficiency in construction and automotive industries is a key driver, as films reduce cooling costs, improve comfort, and enhance UV protection.
- Advanced trends include adoption of nanotechnology and ceramic-based films that offer superior clarity, durability, and non-interference with electronic devices, creating opportunities in premium applications.
- The competitive landscape is shaped by global leaders investing in product innovation, while regional players compete through affordability, though challenges include strict regulations on visible light transmission and pricing pressures.
- Asia-Pacific dominates with a 34% regional share, supported by urbanization and high automotive production, while the automotive segment leads overall applications with a 42% share, reflecting strong consumer demand for safety, comfort, and performance benefits.
Market Segmentation Analysis:
By Type
In the window film market, the vacuum-coated (reflective) films dominate with the largest share, accounting for over 38% of total sales. Their popularity stems from superior heat rejection, UV protection, and glare reduction, making them highly suitable for both automotive and construction applications. Rising energy efficiency standards further strengthen their adoption, particularly in commercial buildings seeking to reduce cooling costs. Although clear and dyed films remain cost-effective options, reflective films drive the segment due to advanced durability, enhanced performance, and compliance with green building certifications.
- For instance, Johnson Window Films’ Supreme IR series incorporates infrared-absorbing nano-ceramic technology capable of blocking up to 97% of infrared radiation. However, its Total Solar Energy Rejection (TSER) rating reaches a maximum of 66% in its darkest legal shade (SUPR 05).
By Application
The automotive segment leads the window film market, holding nearly 42% of the market share. Growth is driven by rising demand for UV protection, passenger comfort, and vehicle aesthetics. Consumers increasingly prefer tinted and reflective films to improve cabin cooling efficiency and protect interiors from fading. Additionally, stricter regulations on vehicle fuel efficiency indirectly support adoption by reducing air-conditioning load. While construction and decorative graphics segments show steady growth, automotive applications dominate due to higher volume installations, aftermarket customization, and technological integration in premium vehicles.
- For instance,The "SUNROOF 50" variant is one of several available in the Sunroof-Moonroof Film series, which also includes a "SUNROOF 70" variant with slightly different specifications, such as 70% visible light transmittance and 48% total heat rejection.
By Absorber
Among absorber types, metallic films command the dominant position with a 36% market share. These films deliver high heat rejection, improved strength, and enhanced durability, making them preferred in both automotive and commercial construction projects. Metallic absorbers reflect solar energy efficiently, lowering energy consumption and extending lifespan compared to organic variants. Inorganic ceramic films are emerging as a premium alternative due to superior clarity and non-interference with electronic devices. However, metallic films continue to dominate due to their cost-effectiveness, strong performance profile, and widespread availability across end-use applications.
Key Growth Drivers
Rising Energy Efficiency Demand
Energy-efficient solutions are becoming critical across residential, commercial, and automotive sectors. Window films play a vital role in reducing energy consumption by minimizing heat gain and improving insulation. Governments and organizations are promoting sustainable building materials, encouraging adoption of reflective and high-performance films. The cost savings on cooling systems further support demand. As energy regulations tighten worldwide, window films are increasingly viewed as an affordable and scalable solution, driving market growth across construction and transportation industries.
- For instance, Lintec products are certified for optical stability with scratch resistance. The 2 mil SR PET UV Block Permanent Window Film offers approximately 0.0508 mm thickness (2 mil), designed for UV-curable inks with good dimensional stability.
Growing Automotive Applications
The automotive industry remains a key growth driver for the window film market. Rising consumer demand for UV protection, glare reduction, and passenger comfort has led to higher adoption in both OEM and aftermarket applications. Films also extend the life of vehicle interiors by preventing fading and material degradation. Premium vehicles increasingly integrate advanced ceramic and metallic films for superior performance. With global automotive sales recovering and customization trends rising, demand for high-quality window films is expected to strengthen further.
- For instance, Solyx’s UltraCool-LE3570 Low-E IR/UV film delivers verified UV transmission of < 1%, visible light transmission (VLT) of 37%, and rejects 72% of infrared radiation.
Increased Awareness of Health and Safety Benefits
Consumers are becoming more aware of the health and safety benefits provided by window films. These products block harmful UV rays, reducing risks of skin damage and protecting furnishings from deterioration. Safety films also enhance glass strength, minimizing shattering risks during accidents or natural disasters. Such benefits align with consumer focus on wellness and safety, making films a preferred solution in residential, commercial, and automotive applications. Growing awareness campaigns and product innovations continue to expand this demand base globally.
Key Trends & Opportunities
Adoption of Advanced Nanotechnology Films
The development of nanotechnology-based films presents a major trend in the market. These films offer superior clarity, high UV protection, and better thermal performance without affecting visibility. Inorganic ceramic nanofilms, in particular, are gaining traction for their durability and non-interference with electronic signals. Their application in high-end automotive and commercial spaces highlights significant growth opportunities. As manufacturers expand their product lines with innovative coatings, demand for advanced films is expected to accelerate.
- For instance, 3M’s Automotive Window Film Crystalline Series uses a proprietary multilayer optical film (MOF) with over 200 nano-layers thinner than a standard Post-it® note. It rejects up to 99% of infrared rays and up to 64% of total solar energy.
Growing Decorative and Aesthetic Applications
Beyond functional benefits, decorative and aesthetic applications are creating new opportunities in the window film market. Graphic and decorative films are increasingly used in residential, retail, and office spaces for branding, privacy, and interior design enhancements. Demand is growing in urban areas where space optimization and style differentiation are priorities. These films combine visual appeal with practical features such as UV blocking, fueling adoption across construction and design projects. This trend is expected to widen the consumer base significantly.
- For instance, The SpectraSelect Performance VS20 SR CDF film, from LLumar (an Eastman brand), allows 23% visible light transmittance (VLT). It blocks over 99% of UV radiation and has a Light-to-Solar-Heat-Gain Ratio (LSG) of 0.22.
Key Challenges
Regulatory and Legal Restrictions
The market faces challenges due to varying regulations on window film usage, particularly in the automotive sector. Many countries impose limits on visible light transmission (VLT), restricting the degree of tint allowed on vehicle windows. Non-compliance can lead to penalties, discouraging adoption among consumers. Manufacturers must continually adapt product specifications to meet diverse regional standards. These legal complexities increase operational costs and pose barriers to consistent market penetration.
High Competition and Price Sensitivity
Intense competition among global and regional players creates significant price pressure in the market. Consumers often prioritize affordability, leading to strong demand for low-cost alternatives over advanced, high-performance films. This limits revenue potential for manufacturers offering premium solutions. Additionally, counterfeit and substandard products further erode pricing structures and consumer trust. Balancing innovation with competitive pricing remains a major challenge for sustaining profitability in the highly fragmented window film market.
Regional Analysis
North America
North America holds a 32% share of the global window film market, driven by strong demand in both construction and automotive applications. The region benefits from widespread adoption of energy-efficient building materials supported by green building certifications and government initiatives. Automotive aftermarket customization also plays a key role, with consumers investing in UV protection and aesthetic enhancements. The United States dominates regional sales due to high urbanization and strict energy regulations. Canada and Mexico show steady growth, supported by infrastructure modernization and rising vehicle ownership, further strengthening the region’s market position.
Europe
Europe accounts for 27% of the global window film market, supported by stringent environmental regulations and increasing adoption of sustainable construction practices. Countries such as Germany, France, and the UK are leading adopters due to energy-saving mandates and rising awareness of UV protection. The region is also witnessing strong growth in decorative and graphic films, driven by commercial and retail applications. Automotive demand remains robust, with premium vehicles integrating advanced films for performance and safety. EU directives on carbon neutrality continue to encourage replacement of conventional glazing with high-performance films.
Asia-Pacific
Asia-Pacific dominates the global market with a 34% share, making it the leading region. High urbanization, rapid infrastructure development, and rising vehicle production underpin this growth. China, Japan, South Korea, and India are key contributors, with construction projects increasingly adopting reflective and ceramic films to reduce cooling loads. The automotive industry drives significant demand, particularly in markets with hot climates. Expanding middle-class consumption and government support for energy efficiency further fuel adoption. The region also leads in production capacity, with manufacturers expanding exports to meet growing international demand.
Latin America
Latin America represents 4% of the global window film market, showing steady but limited growth. Brazil and Mexico are the primary contributors, supported by expanding automotive sales and rising investments in modern construction. The region benefits from hot climatic conditions, driving demand for films that reduce heat and UV exposure. However, price sensitivity remains high, favoring low-cost alternatives over advanced solutions. Growing awareness of energy efficiency and safety features is gradually improving adoption. Local distributors and aftermarket channels play a critical role in market penetration across residential and automotive sectors.
Middle East & Africa
The Middle East & Africa region accounts for 3% of the global window film market, with demand concentrated in the Gulf countries and South Africa. High temperatures drive strong adoption in both commercial construction and automotive applications, where films provide essential cooling benefits. The UAE and Saudi Arabia lead due to large-scale infrastructure projects and premium vehicle sales. However, limited consumer awareness in certain African markets restrains growth. Increasing investments in smart city projects and expanding construction sectors are expected to create opportunities for reflective and ceramic films in the coming years.
Market Segmentations:
By Type:
- Clear (Non Reflective)
- Dyed (Non Reflective)
By Application:
- Construction
- Automotive
By Absorber:
- Organic
- Metallic
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Southeast Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East
- GCC Countries
- Israel
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Rest of Africa
Competitive Landscape
The competitive landscape of the window film market features such as Johnson Window Films, Garware Suncontrol Film, Lintec Corporation, Decorative Films, 3M, Eastman Performance Films, Avery Dennison Corporation, Madico, Deposition Technology Innovations, and Dexerials Corporation. The window film market remains highly competitive, characterized by technological innovation, product diversification, and regional expansion strategies. Manufacturers are increasingly focusing on advanced materials such as ceramic and nanotechnology-based films to enhance performance, durability, and energy efficiency. The market is fragmented, with both global leaders and regional players competing through pricing strategies, product quality, and distribution strength. Strong emphasis is placed on meeting regulatory requirements, particularly for energy efficiency and automotive safety standards. Companies are also leveraging partnerships, acquisitions, and R&D investments to strengthen their positions, address diverse customer needs, and capture emerging growth opportunities.
Key Player Analysis
- Johnson Window Films
- Garware Suncontrol Film
- Lintec Corporation
- Decorative Films
- 3M
- Eastman Performance Films
- Avery Dennison Corporation
- Madico
- Deposition Technology Innovations
- Dexerials Corporation
Recent Developments
- In January 2024, Automotive Glass Experts (AGE) announced a strategic supplier agreement with Johnson Window Films to enhance its offerings and provide a comprehensive range of window film applications as a complementary service in its workstations.
- In August 2024, its Home Electrification and Appliance Rebates (HEAR) program was launched by Arizona which is designed to help low- and middle-income households save on energy-efficient HVAC equipment and other appliances.
- In September 2023, Pella expanded its popular Hidden Screen to the Lifestyle Series wood windows, now available exclusively at Lowe's. As the exclusive home improvement retailer for the Hidden Screen, Lowe's offers Pella's Lifestyle Series double-hung wood windows both online at Lowes.com and in over 1,700 stores nationwide.
- In August 2023, Solar Art announced acquisition of Layr, a window film manufacturing company. Layr has wide customer base including office buildings, schools and high-end retailers. This acquisition helped Solar Art to expand its business East Coast region with infrastructure in New York.
Report Coverage
The research report offers an in-depth analysis based on Type, Application, Absorber and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The window film market will expand with rising demand for energy-efficient building materials.
- Automotive adoption will grow as consumers prioritize UV protection, comfort, and safety.
- Decorative films will gain popularity in residential and commercial interior applications.
- Nanotechnology and ceramic-based films will drive innovation and premium product demand.
- Stringent regulations on energy efficiency will accelerate use in construction projects.
- Asia-Pacific will remain the leading region due to rapid urbanization and vehicle production.
- Aftermarket sales will strengthen as customization and replacement demand increases.
- Smart and switchable films will create opportunities in high-end architectural and automotive sectors.
- Distribution networks will expand to penetrate price-sensitive and emerging markets.
- Competition will intensify as global players and regional firms invest in R&D and capacity.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Energy Efficiency Regulations
Stricter global regulations and incentives for energy-efficient buildings and vehicles are driving adoption of window films, which help reduce cooling loads and energy consumption by minimizing heat gain.
Automotive Industry Growth
Rising vehicle production, especially in Asia-Pacific, and consumer demand for UV protection, comfort, and interior preservation are boosting the use of window films in both OEM and aftermarket automotive applications.
Technological Advancements
Innovations such as nanotechnology and ceramic-based films offer superior clarity, durability, and non-interference with electronics, expanding premium and high-performance market segments.
Health and Safety Awareness
Increasing consumer awareness of the health benefits of UV protection and the safety advantages of shatter-resistant films is fueling demand across residential, commercial, and automotive sectors.
Aesthetic and Decorative Trends
Growing use of decorative and privacy films in residential, commercial, and retail spaces for branding, interior design, and privacy is broadening the market beyond traditional functional uses.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Window Film Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Window Film Market projected to grow between 2025 and 2032?
Which Window Film Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Window Film Market?
Who are the leading companies in the Window Film Market?
Which region commanded the largest share of the Window Film Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Clear (Non Reflective)
- 1.2.2 Dyed (Non Reflective)
- 1.2.3 Vacuum-Coated (Reflective)
- 1.2.4 Ceramic
- 1.2.5 Nano-Technology Based
- 1.3 By Absorber
- 1.3.1 Organic
- 1.3.2 Metallic
- 1.3.3 Inorganic (Ceramic)
- 1.4 By Application
- 1.4.1 Automotive
- 1.4.2 Construction
- 1.4.3 Decorative Graphics
- 1.4.4 Safety & Security
- 1.4.5 Marine & Aerospace
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 14 billion → 2032: USD 22.11 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Windows Films Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Windows Films Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Windows Films Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Windows Films Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Windows Films Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Windows Films Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Windows Films Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Windows Films Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 14 billion → 2032: USD 22.11 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Windows Films Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Clear (Non Reflective)
- 12.3.7.2 Dyed (Non Reflective)
- 12.3.7.3 Vacuum-Coated (Reflective)
- 12.3.7.4 Ceramic
- 12.3.7.5 Nano-Technology Based
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Absorber - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Organic
- 12.4.7.2 Metallic
- 12.4.7.3 Inorganic (Ceramic)
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Automotive
- 12.5.7.2 Construction
- 12.5.7.3 Decorative Graphics
- 12.5.7.4 Safety & Security
- 12.5.7.5 Marine & Aerospace
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Windows Films End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Windows Films Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Windows Films Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Windows Films Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 3M
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Eastman Performance Films
- 18.4 Avery Dennison Corporation
- 18.5 Johnson Window Films
- 18.6 Garware Suncontrol Film
- 18.7 Lintec Corporation
- 18.8 Madico
- 18.9 Decorative Films
- 18.10 Deposition Technology Innovations
- 18.11 Dexerials Corporation
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

