
Market Overview
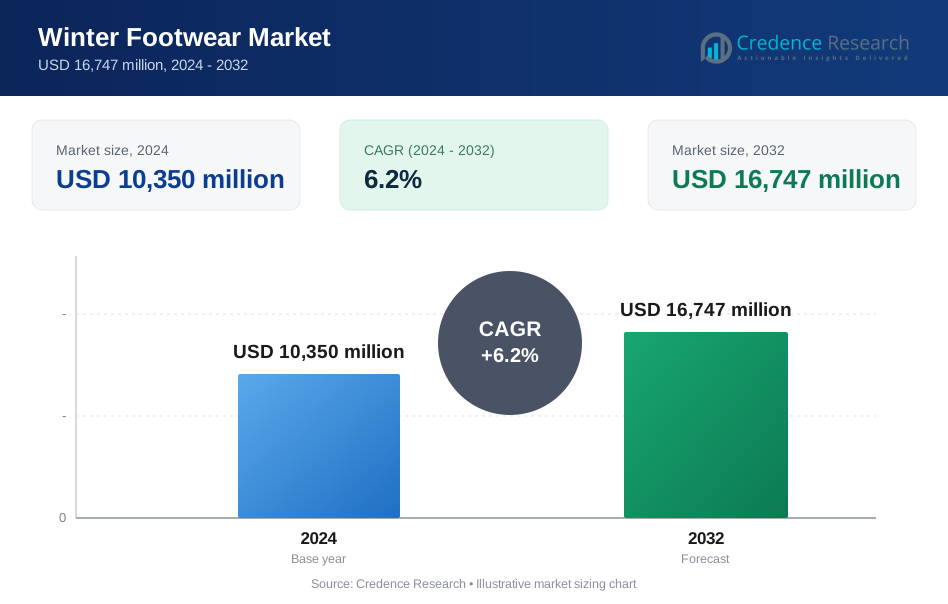
Winter footwear market size was valued at USD 10350 million in 2024 and is anticipated to reach USD 16747 million by 2032, at a CAGR of 6.2% during the forecast period.| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2024 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Winter Footwear Market Size 2024 | USD 10350 Million |
| Winter Footwear Market, CAGR | 6.2% |
| Winter Footwear Market Size 2032 | USD 16747 Million |
Market Insights
- Winter footwear market size was valued at USD 10350 million in 2024 and is anticipated to reach USD 16747 million by 2032, at a CAGR of 6.2%.
- Rising participation in outdoor activities and demand for insulated, durable products drive steady market growth.
- Technological advancements in lightweight frames, traction systems, and thermal insulation strengthen product performance.
- Sustainability trends shape innovation, with brands adopting recycled and eco-friendly materials in design.
- Competition remains intense, with established brands and niche manufacturers investing in global reach.
- Seasonal demand fluctuations and raw material cost volatility act as restraints for manufacturers.
- North America leads with strong outdoor participation, Europe benefits from alpine culture, Asia-Pacific expands rapidly, while Latin America and Middle East & Africa show smaller but growing shares.

Market Drivers
Rising Consumer Demand for Seasonal Durability and Comfort The Winter footwear market benefits from strong consumer preference for products that combine warmth, protection, and style. It responds to cold climate conditions by integrating advanced insulation materials and weather-resistant outsoles that improve durability. Consumers in urban and rural regions expect footwear that withstands snow, slush, and icy terrain while offering everyday comfort. Growth in outdoor leisure activities such as trekking and skiing further supports demand for high-performance models. This emphasis on practicality and comfort pushes brands to innovate with water-resistant fabrics, slip-resistant soles, and thermal lining.- For instance, Columbia Sportswear integrated its patented Omni-Heat™ thermal reflective technology into over 12 million pairs of boots sold. This technology utilizes a pattern of metallic dots, inspired by NASA's reflective technology.
- For instance, Adidas introduced its “Terrex Free Hiker Cold.Rdy” line in 2023, produced with more than 12 million kilograms of recycled ocean plastic through its partnership with Parley for the Oceans, integrating at least.
Market Trends
Increasing Integration of Smart Features and Functional Innovation The Winter footwear market shows a clear trend toward combining smart features with advanced functional design. It includes heated insoles, moisture-control technology, and temperature regulation systems that improve comfort in extreme conditions. Brands experiment with embedded sensors that track movement and offer connectivity with mobile devices. Such advancements extend footwear beyond protection and create value for tech-savvy consumers. The emphasis on performance-driven innovation ensures products cater to both outdoor activities and daily urban use. This trend positions winter footwear as a technologically enhanced lifestyle accessory.- For instance, Digitsole launched its Smartshoe line equipped with auto-tightening laces, step tracking, and heating elements capable of maintaining 30°C internal temperature for up to 8 hours, with over 50,000 units sold across Europe and North America in 2023.
- For instance, Moncler's "City of Genius" event held in Shanghai in October 2024 attracted 8,000 confirmed guests and showcased ten distinct alpine sportswear collections across a venue spanning approximately 323,000 square feet.
Market Challenges Analysis
Rising Cost Pressures and Raw Material Volatility The Winter footwear market faces challenges from fluctuating costs of raw materials and supply chain instability. It relies heavily on leather, rubber, wool, and synthetic fabrics, all of which experience price volatility due to global trade disruptions and climate-related impacts. Manufacturers struggle to maintain competitive pricing while ensuring product quality and durability. Rising energy costs and transportation delays increase overall production expenses, pressuring margins across the industry. Smaller brands encounter greater difficulty absorbing these costs compared to global players. This situation forces companies to explore alternative sourcing strategies and localized manufacturing models. Intense Competition and Shifting Consumer Expectations The Winter footwear market encounters strong competitive pressures from global brands, regional players, and low-cost alternatives. It must consistently adapt to fast-changing consumer preferences that prioritize both style and performance. Shortened fashion cycles demand frequent product updates, straining design and production capacities. The rise of counterfeit products further challenges established brands, eroding trust and revenue. Consumers also expect sustainability and transparency, which require significant investment in materials and processes. Meeting these diverse demands while maintaining profitability remains a central obstacle for industry participants.Market Opportunities
Expansion into Emerging Markets and Cold-Climate Regions The Winter footwear market holds strong opportunities in emerging economies where rising disposable income and urbanization boost demand for premium products. It benefits from colder regions in Asia-Pacific, Eastern Europe, and North America where harsh winters require durable, insulated footwear. Consumers in these areas increasingly value products that combine warmth, comfort, and fashion appeal. Expanding retail networks and growing online accessibility improve product reach and visibility across untapped markets. International brands that localize designs to cultural preferences and climate conditions can gain a competitive edge. This expansion strengthens long-term growth potential for manufacturers and retailers. Innovation in Sustainable Design and Advanced Materials The Winter footwear market creates opportunities through the development of eco-friendly products and advanced material technologies. It focuses on integrating recycled fabrics, plant-based insulations, and biodegradable outsoles that appeal to environmentally conscious buyers. Lightweight yet durable innovations improve comfort and performance, supporting adoption in both outdoor and urban settings. Brands that invest in energy-efficient production and transparent supply chains stand to capture loyalty among sustainability-focused consumers. Collaborations with material science firms accelerate product differentiation and broaden the appeal of green footwear. This pathway aligns with rising global demand for responsible and innovative fashion solutions.Market Segmentation Analysis:
By Product Type The Winter footwear market demonstrates diverse demand across product categories designed for specific consumer groups. Snowshoes for women command a significant share, supported by rising participation in winter sports and outdoor recreational activities. Lightweight designs, ergonomic structures, and enhanced traction systems drive growth in this category. Snowshoes for men dominate backcountry and performance-oriented usage, with a focus on durability and advanced grip technologies. Snowshoes for kids reflect growing family participation in winter activities, creating demand for safe, easy-to-use, and affordable options. It benefits from expanding product customization that caters to lifestyle preferences of each consumer segment. By Frame Material The Winter footwear market segments by frame material, with aluminum snowshoes standing out for their strength-to-weight ratio and resilience in rugged conditions. Aluminum frames remain popular among professional and adventure users who require performance reliability. Plastic snowshoes capture consumer interest in affordability and low-maintenance features, appealing to casual and first-time buyers. Composite frames combine flexibility with lightweight design, creating a balance between durability and user comfort. It supports adoption across both recreational and performance-driven categories, offering versatility for multiple terrains. Manufacturers emphasize material innovation to ensure performance, longevity, and cost efficiency in competitive markets.- For instance, Alpine sports equipment manufacturer Alpina Žiri currently operates with approximately 1,000 employees and produces over 1.7 million pairs of shoes and boots annually.
- For instance, Crescent Moon Snowshoes, based in Colorado, manufactures over 250,000 pairs of snowshoes annually, with its Eva Foam models alone exceeding 80,000 units.
Segments:
Based on Product Type:- Snowshoes for Women
- Snowshoes for Men
- Snowshoes for Kids
- Aluminium
- Plastic
- Composite
- Backcountry Snowshoeing
- Nordic Skiing
- Casual Snowshoeing
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America North America accounts for 35% of the winter footwear market, driven by harsh climatic conditions and strong consumer spending power. The United States leads regional demand with a broad base of consumers engaged in skiing, snowboarding, and casual snowshoeing activities. Canada adds significant growth through its long winters and cultural integration of snow-related sports. The region benefits from advanced retail infrastructure, with strong penetration of e-commerce platforms that expand accessibility across urban and rural communities. Major players invest heavily in product innovation, introducing snowshoes with lightweight aluminium frames and advanced traction technologies tailored to diverse terrains. Sustainability initiatives gain traction in the market, as brands incorporate recycled and eco-friendly materials to meet evolving consumer expectations. The combination of technological innovation, fashion integration, and active outdoor lifestyles strengthens the dominance of North America in the industry. Europe Europe holds 28% of the winter footwear market, supported by established winter sports culture and significant demand across alpine regions. Countries such as Germany, France, Switzerland, and Austria drive sales through professional skiing, Nordic activities, and tourism-linked winter recreation. Consumers prefer products that combine performance and fashion, resulting in demand for snowshoes that are both durable and stylish. Retailers leverage strong distribution networks, including specialty sports outlets and online platforms, to capture seasonal demand. Brands in Europe focus on premium materials and composite frame innovations that appeal to environmentally conscious buyers. Government initiatives to promote winter sports tourism in alpine nations further boost product demand. The combination of sport-driven culture, strong fashion orientation, and sustainable practices secures Europe’s position as a leading region. Asia-Pacific Asia-Pacific contributes 22% of the winter footwear market, with rapid growth attributed to expanding middle-class income, urbanization, and rising interest in outdoor sports. China, Japan, and South Korea represent key demand centers where winter sports adoption has accelerated. International events such as the Winter Olympics have heightened regional interest in snowshoeing and skiing. Local brands compete with global players by offering affordable yet durable options tailored to diverse consumer groups. It reflects growing demand for lightweight plastic and composite snowshoes that suit both recreational and entry-level users. Online retail channels expand significantly, supported by strong digital infrastructure and mobile commerce adoption. The combination of economic growth, cultural adoption of winter sports, and digital retail expansion makes Asia-Pacific a high-potential region. Latin America Latin America captures 8% of the winter footwear market, with demand centered in countries that experience seasonal snowfall, such as Argentina and Chile. These nations benefit from winter tourism and strong engagement in skiing and snowshoeing activities in the Andes region. While consumer spending power remains lower than North America or Europe, increasing tourism and rising outdoor activity participation create steady growth opportunities. Local distributors and specialty sports retailers play a key role in supplying products to tourists and enthusiasts. Brands introduce mid-range products with plastic and composite frames to balance affordability and durability. It reflects a niche yet growing market with potential to expand further through tourism-driven demand. Latin America’s contribution remains smaller, but its importance rises steadily with greater global exposure to winter sports. Middle East & Africa The Middle East & Africa accounts for 7% of the winter footwear market, driven by select regions that experience colder climates and strong tourism sectors. South Africa contributes through recreational snowshoeing activities in mountainous regions, while Middle Eastern countries such as the UAE and Saudi Arabia show demand from indoor winter resorts and adventure parks. The market remains limited in size but attracts premium international brands targeting tourists and expatriates. Rising disposable income in Gulf countries supports purchases of luxury winter footwear products. Retail expansion into airports and specialty outlets further improves accessibility in tourism hubs. It demonstrates gradual growth potential despite climatic limitations, with opportunities tied to tourism, luxury demand, and niche recreational activities.Key Player Analysis
- Black Diamond Equipment
- Alfa Snowshoes
- Dion Snowshoes
- Tubbs Snowshoes
- Atlas SnowShoes
- Crescent Moon Snowshoes
- Karakoram
- G3 Genuine Guide Gear
- TSL Outdoor
- Louis Garneau
Competitive Analysis
The Winter footwear market features include Black Diamond Equipment, Alfa Snowshoes, Dion Snowshoes, Tubbs Snowshoes, Atlas SnowShoes, Crescent Moon Snowshoes, Karakoram, G3 Genuine Guide Gear, TSL Outdoor, and Louis Garneau. The Winter footwear market demonstrates a highly competitive structure defined by continuous innovation, diverse consumer demand, and evolving retail strategies. Companies focus on advanced materials, improved traction systems, and lightweight designs to capture interest across recreational, professional, and lifestyle segments. The market shows strong emphasis on sustainability, with manufacturers integrating recycled fabrics, bio-based insulations, and eco-friendly frames to align with consumer expectations. Digital retail platforms expand visibility and accessibility, supported by omni-channel models that combine convenience with experiential store presence. Seasonal demand cycles drive intense competition during peak winter months, requiring efficient supply chain management and responsive inventory strategies. Innovation, brand positioning, and the ability to adapt to shifting consumer preferences remain the defining factors of long-term success in this industry.Recent Developments
- In March 2025, Black Diamond released updated of its winter and mountaineering with enhanced performance features for the season, including lightweight yet durable designs suitable for alpine use.
- In October 2024, Pajar Canada acquired the Canadian footwear brand Cougar. The acquisition aims to broaden Pajar’s reach both domestically and internationally, enhancing its presence in the winter footwear market.
- In October 2024, the Wales Bonner X Adidas Originals autumn/winter 2024 collection was launched, featuring new trainers and tracksuits. The collaboration emphasizes a refined, soulful aesthetic tailored to fashion-forward consumers.
- In September 2024, Dream Pairs unveiled its Fall/Winter 2024 Fuzzy Collection, comprising four series FuzzyClassic, FuzzyEasy, FuzzyGo, and FuzzyChic. The collection offers warm, plush options like fur-lined boots and fuzzy slippers for the winter season.
Market Concentration & Characteristics
The Winter footwear market shows moderate concentration, with established global brands competing alongside niche regional players that serve specific consumer groups. It is defined by product differentiation where companies focus on insulation, waterproofing, traction, and lightweight frames to meet performance and lifestyle needs. The market reflects strong seasonality, with demand peaking in colder months, pushing firms to optimize logistics and manage supply efficiently. It highlights rising consumer expectations for sustainable options, driving investment in recycled and eco-friendly materials. Competition remains intense across recreational, professional, and fashion segments, supported by digital retail expansion and omni-channel strategies that broaden reach. The Winter footwear market maintains a dynamic structure where innovation, adaptability, and brand reputation play decisive roles in shaping growth and positioning.Report Coverage
The research report offers an in-depth analysis based on Product Type, Frame Material, End-User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.Future Outlook
- The Winter footwear market will see stronger demand for sustainable products using recycled and bio-based materials.
- It will experience growth in digital retail channels supported by virtual fitting tools and AI-driven recommendations.
- Consumer preference will shift toward multifunctional footwear that blends fashion with outdoor performance.
- Advanced insulation and traction technologies will shape new product development across all segments.
- Brands will expand presence in emerging markets with rising participation in winter sports.
- Seasonal demand will drive investment in efficient supply chain and inventory management systems.
- Luxury and premium categories will expand through designer collaborations and limited-edition collections.
- Eco-certifications and transparent sourcing will gain importance in influencing buyer decisions.
- The rise of winter tourism and adventure sports will support continuous market expansion.
- Innovation in lightweight materials and ergonomic design will remain central to competitiveness.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Participation in Outdoor Activities
Increasing engagement in winter sports, trekking, and recreational snowshoeing is driving demand for durable and high-performance winter footwear, especially in regions with harsh winters.
Technological Advancements in Materials and Design
Innovations such as lightweight composite frames, advanced traction systems, and thermal insulation are enhancing comfort, safety, and usability, making winter footwear more appealing to a broader consumer base.
Sustainability and Eco-Friendly Materials
Growing consumer preference for sustainable products is pushing brands to adopt recycled materials, plant-based fibers, and eco-friendly manufacturing processes, which is expanding the market among environmentally conscious buyers.
Fashion Integration with Performance
The blending of style and functionality, including designer collaborations and versatile designs, is attracting both outdoor enthusiasts and urban consumers, broadening the market’s appeal beyond purely functional use.
Expansion of Digital Retail and Omni-Channel Strategies
The growth of e-commerce platforms, virtual fitting tools, and seamless integration of online and offline retail channels is increasing accessibility and convenience, supporting higher sales and market penetration.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Winter footwear market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Winter footwear market projected to grow between 2025 and 2032?
Which Winter footwear market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Winter footwear market?
Who are the leading companies in the Winter footwear market?
Which region commanded the largest share of the Winter footwear market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End-User
- 1.2.1 Backcountry Snowshoeing
- 1.2.2 Nordic Skiing
- 1.2.3 Casual Snowshoeing
- 1.3 By Product Type
- 1.3.1 Snowshoes for Women
- 1.3.2 Snowshoes for Men
- 1.3.3 Snowshoes for Kids
- 1.4 By Frame Material
- 1.4.1 Aluminium
- 1.4.2 Plastic
- 1.4.3 Composite
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 10,350 million → 2032: USD 16,747 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Winter Footwear Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Winter Footwear Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Winter Footwear Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Winter Footwear Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Winter Footwear Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Winter Footwear Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Winter Footwear Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Winter Footwear Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 10,350 million → 2032: USD 16,747 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Winter Footwear Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End-User - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Backcountry Snowshoeing
- 12.3.7.2 Nordic Skiing
- 12.3.7.3 Casual Snowshoeing
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Product Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Snowshoes for Women
- 12.4.7.2 Snowshoes for Men
- 12.4.7.3 Snowshoes for Kids
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Frame Material - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Aluminium
- 12.5.7.2 Plastic
- 12.5.7.3 Composite
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Winter Footwear End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Winter Footwear Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Winter Footwear Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Winter Footwear Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Black Diamond Equipment
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Alfa Snowshoes
- 18.4 Dion Snowshoes
- 18.5 Tubbs Snowshoes
- 18.6 Atlas SnowShoes
- 18.7 Crescent Moon Snowshoes
- 18.8 Karakoram
- 18.9 G3 Genuine Guide Gear
- 18.10 TSL Outdoor
- 18.11 Louis Garneau
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

