
Wound Wash Market Overview:
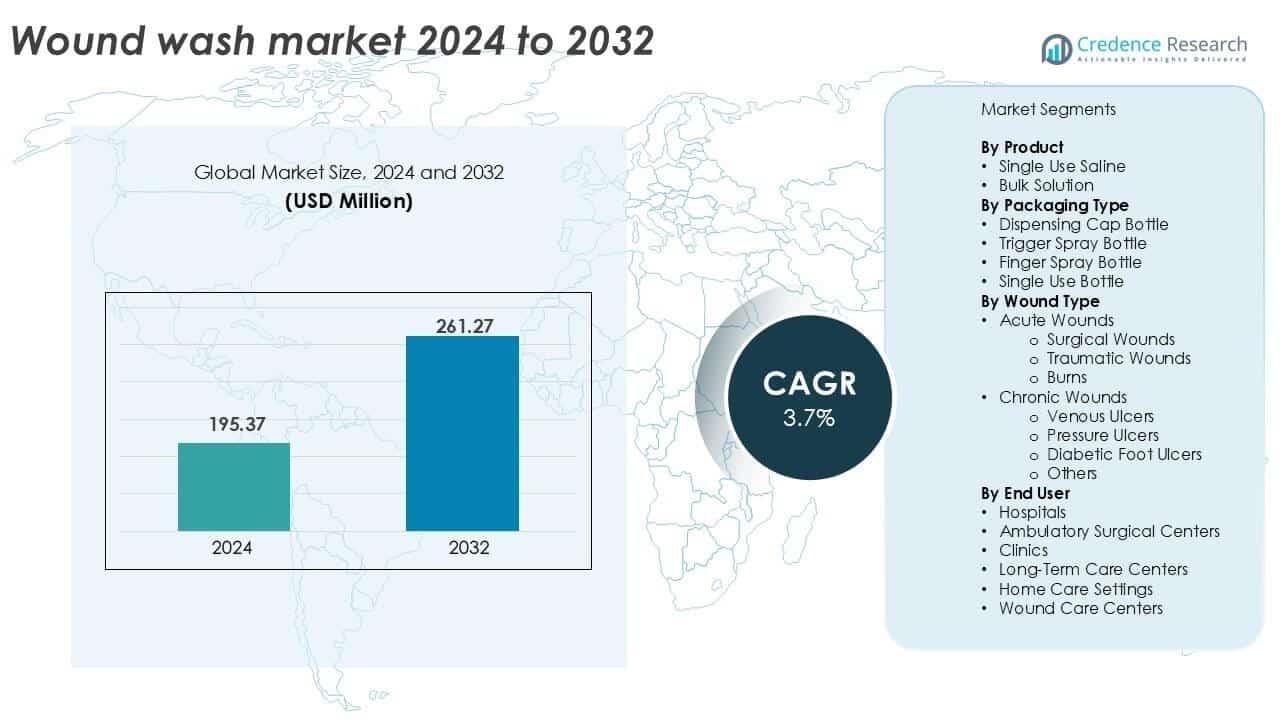
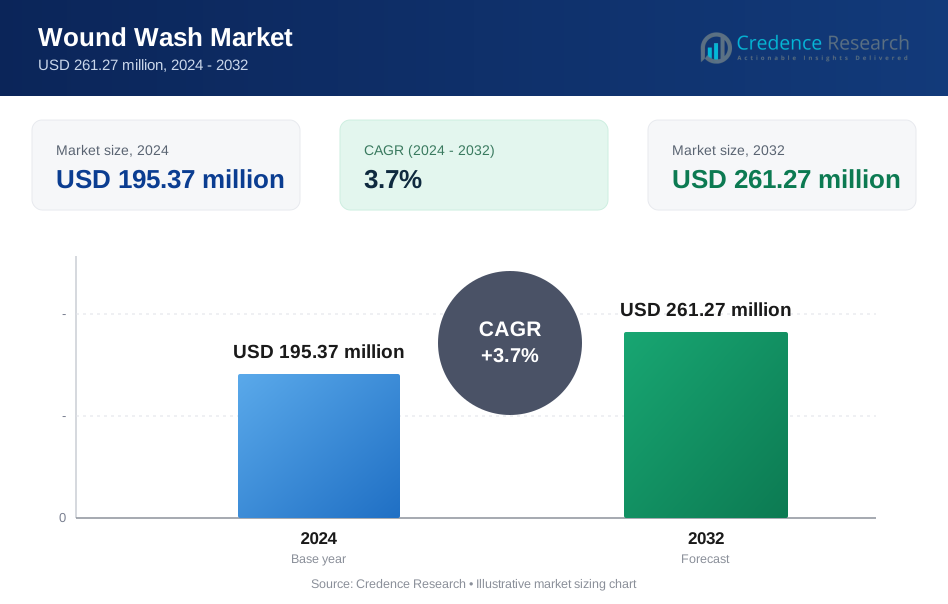
The Wound Wash Market size was valued at USD 195.37 million in 2024 and is anticipated to reach USD 261.27 million by 2032, at a CAGR of 3.7% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Wound Wash Market Size 2024 | USD 195.37 million |
| Wound Wash Market, CAGR | 3.7% |
| Wound Wash Market Size 2032 | USD 261.27 million |
Top players in the wound wash market include McKesson, Mölnlycke Health Care, Cardinal Health, Medline, and DermaRite Industries. These companies lead due to broad product offerings, strong distribution networks, and a focus on sterile, single-use solutions. Innovative players such as Clyra Medical Technologies and AMERX Health Care Corp contribute to market expansion through advanced formulations and niche targeting. North America is the leading region, holding over 35% of the global market share in 2024, supported by high surgical volumes, a strong hospital base, and increasing home healthcare adoption. Europe and Asia Pacific follow as key growth regions.
Wound Wash Market Insights
- The Wound Wash Market was valued at USD 195.37 million in 2024 and is projected to reach USD 261.27 million by 2032, growing at a CAGR of 3.7%.
- Rising surgical procedures, especially in hospitals and ambulatory centers, are driving demand for sterile wound cleansing products, with single-use saline emerging as the most preferred format.
- Market trends include growing usage of trigger spray bottles, which hold 40% segment share due to ease of application and reduced contamination risk, alongside increased demand in home care and long-term care settings.
- Leading players such as McKesson, Mölnlycke, and Medline maintain dominance through broad portfolios, while emerging companies focus on antimicrobial innovation and ergonomic packaging to capture niche segments.
- North America holds the largest regional share at over 35% due to advanced healthcare systems, followed by Europe at 28% and Asia Pacific at 22%, driven by growing surgical demand and expanding healthcare access.
Wound Wash Market Segmentation Analysis:
By Product
The wound wash market, by product, is dominated by single use saline, accounting for over 65% of the market share in 2024. Single use saline solutions are preferred due to their sterility, ease of application, and reduced contamination risk, especially in clinical and home care settings. These products align with infection control standards and are widely adopted in emergency and surgical care. Bulk solutions are more common in institutional settings but face challenges in portability and sterility assurance. The growing demand for convenient, pre-measured wound care drives the expansion of single use options.
- For instance, BD’s single-use sterile saline wound wash is supplied in 15 mL and 30 mL units, each terminally sterilized to a sterility assurance level of 10⁻⁶. Bulk solutions remain common in hospitals.
By Packaging Type
Among packaging types, trigger spray bottles lead the market with a share of approximately 40% in 2024. These bottles offer directional flow, controlled pressure, and minimal touch application, which enhance user convenience and hygiene. Healthcare professionals prefer them in outpatient and surgical settings due to ease of use and waste reduction. Finger spray and single use bottles cater to compact, disposable needs, particularly in home and travel care. Dispensing cap bottles see limited traction due to manual handling concerns. Demand for ergonomic packaging and infection control drives the adoption of advanced spray mechanisms.
- For instance, Medline’s sterile wound wash trigger spray delivers a steady stream at 8 psi, supporting debris removal without tissue damage.
By Wound Type
In wound type segmentation, acute wounds hold the dominant share, led by surgical and traumatic wounds which collectively contribute over 60% to the segment. Surgical procedures and injury-related treatments account for high demand in hospital and ambulatory settings. Burns and traumatic wounds require frequent irrigation, making wound wash solutions essential for cleaning and infection prevention. Chronic wounds like diabetic foot ulcers and pressure ulcers are rising steadily with the aging population and diabetes prevalence. However, their treatment often involves advanced care beyond initial wound cleansing, making acute wounds the primary driver of this segment.
Wound Wash Market Key Growth Drivers
Rising Surgical Procedures and Emergency Treatments
The increasing volume of surgeries and emergency treatments significantly drives the wound wash market. Hospitals and ambulatory surgical centers rely on wound wash solutions for post-operative care, minimizing infection risk and promoting faster recovery. According to WHO, over 300 million major surgeries are performed globally each year, creating sustained demand for sterile irrigation solutions. Emergency departments frequently treat trauma and burn injuries, further contributing to volume consumption. Wound wash solutions, especially single-use saline, are critical for initial cleaning and preparing wounds for dressing or suturing. The shift toward minimally invasive surgeries also increases the need for safe and efficient wound care products during outpatient recovery. As healthcare systems expand in emerging economies and surgical volumes rise due to aging populations, the need for fast, accessible wound cleansing will continue to grow, supporting consistent product demand across both acute and chronic care settings.
- For instance, the WHO reports more than 300 million major surgical procedures performed globally each year, directly increasing use of sterile saline wound wash in operating rooms and recovery units.
Growing Adoption in Home Healthcare and Long-Term Care Settings
The rising preference for home-based wound management and care in long-term facilities is a strong driver of wound wash market expansion. Patients with chronic wounds, diabetic ulcers, or post-surgical incisions are increasingly treated outside hospital settings, necessitating user-friendly and safe wound irrigation products. Wound wash sprays and single-use bottles offer hygienic, no-touch application, suitable for caregivers and patients managing wounds at home. Elderly populations in assisted living or long-term care facilities also require regular wound cleaning, especially for pressure ulcers or minor skin injuries. The growth of telehealth and remote monitoring supports guided wound care at home, reinforcing the demand for easy-to-use wound cleansing solutions. Additionally, healthcare providers aim to reduce hospital readmissions by equipping patients with effective home-based wound care kits, where wound wash products play a central role. This trend creates a stable consumer base outside traditional clinical environments.
- For instance, Dynarex offers single-use saline unit-dose vials (part of the Dynarex Resp-O2 line) which allow the user to control the dosage manually with graduated markings, supporting daily care of diabetic ulcers and pressure sores in home settings through standard saline irrigation practices.
Heightened Focus on Infection Control and Wound Hygiene
Infection prevention remains a critical concern in wound management, reinforcing the use of wound wash products in both acute and chronic care settings. Proper wound irrigation is a key step in minimizing bacterial load before dressing application or surgical closure. Healthcare providers prioritize wound cleansing protocols as part of infection control standards to prevent complications such as cellulitis, sepsis, or delayed healing. Regulatory bodies and accreditation agencies emphasize the use of sterile and approved irrigation solutions, increasing compliance among hospitals and outpatient clinics. Wound wash sprays and single-use saline formats align with infection control measures due to their non-contact design and lower contamination risk. Post-pandemic, infection awareness among consumers has also increased, raising the demand for wound care solutions that offer antimicrobial protection and cleanliness assurance. As antimicrobial resistance becomes a rising concern, mechanical cleansing through sterile wound wash solutions is gaining favor over topical antibiotic applications.
Wound Wash Market Key Trends & Opportunities
Shift Toward Ergonomic and Advanced Packaging Designs
Product design innovation plays a vital role in differentiating offerings in the wound wash market. Manufacturers are investing in packaging types that enhance user convenience, control, and hygiene. Trigger spray bottles and finger spray formats are gaining traction due to their directional application and reduced risk of cross-contamination. Single-use bottles are also increasingly preferred in settings requiring strict sterility protocols. Furthermore, packaging that allows one-handed use, minimal product waste, and accurate volume dispensing is favored in both clinical and home care. As wound care extends beyond hospitals into home-based and long-term care scenarios, demand rises for intuitive, easy-to-use packaging. This trend opens opportunities for brands to develop compact, travel-friendly, and child-safe wound wash formats. Eco-friendly packaging options are also emerging in response to sustainability goals, giving companies an edge with environmentally conscious buyers. These advancements create strong product differentiation and improve patient adherence to wound hygiene protocols.
- For instance, Medline’s sterile trigger spray wound wash delivers saline at a calibrated pressure of 8 psi and allows one-handed operation, supporting safe debris removal.
Expansion of Retail and E-Commerce Distribution Channels
The growing availability of wound wash products through retail pharmacies and online platforms presents a major opportunity for market penetration. Over-the-counter access to wound care solutions is expanding as consumers increasingly manage minor injuries, burns, and chronic wounds at home. E-commerce platforms allow brands to directly engage with customers, offer subscription-based wound care kits, and educate users on wound hygiene practices. Retail visibility also enhances brand recognition and promotes impulse purchases of wound wash sprays for first-aid kits. Online availability supports bulk orders for home care agencies, long-term care facilities, and mobile health services. Product bundling with wound dressings, antiseptics, and bandages further drives consumer value perception. The COVID-19 pandemic accelerated consumer comfort with digital health purchases, a trend that continues to benefit wound wash sales. Companies that optimize multi-channel distribution, offer product personalization, and provide clear usage instructions will gain a competitive edge in this evolving retail landscape.
Wound Wash Market Key Challenges
Limited Awareness in Low-Income and Rural Settings
A major challenge facing the wound wash market is limited product awareness and access in low-income and rural regions. In many developing economies, traditional methods of wound cleaning such as tap water or home remedies-still prevail due to lack of education and limited healthcare outreach. Even where primary healthcare services are available, sterile wound wash products are often underutilized due to cost sensitivity or lack of stock. This gap in wound hygiene increases infection risks and slows wound healing. Healthcare workers in rural areas may also lack training on proper wound irrigation practices, further affecting adoption. Public health initiatives often prioritize vaccines, maternal care, or infectious disease control over wound management. Overcoming this challenge requires active collaboration between manufacturers, governments, and NGOs to educate communities, subsidize essential wound care kits, and strengthen rural healthcare supply chains. Expanding awareness campaigns and affordable pricing models are crucial for wider adoption.
Regulatory Compliance and Sterility Assurance Challenges
Wound wash solutions must meet strict regulatory and sterility standards, posing challenges for manufacturers in terms of compliance and quality assurance. Products classified as medical devices or pharmaceuticals require validation of sterility, biocompatibility, and shelf-life stability. Variations in classification and labeling rules across countries create additional barriers for global expansion. Any deviation in manufacturing practices can lead to product recalls, regulatory fines, or loss of market reputation. Maintaining aseptic packaging environments and validating spray mechanisms for non-contaminating use requires significant investment. Smaller companies often struggle to meet these standards, limiting their ability to scale or enter regulated markets. Furthermore, counterfeit or substandard wound wash products in unregulated markets pose safety risks and undermine trust in legitimate brands. Manufacturers must continually invest in robust quality control systems, regulatory intelligence, and compliant packaging innovations to ensure safe and globally accepted product offerings.
Wound Wash Market Regional Analysis
North America
North America dominates the wound wash market with a market share of over 35% in 2024, driven by high surgical volumes, strong healthcare infrastructure, and widespread adoption of advanced wound care protocols. The U.S. leads regional demand due to growing elderly populations, chronic wound cases, and favorable reimbursement policies. Rising home healthcare trends and increasing awareness about infection prevention further support market growth. Canada also contributes with expanding hospital networks and retail availability of over-the-counter wound wash products. Continued investment in wound management training and increased usage of single-use sterile solutions sustain the region’s leadership position.
Europe
Europe holds approximately 28% of the global wound wash market share in 2024, supported by established healthcare systems, a growing aging population, and strict infection control regulations. Countries like Germany, France, and the UK are key contributors due to advanced surgical care infrastructure and emphasis on post-operative hygiene. Chronic wounds related to diabetes and pressure ulcers are increasing across elderly populations, creating sustained demand for effective wound cleansing solutions. The presence of major wound care companies, along with government-funded wound care initiatives, ensures broad access to quality wound irrigation products across clinical and long-term care settings.
Asia Pacific
Asia Pacific accounts for nearly 22% of the wound wash market share in 2024, driven by rising healthcare access, urbanization, and growing surgical procedures in countries like China, India, Japan, and South Korea. Chronic wound prevalence is increasing due to rising diabetes rates and an aging population. Government investments in primary care and hospital infrastructure support greater wound care adoption. Local manufacturing expansion and e-commerce growth improve product availability, particularly in urban and semi-urban areas. However, lower awareness in rural areas remains a barrier. Demand is accelerating due to expanding medical tourism and rising focus on post-surgical care.
Latin America
Latin America captures around 8% of the global wound wash market share in 2024, with Brazil and Mexico leading regional consumption. Expanding access to basic healthcare services and rising surgical procedures drive demand for wound cleansing products. Public health systems in major countries are improving post-operative and emergency care services, supporting product usage in hospitals and outpatient settings. Retail growth and online pharmacies enhance product reach. However, inconsistent distribution networks and lower adoption in remote regions limit broader penetration. Despite challenges, the region presents growth opportunities through government health reforms and increasing awareness about wound hygiene.
Middle East & Africa (MEA)
The Middle East & Africa region holds nearly 7% of the global wound wash market share in 2024. Growth is concentrated in GCC countries like Saudi Arabia and the UAE, where advanced healthcare infrastructure and higher spending on surgical care support strong product adoption. In Africa, demand is rising gradually due to international health initiatives and expansion of hospital services, though product awareness and access remain limited. Increasing cases of trauma and burns in conflict-prone or low-income areas further highlight the need for sterile wound irrigation. Private sector growth and partnerships with NGOs offer potential for future market expansion.
Wound Wash Market Segmentations:
By Product
- Single Use Saline
- Bulk Solution
By Packaging Type
- Dispensing Cap Bottle
- Trigger Spray Bottle
- Finger Spray Bottle
- Single Use Bottle
By Wound Type
- Acute Wounds
- Surgical Wounds
- Traumatic Wounds
- Burns
- Chronic Wounds
- Venous Ulcers
- Pressure Ulcers
- Diabetic Foot Ulcers
- Others
By End User
- Hospitals
- Ambulatory Surgical Centers
- Clinics
- Long-Term Care Centers
- Home Care Settings
- Wound Care Centers
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The wound wash market is moderately fragmented, with a mix of global healthcare leaders and niche players actively competing across regions. Companies such as McKesson, Cardinal Health, Medline, and Mölnlycke Health Care maintain strong market positions due to their extensive distribution networks, wide product portfolios, and established clinical trust. These firms offer sterile, single-use solutions and innovative spray packaging that meet evolving hospital and outpatient needs. Emerging players like Clyra Medical Technologies and AMERX Health Care focus on antimicrobial formulations and user-friendly delivery formats, targeting ambulatory and home care segments. Several regional firms, including Zuche Pharmaceuticals and Steroplast Healthcare, enhance market accessibility in cost-sensitive geographies. Retail expansion and e-commerce presence are intensifying competition, while regulatory compliance and sterility assurance remain key differentiators. Strategic partnerships, product innovation, and regional expansion are core focus areas for sustaining growth and competitiveness across the market.
Key Player Analysis
- Cardinal Health
- Clyra Medical Technologies Inc.
- CD Medical
- Winchester Laboratories, LLC
- NeilMed Pharmaceuticals Inc.
- AMERX Health Care Corp
- McKesson
- DermaRite Industries, LLC.
- Steroplast Healthcare Limited
- Medline
- Zuche Pharmaceuticals Private Limited
- Mölnlycke Health Care
- Church & Dwight Co.
- Others
Recent Developments
- In 2023, Convatec has launched ConvaFoam™ in the United States, which is a line of innovative foam dressings for healthcare practitioners and patients. ConvaFoam™ is a versatile dressing that may be applied to many wound types at any point of the healing process, making it the ideal solution for wound care and skin protection.
- In May 2023, NovaBay Pharmaceuticals, Inc. successfully fulfilled a USD 1 million order from China Pioneer Pharma Holdings, Limited for its NeutroPhase Skin and Wound Cleanser.
Report Coverage
The research report offers an in-depth analysis based on Product, Packaging Type, Wound Type and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for sterile, single-use wound wash solutions will rise with growing focus on infection prevention.
- Home healthcare and remote wound management will drive product usage beyond clinical settings.
- Trigger spray and finger spray formats will gain traction due to user-friendly application.
- Rising chronic wound cases, especially diabetic ulcers and pressure injuries, will support steady product adoption.
- Retail pharmacies and e-commerce will expand access to wound wash products across regions.
- Manufacturers will focus on compact, travel-friendly, and eco-conscious packaging innovations.
- Asia Pacific will emerge as a key growth region with expanding surgical procedures and healthcare access.
- Public health programs and NGO partnerships will support market entry in underserved rural areas.
- Technological improvements in antimicrobial wound wash solutions will enhance clinical outcomes.
- Competitive pricing and education initiatives will increase adoption in cost-sensitive and emerging markets.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Surgical Procedures and Emergency Treatments
The increasing number of surgeries and trauma cases globally is driving demand for sterile wound wash solutions, as these products are essential for post-operative care and initial wound cleaning to reduce infection risk.
Growing Adoption in Home Healthcare and Long-Term Care
The shift toward home-based wound management and care in long-term facilities is boosting demand for user-friendly, single-use wound wash products, as more patients manage chronic wounds and post-surgical care outside hospitals.
Heightened Focus on Infection Control and Wound Hygiene
Stricter infection prevention protocols in healthcare settings and increased consumer awareness post-pandemic are fueling the use of sterile, single-use wound wash products that minimize contamination risk.
Shift Toward Ergonomic and Advanced Packaging Designs
Innovations in packaging, such as trigger and finger spray bottles, are making wound wash products easier and safer to use, driving adoption in both clinical and home care environments.
Expansion of Retail and E-Commerce Distribution Channels
Greater availability of wound wash products through pharmacies and online platforms is increasing market penetration, making these solutions more accessible for both healthcare providers and consumers managing wounds at home.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the wound wash market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the wound wash market projected to grow between 2024 and 2032?
Which wound wash market segment held the largest share in 2024?
What are the primary factors fueling the growth of the wound wash market?
Who are the leading companies in the wound wash market?
Which region commanded the largest share of the wound wash market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Product
- 1.2.1 Single Use Saline
- 1.2.2 Bulk Solution
- 1.3 By End User
- 1.3.1 Hospitals
- 1.3.2 Ambulatory Surgical Centers
- 1.3.3 Clinics
- 1.3.4 Long-Term Care Centers
- 1.3.5 Home Care Settings
- 1.3.6 Wound Care Centers
- 1.4 By Wound Type
- 1.4.1 Surgical Wounds
- 1.4.2 Traumatic Wounds
- 1.4.3 Burns
- 1.4.4 Venous Ulcers
- 1.4.5 Pressure Ulcers
- 1.4.6 Diabetic Foot Ulcers
- 1.5 By Packaging Type
- 1.5.1 Trigger Spray Bottle
- 1.5.2 Finger Spray Bottle
- 1.5.3 Single Use Bottle
- 1.5.4 Dispensing Cap Bottle
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 195.37 million → 2032: USD 261.27 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Wound Wash Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Wound Wash Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Wound Wash Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Wound Wash Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Wound Wash Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Wound Wash Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Wound Wash Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Wound Wash Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 195.37 million → 2032: USD 261.27 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Wound Wash Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Product - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Single Use Saline
- 12.3.7.2 Bulk Solution
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By End User - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Hospitals
- 12.4.7.2 Ambulatory Surgical Centers
- 12.4.7.3 Clinics
- 12.4.7.4 Long-Term Care Centers
- 12.4.7.5 Home Care Settings
- 12.4.7.6 Wound Care Centers
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Wound Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Surgical Wounds
- 12.5.7.2 Traumatic Wounds
- 12.5.7.3 Burns
- 12.5.7.4 Venous Ulcers
- 12.5.7.5 Pressure Ulcers
- 12.5.7.6 Diabetic Foot Ulcers
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Packaging Type - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Trigger Spray Bottle
- 12.6.7.2 Finger Spray Bottle
- 12.6.7.3 Single Use Bottle
- 12.6.7.4 Dispensing Cap Bottle
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Wound Wash End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Wound Wash Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Wound Wash Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Wound Wash Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 McKesson
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Mölnlycke Health Care
- 18.4 Cardinal Health
- 18.5 Medline
- 18.6 DermaRite Industries
- 18.7 Clyra Medical Technologies
- 18.8 AMERX Health Care Corp
- 18.9 Steroplast Healthcare Limited
- 18.10 NeilMed Pharmaceuticals Inc.
- 18.11 Zuche Pharmaceuticals Private Limited
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

