
Antihypertensive drugs gain volume as generics cap prices
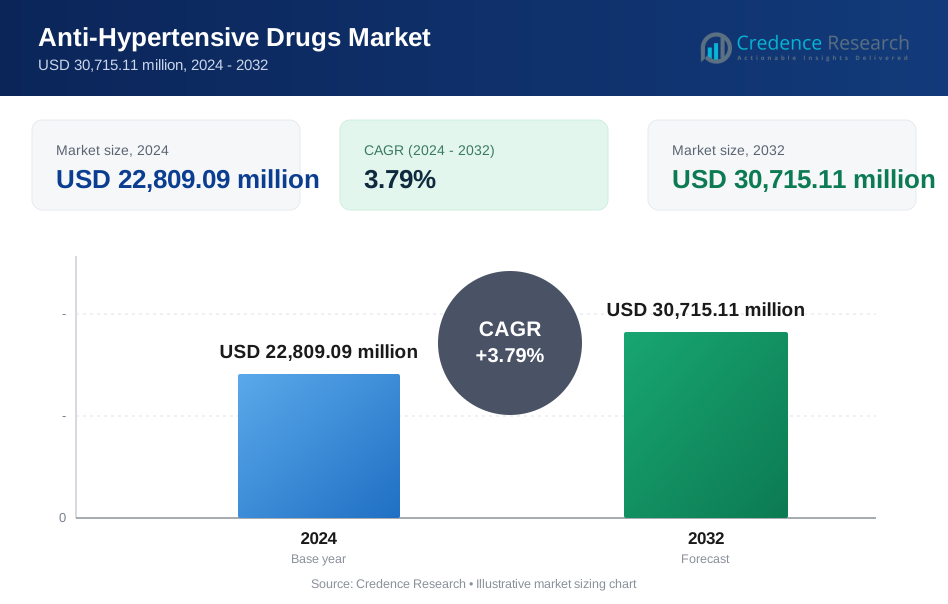
The global antihypertensive drugs market was valued at USD 21.49 billion in 2025 and is projected to increase from USD 22.29 billion in 2026 to USD 30.92 billion by 2035, registering a CAGR of 3.70% during 2026–2035. Demand comes from a very large treated population, since WHO estimates that 1.4 billion people lived with hypertension in 2024 and just over one in five had it under control. Most spending goes to low-cost oral generics, so growth depends on more patients starting and staying on therapy rather than on price. North America held the largest regional share, 34.0% in 2025, supported by high diagnosis rates and wider use of branded combinations. Asia Pacific is the fastest-growing region at 4.69% a year, as screening programs expand in China and India. Single-pill combinations and the 2026 U.S. approval of the first aldosterone synthase inhibitor are adding new value at the top of the market.
What counts as antihypertensive drugs in this report?
The scope counts revenue from prescription medicines used to lower systemic blood pressure in adults and children with hypertension. It covers ACE inhibitors, angiotensin II receptor blockers, calcium channel blockers, beta-blockers, vasodilators, the direct renin inhibitor aliskiren and other classes such as diuretics and aldosterone synthase inhibitors. Fixed-dose combinations are counted under the class of their main renin-angiotensin or calcium channel component.
Medicines for pulmonary arterial hypertension, which act on lung vessels rather than systemic blood pressure, sit outside the scope. Blood pressure monitors, renal denervation procedures and over-the-counter supplements are also excluded from the valuation. The value chain runs from active ingredient synthesis, much of it in India and China, through tablet manufacturing, wholesale distribution and pharmacy dispensing.
Antihypertensive Drugs Market Insights
- The antihypertensive drugs market grows from USD 21.49 billion in 2025 to USD 30.92 billion by 2035, a CAGR of 3.70% during 2026–2035.
- North America held 34.0% of global value in 2025, supported by high diagnosis rates and wider use of branded combination therapies.
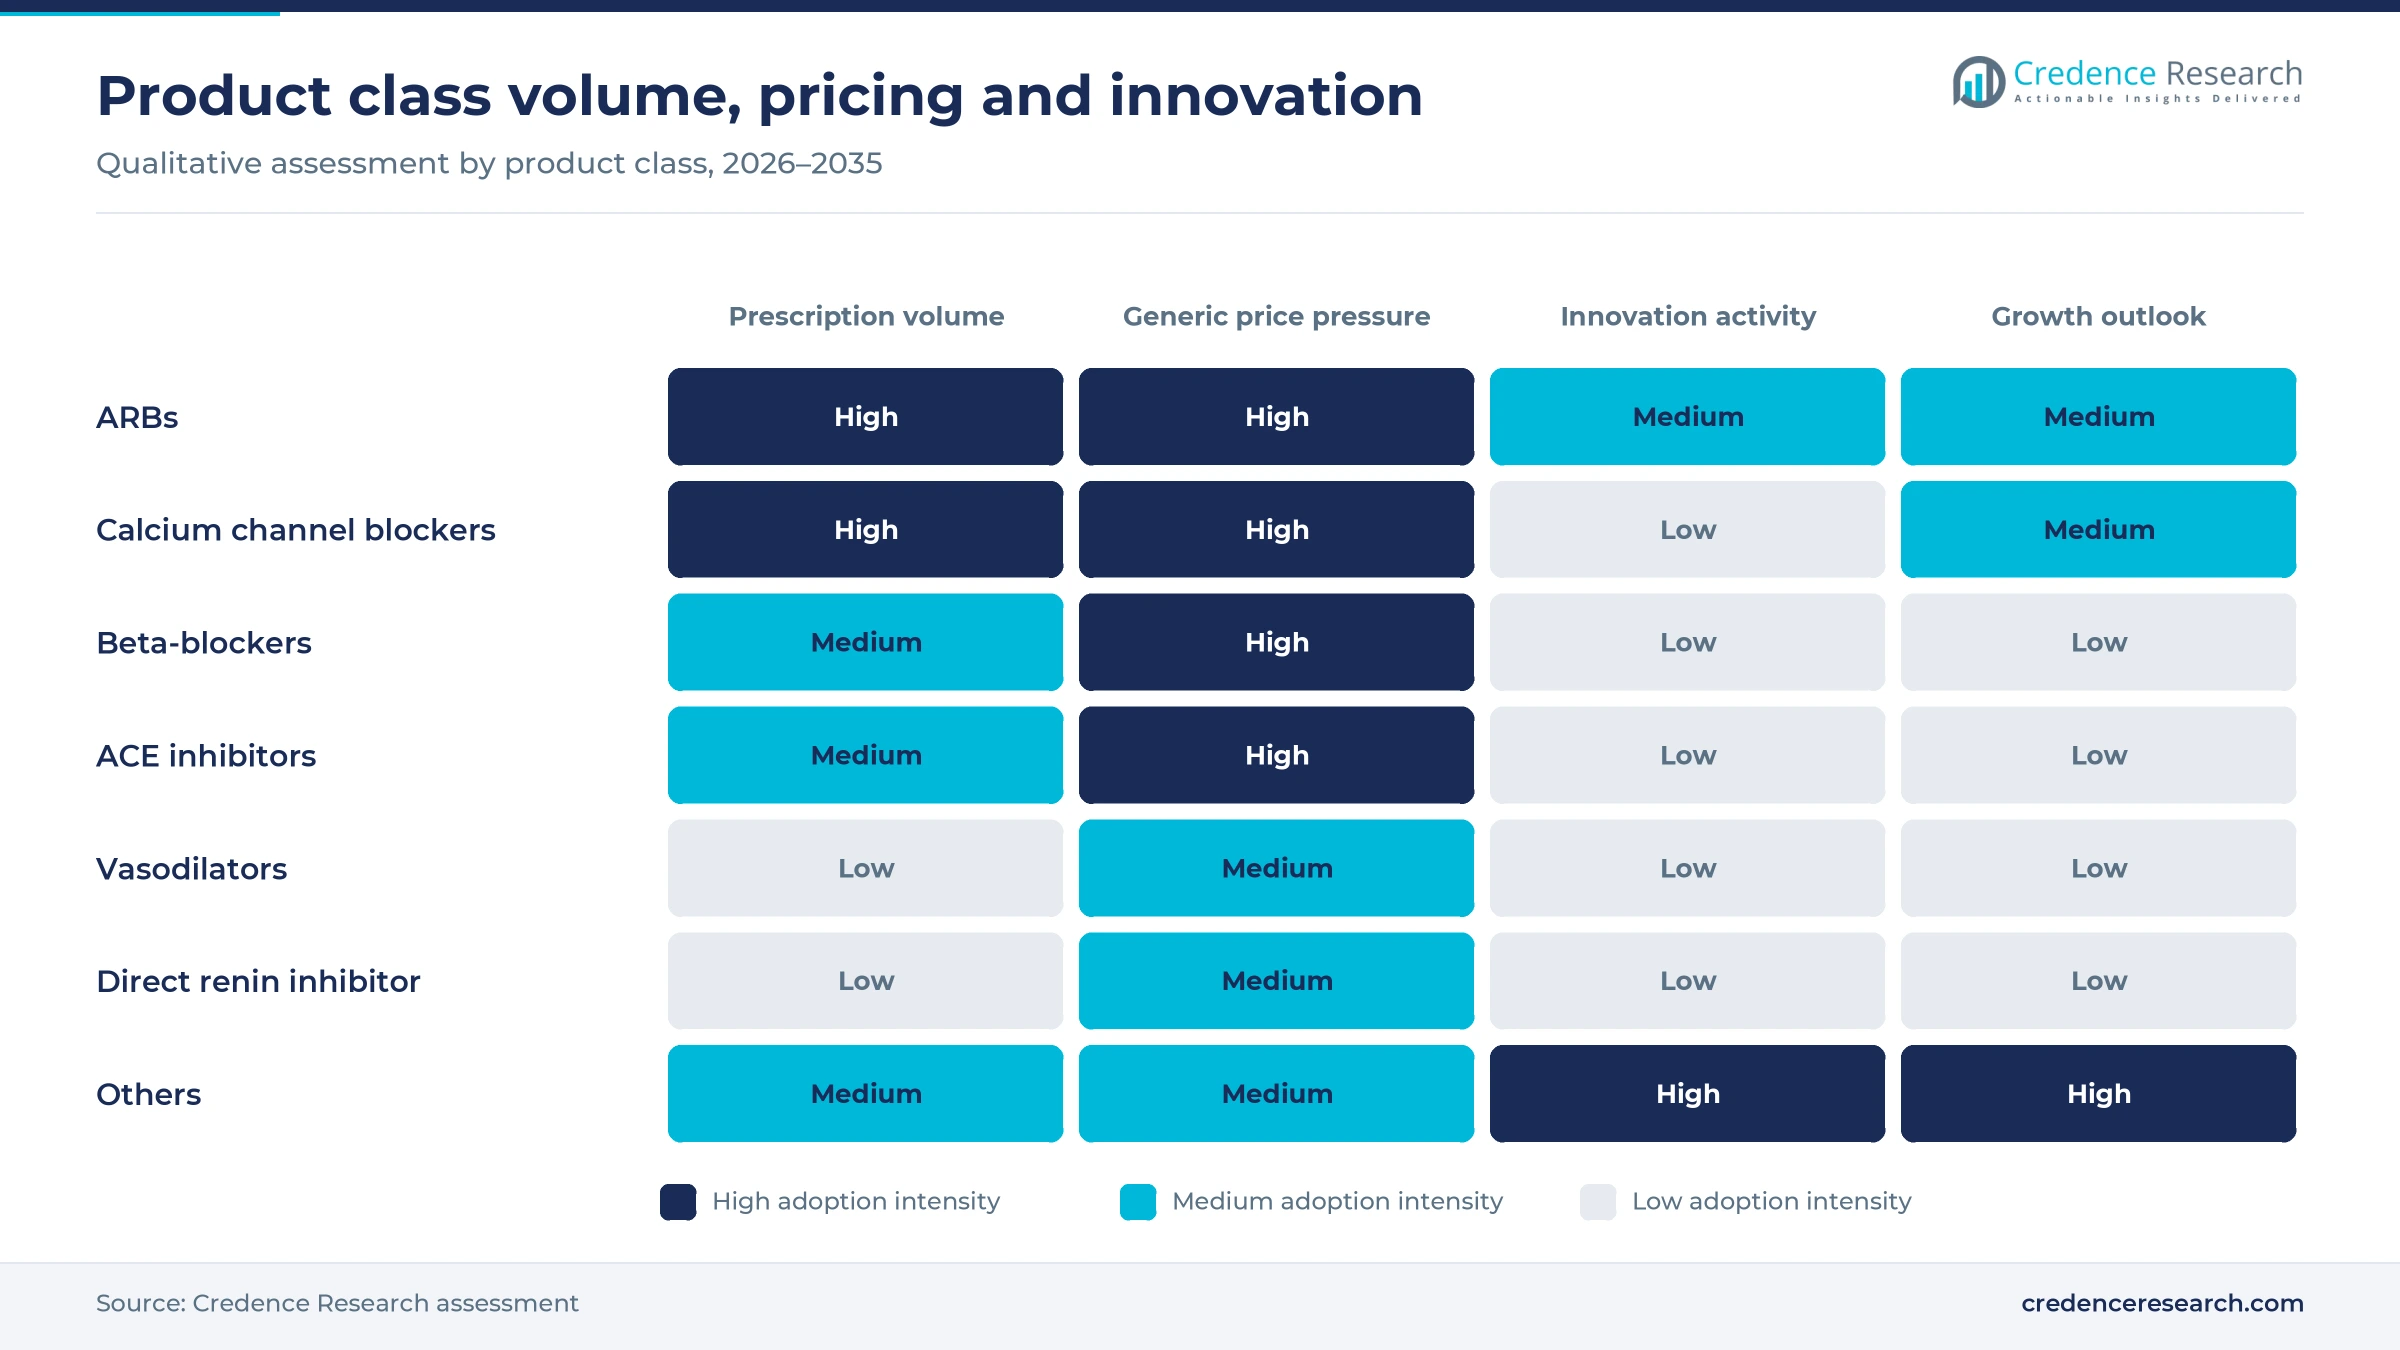
- Angiotensin II receptor blockers led product classes with 30.0% of 2025 value, helped by good tolerability and frequent use in single-pill combinations.
- AstraZeneca announced FDA approval of Baxfendy in May 2026, the first aldosterone synthase inhibitor for adults whose blood pressure is not adequately controlled.
- WHO reported in September 2025 that 1.4 billion people lived with hypertension in 2024, leaving a large untreated pool for low-cost generic therapy.
ARBs and oral tablets hold the largest shares
Why do angiotensin II receptor blockers lead product value?
Based on product, the market is categorized into ACE inhibitors, angiotensin II receptor blockers, calcium channel blockers, beta-blockers, vasodilators, direct renin inhibitor and others. Angiotensin II receptor blockers led with 30.0% of 2025 value, because losartan, valsartan and telmisartan cause less cough than ACE inhibitors. The others group grows fastest at 6.08% a year, as aldosterone synthase inhibitors and endothelin receptor antagonists add branded value for patients with uncontrolled blood pressure.
How dominant are oral tablets in blood pressure treatment?
Based on route of administration, the market is categorized into oral, parenteral and transdermal products. Oral tablets led with 94.0% of 2025 value, because nearly all long-term blood pressure treatment is taken by mouth once or twice a day. Oral products also grow fastest at 3.73% a year as single-pill combinations and new oral classes reach more patients. Parenteral agents serve hypertensive emergencies in hospitals, while transdermal clonidine remains a small niche.
Where do patients fill blood pressure prescriptions?
Based on distribution channel, the market is categorized into retail pharmacy, hospital pharmacy and others. Retail pharmacies led with 62.0% of 2025 value, because patients refill chronic blood pressure prescriptions every one to three months at community stores. The others channel, which includes online and mail-order pharmacies, grows fastest at 5.86% a year as 90-day refills and home delivery spread. Hospital pharmacies handle inpatient therapy and treatment starts after cardiovascular events.
| Segment Group | Leading Sub-segment | Share, 2025 | Fastest-growing Sub-segment | CAGR, 2026–2035 |
|---|---|---|---|---|
| By Product | Angiotensin II Receptor Blockers | 30.0% | Others | 6.08% |
| By Route of Administration | Oral | 94.0% | Oral | 3.73% |
| By Distribution Channel | Retail Pharmacy | 62.0% | Others | 5.86% |
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Uncontrolled patients and new guidelines lift volume
More than a billion patients with uncontrolled blood pressure
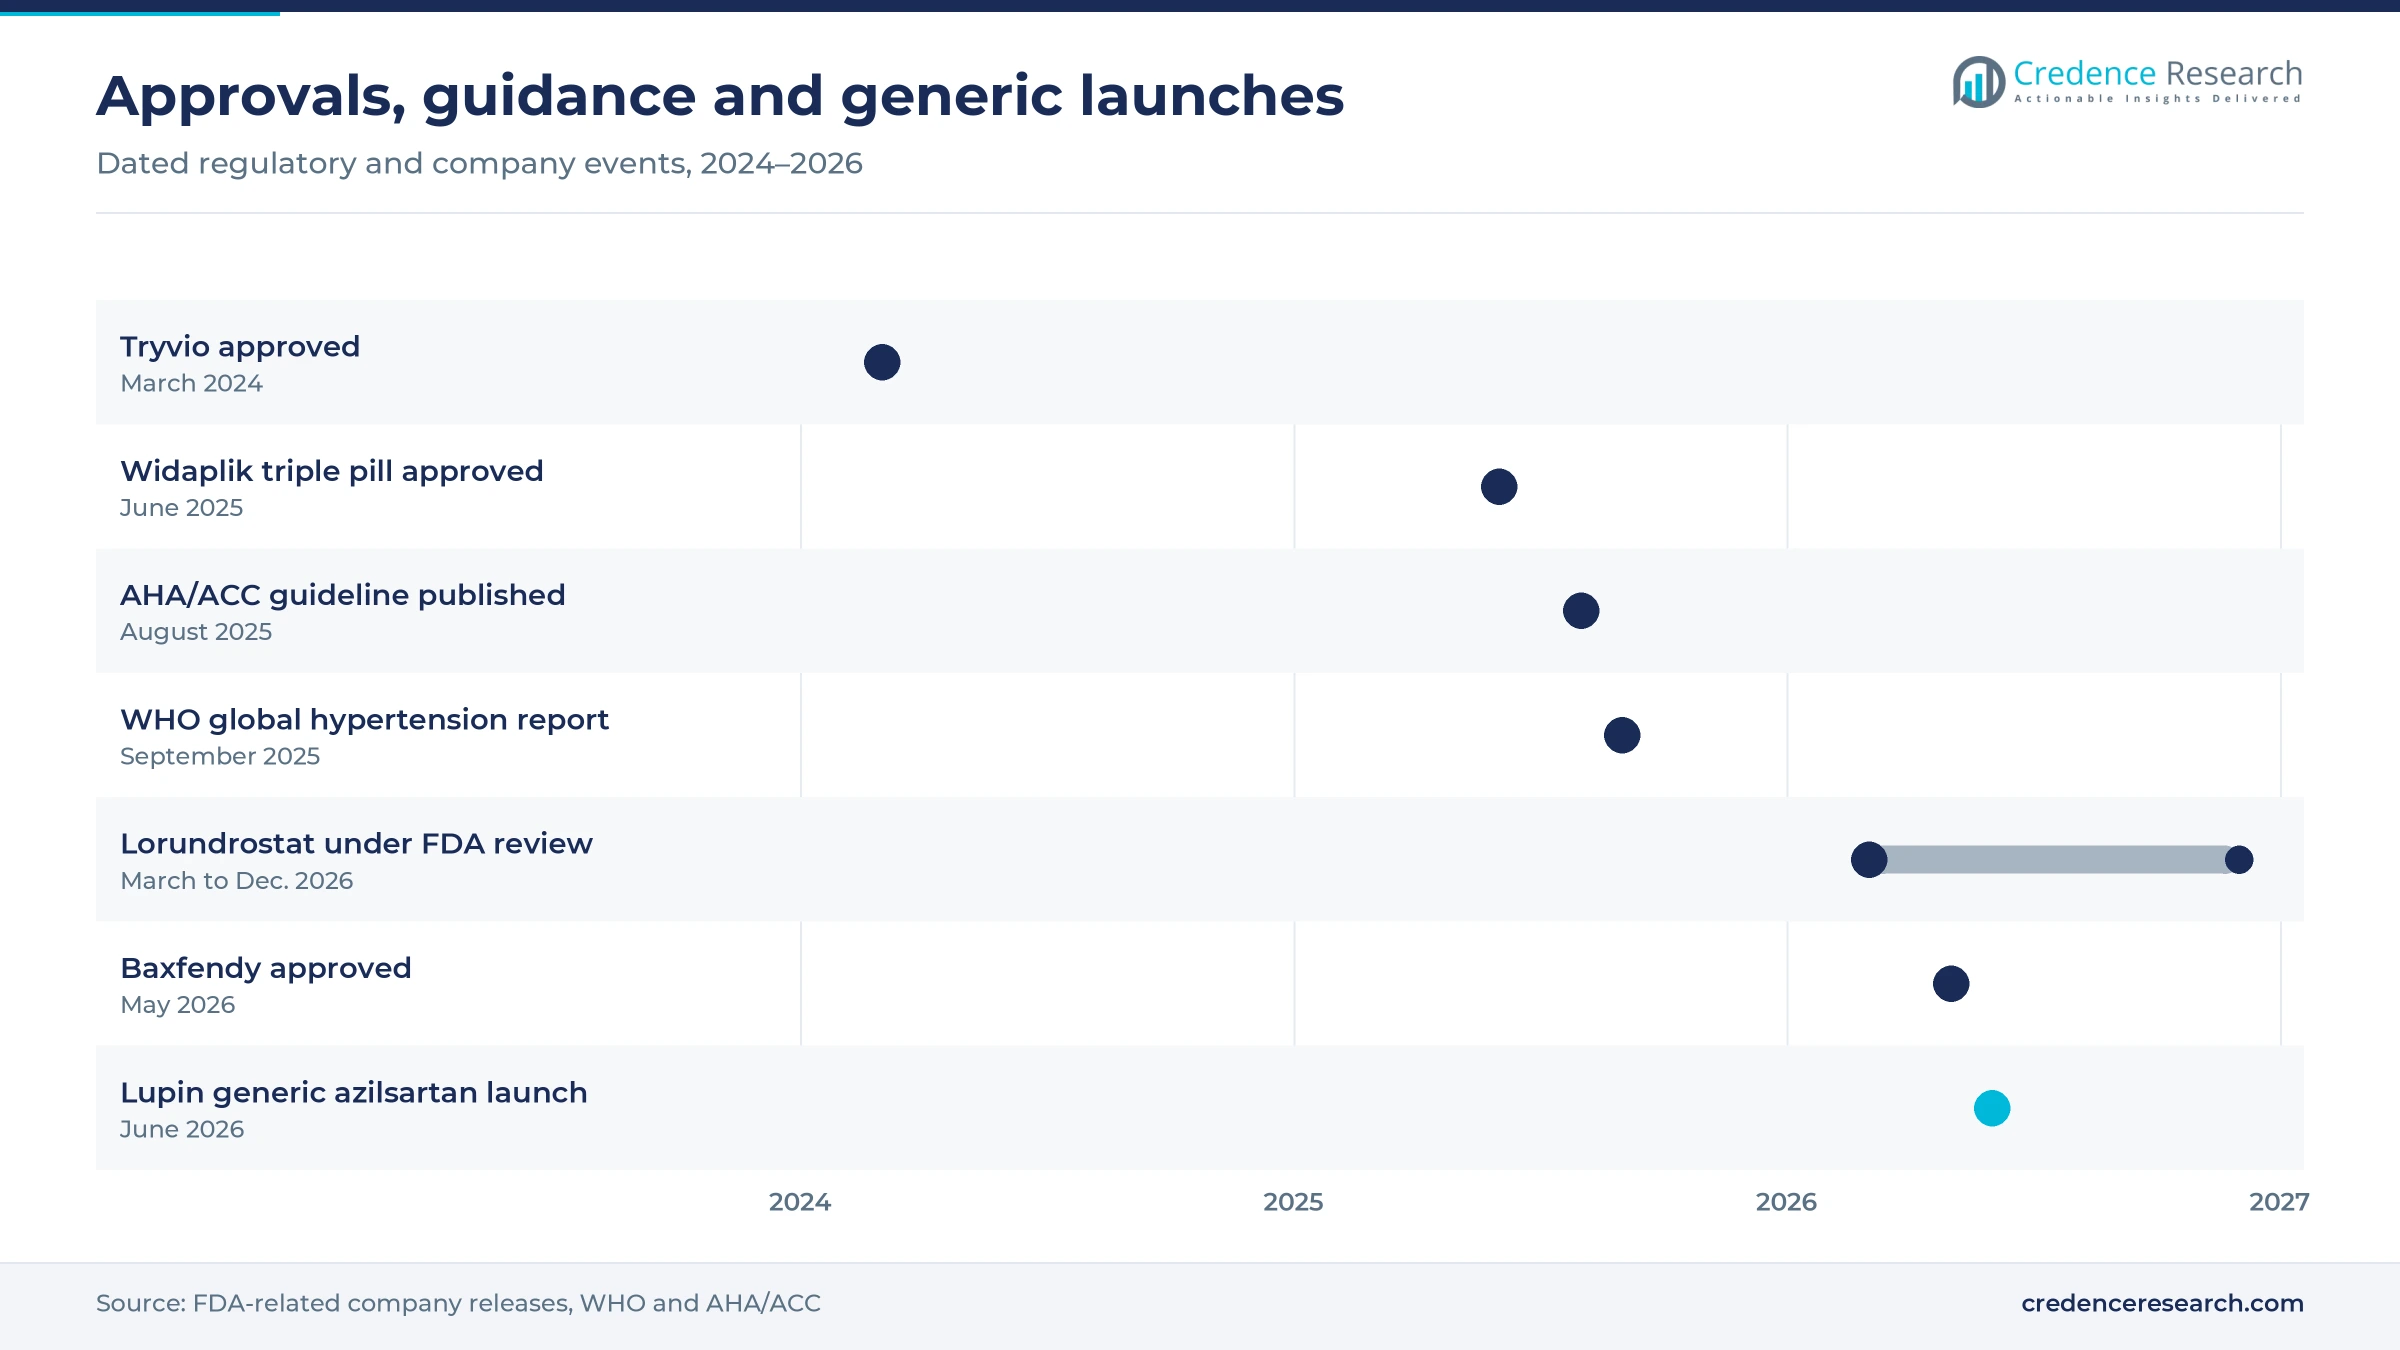
The gap between diagnosis and control is the main source of new prescription volume worldwide. The WHO reported in September 2025 that 1.4 billion people lived with hypertension in 2024, and only just over one in five had it under control. Only 28% of low-income countries report general availability of all WHO-recommended blood pressure medicines, compared with 93% of high-income countries. As a result, each gain in screening and supply converts directly into demand for antihypertensive drugs.
Guidelines favor earlier treatment with single-pill combinations
Updated guidelines are pushing clinicians to start drug therapy earlier and with two agents in one tablet. The 2025 AHA/ACC high blood pressure guideline, published in August 2025, recommends starting most adults with stage 2 hypertension on two first-line drugs, preferably as a single-pill combination. This approach raises the number of molecules per patient and supports branded combination products. In turn, prescription volume grows faster than the hypertensive population in markets that adopt these recommendations.
New mechanisms target patients who stay uncontrolled
New drug classes are targeting patients whose blood pressure stays high despite several existing medicines. The FDA approved Idorsia’s Tryvio in March 2024 as the first endothelin receptor antagonist for hypertension not adequately controlled on other drugs. AstraZeneca announced FDA approval of Baxfendy in May 2026, the first aldosterone synthase inhibitor for this population. Because treatment-resistant hypertension affects a sizable minority of treated adults, these branded add-on therapies lift value per patient.
Aging and cardiometabolic disease widen the treated pool
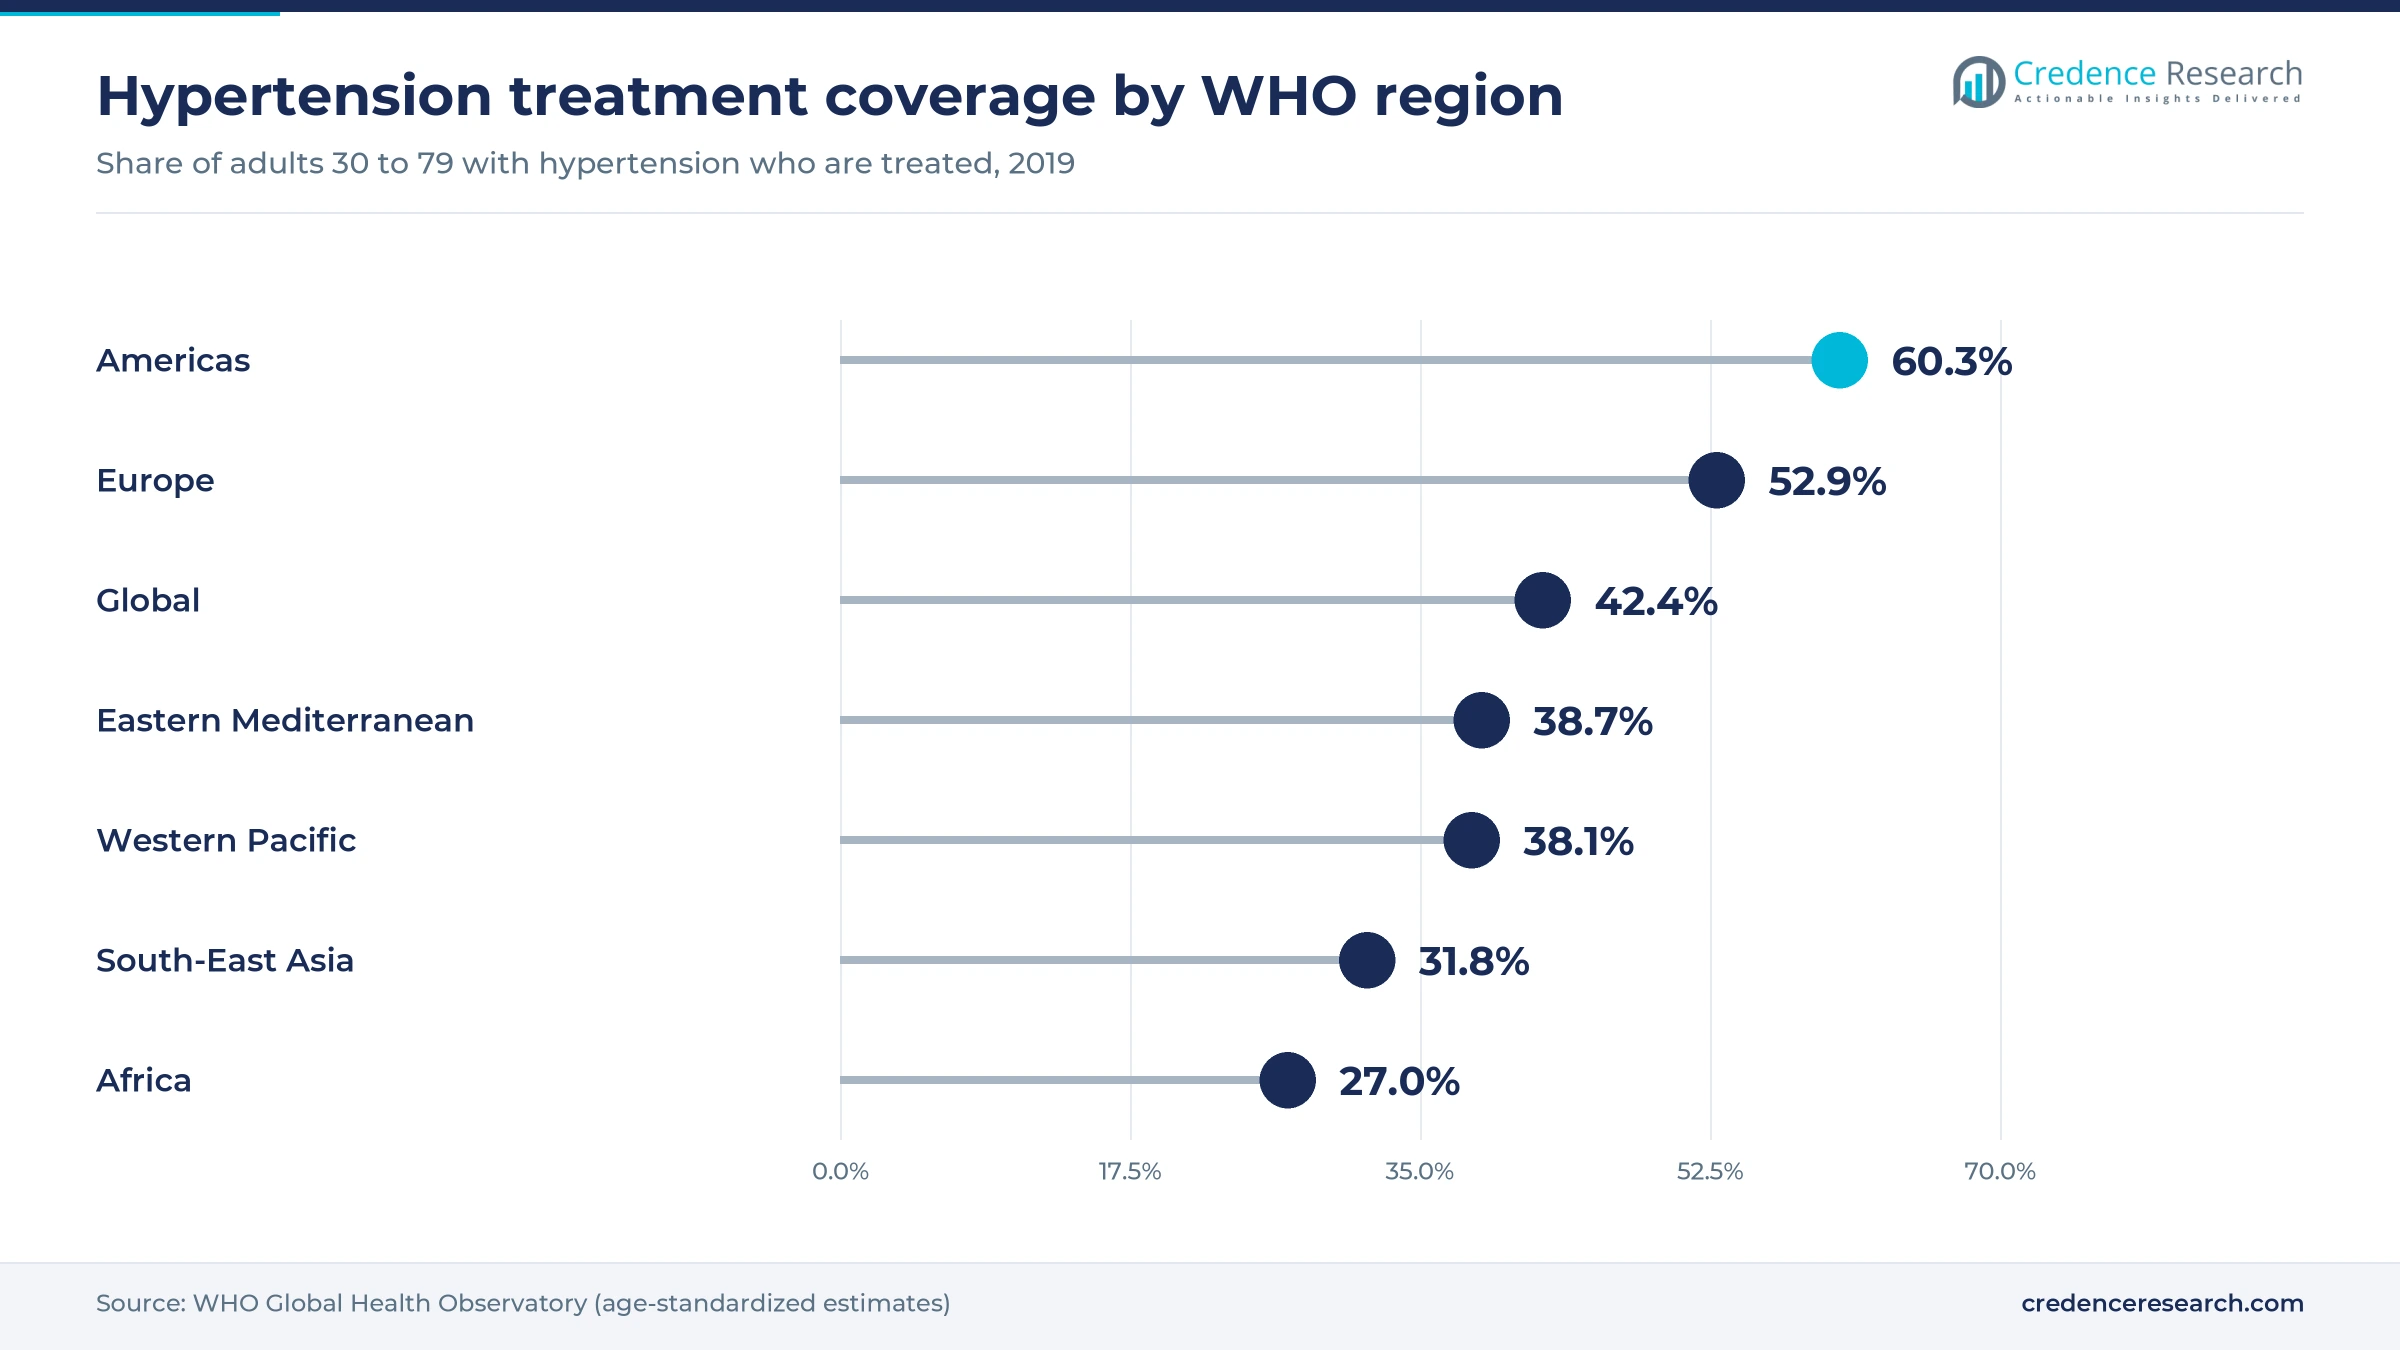
Aging populations raise hypertension prevalence, because blood pressure rises steadily with age in most countries. Obesity, diabetes and chronic kidney disease add further patients who need multiple blood pressure medicines to protect heart and kidney function. Wider use of home blood pressure monitoring also helps clinicians detect uncontrolled cases and intensify therapy sooner. Together, these forces support steady volume growth for antihypertensive drugs even as generic prices continue to fall. WHO data put treatment coverage at only 27.0% in the African region in 2019, against 60.3% in the Americas, which shows how much demand remains untapped.
Single-pill triples and new hormonal classes emerge
Shift toward low-dose triple single-pill combinations
Combination therapy is shifting from separate pills toward one tablet that holds two or three drugs at low doses. George Medicines announced FDA approval of Widaplik in June 2025, a single pill that combines telmisartan, amlodipine and indapamide. The company describes it as the first triple combination approved for initial therapy in the United States. Because low-dose triples can control more patients with fewer side effects, they are likely to gain share in guideline-driven practices.
Rise of aldosterone synthase inhibitors as a new oral class
Aldosterone synthase inhibitors are emerging as a new oral class that targets a hormonal driver of resistant hypertension. Baxfendy cut seated systolic pressure by 9.8 mmHg on a placebo-adjusted basis at the 2 mg dose in the BaxHTN Phase III trial. Mineralys announced in March 2026 that the FDA had accepted its application for lorundrostat, with a target action date of Dec. 22, 2026. As a result, competition within this new class could begin within a year.
Opportunity in low-cost generics for underserved countries
Low- and middle-income countries offer the largest volume opportunity, because control rates remain below 20% in 99 of 195 countries. Manufacturers in India and China can supply amlodipine, losartan and other WHO-recommended medicines at very low cost. Public programs with standard treatment protocols raised control in parts of Bangladesh from 15% to 56% between 2019 and 2025. As a result, tender-based supply of generic pharmaceuticals can expand treated patients rapidly.
Opportunity in first-to-file generics of recent branded ARBs
Patent expiries on newer branded products create openings for generic makers that file early with regulators. Lupin launched generic azilsartan medoxomil tablets in the United States in June 2026, referencing Edarbi, with eligibility for 180-day exclusivity. First-to-file generics capture high early margins before more competitors enter the market. Companies such as Lupin, Dr. Reddy’s, Sun Pharmaceutical and Teva therefore compete to be first on remaining branded molecules and combinations.
Generic price erosion and poor adherence slow value
Generic price erosion limits value growth
Most blood pressure molecules lost patent protection years ago, so prices for common tablets are very low in mature markets. Amlodipine, losartan, lisinopril and metoprolol sell for a few cents per dose in many countries, which caps revenue even when volume grows. Tender systems in Europe and volume-based procurement in China push prices down further with each cycle. As a result, value growth lags prescription growth across most product classes through 2035.
Poor adherence keeps control rates low
Many patients stop treatment within a year because hypertension causes few symptoms until complications appear. WHO data show that only 42.4% of adults with hypertension worldwide were receiving treatment in 2019. Side effects, pill burden and out-of-pocket costs further reduce persistence, especially in low-income settings. Because lost adherence means lost refills, manufacturers and payers invest in combination pills, pharmacy follow-up and digital reminders.
Impurity findings and recalls strain generic supply
Quality failures can disrupt supply, because a few active ingredient plants serve much of the global generic market. Nitrosamine impurity findings forced recalls of valsartan, losartan and irbesartan products from 2018 onward, and regulators still require testing for these impurities. Such events lead to shortages, switching costs and stricter audits of suppliers in India and China. In turn, manufacturers face higher compliance spending, which squeezes margins on low-priced tablets.
Procedure-based options compete for resistant cases
Non-drug approaches compete for some patients, especially those with resistant hypertension or poor tolerance of medicines. The FDA approved two renal denervation systems in November 2023, which offer a procedure-based option for patients who remain uncontrolled. Lifestyle programs that cut salt intake and weight can also reduce or delay the need for medicines. However, these approaches add to rather than replace drug therapy for most patients, so their effect on demand stays limited.
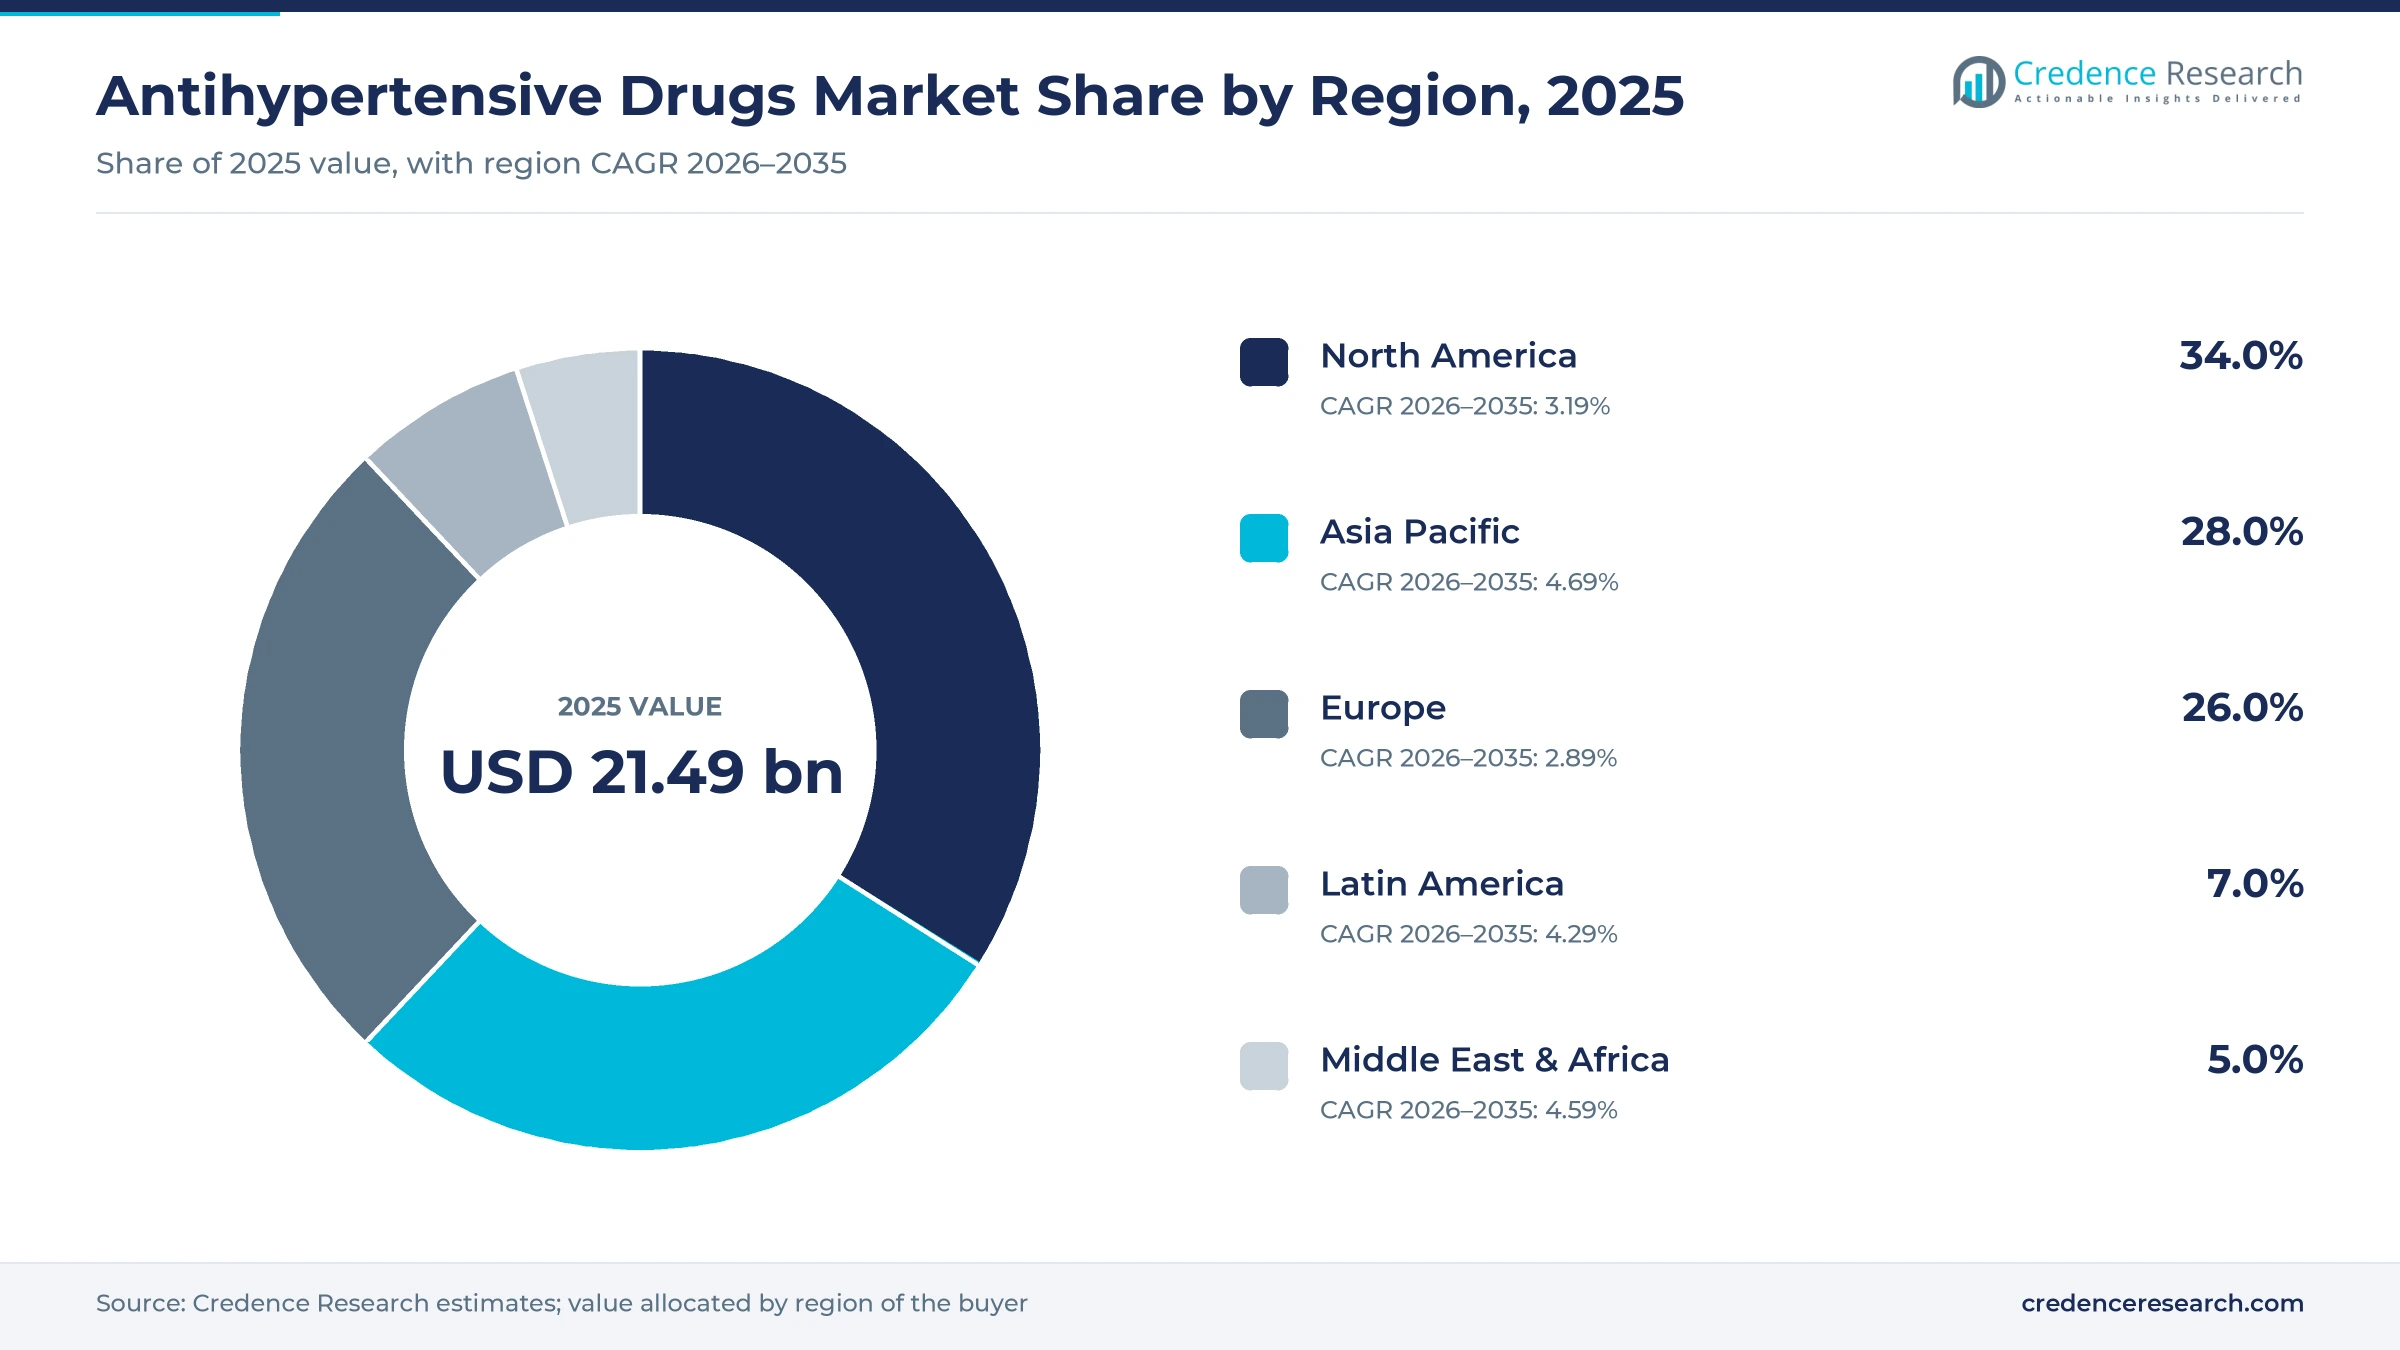
North America leads while Asia Pacific grows fastest
| Region | Value, 2025 (USD billion) | Share, 2025 | CAGR, 2026–2035 |
|---|---|---|---|
| North America | 7.31 | 34.0% | 3.19% |
| Asia Pacific | 6.02 | 28.0% | 4.69% |
| Europe | 5.59 | 26.0% | 2.89% |
| Latin America | 1.50 | 7.0% | 4.29% |
| Middle East & Africa | 1.07 | 5.0% | 4.59% |
North America leads on diagnosis and branded combinations
North America held the largest regional share, 34.0% of 2025 value, and grows at 3.19% a year through 2035. The United States leads, because nearly half of adults have high blood pressure under current definitions and most are diagnosed through routine care. Branded products such as Baxfendy and Widaplik add premium value on top of a large generic base. However, generic price competition and pharmacy benefit pressure keep regional growth below the global rate.
Asia Pacific adds the most new patients
Asia Pacific accounted for a 28.0% regional share in 2025 and is the fastest-growing region at 4.69% a year. China and India hold the largest hypertensive populations, and screening programs continue to bring new patients into treatment. Japan contributes high value per patient through branded receptor blockers and calcium channel blockers. Because China’s volume-based procurement has cut generic prices sharply, regional growth comes mainly from higher treated volumes.
Europe grows slowest under reference pricing
Europe held a 26.0% regional share in 2025 and grows at 2.89% a year, the slowest rate among regions. Germany, France, the United Kingdom, Italy and Spain rely on reference pricing and tenders that keep generic prices low. European guidelines favor starting most patients on a two-drug single-pill combination, which supports prescription volume. Even so, high generic penetration limits value growth across most European markets.
Latin America widens public access to treatment
Latin America accounted for 7.0% of 2025 value and grows at 4.29% a year. Brazil and Mexico lead demand, supported by public pharmacy programs that dispense common blood pressure medicines at little or no cost. Expanding primary care and the HEARTS program in the Americas also help more patients reach blood pressure control.
Middle East & Africa holds large unmet need
Middle East & Africa held 5.0% of 2025 value and grows at 4.59% a year. WHO data show that the African region has the lowest treatment coverage among WHO regions, which leaves large unmet demand. Gulf states fund branded and combination products through public insurance, while most African markets depend on low-cost generics.
First-in-class approvals and generic launches
| Development | Status and market relevance |
|---|---|
| In March 2024, Idorsia announced FDA approval of Tryvio, the first endothelin receptor antagonist for hypertension. | Approved as add-on therapy for adults not adequately controlled on other medicines. |
| In June 2025, George Medicines announced FDA approval of Widaplik, a telmisartan, amlodipine and indapamide single pill. | Approved for adults, including as initial treatment, widening branded combination options. |
| In March 2026, Mineralys announced FDA acceptance of its application for lorundrostat in hypertension. | Under review with a target action date of Dec. 22, 2026, which could add a second aldosterone synthase inhibitor. |
| In May 2026, AstraZeneca announced FDA approval of Baxfendy, the first aldosterone synthase inhibitor. | Approved as add-on therapy for adults whose blood pressure is not adequately controlled. |
| In June 2026, Lupin launched generic azilsartan medoxomil tablets in the United States. | Launched as first-to-file with eligibility for 180-day exclusivity against Edarbi. |
Combination pills and new mechanisms reshape therapy
- Low-dose triple single-pill combinations pair three drug classes at reduced doses, which aims to lower blood pressure faster with fewer side effects.
- Aldosterone synthase inhibitors block the enzyme that makes aldosterone, a hormone that drives resistant hypertension in many patients.
- Investigational RNA-targeted therapies such as zilebesiran aim to silence angiotensinogen production in the liver with injections given every few months, which could ease adherence for patients who miss daily tablets.
- Connected cuffs and remote titration link home readings to clinician dashboards, so doses can be adjusted between office visits and uncontrolled patients are flagged sooner.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Generic makers and originators split the market
The market is highly fragmented, because most volume comes from off-patent molecules made by many generic manufacturers. Originators such as Novartis, Takeda, Boehringer Ingelheim and AstraZeneca built the receptor blocker and related classes, and they now compete mainly through combination products, newer mechanisms and established brands in emerging markets. AstraZeneca has returned to the forefront with Baxfendy, the first aldosterone synthase inhibitor approved in the United States. Generic leaders, including Teva, Sun Pharmaceutical, Lupin, Dr. Reddy’s and Emcure, compete on cost, regulatory approvals and first-to-file opportunities in the United States and Europe. Indian companies also hold large branded generic portfolios at home, where doctors often prescribe by brand. Smaller specialists such as Idorsia, George Medicines and Mineralys bring new mechanisms or combinations and often seek partners for wider commercial reach.
Companies profiled and their roles in this market
| Company | Type | Role in the market |
|---|---|---|
| Novartis | Originator | Valsartan (Diovan) and valsartan-based combinations; originated aliskiren |
| Teva Pharmaceutical Industries Ltd. | Generics | Broad generic range of receptor blockers, calcium channel blockers and beta-blockers |
| Sun Pharmaceutical Ltd. | Generics and branded generics | Cardiovascular generics in the United States and branded generics in India |
| Emcure Pharma | Branded generics | Cardiovascular brands in India and other emerging markets |
| Takeda Pharmaceutical Company Limited | Originator | Azilsartan (Edarbi) and candesartan receptor blockers |
| Lupin Limited | Generics | First-to-file U.S. generic azilsartan medoxomil, launched in June 2026 |
| Dr. Reddy's | Generics | Generic receptor blockers and combinations in the United States and India |
| Boehringer Ingelheim International GmbH | Originator | Telmisartan (Micardis) and its combinations |
| AstraZeneca plc | Originator | Baxdrostat (Baxfendy), the first aldosterone synthase inhibitor, and candesartan |
Why value grows slower than prescription volume
Credence Research’s view is that the antihypertensive drugs market will grow slowly in value but strongly in volume, because generic tablets dominate treatment worldwide. The main value additions come from single-pill combinations and new classes for resistant hypertension, led by aldosterone synthase inhibitors. Branded launches such as Baxfendy will lift spending per patient in North America and Europe, while low-cost generics drive treated volume in Asia Pacific, Latin America and Africa. The key risk to the forecast is faster price erosion from tenders and procurement programs than currently assumed.
How the 2025 baseline and forecast were built
The report uses 2025 as the base year, 2026 as the first forecast year and 2035 as the final forecast year. Market values come from the Credence Research model, which builds spending from treated patient populations, product class mix and prevailing prices. Segment and regional splits are Credence Research estimates based on prescribing patterns, pricing levels and access conditions. Inputs drew on WHO reports and Global Health Observatory data, FDA approvals, clinical guidelines and company press releases and filings. No primary interviews or surveys were conducted for this edition of the report.
Resistant hypertension drives branded value to 2035
By 2035, the market reaches USD 30.92 billion, as more patients start treatment and newer classes add branded value. Growth stays modest because generic prices keep falling in mature markets, but treated volume rises steadily with aging and wider screening. Asia Pacific should gain share as China and India bring more patients into care, while North America remains the largest region. Aldosterone synthase inhibitors and triple combinations should reshape treatment of uncontrolled hypertension. Companies with low-cost manufacturing or differentiated mechanisms are best placed to gain share through 2035.
Frequently Asked Questions
How big is the antihypertensive drugs market?
Which product class leads the market?
Which region holds the largest share?
What is driving demand for antihypertensive drugs?
Which new drug classes have reached the market?
Which route of administration dominates?
Who are the leading companies?
How do generics affect the market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Product
- 1.2.1 Angiotensin II Receptor Blockers
- 1.2.2 Calcium Channel Blockers
- 1.2.3 Beta-blockers
- 1.2.4 ACE Inhibitors
- 1.2.5 Vasodilators
- 1.2.6 Direct Renin Inhibitor
- 1.2.7 Others
- 1.3 By Route of Administration
- 1.3.1 Oral
- 1.3.2 Parenteral
- 1.3.3 Transdermal
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 21.49 billion → 2035: USD 30.92 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Historical Period: 2018-2025
- 2.6.2 Base Year: 2025
- 2.6.3 Forecast Period: 2025-2035
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2035
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Antihypertensive Drugs Market Trends and Developments
- 4.1 Historical Industry Development, 2018-2025
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Antihypertensive Drugs Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis, 2018-2025
- 5.2 Demand Forecast, 2025-2035
- 5.3 Production and Output Trend, 2018-2025
- 5.4 Production and Output Forecast, 2025-2035
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Antihypertensive Drugs Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends, 2018-2025
- 6.3 Pricing Outlook, 2025-2035
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Antihypertensive Drugs Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Antihypertensive Drugs Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Antihypertensive Drugs Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Antihypertensive Drugs Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Antihypertensive Drugs Market Outlook, 2025-2035
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 21.49 billion → 2035: USD 30.92 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size, 2018-2025
- 11.1.4 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2035
- 11.2.1 Revenue Forecast to 2035
- 11.2.2 Volume Forecast to 2035
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Antihypertensive Drugs Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Product - Market Size and Forecast, 2025-2035
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size, 2018-2025
- 12.3.3 Revenue Forecast, 2025-2035
- 12.3.4 Volume Forecast, 2025-2035
- 12.3.5 Base-Year Market Share, 2025
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Angiotensin II Receptor Blockers
- 12.3.7.2 Calcium Channel Blockers
- 12.3.7.3 Beta-blockers
- 12.3.7.4 ACE Inhibitors
- 12.3.7.5 Vasodilators
- 12.3.7.6 Direct Renin Inhibitor
- 12.3.7.7 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Route of Administration - Market Size and Forecast, 2025-2035
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size, 2018-2025
- 12.4.3 Revenue Forecast, 2025-2035
- 12.4.4 Volume Forecast, 2025-2035
- 12.4.5 Base-Year Market Share, 2025
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Oral
- 12.4.7.2 Parenteral
- 12.4.7.3 Transdermal
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global Antihypertensive Drugs Geographic Market Outlook, 2025-2035
- 13.1 Regional Market Size and Share, 2025
- 13.2 Regional Market Forecast, 2025-2035
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Antihypertensive Drugs Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2025-2035
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Antihypertensive Drugs Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2025
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2025-2035
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Novartis
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Teva Pharmaceutical Industries Ltd.
- 17.4 Sun Pharmaceutical Ltd.
- 17.5 Emcure Pharma
- 17.6 Takeda Pharmaceutical Company Limited
- 17.7 Lupin Limited
- 17.8 Dr. Reddy's
- 17.9 Boehringer Ingelheim International GmbH
- 17.10 AstraZeneca plc
- 17.11 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

