
Market Overview
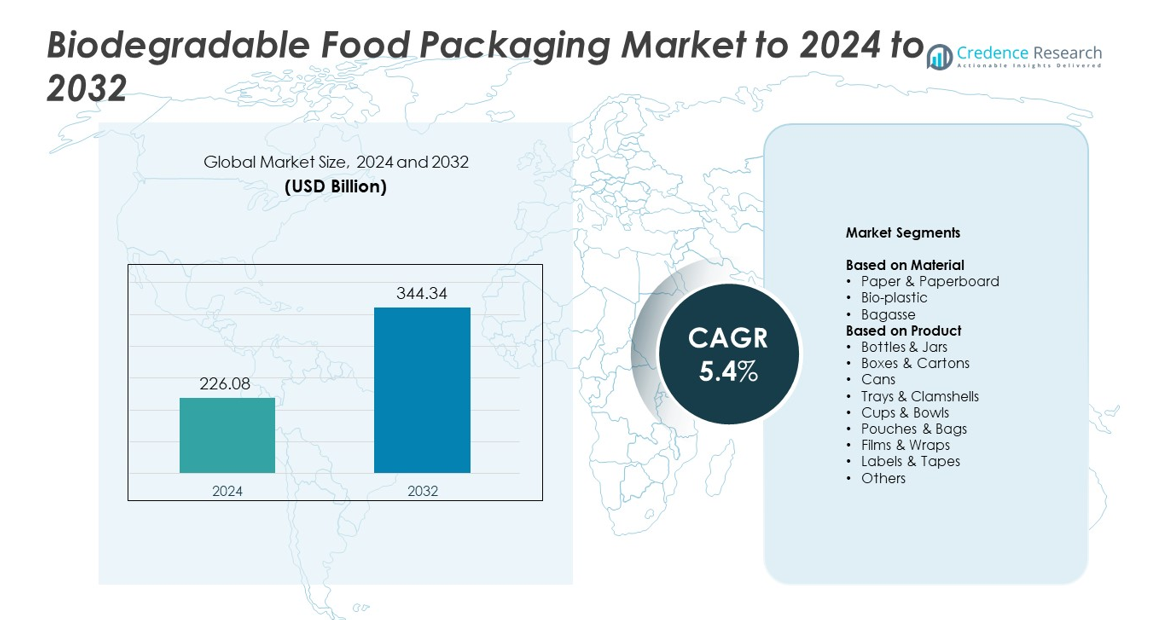
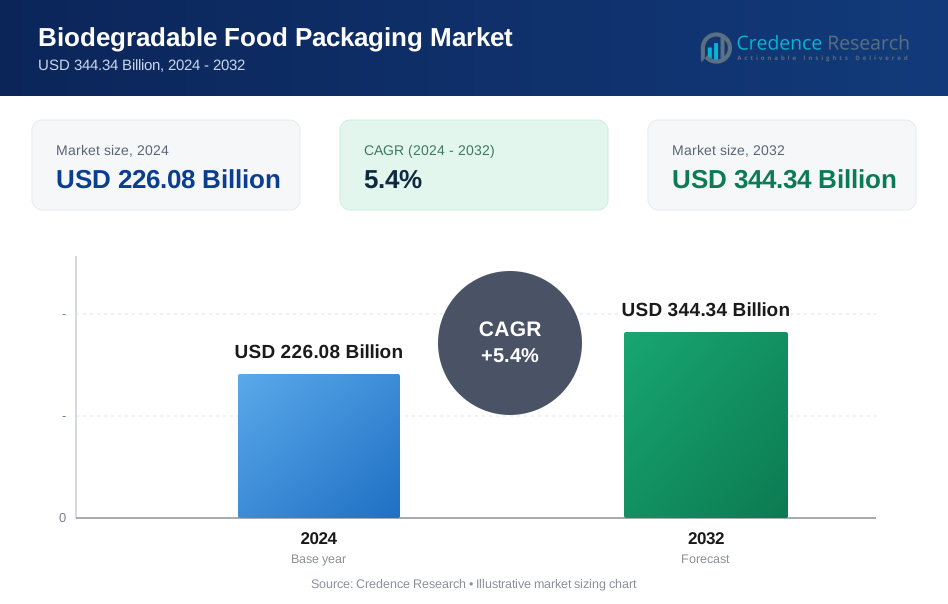
Biodegradable Food Packaging Market size was valued at USD 226.08 Billion in 2024 and is anticipated to reach USD 344.34 Billion by 2032, at a CAGR of 5.4% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Biodegradable Food Packaging Market Size 2024 | USD 226.08 Billion |
| Biodegradable Food Packaging Market, CAGR | 5.4% |
| Biodegradable Food Packaging Market Size 2032 | USD 344.34 Billion |
The biodegradable food packaging market includes leading companies such as Tetra Pak, Smurfit Westrock, Greenhope, Mondi, Notpla Limited, DS Smith, Amcor plc, Stora Enso, Elevate Packaging, and Sonoco Products Company. These players expand bio-based portfolios and invest in fiber, compostable film, and molded packaging technologies to meet rising sustainability demands from food manufacturers and retailers. They collaborate with foodservice chains and e-commerce platforms to scale recyclable and compostable formats across major applications. North America led the market in 2024 with about 34% share, followed by Europe with nearly 31%, supported by strong regulations, advanced recycling systems, and high consumer preference for eco-friendly packaging.
Market Insights
- The biodegradable food packaging market was valued at USD 226.08 Billion in 2024 and is projected to reach USD 344.34 Billion by 2032, growing at a CAGR of 5.4%.
- Strong market growth is driven by rising bans on single-use plastics and higher demand for safe, eco-friendly materials across foodservice, retail, and delivery sectors.
- Key trends include rapid expansion of molded fiber trays, coated paperboard, and high-barrier compostable films, with fiber-based products holding the largest material share at about 47%.
- Leading companies focus on recyclable designs, bio-based coatings, and circular packaging models to stay competitive as buyers demand low-carbon, compliant alternatives.
- North America led the market with about 34% share in 2024, followed by Europe at nearly 31% and Asia Pacific with about 26%, supported by strong regulatory pressure and fast adoption in takeaway, bakery, and ready-meal applications.
Market Segmentation Analysis:
By Material
Paper and paperboard dominated the material segment in 2024 with about 47% share due to strong adoption across foodservice, bakery, and ready-to-eat products. Brands preferred these materials because they offer high printability, wide recycling access, and lower contamination risk for fresh foods. Governments also supported this shift through bans on single-use plastics and incentives for fiber-based packaging expansion. Bio-plastic gained steady traction as compostable grades improved performance, while bagasse advanced through rising demand for molded fiber trays and cutlery, yet paper and paperboard stayed in the lead due to mature supply chains and high consumer acceptance.
- For instance, Stora Enso is doubling formed-fiber capacity at its Hylte mill. Annual output is rising from about 50 million to around 115 million units for food bowls, trays, and lids.
By Product
Boxes and cartons led the product segment in 2024 with nearly 29% share, driven by growing demand for takeaway meals, bakery items, and online grocery shipments. Food brands used these formats because they provide strong structural rigidity and better protection during transport. Rising quick-service restaurant activity boosted the use of folding cartons made from recyclable kraft and coated boards. Cups and bowls gained momentum in ready-to-eat categories, while pouches, films, and wraps expanded with barrier-grade bio-material development. However, boxes and cartons maintained leadership due to large-scale conversion capacity and broad use across retail and foodservice channels.
- For instance, in their 2023/24 fiscal year, DS Smith produced approximately 4.1 million metric tons of containerboard material, the paper used to make corrugated boxes.
Key Growth Drivers
Rising Global Restrictions on Single-Use Plastics
Governments expanded bans and levies on single-use plastics, which pushed food brands toward biodegradable packaging as a primary replacement. These rules accelerated the shift in retail, foodservice, and delivery sectors, where compliance deadlines created rapid procurement changes. Producers increased output of compostable and fiber-based formats to match regulatory timelines. Retailers also adopted biodegradable solutions to strengthen sustainability credentials. This regulatory momentum became the strongest growth driver across emerging and developed markets.
- For instance, before switching to paper straws, McDonald’s in the UK used around 1.8 million plastic straws daily.
Growing Demand for Sustainable and Safe Food Packaging
Consumers preferred packaging made from natural, compostable, or plant-based inputs due to rising environmental and health awareness. Food brands responded by reformulating packaging to reduce chemical migration risk and improve end-of-life disposal. This shift supported strong adoption of biodegradable trays, bowls, and wraps in convenience foods. Companies used sustainability labeling to attract eco-focused buyers, which boosted replacement of conventional plastics. High visibility on e-commerce platforms further amplified demand and reinforced this driver.
- For instance, Tetra Pak estimates that about 1.2 million tonnes of beverage cartons were collected and sent for recycling in 2021.
Expansion of Quick-Service Restaurants and Online Food Delivery
The growth of quick-service restaurants and rapid expansion of app-based food delivery increased demand for biodegradable containers, cartons, cups, and bags. Food chains adopted fiber-based and compostable formats to meet rising takeaway volumes and lower their environmental footprint. Packaging suppliers scaled molded fiber and coated paperboard lines to support heavier loads and temperature variations. Growth in cloud kitchens and ready-meal brands also strengthened consistent procurement of biodegradable solutions, making this a major contributor to overall market expansion.
Key Trends and Opportunities
Advancements in Compostable and Bio-Based Materials
Producers accelerated development of high-barrier compostable films, heat-resistant biopolymers, and improved molded fiber designs. These upgrades allowed biodegradable packaging to replace synthetic plastics in fresh foods, sauces, frozen meals, and ready-to-eat products. Innovations in PLA blends, PHA resins, and water-based coatings opened new applications where durability and moisture resistance were earlier concerns. This trend created opportunities for brands to reduce plastic waste without sacrificing shelf life or product security.
- For instance, NatureWorks’ Blair, Nebraska plant has a nameplate capacity of about 150,000 metric tons of Ingeo PLA each year.
Growth of Circular Packaging and Closed-Loop Systems
Demand increased for packaging that fits into composting, recycling, or hybrid recovery systems. Retailers partnered with waste operators to expand organics collection and improve sorting for fiber-based materials. Food chains introduced take-back programs for compostable containers, while cities upgraded composting facilities to handle higher bioplastic volumes. These developments created strong opportunities for packaging firms that design materials aligned with circularity targets and municipal processing capabilities.
- For instance, the use of a Universal Bottle program in Brazil meant Coca-Cola produced approximately 1.8 billion fewer single-use bottles annually in the country as of 2019.
Rising Adoption of Eco-Friendly Branding Strategies
Food manufacturers used biodegradable packaging to strengthen brand image and meet corporate sustainability goals. Companies redesign packs with minimalist fiber materials, natural colors, and clear environmental claims. This trend offered opportunities for premium positioning, especially in organic, clean-label, and health-focused categories. Retailers promoted eco-friendly packaging as part of loyalty programs and private-label upgrades, increasing visibility for biodegradable formats across large retail chains.
Key Challenges
Limited Industrial Composting and Waste Processing Infrastructure
Many regions lacked adequate composting facilities that can handle biodegradable materials at large scale. This gap restricted proper end-of-life processing and reduced the environmental benefit of compostable formats. Some bioplastics require controlled conditions that municipal systems cannot yet support. As a result, packaging often ends up in landfills, limiting adoption among food producers who face stricter sustainability auditing. The slow pace of infrastructure expansion remained a major challenge for the market.
Higher Production Costs Compared to Conventional Plastics
Biodegradable packaging materials often cost more due to expensive feedstocks, complex processing, and lower economies of scale. These higher costs created barriers for small food businesses and price-sensitive markets. Fluctuations in agricultural raw materials also affected pricing stability for fiber-based and bioplastic grades. Manufacturers struggled to balance premium inputs with competitive pricing, especially in mass-market food categories. This challenge slowed faster substitution of traditional plastics in several regions.
Regional Analysis
North America
North America held about 34% share in 2024, driven by strong adoption of eco-friendly materials across packaged foods, beverages, and foodservice chains. Brands invested in compostable trays, fiber cartons, and bio-based films due to strict state-level plastic bans. Large retailers expanded private-label sustainable packaging programs, while quick-service restaurants shifted to biodegradable cups and clamshells. Growth in online grocery and meal-kit services increased demand for recyclable and compostable formats. Strong consumer preference for low-waste packaging and expansion of municipal composting facilities helped the region maintain its leading position.
Europe
Europe accounted for nearly 31% share in 2024, supported by advanced recycling frameworks and strict regulations targeting plastic reduction. Food manufacturers transitioned rapidly to biodegradable cartons, molded fiber products, and certified compostable films under extended producer responsibility rules. High adoption of sustainable labels encouraged retailers to expand fiber-based formats across fresh produce and bakery categories. Investment in circular systems and industrial composting enhanced material recovery, while regional sustainability goals accelerated innovation. The region’s strong regulatory push and consumer awareness kept Europe a major contributor to global biodegradable packaging growth.
Asia Pacific
Asia Pacific captured about 26% share in 2024, fueled by rising food delivery volumes, large urban populations, and increasing restrictions on single-use plastics across major economies. Restaurants and street-food operators adopted biodegradable containers, bowls, and cutlery to align with city-level waste rules. Expanding supermarket chains used fiber-based packaging to reduce plastic waste in fresh produce. Growth in e-commerce grocery and ready-meal categories increased demand for compostable films and paper-based pouches. Rapid industrialization and government-backed sustainability programs strengthened market penetration across emerging markets, making Asia Pacific one of the fastest-growing regions.
Latin America
Latin America held close to 6% share in 2024, supported by early-stage adoption of biodegradable cartons, bags, and molded fiber trays in foodservice and retail channels. Countries introduced plastic bag bans and producer responsibility rules that encouraged fiber and bagasse usage. Local food brands used compostable materials to differentiate in competitive categories such as snacks, bakery, and beverages. Growth in organic and natural food products also boosted demand for sustainable packaging solutions. Infrastructure gaps in composting limited wider uptake, yet regulatory momentum and rising consumer awareness sustained steady expansion.
Middle East and Africa
Middle East and Africa accounted for nearly 3% share in 2024, driven by gradual policy shifts toward reducing plastic waste in urban centers. Food manufacturers explored biodegradable films and fiber-based trays to meet emerging sustainability requirements from retailers and hospitality groups. Growing quick-service restaurant networks increased demand for compostable cups and takeout packs. Adoption remained moderate due to limited waste-processing capacity, yet pilot composting projects and rising consumer interest in eco-friendly packaging supported early market growth. International brands operating in the region accelerated the shift toward biodegradable materials through regional sourcing partnerships.
Market Segmentations:
By Material
- Paper & Paperboard
- Bio-plastic
- Bagasse
By Product
- Bottles & Jars
- Boxes & Cartons
- Cans
- Trays & Clamshells
- Cups & Bowls
- Pouches & Bags
- Films & Wraps
- Labels & Tapes
- Others
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The biodegradable food packaging market is shaped by major players such as Tetra Pak, Smurfit Westrock, Greenhope, Mondi, Notpla Limited, DS Smith, Amcor plc, Stora Enso, Elevate Packaging, and Sonoco Products Company. These companies expand bio-based portfolios by investing in molded fiber technology, compostable coatings, and recyclable paper-based formats to meet rising regulatory and consumer sustainability demands. Manufacturers focus on high-barrier solutions that support dairy, beverages, ready meals, and fresh produce without relying on traditional plastics. Many groups strengthen competitiveness through partnerships with foodservice chains aiming to reduce plastic waste and adopt circular materials. Production facilities increasingly use renewable feedstocks, lightweight designs, and water-based dispersion barriers to improve environmental performance. Several firms collaborate with recyclers and composting operators to ensure better end-of-life processing and compliance with global waste policies. Continuous innovation in plant-based films, pulp-based containers, and renewable fiber solutions supports wider adoption across retail, e-commerce, and quick-service channels.
Key Player Analysis
- Tetra Pak
- Smurfit Westrock
- Greenhope
- Mondi
- Notpla Limited
- DS Smith
- Amcor plc
- Stora Enso
- Elevate Packaging
- Sonoco Products Company
Recent Developments
- In April 2025, Stora Enso launched Performa Nova, a high-yield folding boxboard designed for renewable, recyclable, and efficient food packaging including dry, frozen, and chilled foods.
- In 2024, Smurfit Kappa and WestRock combined to form Smurfit Westrock, a global leader in sustainable paper-based packaging.
- In 2023, Mondi and Veetee launched the first dry rice pack made from recyclable functional barrier paper, replacing plastic packaging.
Report Coverage
The research report offers an in-depth analysis based on Material, Product and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will expand as more countries tighten rules on single-use plastics.
- Demand will rise with food brands adopting fiber-based and compostable packaging for sustainability goals.
- Bioplastic production capacity will increase as manufacturers invest in advanced PHA and PLA technologies.
- Quick-service restaurants and delivery platforms will accelerate the shift toward biodegradable takeaway solutions.
- Retailers will boost private-label products using eco-friendly packaging to strengthen brand reputation.
- Improvements in composting infrastructure will enhance recovery rates for biodegradable materials.
- Innovation in high-barrier compostable films will unlock new applications in frozen and ready-to-eat foods.
- Growth in organic and health-focused foods will support wider use of biodegradable formats.
- Circular packaging systems will expand as cities adopt composting and collection programs.
- Emerging markets will see faster adoption due to rising environmental awareness and regulatory reforms.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Global Restrictions on Single-Use Plastics
Governments worldwide are implementing bans and levies on single-use plastics, compelling food brands and retailers to switch to biodegradable packaging alternatives. These regulatory measures are accelerating the adoption of compostable and fiber-based packaging across retail, foodservice, and delivery sectors.
Growing Demand for Sustainable and Safe Food Packaging
Consumers are increasingly seeking packaging made from natural, compostable, or plant-based materials due to heightened environmental and health awareness. This trend is driving food brands to reformulate packaging to reduce chemical migration risks and improve end-of-life disposal, boosting the uptake of biodegradable trays, bowls, and wraps.
Expansion of Quick-Service Restaurants and Online Food Delivery
The rapid growth of quick-service restaurants and app-based food delivery platforms is increasing the need for biodegradable containers, cartons, cups, and bags. Food chains and delivery services are adopting fiber-based and compostable formats to meet rising takeaway volumes and reduce their environmental footprint.
Advancements in Compostable and Bio-Based Materials
Ongoing innovation in high-barrier compostable films, heat-resistant biopolymers, and improved molded fiber designs is enabling biodegradable packaging to replace synthetic plastics in a wider range of food applications. These advancements are opening new market opportunities by addressing durability and moisture resistance concerns.
Growth of Circular Packaging and Closed-Loop Systems
Retailers and foodservice operators are increasingly investing in packaging that fits into composting, recycling, or hybrid recovery systems. The expansion of organics collection, take-back programs, and municipal composting facilities is supporting the adoption of biodegradable packaging aligned with circular economy goals.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Biodegradable Food Packaging Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Biodegradable Food Packaging Market projected to grow between 2025 and 2032?
What are the critical drivers for the growth of the Biodegradable Food Packaging market?
Who are the leading companies in the Biodegradable Food Packaging Market?
Which region commanded the largest share of the Biodegradable Food Packaging Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Product
- 1.2.1 Bottles & Jars
- 1.2.2 Boxes & Cartons
- 1.2.3 Cans
- 1.2.4 Trays & Clamshells
- 1.2.5 Cups & Bowls
- 1.2.6 Pouches & Bags
- 1.2.7 Films & Wraps
- 1.2.8 Labels & Tapes
- 1.2.9 Others
- 1.3 By Material
- 1.3.1 Paper & Paperboard
- 1.3.2 Bio-plastic
- 1.3.3 Bagasse
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 226.08 Billion → 2032: USD 344.34 Billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Biodegradable Food Packaging Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Biodegradable Food Packaging Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Biodegradable Food Packaging Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Biodegradable Food Packaging Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Biodegradable Food Packaging Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Biodegradable Food Packaging Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Biodegradable Food Packaging Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Biodegradable Food Packaging Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 226.08 Billion → 2032: USD 344.34 Billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Biodegradable Food Packaging Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Product - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Bottles & Jars
- 12.3.7.2 Boxes & Cartons
- 12.3.7.3 Cans
- 12.3.7.4 Trays & Clamshells
- 12.3.7.5 Cups & Bowls
- 12.3.7.6 Pouches & Bags
- 12.3.7.7 Films & Wraps
- 12.3.7.8 Labels & Tapes
- 12.3.7.9 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Material - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Paper & Paperboard
- 12.4.7.2 Bio-plastic
- 12.4.7.3 Bagasse
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global Biodegradable Food Packaging Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Biodegradable Food Packaging Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Biodegradable Food Packaging Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Tetra Pak
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Smurfit Westrock
- 17.4 Greenhope
- 17.5 Mondi
- 17.6 Notpla Limited
- 17.7 DS Smith
- 17.8 Amcor plc
- 17.9 Stora Enso
- 17.10 Elevate Packaging
- 17.11 Sonoco Products Company
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

