
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
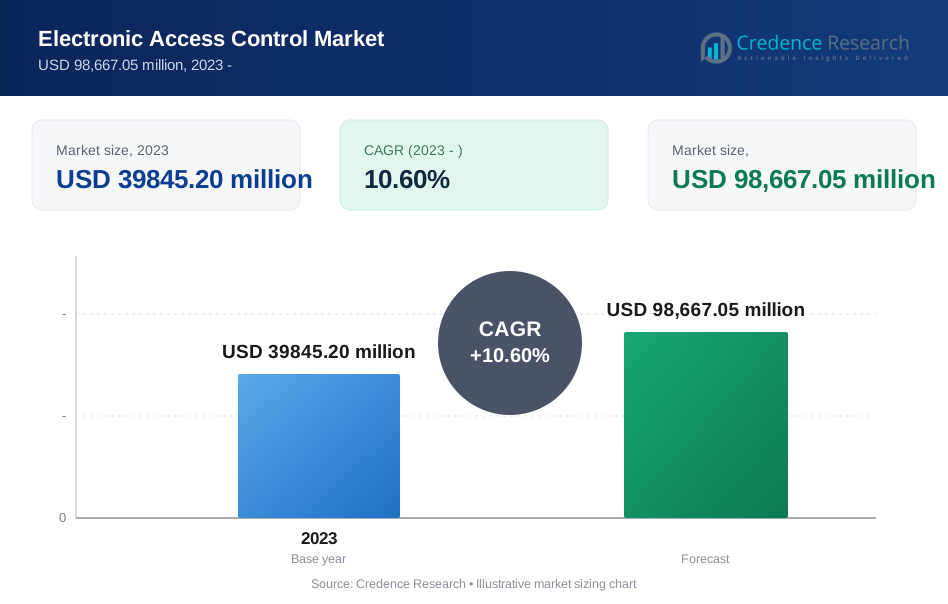
| Electronic Access Control Market Size 2023 | USD 39845.20 million |
| Electronic Access Control Market, CAGR | 10.60% |
| Electronic Access Control Market Size 2032 | USD 98667.05 million |
Market Insights
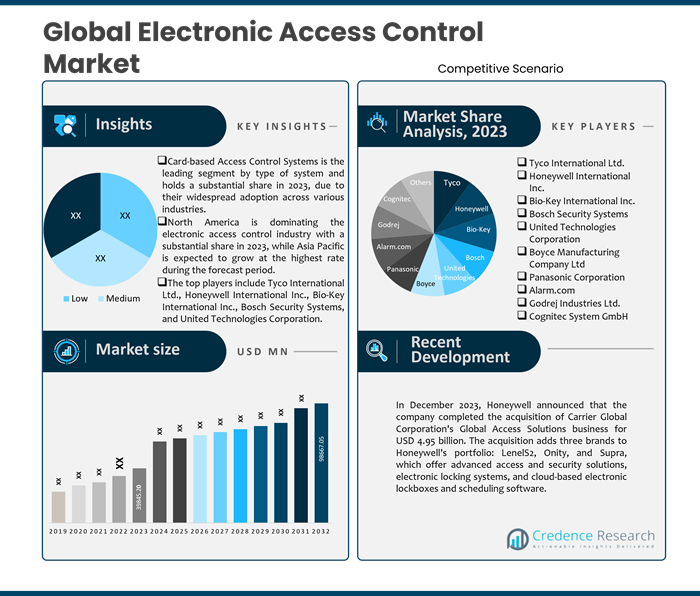
- The global demand for electronic access control systems was valued at USD 39845.20 million in 2023 and is expected to reach USD 98667.05 million in 2032, growing at a CAGR of 10.60% between 2024 and 2032.
- The card-based access control systems segment was the market leader by type of system, accounting for the highest share in value in 2023, and the cloud-based access control systems segment is expected to grow rapidly throughout the forecast period.
- The healthcare facilities segment is predicted to grow fastest over the projection period, while commercial and industrial buildings had the largest share by application in 2023.
- Over the projection period, the healthcare providers segment is expected to expand at the fastest rate, and the large enterprises and corporations segment dominated the market share by end-user in 2023.
- North America is dominating the electronic access control industry, with over one-third of the market in 2023.
- The market's primary possibilities include integration with emerging technologies such as cloud-based systems and the Internet of Things (IoT) to deliver enhanced security and access control solutions.
Executive Summary
Market Definition
Electronic Access Control Systems (EACS) are security systems that use electronic methods, such as key cards, biometric scans, or PIN codes, to grant or restrict access to a building or specific areas within a facility. These systems enhance security by ensuring that only authorized individuals can enter secure zones.
EACS works by requiring users to present their credentials, such as a card, fingerprint, or code, which the system verifies against a database of authorized users. Upon successful verification, the system unlocks the door or grants access, logging the event for security monitoring. EACS offers enhanced security, streamlined access management, and detailed audit trails for monitoring and reporting access events.
Market Overview
The global electronic access control market has witnessed steady growth in recent years and is expected to grow at a CAGR of 10.60% between 2024 and 2032. The market was valued at USD 39845.20 million in 2023 and is expected to reach USD 98667.05 million in 2032.
The electronic access control market is driven by the increasing security threats that have amplified the demand for sophisticated access control solutions. The rise in criminal activities, such as unauthorized entries, data breaches, and terrorism, has necessitated the adoption of more robust security measures. Organizations are increasingly recognizing the need to protect their physical and digital assets, driving the deployment of comprehensive EAC systems. These systems also integrate seamlessly with existing security frameworks, offering a multi-layered defense mechanism.
Moreover, governments and regulatory bodies worldwide are imposing stringent security regulations and standards across various industries. Compliance with these regulations often requires the implementation of advanced access control systems. For instance, the Health Insurance Portability and Accountability Act (HIPAA) in the healthcare sector mandates strict access controls to protect patient data. Similarly, financial institutions must adhere to regulations such as the Sarbanes-Oxley Act, which necessitates the use of secure access control systems to safeguard sensitive financial information.
Additionally, the growing trend towards smart buildings and smart cities is contributing to the expansion of the EAC market. As urbanization accelerates, there is a rising demand for integrated security solutions that can manage and monitor access across multiple entry points in real time. Smart EAC systems, equipped with networked surveillance and automation capabilities, are increasingly being adopted in residential complexes, commercial buildings, and public infrastructure projects. These systems also offer convenience and efficiency, making them an attractive proposition for modern urban developments.
Furthermore, the increasing adoption of cloud-based solutions is transforming the EAC landscape. Cloud-based access control systems offer several advantages, including scalability, remote access, and cost-effectiveness. They allow organizations to manage access control across multiple locations from a centralized platform, reducing the need for extensive on-site infrastructure and maintenance. The flexibility and affordability of cloud-based EAC solutions are particularly appealing to small and medium-sized enterprises (SMEs), further driving market growth.
Segmentation by Type of System
- Card-based access control systems are the leading segment by type of system and held the dominant share in value in 2023. This dominance is primarily due to their widespread adoption across various industries, including commercial, governmental, and residential sectors. Card-based systems are cost-effective, easy to use, and integrate seamlessly with existing infrastructure, making them a popular choice for many organizations. They provide a reliable method of controlling access to secure areas and are widely accepted as a standard security measure.
- The cloud-based access control systems segment is expected to exhibit the highest CAGR during the forecast period due to several key factors. They offer greater scalability and flexibility, making them highly attractive for businesses aiming to expand or modify their security systems without significant additional infrastructure costs. The ability to manage access control systems remotely is a major advantage, particularly in an environment where remote work and decentralized offices are becoming more prevalent. Additionally, cloud-based solutions often require lower upfront investment compared to traditional on-premises systems, reducing the financial barrier to adoption.
- Other segments, such as biometric access control systems, keypad/pin-based access control systems, multi-factor authentication systems, and wireless access control systems, are anticipated to grow moderately compared to the cloud-based access control systems segment during the forecasted period.
Segmentation by Application
- The commercial and industrial buildings held the largest market share by application in terms of value in 2023 due to the extensive use of electronic access control systems in offices, factories, warehouses, and other commercial properties. These buildings require robust security measures to protect assets, ensure employee safety, and comply with regulations, leading to the widespread adoption of access control systems .
- The healthcare facilities segment is expected to be the fastest-growing segment during the forecasted period. The increasing need for stringent security measures to protect sensitive patient data and high-value medical equipment drives the demand for advanced access control systems. Regulatory compliance, such as HIPAA in the US, mandates strict access control measures, further accelerating adoption. Additionally, the COVID-19 pandemic has heightened the need for contactless and hygienic access control solutions, prompting healthcare facilities to adopt advanced systems rapidly.
- Government and defense, education institutions, residential buildings, and transportation and logistics segments are projected to grow at a moderate CAGR and hold a lower share than the commercial and industrial buildings segment.
Segmentation by End-User
- The large enterprises and corporations segment held the largest market share in terms of value in 2023 due to their substantial investments in comprehensive security infrastructure needed to protect sensitive data, intellectual property, and physical assets across multiple facilities. These organizations require advanced and reliable access control systems to manage high employee counts and complex security needs .
- The healthcare providers segment is anticipated to be the fastest-growing segment in terms of end-users. This growth is driven by the sector's increasing security requirements to safeguard patient data and medical equipment, compliance with stringent regulations such as HIPAA, and the heightened demand for contactless and hygienic access control solutions. Additionally, technological advancements in biometric and cloud-based access control systems are rapidly being adopted in healthcare facilities to enhance security and operational efficiency.
- Other end-user segments, such as small and medium-sized enterprises (SMEs), government and public sector, educational institutions, and transportation and logistics Companies, are anticipated to contribute significantly to the market's growth during the forecasted period.
Segmentation by Region
- North America dominated the electronic access control industry in 2023, fueled by the rapid adoption of cutting-edge technologies such as biometric systems, artificial intelligence (AI), and the Internet of Things (IoT) alongside increasing prevalence of security threats, including cyber-attacks, physical breaches, and terrorism.
- Asia Pacific is expected to experience significant growth during the forecasted period, driven by rapid urbanization, smart city initiatives, and the presence of regional market players launching numerous innovative products in the region.
- The rest of the world, including Latin America, the Middle East, and Africa, supplies the remaining demand for retail inventory management software.
North America holds the dominant share of the electronic access control market and is expected to maintain its dominance during the forecast period. This dominance is attributed to the rapid adoption of cutting-edge technologies such as biometric systems, artificial intelligence (AI), and the Internet of Things (IoT). North America, being a hub for technological innovation, has seen widespread implementation of these advanced systems across various sectors. These technologies provide enhanced security features, such as facial recognition, fingerprint scanning, and real-time data analytics, which are crucial for modern access control solutions. For instance, in April 2024, U.S. Customs and Border Protection (CBP) successfully integrated facial biometrics into the entry procedures at all international airports through its Simplified Arrival program and extended the technology to the exit processes at 49 airport locations. Additionally, CBP expanded the use of facial biometrics to 39 seaports and all pedestrian lanes at ports of entry along both the Southwest and Northern Borders.
Moreover, the increasing prevalence of security threats, including cyber-attacks, physical breaches, and terrorism, has significantly heightened awareness and concern among organizations. This growing threat has compelled companies to invest heavily in robust security measures. For instance, in August 2023, a hacktivist group stole files from the US Army Aviation and Missile Command and purportedly sold access to a USD 75 billion aerospace and defense company. The compromised data includes a substantial amount of code, encompassing source software taken from the defense company's CI/CD pipeline, Bitbucket, GitHub, and Apache SVN repositories. Such high-profile breaches highlight the vulnerabilities within existing security frameworks and drive demand for more advanced and reliable EAC solutions in the region.
On the other hand, the Asia Pacific region is anticipated to be the fastest-growing market for electronic access control during the forecast period. This rapid growth is fueled by the region's ongoing urbanization and rapidly expanding cities that require efficient management of their infrastructure.
As urban populations grow across countries such as China, India, and Southeast Asia, the demand for security solutions to safeguard residential, commercial, and government facilities increases. According to the United Nations, Asia's urban population is expected to reach a 50% increase by 2050. Electronic access control systems address this need by offering advanced capabilities such as biometric authentication, remote management, and seamless integration with smart city initiatives. Furthermore, government initiatives promoting urban development and infrastructure modernization further fuel the growth of the market.
In addition, the presence of regional market players such as Hikvision and Dahua Technology, which are investing heavily in R&D and launching numerous products in the region, further driving the growth of the market. For instance, in May 2024, Hikvision debuted its next-generation network video recording technology, enhancing the capabilities of its electronic access control solutions by integrating AI-powered features for improved security and efficiency.
Key Highlights of the Report
The global Electronic Access Control Market is segmented by type of system, application, end-user, and region. The Card-Based Access Control Systems dominated the market in 2023, holding the largest value share. However, healthcare facilities are expected to see the fastest growth, and large enterprises and corporations remain the primary end-user, with North America leading the market share.
The electronic access control market is driven by growing smart city initiatives that adopt advanced technologies to secure public spaces and critical infrastructure effectively. This demand is further fuelled by stringent regulatory frameworks mandating compliance with security and data protection standards. Additionally, the market is propelled by the increasing adoption of mobile access technologies, catering to the growing preference for convenient and secure access solutions.
Nonetheless, while North America led growth in the electronic access control industry in 2023, driven by the rapid adoption of cutting-edge technologies and the increasing prevalence of security threats, while Asia Pacific is poised to have the highest forecasted growth, driven by rapid urbanization, initiatives advancing smart cities, and the introduction of numerous innovative products by regional market players.
What Are The Main Drivers Of The Global Electronic Access Control Market?
Smart city initiatives are driving growth in the global electronic access control market as urbanization intensifies and municipalities seek to optimize security and efficiency. These initiatives mandate advanced access control solutions to secure public spaces and critical infrastructure effectively. Additionally, stringent regulatory frameworks surrounding security and data protection further stimulate demand for compliant electronic access control systems. Furthermore, the increasing adoption of mobile devices and the preference for contactless solutions are accelerating the integration of mobile access technologies into electronic access control, catering to the convenience and security needs of modern users.
What are The Major Challenges Faced By The Global Electronic Access Control Market?
The global electronic access control market faces several major challenges that impact its growth and development. One significant challenge is the high cost of advanced electronic access control systems, which can be prohibitive for small and medium-sized enterprises (SMEs) and developing regions. Additionally, the integration of these systems with existing security infrastructure and IT networks can be complex and require significant technical expertise. Additionally, the market is challenged by varying standards and regulations across different regions, which complicate the implementation and interoperability of electronic access control solutions globally.
What Are The Growth Opportunities In The Global Electronic Access Control Market?
The global electronic access control market presents several growth opportunities driven by advancements, such as the integration of Internet of Things (IoT) technology with access control systems. IoT-enabled devices provide real-time monitoring and management of access points, enhance data collection, and improve the overall security infrastructure.
Market Drivers
Growing Urbanization and Smart City Initiatives
Growing urbanization and smart city initiatives are the major drivers for the global electronic access control market due to the increasing need for enhanced security and efficient resource management in densely populated urban areas. As cities expand and more people move into urban environments, increasing the demand for advanced security measures to protect residential, commercial, and public spaces. Smart city projects leverage technology to improve the safety, sustainability, and efficiency of urban living by incorporating electronic access control systems.
These systems ensure that only authorized individuals can access buildings and critical infrastructure and integrate with other smart technologies, such as traffic management and public surveillance systems, to create a cohesive and intelligent urban security framework. Additionally, the push towards smarter, more secure cities significantly boosts the adoption and innovation of electronic access control solutions, in turn driving the market's growth.
Market Restraints
High Cost of Advanced Electronic Access Control Systems
The high cost of advanced electronic access control systems presents a significant challenge for small and medium-sized enterprises (SMEs) and organizations in developing regions. These systems incorporate advanced technologies such as biometric authentication and advanced encryption and integrate cloud-based platforms that require substantial financial investment. The initial costs include the purchase of sophisticated hardware such as biometric scanners, high-resolution cameras, and secure access readers. Additionally, there are costs associated with software licenses, installation, and integration with existing IT infrastructure.
Additionally, regular maintenance, software updates, and potential costs for technical support and training staff to use and manage the systems effectively further restrain the adoption of these systems. For SMEs and organizations with limited budgets, these costs can be prohibitive, making it challenging to adopt the latest electronic access control technologies. In developing regions, the economic constraints can be even more pronounced, limiting the adoption of these advanced security solutions despite the growing need for enhanced security measures.
Opportunities
Integration of Internet of Things (IoT) technology
The integration of the Internet of Things (IoT) into electronic access control systems is anticipated to create ample opportunities for the market in the coming years. IoT-enabled devices, such as smart locks, sensors, and access readers, provide real-time monitoring and control of access points, allowing for immediate responses to security breaches and anomalies.
These devices generate vast amounts of data that can be analyzed to identify patterns, enhance security protocols, and optimize resource allocation. The connectivity offered by IoT allows for remote management and integration with other building management systems, creating a cohesive and intelligent security infrastructure. This integration improves operational efficiency and security and enhances user convenience by enabling seamless access through smartphones and other connected devices.
Competitive Landscape
Key Players
The global electronic access control market is highly competitive, with several key players. Some of the major players in the market:
- Tyco International Ltd.
- Honeywell International Inc.
- Bio-Key International Inc.
- Bosch Security Systems
- United Technologies Corporation
- Boyce Manufacturing Company Ltd
- Panasonic Corporation
- Alarm.com
- Godrej Industries Ltd.
- Cognitec System GmbH
These organizations prioritize product innovation, distribution channel expansion, collaborations, and mergers & acquisitions to stay competitive.
The key players in the global electronic access control market continually seek to stay ahead by launching new products and making acquisitions.
In December 2023, Honeywell annouched that the company completed the acquisition of Carrier Global Corporation's Global Access Solutions business for USD 4.95 billion. The acquisition adds three brands to Honeywell's portfolio: LenelS2, Onity, and Supra, which offer advanced access and security solutions, electronic locking systems, and cloud-based electronic lockboxes and scheduling software.
In August 2022, BIO-key International, Inc. launched a new mobile authenticator solution that combines server-secured and on-device multi-biometric authentication methods. The mobile authenticator offers a convenient password less login to applications and websites, utilizing the power of biometrics to protect against unauthorized access. It features server-secured biometric authentication, where biometric templates are securely stored and matched on BIO-key's servers, as well as on-device multi-biometric authentication options such as fingerprint, face, voice, and palm.
How are Companies Performing in the Electronic Access Control Market?
The global electronic access control market is highly competitive, with several key players.
Several startups in the electronic access control industry are developing innovative solutions to enhance security and convenience. Cloud-based access control systems are becoming increasingly popular, offering advantages such as ease of deployment and management, real-time data across multiple sites, and improved security protocols.
For instance, OLOID, a US-based startup, offers a cloud-based SaaS platform for managing workplace identity and access. It offers a high level of security and convenience for modern workplaces of all sizes. OLOID integrates seamlessly with different types of physical access control systems, such as key cards, biometrics, multi-factor authentication, and mobile-based access systems. Moreover, startups such as Swiftlane provide an all-in-one access control system that includes touchless face recognition access, reliable mobile unlock, voice unlock, and cloud-based remote management.
Summary of Key Findings
- The electronic access control market is driven by the integration of advanced technologies in smart city initiatives to enhance security in public spaces and critical infrastructure, supported by stringent regulatory standards. Additionally, the increasing adoption of mobile access technologies responds to the growing demand for convenient and secure access solutions.
- Market segmented by type of system, application, end-user, and region.
- Card-based access control systems are the most popular, with large enterprises and corporations remaining the primary end-user segment.
- North America is leading market growth; the market is highly competitive, with key players including Tyco International Ltd., Honeywell International Inc., Bio-Key International Inc., Bosch Security Systems, United Technologies Corporation, Boyce Manufacturing Company Ltd, Panasonic Corporation, Alarm.com, Godrej Industries Ltd., and Cognitec System GmbH.
Future Outlook
- Positive outlook for the global electronic access control market with significant growth potential in the Asia Pacific region.
- The electronic access control market is driven by the integration of advanced technologies in smart city initiatives to enhance security in public spaces and critical infrastructure, bolstered by stringent regulatory standards and increasing adoption of mobile access technologies.
- During the forecast period, the high initial cost and complex integration with existing infrastructure are expected to restrain the market growth.
- Key firms must focus on product innovation, growing market reach, and maintaining competitive pricing to keep ahead of the competition.
How CXOs Can Benefit from the Credence Research Electronic Access Control Market Report
The Credence Research Electronic Access Control Market Report provides CXOs with a comprehensive overview of the market, including:
- Market size and growth forecast: The report provides detailed estimates of the global electronic access control market size, segmented by type of system, application, end-user, and region. It also includes forecasts for the market through 2032 based on key trends and drivers.
- Market segmentation: The report segments the electronic access control market by type of system, application, end-user, and region. This segmentation provides CXOs with a granular understanding of the market and the opportunities in each segment.
- Competitive Landscape: The report profiles the key players in the electronic access control market and provides insights into their strategies, product offerings, and financial performance. This information can help CXOs to identify and assess their competition.
- Key trends and drivers: The report identifies and analyzes the key trends and drivers shaping the electronic access control market. This information can help CXOs make informed decisions about their investments and strategies.
CXOs can use the insights from the Credence Research Electronic Access Control Market Report to:
- Identify growth opportunities: The report can help CXOs identify new growth opportunities in the electronic access control market. For example, it identifies the growing demand for electronic access control in the healthcare industry, driven by stricter compliance with patient data privacy regulations and enhanced security for controlled substances and medications.
- Make informed investment decisions: The report can help CXOs make informed investment decisions about electronic access control systems. For example, it provides insights into the key factors to consider when evaluating electronic access control system providers.
- Develop competitive strategies: The report can help CXOs develop competitive strategies for their electronic access control businesses. For example, it identifies the key strategies that electronic access control system providers are using to differentiate themselves from their competitors.
- Track market developments: The report can help CXOs monitor market developments and stay ahead of the curve. For example, it provides insights into the latest trends and innovations in the electronic access control market.
Overall, the Credence Research Electronic Access Control Market Report is a valuable resource for CXOs who are looking to gain a deeper understanding of the market and identify opportunities for growth.
Segmentation
-
By Type of System
- Card-based Access Control Systems
- Biometric Access Control Systems
- Keypad/PIN-based Access Control Systems
- Multi-factor Authentication Systems
- Wireless Access Control Systems
- cloud-based access control systems
-
By Application
- Commercial and Industrial Buildings
- Government and Defense
- Healthcare Facilities
- Education Institutions
- Residential Buildings
- Transportation and Logistics
-
By End-User
- large enterprises and corporations
- Small and Medium-sized Enterprises (SMEs)
- Government and Public Sector
- Healthcare Providers
- Educational Institutions
- Transportation and Logistics Companies
-
By Region
- North America
- US
- Canada
- Mexico
- Europe
- Germany
- France
- UK.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
- North America
Adjacent Markets
In the electronic access control market, several adjacent markets have high revenue growth opportunities. The key adjacent markets for electronic access control are-
Adjacent Markets |
||
| Video Surveillance Systems Market | Intrusion Detection and Alarm Systems Market | Visitor Management Systems Market |
| Physical Security Information Management (PSIM) Systems Market | Building Management Systems (BMS) Market | Logical Access Control Systems Market |
| Identity and Access | Biometric | Internet of Things |
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Smart City Initiatives and Urbanization
Rapid urbanization and the proliferation of smart city projects are driving the adoption of electronic access control systems to secure public spaces, critical infrastructure, and high-density residential and commercial developments.
Stringent Regulatory Compliance
Increasingly strict regulations in sectors such as healthcare (e.g., HIPAA) and finance (e.g., Sarbanes-Oxley Act) require organizations to implement advanced access control systems to protect sensitive data and ensure compliance.
Integration with Emerging Technologies
The integration of electronic access control with cloud platforms, IoT devices, and AI-powered analytics enhances security, enables remote management, and provides real-time monitoring, making these systems more attractive to enterprises.
Rising Security Threats and Demand for Contactless Solutions
Growing concerns over unauthorized access, data breaches, and physical security threats, along with heightened demand for contactless and hygienic access solutions post-pandemic, are accelerating the deployment of advanced electronic access control systems.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the global electronic access control market?
What is the expected growth rate of the electronic access control market between 2024 and 2032?
Which segment is leading the market share in terms of type of system?
Which application governs the demand for electronic access control globally?
Which end-user is expected to post the highest CAGR during the forecast period?
Which region is fueling the growth of the electronic access control industry?
Who are the major players in the global electronic access control market?
What are the major market drivers of the electronic access control industry?
What are the major market restraints of the electronic access control industry?
What are the major market opportunities of the electronic access control industry?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End-User
- 1.2.1 Large Enterprises and Corporations
- 1.2.2 Small and Medium-sized Enterprises (SMEs)
- 1.2.3 Government and Public Sector
- 1.2.4 Healthcare Providers
- 1.2.5 Educational Institutions
- 1.2.6 Transportation and Logistics Companies
- 1.3 By Application
- 1.3.1 Commercial and Industrial Buildings
- 1.3.2 Government and Defense
- 1.3.3 Healthcare Facilities
- 1.3.4 Education Institutions
- 1.3.5 Residential Buildings
- 1.3.6 Transportation and Logistics
- 1.4 By Type of System
- 1.4.1 Card-based Access Control Systems
- 1.4.2 Biometric Access Control Systems
- 1.4.3 Keypad/PIN-based Access Control Systems
- 1.4.4 Multi-factor Authentication Systems
- 1.4.5 Wireless Access Control Systems
- 1.4.6 Cloud-based Access Control Systems
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2023: USD 39845.20 million → 2032: USD 98,667.05 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2023
- 2.6.2 Forecast Period: 2023-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2023
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Electronic Access Control Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Electronic Access Control Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2023-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2023-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Electronic Access Control Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2023-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Electronic Access Control Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Electronic Access Control Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Electronic Access Control Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 Global Electronic Access Control Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Electronic Access Control Market Outlook, 2023-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2023: USD 39845.20 million → 2032: USD 98,667.05 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2023
- 11.2 Market Forecast, 2023-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Electronic Access Control Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2023
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End-User - Market Size and Forecast, 2023-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2023-2032
- 12.3.4 Volume Forecast, 2023-2032
- 12.3.5 Base-Year Market Share, 2023
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Large Enterprises and Corporations
- 12.3.7.2 Small and Medium-sized Enterprises (SMEs)
- 12.3.7.3 Government and Public Sector
- 12.3.7.4 Healthcare Providers
- 12.3.7.5 Educational Institutions
- 12.3.7.6 Transportation and Logistics Companies
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2023-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2023-2032
- 12.4.4 Volume Forecast, 2023-2032
- 12.4.5 Base-Year Market Share, 2023
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Commercial and Industrial Buildings
- 12.4.7.2 Government and Defense
- 12.4.7.3 Healthcare Facilities
- 12.4.7.4 Education Institutions
- 12.4.7.5 Residential Buildings
- 12.4.7.6 Transportation and Logistics
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Type of System - Market Size and Forecast, 2023-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2023-2032
- 12.5.4 Volume Forecast, 2023-2032
- 12.5.5 Base-Year Market Share, 2023
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Card-based Access Control Systems
- 12.5.7.2 Biometric Access Control Systems
- 12.5.7.3 Keypad/PIN-based Access Control Systems
- 12.5.7.4 Multi-factor Authentication Systems
- 12.5.7.5 Wireless Access Control Systems
- 12.5.7.6 Cloud-based Access Control Systems
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Electronic Access Control End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Electronic Access Control Geographic Market Outlook, 2023-2032
- 14.1 Regional Market Size and Share, 2023
- 14.2 Regional Market Forecast, 2023-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Electronic Access Control Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2023-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Electronic Access Control Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2023
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2023-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Honeywell International Inc.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Tyco International Ltd.
- 18.4 Bosch Security Systems
- 18.5 Bio-Key International Inc.
- 18.6 United Technologies Corporation
- 18.7 Panasonic Corporation
- 18.8 Alarm.com
- 18.9 Godrej Industries Ltd.
- 18.10 Cognitec System GmbH
- 18.11 Hikvision
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

