
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
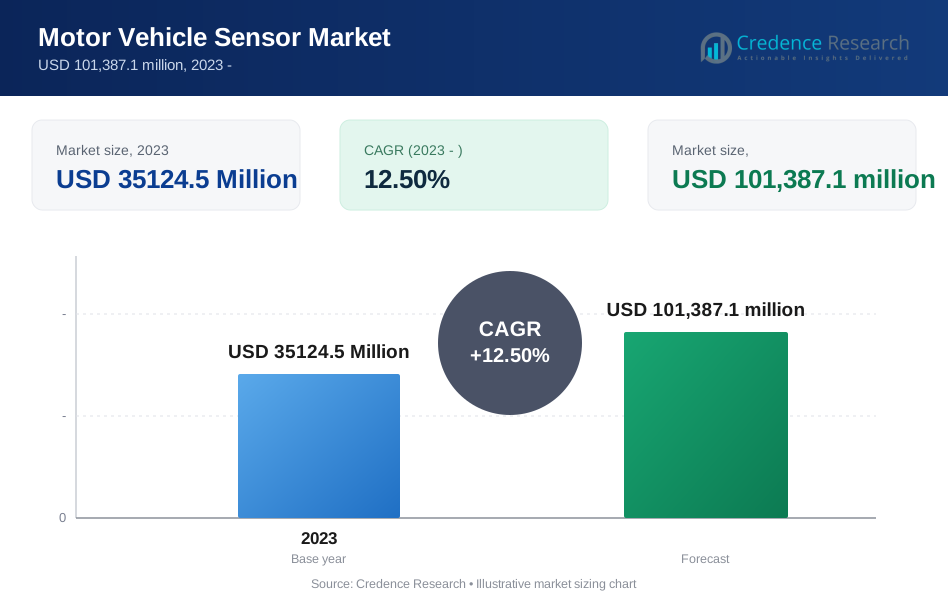
| Saline Laxatives Market Size 2023 | USD 35124.5 Million |
| Saline Laxatives Market, CAGR | 12.50% |
| Saline Laxatives Market Size 2032 | USD 101387.1 Million |
Market Insights
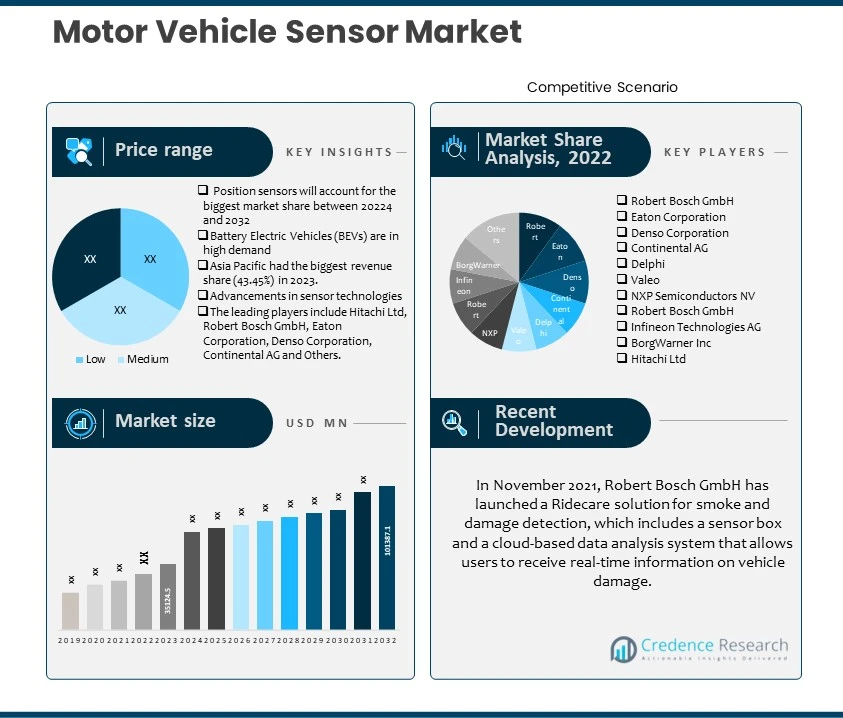
- The global demand for Motor Vehicle Sensors was valued at USD 35124.5 million in 2023 and is expected to reach USD 101387.1 million in 2032, growing at a CAGR of 12.50% between 2024 and 2032.
- Position sensors will account for the largest market share between 2024 and 2032, while the Pressure Sensors category is predicted to rise at a significant CAGR of 10.1% throughout the forecast period.
- The most popular category in the motor vehicle sensor market is passenger vehicles.
- The powertrain systems category dominated the automotive sensor market during the forecast period, while the chassis segment is expected to rise at a significant CAGR of 10.0% throughout the projection period.
- The MEMS (Micro-Electro-Mechanical Systems) division owns the bulk of the shares.
- The original equipment manufacturer (OEM) category will increase the most throughout the projection period, and aftermarket is another major vehicle type in the Motor Vehicle Sensor Market.
- Battery Electric Vehicles (BEVs) are in great demand, and hybrid electric vehicles (HEVs) are the fastest-growing segment of the motor vehicle sensor market.
- Level 2 (Partial Automation) is the fastest expanding sector in the motor sensor industry, followed by Level 4 (High Automation).
- Wired sensors are a significant segment of the motor sensor market.
- In 2023, Asia Pacific had the largest revenue share (43.45%), with North America ranking second.
- Improvements in the sensor sales channel to meet client needs boost market growth.
- The high cost of LiDAR automotive sensors limits industry growth.
Executive Summary
Market Definition
The Motor Vehicle Sensor Market is the industry that manufactures and provides sensors intended exclusively for motor vehicles. These sensors are electronic devices that detect and measure a variety of data, including temperature, pressure, speed, position, and other critical aspects affecting vehicle operation. They serve an important role in assuring the safety, efficiency, and performance of motor vehicles by supplying real-time data to the vehicle control systems. The market for motor vehicle sensors is being pushed by factors such as increased vehicle electrification, advances in sensor Sales Channel, and rising demand for advanced driver assistance systems (ADAS) and autonomous vehicles.
Market Overview
The global Motor Vehicle Sensor Market has witnessed steady growth in recent years and is expected to grow at a CAGR of 12.50% between 2024 and 2032. The market was valued at USD 35124.5 million in 2023 and is expected to reach USD 101387.1 million in 2032.
The market for motor vehicle sensors is large and growing. This growth is being driven by an increase in demand for advanced driver assistance systems (ADAS) and driverless vehicles, as well as the continued trend of vehicle electrification. With the increase in the number of electric vehicles and the requirement for enhanced safety features, the demand for motor vehicle sensors is likely to expand further.
Furthermore, advances in sensor technologies are helping to drive the growth of this market. Manufacturers are continually creating new sensor systems to increase accuracy, reliability, and utility. This improves the entire driving experience and allows vehicles to run more effectively.
Segmentation by Type
- Position sensors will account for the biggest market share between 2024 and 2032. The increasing demand for autonomous vehicles and autopilot applications is driving the expansion of this segment.
- The Pressure Sensors segment is expected to grow at a substantial CAGR of 10.1% throughout the forecast period.
Segmentation by Vehicle Type
- The Motor Vehicle Sensor Market's most popular sector is Passenger Vehicles. Passenger vehicles include automobiles, SUVs, and other vehicles meant for personal use. This sector holds a sizable proportion of the motor vehicle sensor market due to the rising demand for sensors in passenger vehicles for a variety of applications such as safety systems, engine management, and driver assistance features. The increased adoption of advanced driver assistance systems (ADAS), as well as the growing emphasis on passenger safety and comfort, contribute to the segment's appeal in the motor vehicle sensor market.
Segmentation by Application
- The powertrain systems category dominated the automotive sensor market during the predicted period. A vehicle's powertrain system determines its performance, comfort, and safety. To lower fuel consumption, producers of powertrain systems and components have adopted hybrid powertrain systems.
- The Chassis segment is expected to grow at a substantial CAGR of 10.0% throughout the projection period.
Segmentation by Technology
- The MEMS (Micro-Electro-Mechanical Systems) segment holds the majority of the shares. MEMS sensors are commonly utilized in a variety of automotive applications due to their compact size, low power consumption, and great reliability. They're employed in things like airbag systems, tire pressure monitoring systems, electronic stability control, and engine management.
Segmentation by Sales Channel
- The original equipment manufacturer (OEM) segment will have the most growth during the projection period. The term "original equipment manufacturer" (OEM) refers to the manufacturer of original parts that are built and installed during the production of a new vehicle.
- Aftermarket is another key Vehicle Type in the Motor Vehicle Sensor Market.
Segmentation by Electric Vehicle Type
- Battery Electric Vehicles (BEVs) are in high demand. BEVs are cars that only run on electricity stored in rechargeable batteries. With an increased emphasis on sustainability and lowering carbon emissions, there is a growing demand for BEVs, which provide zero-emission transportation.
- The fastest-growing category in the motor vehicle sensor industry is related to hybrid electric vehicles (HEVs). HEVs combine an internal combustion engine, an electric motor, and a battery.
Segmentation by Autonomous Level
- The motor sensor market's fastest growing sector is Level 2 (Partial Automation). Level 2 automation includes technologies like adaptive cruise control and lane-keeping assistance, which help the driver steer the car but still demand their active involvement. The demand for Level 2 automation is growing as more vehicles are outfitted with advanced driver assistance systems (ADAS) that improve safety and convenience.
- Level 4 (High Automation) is another key market area for motor sensors.
Segmentation by Communication Sales Channel
- Wired sensors are an important sector of the motor sensor market. Wired sensors, as the name implies, link to the vehicle's system by actual wiring. They enable dependable and direct communication between the sensor and the control unit, resulting in accurate data transmission. Wired sensors are widely employed in important applications requiring real-time data, such as engine monitoring and safety systems.
Segmentation by Region
- Asia Pacific had the biggest revenue share (43.45%) in 2023.
- North America is the second-largest region in the market.
- The rest of the world, including Latin America, the Middle East, and Africa, supplies the remaining demand for Motor Vehicle Sensor.
Asia-Pacific was the largest revenue contributor and is expected to expand at a CAGR of 11.5%. Asia-Pacific is made up of China, Japan, India, South Korea, and the remaining Asian nations. Asia-Pacific has a considerable market share in the global sensors business as a result of increased technological breakthroughs and automotive standards in developing countries such of India, China, and Indonesia. Several factors contribute to Asia-Pacific market growth, including rapid industry expansion, low operating costs, and rising population levels. Because of its growing economy and technological developments in the sensor framework, Asia-Pacific is the largest contributor to the vehicle sector. China, Japan, and India are expected to have a considerable market share over the forecast period. Japan and China are technologically advanced nations with high demand for intelligent sensors.
In addition, North America is the second-largest region. It is being studied in the United States, Canada, and Mexico. The rise in automotive sector innovations and connected devices is expected to increase the use of automotive sensor Sales Channel. The United States currently dominates the automotive sensor market and is likely to do so during the forecast period. The ability to mass produce and be environmentally friendly are expected to drive up demand for vehicle sensors in North America. Advanced technologies are being introduced, particularly in pressure sensors, which are predicted to increase faster than other regional sensor types.
Key Highlights of the Report
Type, Vehicle Type, Application, Technology, Type, Electric Vehicle Type, Autonomous Level, Communication Technology and region segment of the global Motor Vehicle Sensor Market. During the forecast period, the powertrain systems category led the automotive sensor market, with Level 2 (Partial Automation) being the fastest expanding sector. In addition, Battery Electric Vehicles (BEVs) are in increasing demand, and wired sensors comprise a significant portion of the motor sensor industry. Also, the chassis segment is a significant CAGR holder, with Asia Pacific leading the market growth.
The market's primary drivers are increasing demand for advanced driver assistance systems (ADAS) and autonomous vehicles, a growing focus on vehicle safety and regulatory standards, and advancements in sensor technology. Furthermore, the high cost of implementing sensor technology in vehicles, the complex integration of sensors with current vehicle systems, and the potential cybersecurity threats associated with sensor-enabled vehicles are the main market limitations.
Nonetheless, Asia-Pacific was the largest revenue contributor. Asia-Pacific is comprised of China, Japan, India, South Korea, and the remaining Asian countries. Additionally, North America is the second-largest region. It is being studied in the USA, Canada, and Mexico.
What Are The Main Drivers Of The Global Motor Vehicle Sensor Market?
The Motor Vehicle Sensor Market is driven by several factors that contribute to its growth and development. One key driver is the increasing demand for advanced driver assistance systems (ADAS) and autonomous vehicles. As Sales Channel continues to advance, there is a growing need for sensors that can provide accurate and real-time data to enable these systems to function effectively. Another driver is the growing focus on vehicle safety and regulatory standards. Governments and organizations around the world are placing more emphasis on improving vehicle safety, which has led to the integration of various sensors in vehicles to monitor and enhance safety features.
What Are The Major Challenges Faced By The Global Motor Vehicle Sensor Market?
While the Motor Vehicle Sensor Market is experiencing growth, some restraints need to be considered. One major restraint is the high cost of implementing sensor Sales Channel in vehicles. The development and integration of sensors can be expensive, especially for smaller manufacturers or those operating on tighter budgets. Another restraint is the complex integration of sensors with existing vehicle systems. Ensuring seamless integration and compatibility can be challenging, requiring extensive testing and validation processes.
What Are The Growth Opportunities In The Global Motor Vehicle Sensor Market?
The Motor Vehicle Sensor Market presents several opportunities for growth and innovation. With the expansion of the electric vehicle (EV) market, there is a growing need for specialized sensors that can monitor and optimize the performance of these vehicles. This presents an opportunity for sensor manufacturers to develop solutions tailored to the unique requirements of EVs. Another opportunity lies in the market for sensor fusion Sales Channel. By combining data from multiple sensors, such as radar, LiDAR, and cameras, vehicles can benefit from enhanced capabilities, such as improved object detection and collision avoidance.
Market Drivers
Several factors drive the global Motor Vehicle Sensor Market. The following are the key drivers of the global Motor Vehicle Sensor Market:
Improvements in SENSOR SALES Channel to Fulfill Customer Needs
Sensors have become increasingly compact, energy-efficient, and cost-effective, allowing for smooth integration into a variety of Technologys. Solid-state LiDAR, CMOS image sensors with improved resolution and low-light capabilities, and sensitive microelectromechanical systems (MEMS) accelerometers have transformed the data collecting and analysis landscape. These innovations have enabled businesses to obtain real-time data with remarkable accuracy, resulting in increased efficiency, process optimization, and the development of cutting-edge products and services that meet changing client needs. Sensors to monitor battery health, temperature, charging status, and other vital characteristics are required for optimal performance and safety as electric and hybrid vehicles become more prevalent. The demand for in-car infotainment, navigation, and networking services mandates the integration of sensors like GPS and accelerometers to give accurate navigation data and improve the user experience.
Market Restraints
The global Motor Vehicle Sensor Market faces some challenges that may hinder its growth. These include the following:
High Cost of LiDAR Automobile Sensors
Automotive sensors are relatively expensive, which limits their broad Technology. The cost rises due to high raw material costs, complex manufacturing procedures, and increased demand for these sensors. This makes developing and implementing advanced sensor technologies difficult, particularly in price-sensitive sectors where high costs might reduce adoption rates. Sensors are used in automobiles for a variety of purposes, including safety, engine management, and comfort features. This diversity raises expenses due to the requirement to build and integrate different sensor types within a single vehicle. Developing advanced sensing Sales Channel necessitates significant research, testing, and prototyping investments. Costs are expended when exploring innovative sensor designs, materials, and functionalities to fulfill the changing demands of the automotive industry. Rapid technological breakthroughs necessitate frequent updates and variations of sensor designs. As manufacturers attempt to stay on the cutting edge of sensor capabilities, continuing innovation can drive up costs.
LiDAR sensors are becoming increasingly important in advanced driver assistance systems (ADAS) and driverless vehicles because to their superior 3D mapping and object detection capabilities. However, their incorporation into the automotive sector has been limited because to high production costs. The car sector relies on mass production, whereas LiDAR sensors are often produced in smaller amounts, resulting in higher unit prices. Extensive investment in R&D, modification for automotive Technology, regulatory compliance, and performance criteria all contribute to higher costs.
Despite these obstacles, industry initiatives and developments, including as solid-state LiDAR Sales Channel and more competition, are steadily driving cost reductions, promising more affordable LiDAR solutions for a wider range of vehicles and Technologys in the future.
Opportunities
The global Motor Vehicle Sensor Market offers significant growth opportunities. These include the following:
Growing Need for Automotive Aftermarket Services
Aftermarket opportunities in the automotive sensors market relate to the potential for selling and installing sensor-based goods and solutions in vehicles that were not originally equipped with those sensors by the manufacturer. This expansion is being fueled by increased demand for safety features, the growing popularity of aftermarket automotive modifications, and the growing popularity of electric vehicles. Specific aftermarket prospects in the vehicle sensor industry include blind spot monitoring systems, lane departure warning systems, parking sensors, battery monitoring systems, and solar charging systems. Older vehicles lacked enhanced safety measures that are now standard on modern models.
Aftermarket sensors can be used to add features like lane departure warning, blind spot recognition, and collision avoidance systems. Retrofitting telematics devices into older vehicles allows for connectivity capabilities such as remote diagnostics, vehicle tracking, and mobile app integration. As Sales Channel evolves and consumer demand rises, the aftermarket car sensor market remains a potential business opportunity.
Competitive Landscape
Key Players
The global Motor Vehicle Sensor Market is highly competitive, with several key players. Some of the major players in the market and their market share are as follows:
- Robert Bosch GmbH
- Eaton Corporation
- Denso Corporation
- Continental AG
- Delphi
- Valeo
- NXP Semiconductors NV
- Robert Bosch GmbH
- Infineon Technologies AG
- BorgWarner Inc
- Hitachi Ltd
These organizations prioritize product innovation, Application expansion, and mergers and acquisitions to stay competitive.
The global Motor Vehicle Sensor Market's key players continually seek to stay ahead by offering new products and developments.
In January 2022, Denso Corporation, a global mobility supplier, expanded its existing global safety package with a new combined millimeter wave radar sensor and vision sensor to help drivers control their vehicles safely.
In December 2022, Continental AG (Continental) said that it will showcase modules and sensors designed specifically for electromobility. Continental will introduce its Advanced Driver Assistance Systems (ADAS), which has been integrated into the "CV3" SoC (System on Chip) family and features artificial intelligence (AI) from semiconductor startup Ambarella.
Summary of Key Findings
- Increasing need for automotive aftermarket services.
- The market is segmented by Type, Vehicle Type, Application, Technology Type, Electric Vehicle Type, Autonomous Level, Communication Technology and region.
- During the forecast period, the powertrain systems category dominated the automotive sensor market
- Passenger vehicles are the most popular sector in the Motor Vehicle Sensor Market.
- Asia Pacific is leading market growth. The market is highly competitive, with key players including Hitachi Ltd, Robert Bosch GmbH, Eaton Corporation, Denso Corporation, Continental AG, Delphi, and Valeo. and Others.
Future Outlook
- Growing demand for advanced driver assistance systems (ADAS)
- Increasing adoption of autonomous vehicles
- Rise of electric vehicles (EVs) and hybrid vehicles
- Advancements in sensor technologies
- Integration of sensors with Internet of Things (IoT) platforms
- Focus on improving vehicle safety and efficiency
How CXOs Can Benefit from the Credence Research Motor Vehicle Sensor Market Report
The Credence Research Motor Vehicle Sensor Market Report provides CXOs with a comprehensive overview of the market, including:
- Market Vehicle Type and growth forecast: The report provides detailed estimates of the global Motor Vehicle Sensor Market Vehicle Type, segmented by Type, Vehicle Type, Application, Technology, Type, Electric Vehicle Type, Autonomous Level , Communication Technology and region. It also includes forecasts for the market through 2032, based on key trends and drivers.
- Market segmentation: The report segments the Motor Vehicle Sensor Market by Type, Vehicle Type, Application, Technology, Type, Electric Vehicle Type, Autonomous Level, Communication Technology and region. This segmentation provides CXOs with a granular understanding of the market and the opportunities in each segment.
- Competitive Landscape: The report profiles the key players in the Motor Vehicle Sensor Market and provides insights into their strategies, product offerings, and financial performance. This information can help CXOs to identify and assess their competition.
- Key trends and drivers: The report identifies and analyzes the key trends and drivers shaping the Motor Vehicle Sensor Market. This information can help CXOs make informed decisions about their investments and strategies.
CXOs can use the insights from the Credence Research Motor Vehicle Sensor Market Report to:
- Identify growth opportunities: The report can help CXOs to identify new growth opportunities in the Motor Vehicle Sensor Market. For example, it can provide insights into emerging technologies, market trends, and key market players.
- Make informed investment decisions: The report can help CXOs to make informed investment decisions about Motor Vehicle Sensor. For example, it can provide insights into market trends, growth potential, competitive landscape, and key players in the industry.
- Develop competitive strategies: The report can help CXOs to develop competitive strategies for their Motor Vehicle Sensor businesses. For example, the report identifies the key strategies that dark fiber providers are using to differentiate themselves from their competitors.
- Track market developments: The .report can help CXOs to track market developments and stay ahead of the curve. For example, the report provides insights into the latest trends and innovations in the Motor Vehicle Sensor Market.
Overall, the Credence Research Breast Cancer .Treatment Market Report is a valuable resource for CXOs who are looking to gain a deeper understanding of the market and identify opportunities for growth.
Segmentation
By Type:- Temperature Sensors
- Pressure Sensors
- Position Sensors
- Speed Sensors
- Oxygen Sensors
- Inertia Sensors (Accelerometers, Gyroscopes)
- Image Sensors (Cameras)
- Proximity Sensors
- LiDAR Sensors
- Radar Sensors
- Ultrasonic Sensors
- Others
- Passenger Vehicles
- Commercial Vehicles (Trucks, Buses)
- Two-Wheelers
- Others
- Powertrain
- Chassis
- Safety and Control
- Body Electronics
- Telematics
- Others
- MEMS (Micro-Electro-Mechanical Systems)
- Non-MEMS
- OEMs (Original Equipment Manufacturers)
- Aftermarket
- Battery Electric Vehicles (BEVs)
- Hybrid Electric Vehicles (HEVs)
- Plug-in Hybrid Electric Vehicles (PHEVs)
- Fuel Cell Electric Vehicles (FCEVs)
- Level 1 (Driver Assistance)
- Level 2 (Partial Automation)
- Level 3 (Conditional Automation)
- Level 4 (High Automation)
- Level 5 (Full Automation)
- Wired Sensors
- Wireless Sensors (Bluetooth, Wi-Fi, Cellular)
-
- North America
- The U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- The U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of Middle East and Africa
- North America
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Expansion of Advanced Driver Assistance Systems (ADAS) and Autonomous Vehicles
The increasing integration of ADAS and autonomous driving features in vehicles is driving demand for a wide range of sensors, as these systems rely on real-time data for functions such as collision avoidance, lane keeping, and adaptive cruise control.
Vehicle Electrification and Growth of Electric Vehicles
The shift toward electric and hybrid vehicles requires specialized sensors for battery management, powertrain optimization, and safety monitoring, significantly boosting sensor adoption in new vehicle platforms.
Stringent Safety and Emission Regulations
Global regulatory mandates for improved vehicle safety and reduced emissions are compelling automakers to incorporate more sensors for monitoring and controlling critical vehicle functions, thus expanding the market.
Technological Advancements in Sensor Design and Integration
Innovations such as MEMS technology, solid-state LiDAR, and sensor fusion are enhancing sensor performance, reliability, and cost-effectiveness, making it feasible to deploy more sensors per vehicle and enabling new applications.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current Vehicle Type of the global Motor Vehicle Sensor Market?
What is the expected growth rate of the Motor Vehicle Sensor Market between 2024 and 2032?
Which segment is leading the market share in terms of Type?
Which Electric Vehicle Type segment governs the demand for Motor Vehicle Sensor in the world?
Who are the major players in the global Motor Vehicle Sensor Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Position Sensors
- 1.2.2 Pressure Sensors
- 1.2.3 Temperature Sensors
- 1.2.4 Speed Sensors
- 1.2.5 Oxygen Sensors
- 1.2.6 LiDAR Sensors
- 1.3 By Technology
- 1.3.1 MEMS (Micro-Electro-Mechanical Systems)
- 1.3.2 Non-MEMS
- 1.4 By Application
- 1.4.1 Powertrain
- 1.4.2 Chassis
- 1.4.3 Safety and Control
- 1.4.4 Body Electronics
- 1.4.5 Telematics
- 1.5 By Vehicle Type
- 1.5.1 Passenger Vehicles
- 1.5.2 Commercial Vehicles
- 1.5.3 Two-Wheelers
- 1.5.4 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2023: USD 35124.5 Million → 2032: USD 101,387.1 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2023
- 2.6.2 Forecast Period: 2023-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2023
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Motor Vehicle Sensor Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Motor Vehicle Sensor Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2023-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2023-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Motor Vehicle Sensor Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2023-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Motor Vehicle Sensor Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Motor Vehicle Sensor Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Motor Vehicle Sensor Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Motor Vehicle Sensor Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Motor Vehicle Sensor Market Outlook, 2023-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2023: USD 35124.5 Million → 2032: USD 101,387.1 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2023
- 11.2 Market Forecast, 2023-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Motor Vehicle Sensor Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2023
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2023-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2023-2032
- 12.3.4 Volume Forecast, 2023-2032
- 12.3.5 Base-Year Market Share, 2023
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Position Sensors
- 12.3.7.2 Pressure Sensors
- 12.3.7.3 Temperature Sensors
- 12.3.7.4 Speed Sensors
- 12.3.7.5 Oxygen Sensors
- 12.3.7.6 LiDAR Sensors
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Technology - Market Size and Forecast, 2023-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2023-2032
- 12.4.4 Volume Forecast, 2023-2032
- 12.4.5 Base-Year Market Share, 2023
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 MEMS (Micro-Electro-Mechanical Systems)
- 12.4.7.2 Non-MEMS
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2023-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2023-2032
- 12.5.4 Volume Forecast, 2023-2032
- 12.5.5 Base-Year Market Share, 2023
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Powertrain
- 12.5.7.2 Chassis
- 12.5.7.3 Safety and Control
- 12.5.7.4 Body Electronics
- 12.5.7.5 Telematics
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Vehicle Type - Market Size and Forecast, 2023-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2023-2032
- 12.6.4 Volume Forecast, 2023-2032
- 12.6.5 Base-Year Market Share, 2023
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Passenger Vehicles
- 12.6.7.2 Commercial Vehicles
- 12.6.7.3 Two-Wheelers
- 12.6.7.4 Others
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Motor Vehicle Sensor End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Motor Vehicle Sensor Geographic Market Outlook, 2023-2032
- 14.1 Regional Market Size and Share, 2023
- 14.2 Regional Market Forecast, 2023-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Motor Vehicle Sensor Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2023-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Motor Vehicle Sensor Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2023
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2023-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Robert Bosch GmbH
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Denso Corporation
- 18.4 Continental AG
- 18.5 Delphi
- 18.6 Valeo
- 18.7 NXP Semiconductors NV
- 18.8 Infineon Technologies AG
- 18.9 Eaton Corporation
- 18.10 BorgWarner Inc
- 18.11 Hitachi Ltd
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

